
 Behavioral Health Software Market | 2026-2036
Behavioral Health Software Market Size, Share, and Industry Trends Forecast 2026-2036
Behavioral Health Software Market Analysis
Multi-source procurement of clinical modules is rebalancing toward integrated suites that unify EMR, billing, and telehealth workflows. Epic Systems Corporation anchors hospital system deployments with its tightly coupled inpatient-outpatient architecture. Netsmart Technologies specializes in post-acute and community behavioral health settings, sustaining dominance across state-level provider networks. Qualifacts competes on configurability for small-to-mid-sized clinics, leveraging flexible deployment options that reduce IT overhead.
Behavioral health software encompasses clinical, administrative, and patient engagement applications designed to document, coordinate, and deliver mental health and substance abuse services, typically incorporating HL7 FHIR interoperability protocols, CCBHC-compliant reporting modules, and real-time clinical decision support algorithms. Telehealth Solutions and Cloud-Based deployment represent the fastest-expanding structural segments, as remote care modalities and subscription pricing models displace capital-intensive on-premises installations. Clinical Management Software retains the deepest margin pools due to recurring certification requirements and sticky enterprise contracts, while Mobile Platforms capture growing share among peer-support and crisis-intervention use cases.
The US FDA regulates digital therapeutics embedded within behavioral platforms, while ONC certification mandates under the 21st Century Cures Act enforce interoperability standards that gate Medicare reimbursement eligibility. HIPAA and state-level parity statutes further constrain data architecture choices, elevating compliance costs for vendors without established legal-technical teams. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classifications and ONC timeline enforcement to anticipate which product categories face expanded premarket scrutiny or accelerated reimbursement pathways.
Market Dynamics
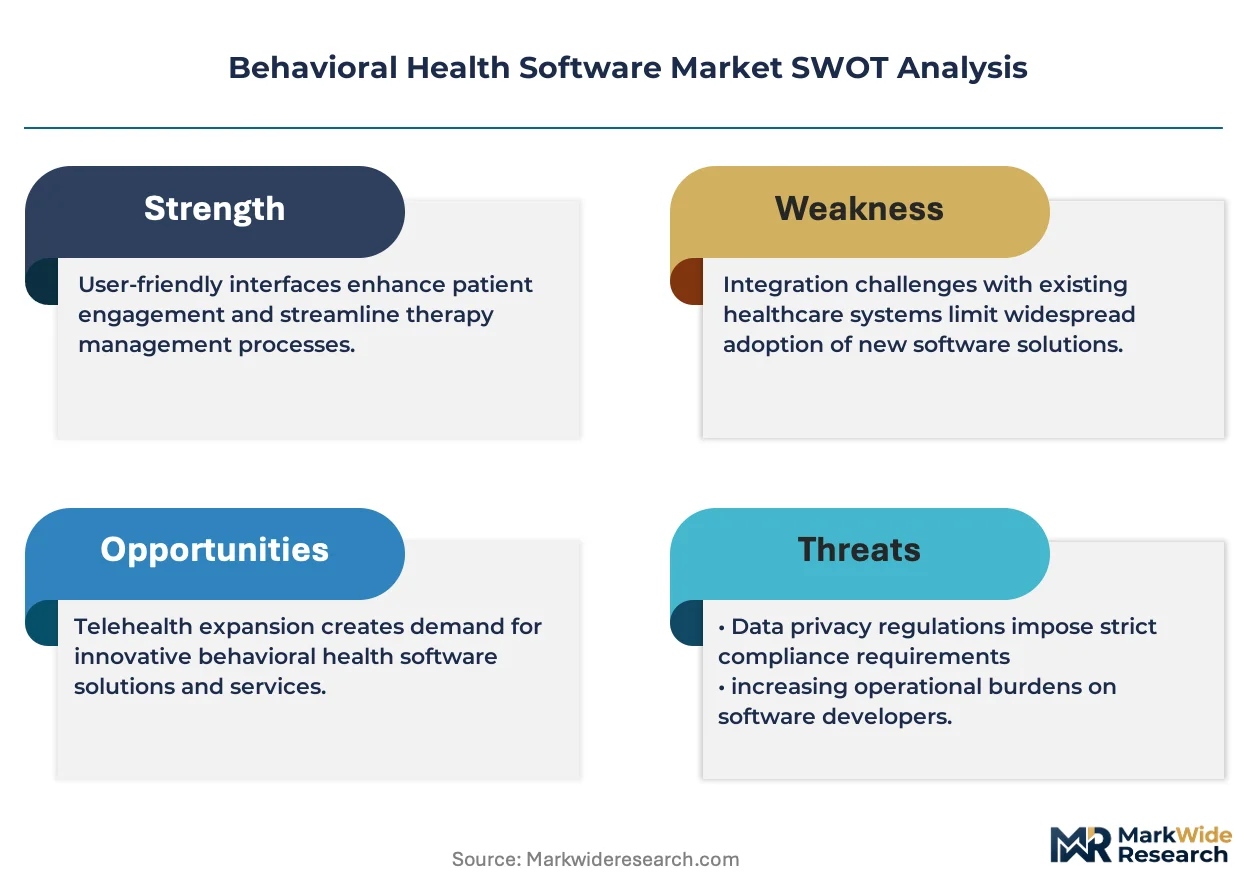
Federal parity enforcement and ONC interoperability mandates are compressing procurement cycles, forcing payers and providers to consolidate fragmented clinical systems into unified platforms that satisfy certification requirements.
Growth Catalysts
- 21st Century Cures Act:ONC certification mandates gate Medicare reimbursement, compelling provider networks to upgrade digital infrastructure and expand vendor procurement.
- Telehealth modality expansion:Outpatient clinics are replacing capital-intensive on-premises installations with subscription-based cloud platforms for remote care delivery.
- Federal parity statutes:Enforcement actions against commercial payers are accelerating investment in behavioral health claims processing and network management software.
Market Restraints
- Certification cost concentration:HIPAA compliance and state-level data architecture requirements elevate fixed costs for vendors lacking established legal-technical teams.
- Interoperability friction:HL7 FHIR implementation gaps between legacy EMR systems and modern platforms create integration delays and data migration risks.
- Specialized talent scarcity:Clinical informaticists with dual expertise in behavioral health workflows and health IT architecture command premium compensation, constraining vendor scaling.
Strategic Opportunities
- CCBHC expansion:Certified Community Behavioral Health Clinic designation programs in underserved states are creating demand for compliant reporting modules and care coordination tools.
- Crisis intervention mobile platforms:Peer-support applications and real-time clinical decision support algorithms are penetrating emergency departments and mobile crisis teams.
- AI-actuated documentation:Natural language processing for clinical note generation is converging with voice recognition to reduce administrative burden in high-volume outpatient settings.
Industry Challenges
- Legacy system entrenchment:State-level provider networks with decades-old client-server architectures face multi-year migration timelines to cloud-native platforms.
- Software-as-medical-device ambiguity:Evolving FDA guidance on digital therapeutic classifications creates premarket pathway uncertainty for platforms embedding algorithmic treatment recommendations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behavioral Health Software Market |
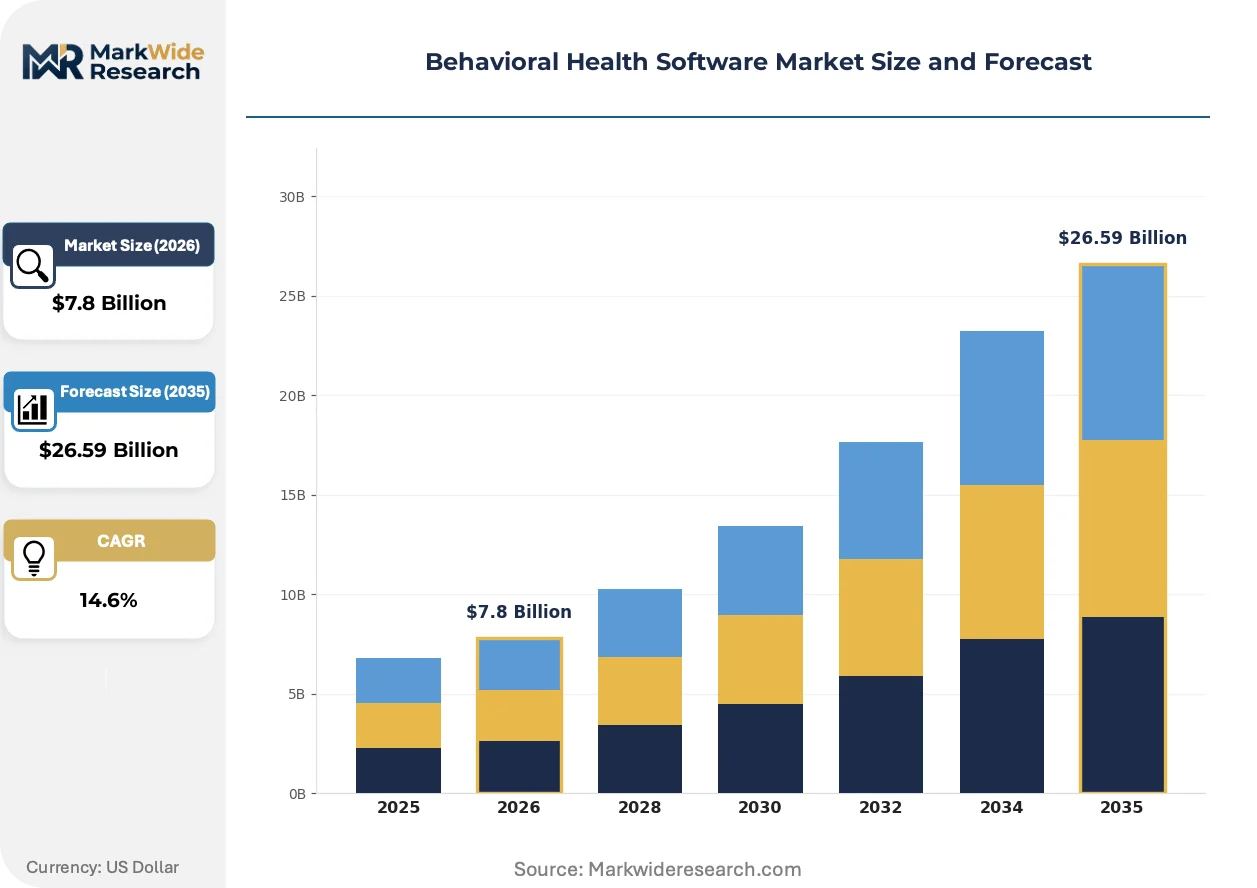
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $26.59 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Management Software, Telehealth Solutions, EMR Systems, Billing Software End User: Hospitals, Outpatient Clinics, Residential Treatment Centers, Specialty Care Providers Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms Application: Substance Abuse Treatment, Mental Health Counseling, Patient Monitoring, Behavioral Assessments |
| Companies Covered | Oracle Health, Epic Systems Corporation, Netsmart Technologies, Qualifacts, Core Solutions, Meditab Software, Welligent, Valant, AdvancedMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behavioral Health Software Market Emerging Trajectories
Clinical workflow automation and regulatory data exchange requirements are reshaping how behavioral health platforms capture, structure, and transmit patient information across care settings.
Natural language processing engines are absorbing unstructured clinical encounter data into structured billing and quality reporting formats. Community mental health centers and federally qualified health centers are deploying these tools to reduce documentation burden and improve encounter completeness. The technology is absorbing hours of administrative labor previously performed by licensed clinicians, compressing cost structures in thin-margin outpatient operations.
REACH-style chemical substance regulations in the European Union are extending to software components with embedded AI, requiring transparency documentation for algorithmic decision support. Vendors seeking CE marking under the EU AI Act must demonstrate clinical validation for mental health risk stratification tools. European psychiatric hospitals and ambulatory networks are responding by demanding vendor-provided conformity assessments before procurement.
Subscription pricing for enterprise behavioral health suites is displacing perpetual license models that dominated prior procurement cycles. Hospital systems and multi-site outpatient networks are consolidating vendor relationships to capture volume discounts and reduce integration complexity. This shift is most visible in United States markets where federal value-based care incentives reward unified data infrastructure across inpatient and outpatient behavioral health settings.
Behavioral Health Software Market Segmentation
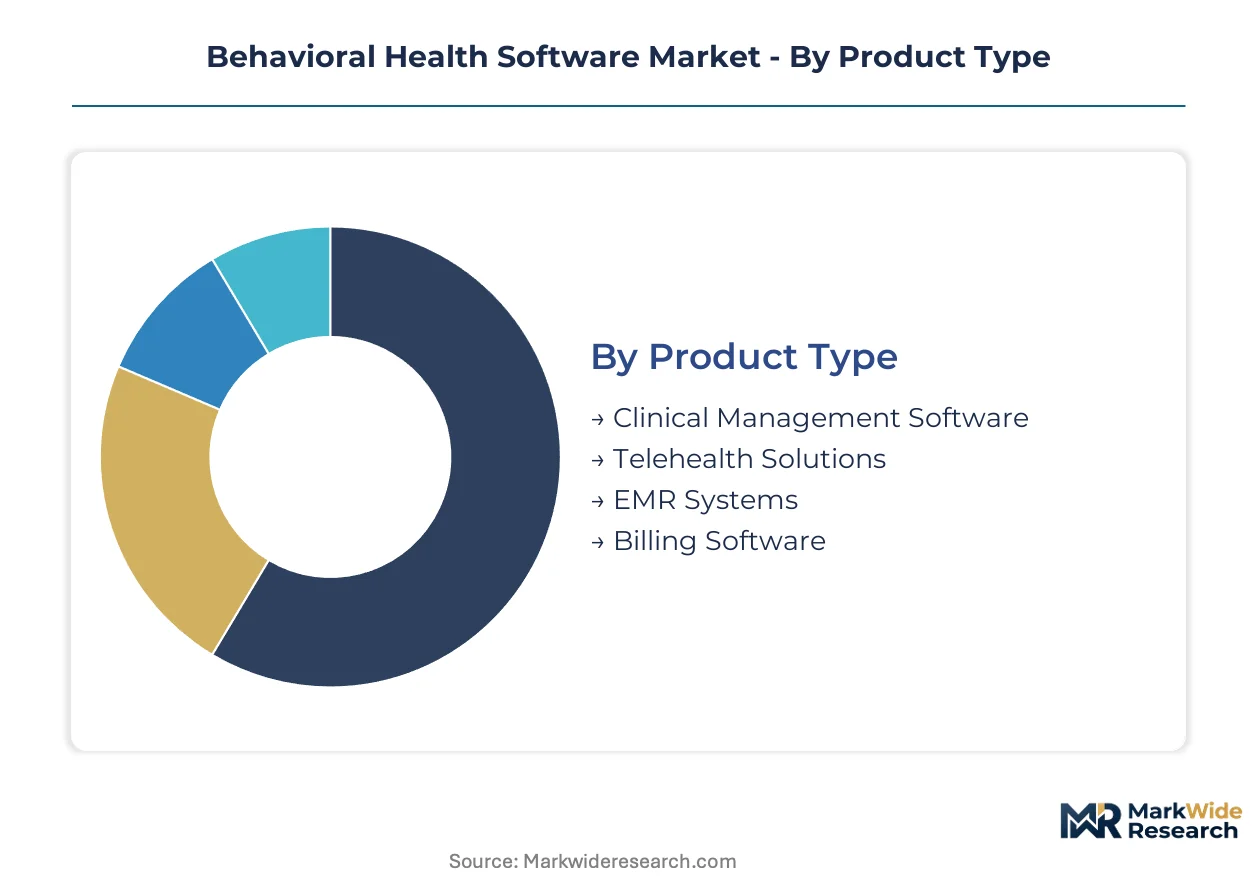
Segmentation in behavioral health software reflects divergent upgrade cycles across provider types and regulatory maturity. Cloud migration timelines, federal certification deadlines, and care delivery modality shifts each reshape how procurement budgets flow across product categories.
Product Type:
Replacement cycles accelerate where ONC certification mandates force infrastructure overhauls before Medicare reimbursement gates close.
- Clinical Management Software:Core platforms integrate CCBHC-compliant reporting modules with real-time clinical decision support. Hospital systems in Texas and California concentrate procurement here as they consolidate fragmented inpatient-outpatient workflows ahead of federal deadlines.
- Telehealth Solutions:Video-based care delivery platforms embed HIPAA-compliant encryption and asynchronous messaging. Outpatient clinics in Florida and New York displace legacy phone systems with these tools to capture remote patient volumes without physical expansion.
- EMR Systems:Behavioral health-specific electronic records with HL7 FHIR interoperability.
- Billing Software:Claims processing modules tuned to federal parity enforcement and state Medicaid variations.
Clinical Management Software sits at the top of the volume ranking, with Telehealth Solutions climbing the fastest.
End User:
Cost tier differentiation separates enterprise hospital deployments from lean outpatient implementations.
- Hospitals:Integrated health systems demand unified EMR-telehealth-billing suites with enterprise-grade uptime guarantees. Academic medical centers in Massachusetts and North Carolina anchor this segment through multi-year vendor consolidations.
- Outpatient Clinics:Federally qualified health centers and community mental health providers prioritize subscription-priced cloud platforms with minimal IT overhead. CCBHC-designated clinics in Ohio and Arizona drive fastest expansion here.
- Residential Treatment Centers:Long-stay facilities require medication management and incident reporting modules.
- Specialty Care Providers:Eating disorder, autism, and addiction-focused practices need configurable assessment tools.
Outpatient Clinics capture the steepest expansion trajectory as federal funding streams broaden access infrastructure.
Deployment:
Application urgency varies by care setting—crisis intervention demands mobile immediacy while enterprise billing tolerates hybrid latency.
- Cloud-Based:Subscription-hosted platforms with automatic regulatory updates and elastic scaling. State-level provider networks in Illinois and Georgia favor these to escape client-server maintenance burdens.
- Mobile Platforms:Native iOS and Android applications for peer support and crisis response. Emergency departments in Washington and Colorado deploy these for real-time risk stratification and warm handoffs.
- On-Premises:Self-hosted installations retained where data residency requirements or legacy integration complexity blocks migration.
- Hybrid Solutions:Mixed architectures keeping sensitive records local while pushing analytics to cloud environments.
Cloud-Based deployment holds volume leadership, with Mobile Platforms gaining share fastest among frontline crisis teams.
Application:
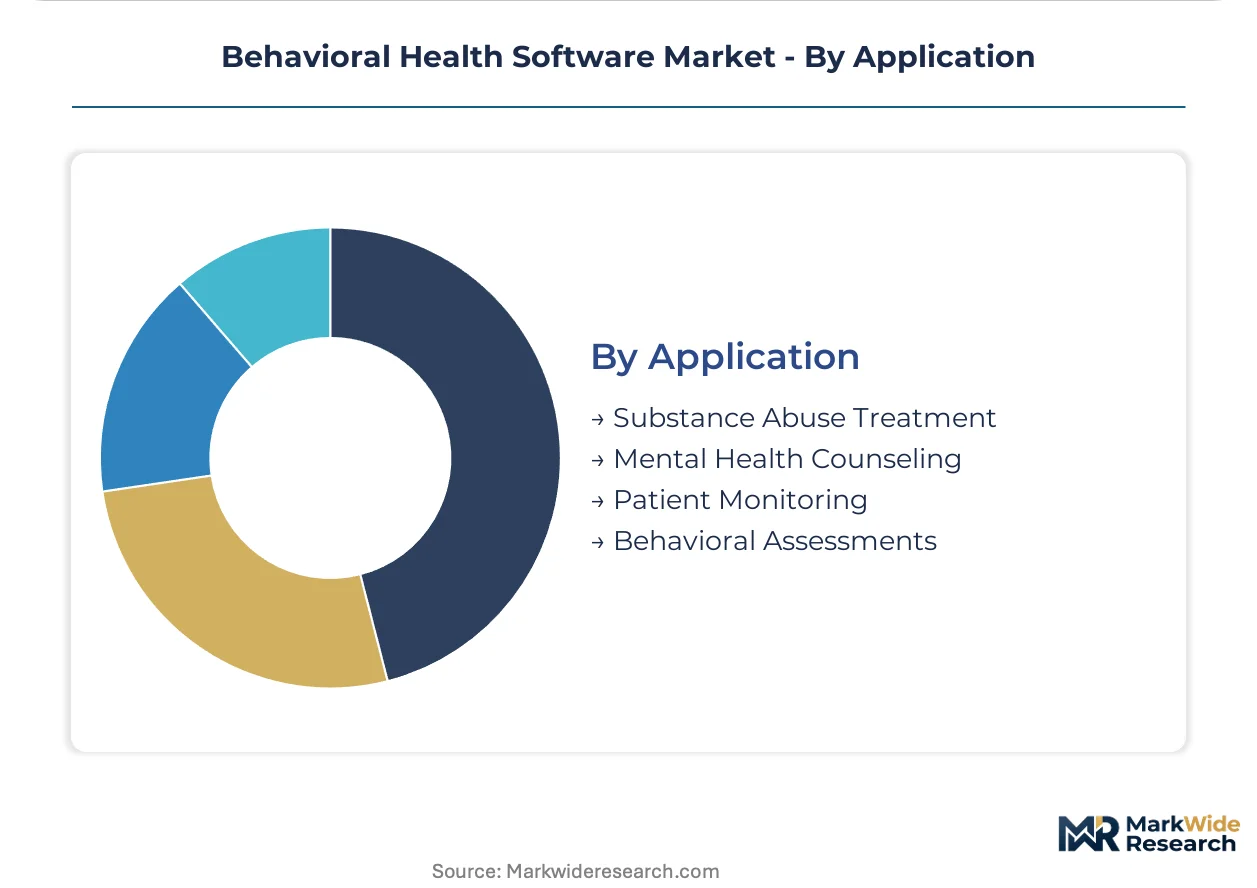
Customer type segmentation maps to reimbursement pathway maturity—substance abuse treatment carries established billing codes while behavioral assessments navigate emerging value-based frameworks.
- Substance Abuse Treatment:Medication-assisted therapy tracking, urine drug screening integration, and state registry reporting. Opioid treatment programs in Pennsylvania and Maryland concentrate demand as federal block grants expand.
- Mental Health Counseling:Session documentation, treatment planning, and outcome measurement tools. Private practice networks in Texas and Florida scale these for telehealth-first service delivery.
- Patient Monitoring:Remote symptom tracking and medication adherence applications.
- Behavioral Assessments:Standardized screening instruments and algorithmic risk scoring.
Substance Abuse Treatment leads by installed base, with Behavioral Assessments expanding most quickly as predictive analytics penetrate prevention programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the dominant share of behavioral health software procurement, with federal parity enforcement and ONC certification mandates compressing upgrade cycles across hospital systems and outpatient networks.
United States
Hospital systems in Texas and California are consolidating fragmented EMR-telehealth-billing suites ahead of Medicare reimbursement deadlines. The ONC interoperability mandates under the 21st Century Cures Act gate federal payments, compelling provider networks to replace legacy client-server installations. Academic medical centers in Massachusetts anchor enterprise deployments with multi-year vendor consolidations.
Germany
Psychiatric hospitals in Bavaria and North Rhine-Westphalia are demanding vendor-provided conformity assessments under the EU AI Act for algorithmic decision support tools. REACH-style chemical substance regulations extend to software components with embedded AI, requiring transparency documentation. Berlin-based ambulatory networks are procuring cloud-native platforms to escape maintenance burdens of decades-old architectures.
United Kingdom
NHS Trusts in London and the Southeast are integrating behavioral health modules into unified electronic patient record systems. The country's national health technology regulator enforces interoperability standards that shape procurement specifications. Manchester and Birmingham clusters are deploying crisis intervention mobile platforms for emergency department warm handoffs.
Canada
Provincial health authorities in Ontario and Quebec are expanding telehealth infrastructure for remote mental health delivery. Health Canada regulates digital therapeutics embedded within behavioral platforms, creating premarket pathway requirements. Vancouver and Toronto metropolitan areas are consolidating vendor relationships to capture volume discounts across inpatient and outpatient settings.
Australia
Federally qualified health centers in New South Wales and Victoria are adopting subscription-priced cloud platforms with CCBHC-compliant reporting modules. The Therapeutic Goods Administration oversees software-as-medical-device classifications for algorithmic treatment recommendations. Melbourne and Sydney clusters are deploying natural language processing engines to reduce documentation burden in high-volume outpatient operations.
Behavioral Health Software Market Vendor Landscape
Global majors compete with regional champions across certification-heavy procurement cycles, with hospital system consolidation favoring integrated suite vendors over point-solution specialists. The vendor base separates into three tiers: enterprise-grade platforms with inpatient-outpatient unification, mid-market configurable systems for community behavioral health, and niche telehealth-first tools for private practice networks. Dominant competitive moves include strategic partnerships with state-level provider networks and portfolio diversification into AI-actuated documentation modules.
Within the enterprise-tier segment, Epic Systems Corporation and Oracle Health occupy positions as anchors for academic medical center deployments, while Netsmart Technologies exemplifies the community behavioral health specialist archetype serving state-level provider networks. These three entities represent the spectrum from tightly coupled hospital system architectures to post-acute and ambulatory-focused configurations.
| Leading Market Players |
|---|
| Oracle Health |
| Epic Systems Corporation |
| Netsmart Technologies |
| Qualifacts |
| Core Solutions |
| Meditab Software |
| Welligent |
| Valant |
| AdvancedMD |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists have consolidated fragmented behavioral health software vendors across the United States, concentrating supply-side pricing power while compressing margins for undifferentiated point-solution providers. This ownership pattern feeds directly into procurement dynamics: hospital systems leverage volume commitments against vendor consolidation premiums, while outpatient clinics face SaaS pricing tier compression as platform vendors cross-sell integrated suites.
Pricing Analysis
Input-cost pass-through from specialized clinical informaticist talent and HIPAA compliance architecture elevates base platform pricing for vendors lacking scale. Three-tier pricing structure across enterprise, mid-market, and small-practice levels separates Epic and Oracle Health deployments from Qualifacts configurations and Valant subscriptions. Pricing pressure stems from federal ONC certification deadlines forcing accelerated upgrade cycles. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers absorb premium tiers for inpatient-outpatient unification.
Supply Chain Analysis
Regional distribution centers for cloud-native platforms concentrate in Virginia, Oregon, and Ohio, anchoring hub-and-spoke data residency patterns for state Medicaid compliance. Core supply draws from specialized health IT engineering talent pools in Massachusetts, California, and Texas, with AI/ML development tethered to Toronto and London satellite offices. Single-source vulnerability rests on concentrated Epic and Oracle Health enterprise channel control. Distribution runs through direct sales teams for hospital systems and value-added resellers for community behavioral health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Behavioral health software procurement functions as a geographic-arbitrage play: European vendors face EU AI Act conformity assessment costs that US counterparts avoid, while American vendors absorb HIPAA and ONC certification burdens that create moats against foreign competition.
For Market Incumbents: To counter cloud-native entrants displacing legacy client-server installations, incumbents must accelerate CCBHC-compliant reporting module development and establish captive integration specialist teams. Certification investment in FDA software-as-medical-device pathways represents the critical defensive lever against algorithmic treatment recommendation platforms.
For New Entrants and Emerging Players: Begin with crisis intervention mobile platforms for emergency department warm handoffs, the most penetrable segment given thin incumbent presence and frontline clinician demand. Target state-level provider networks in Illinois and Georgia escaping decades-old architectures. A direct-to-clinic SaaS model with minimal IT overhead captures outpatient clinic procurement cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market configurable platforms serving community behavioral health without enterprise-grade certification completion. Long-term viability across the projection horizon rests on CCBHC expansion program capture and AI-actuated documentation integration. The signal to watch is ONC timeline enforcement acceleration, which gates Medicare reimbursement and consolidates vendor selection pools.
| Strategic Initiative | Industry Significance |
|---|---|
| CCBHC Compliance Module Development | Captures federal expansion funding streams in Ohio, Arizona, and underserved states. |
| AI-Actuated Documentation Integration | Reduces clinician administrative burden in high-volume Texas and Florida outpatient settings. |
| ONC Certification Acceleration | Gates Medicare reimbursement eligibility under 21st Century Cures Act mandates. |
| State-Level Provider Network Partnership | Locks in multi-year procurement cycles for Illinois and Georgia cloud migrations. |
| Crisis Intervention Mobile Platform Launch | Penetrates Washington and Colorado emergency department warm handoff workflows. |
Methodological Framework
Multiple input streams — behavioral health CIO interviews, ONC certification database analysis, and federal procurement record review — were reconciled against secondary validation from CMS Medicare reimbursement filings and state Medicaid technology plans. Primary conversations engaged health system digital transformation officers, community mental health center IT directors, CCBHC program administrators, and behavioral health software product managers. Secondary sources included FDA software-as-medical-device guidance documents, ONC interoperability standards publications, and hospital GPO contract databases. Bottom-up deployment counts across outpatient clinics, hospitals, and residential facilities were triangulated against top-down vendor revenue segmentation.
Data-stream reconciliation anchored volume projections across the modeling period, with deployment model, organization size, and CCBHC designation status serving as core segmentation dimensions. CAGRs were derived from fitted adoption curves weighted by federal funding authorization trajectories and certification deadline enforcement patterns. Forecast inputs incorporated telehealth modality penetration rates and cloud migration timeline elasticity specific to state-level provider network upgrade cycles.
Several conditions sit outside the modeled scope, including potential FDA reclassification of algorithmic decision support tools and unscheduled ONC timeline extensions. Forecasts reflect documented assumptions regarding federal parity enforcement continuity and CCBHC program geographic expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Mental Health Software Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
US Workplace Stress Management Market