
 Agoraphobia Treatment Market | 2026-2036
Agoraphobia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Agoraphobia Treatment Market Analysis
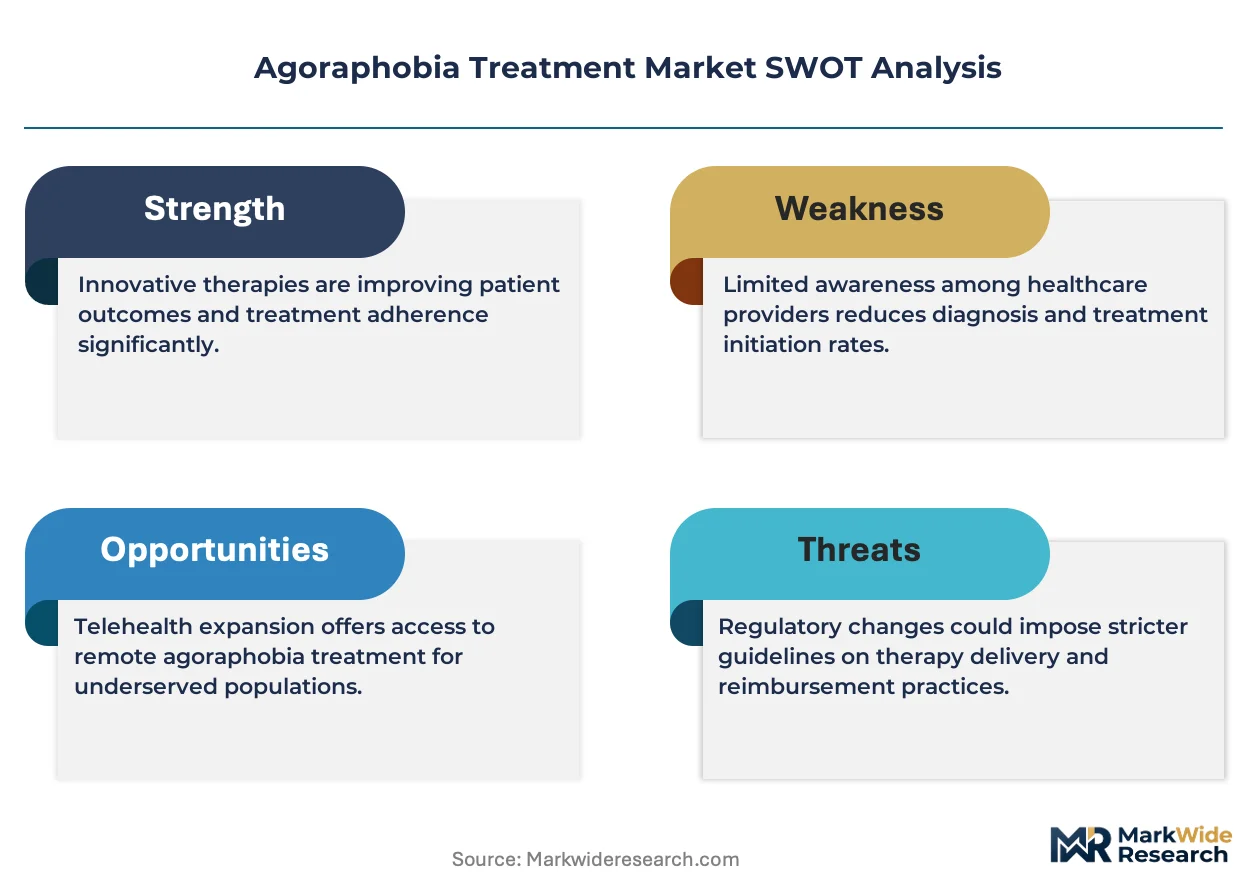
Psychiatrist supply is bifurcating between urban hospital systems and distributed telehealth platforms, constraining in-person capacity while unlocking virtual access. Pfizer Inc. leverages its established SSRI portfolio to anchor prescription volumes across both channels. Eli Lilly and Company differentiates through psychiatric R&D intensity, sustaining pipeline visibility in anxiety disorders. GlaxoSmithKline plc operates a broad primary-care network that competes on brand recognition and physician detailing reach.
Agoraphobia treatment encompasses pharmacological interventions, structured psychotherapy, and technology-mediated care protocols designed to reduce panic-triggered avoidance of public spaces; selective serotonin reuptake inhibitors remain the first-line pharmacotherapy, with cognitive behavioral therapy serving as the evidence-based psychological standard. Medications and psychotherapy together occupy the core revenue pool, though virtual therapy represents the fastest-expanding delivery category as asynchronous platforms reduce therapist-time constraints. The delivery mode dimension shows online and teletherapy formats capturing share from traditional in-person sessions, while hybrid models are emerging as the structural compromise for patients transitioning between acute and maintenance care phases.
The FDA oversees digital therapeutic approvals and antidepressant labeling standards that determine product marketability, while HIPAA mandates shape data architecture investments across telehealth platforms. State-level telehealth parity laws in the United States create patchwork reimbursement conditions that vendors must navigate for sustainable platform economics. Stakeholders should monitor evolving FDA guidance on prescription digital therapeutics, as classification decisions will determine whether software-based exposure protocols compete as medical devices or supplement traditional therapeutic modalities.
Market Dynamics
Telehealth reimbursement parity laws in the United States have permanently altered how agoraphobia care reaches homebound patients, forcing outpatient psychiatric clinics to restructure around hybrid delivery models rather than traditional in-person capacity.
Growth Catalysts
- FDA accelerated approval pathways:Digital therapeutics for anxiety disorders now enter clinical practice faster, reducing time-to-market for software-based exposure therapy protocols.
- SSRI first-line protocols:Established pharmacotherapy standards sustain prescription volumes across both virtual and in-person channels, anchoring medication adherence programs.
- United States:State-level telehealth parity mandates create sustained reimbursement conditions that unlock platform economics for asynchronous therapy providers.
Market Restraints
- Psychiatrist supply bifurcation:Urban hospital systems capture in-person specialists while distributed telehealth platforms drain talent, creating geographic access deserts.
- HIPAA compliance costs:Data architecture investments for telehealth platforms impose fixed cost burdens that strain smaller outpatient clinic margins.
- Exposure therapy substitution:Self-directed virtual reality applications threaten structured cognitive behavioral therapy adherence by fragmenting clinician oversight.
Strategic Opportunities
- Maintenance care phase protocols:Hybrid models blending acute teletherapy with periodic in-person assessment capture patients transitioning between treatment intensities.
- Asynchronous platform expansion:Therapist-time constraints ease through AI-guided exposure homework systems that extend session value beyond synchronous contact.
- United Kingdom:NHS digital-first mental health targets create procurement openings for FDA-cleared digital therapeutics seeking European market entry.
Industry Challenges
- Digital therapeutic certification timelines:FDA classification uncertainty between medical device and wellness software categories delays commercialization roadmaps.
- Clinician workflow integration:Telehealth platforms require retraining for psychiatric staff accustomed to in-person rapport-building techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agoraphobia Treatment Market |
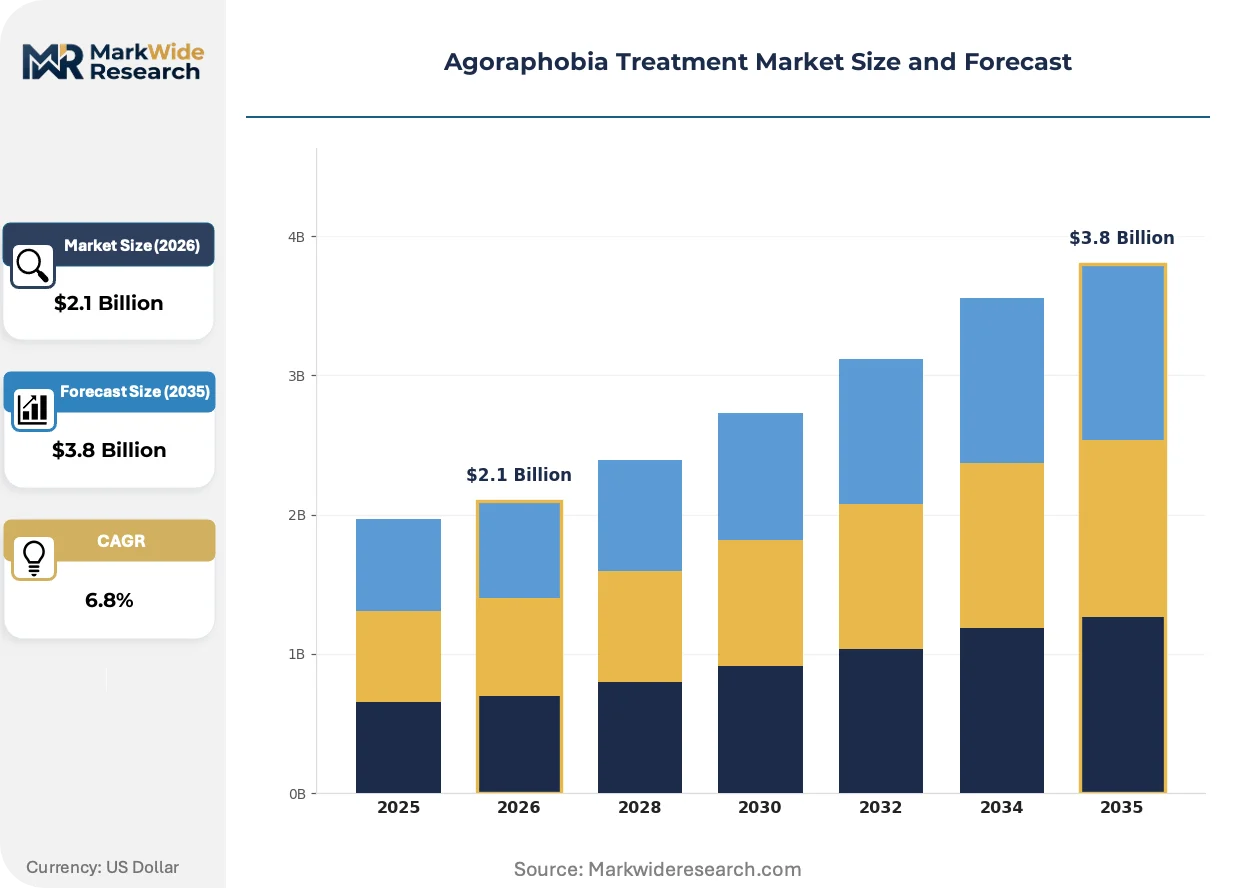
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Psychotherapy, Support Groups, Virtual Therapy Delivery Mode: In-person, Online, Teletherapy, Hybrid End User: Clinics, Hospitals, Community Health Centers, Private Practices Therapeutic Approach: Cognitive Behavioral Therapy, Exposure Therapy, Medication Management, Mindfulness Techniques |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline plc, AstraZeneca, Johnson & Johnson, Bristol-Myers Squibb Company, Novartis AG, H. Lundbeck A/S, Apotex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agoraphobia Treatment Market Emerging Trajectories
Virtual therapy delivery is compressing the traditional therapist-patient relationship into modular, platform-mediated interactions that reshape how exposure protocols are administered and monetized.
Prescription digital therapeutics is bifurcating between software-as-medical-device pathways requiring FDA premarket clearance and wellness-adjacent applications operating under enforcement discretion. Outpatient psychiatric clinics in the United States are adopting cleared exposure therapy apps at accelerating pace, while maintenance-phase patients gravitate toward lower-regulation alternatives. This divergence is bifurcating revenue models between reimbursable clinical interventions and direct-to-consumer subscription services.
REACH compliance requirements in the European Union are forcing telehealth platform operators to restructure data residency architectures for patient health records. The industrial consequence is elevated infrastructure capex for multi-jurisdictional providers seeking EU market access. United Kingdom and German mental health platforms are responding by establishing localized server clusters and appointing EU-based data protection officers ahead of MDR-aligned digital health enforcement.
Patient self-referral patterns are fragmenting traditional gatekeeper relationships between primary care physicians and psychiatric specialists. United States employer-sponsored health plans are disintermediating these channels by contracting directly with teletherapy platforms for anxiety disorder carve-outs. This channel shift is most visible in California and Texas, where large self-insured employers now account for substantial virtual agoraphobia intake volume.
Agoraphobia Treatment Market Segmentation
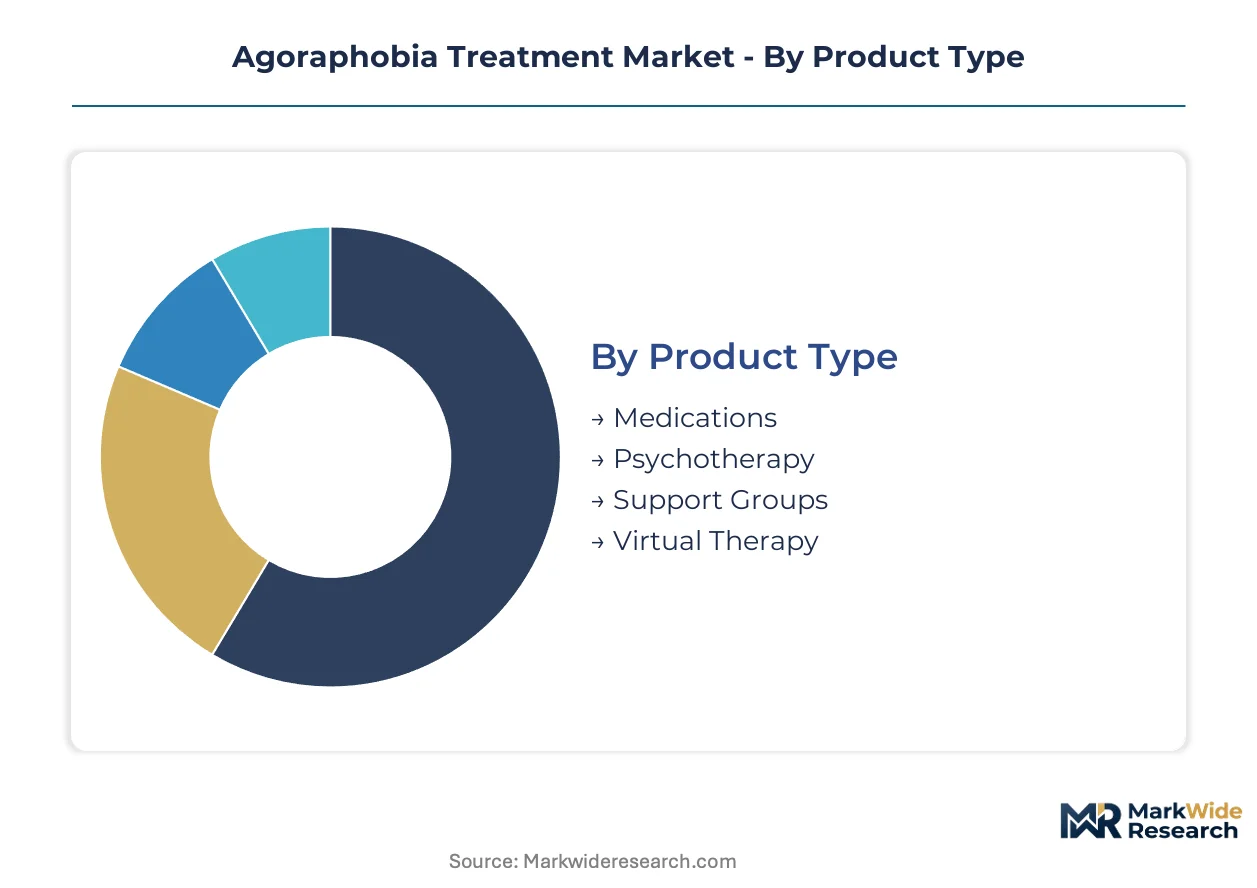
Segmentation in agoraphobia treatment reveals how care delivery is fragmenting across pharmacological, psychological, and technology-mediated channels. Each dimension carries distinct reimbursement economics and regulatory requirements that shape vendor positioning and patient access patterns.
Product Type:
Domestic prescription volumes anchor medications and psychotherapy in United States and United Kingdom markets, while virtual therapy platforms pursue export-led expansion into European and Asia-Pacific jurisdictions with nascent telehealth infrastructure.
- Medications:Selective serotonin reuptake inhibitors constitute the pharmacological foundation, with fixed-dose combinations and extended-release formulations commanding premium positioning. United States demand concentrates around Medicare Part D formularies and employer-sponsored pharmacy benefit managers, where prior authorization protocols constrain rapid generic substitution.
- Psychotherapy:Structured cognitive behavioral interventions delivered by licensed practitioners retain the highest evidence-grade reimbursement codes. United Kingdom NHS Talking Therapies procurement and United States commercial insurance carve-outs drive volume concentration, though session-frequency caps create adherence drop-off after twelve weeks.
- Support Groups:Peer-led facilitation models operate largely outside formal reimbursement, sustaining direct-to-consumer payment or charitable subsidy structures.
- Virtual Therapy:Asynchronous platform delivery reduces per-session therapist time requirements, enabling scalable unit economics for homebound patient populations.
Medications command the established base. The steepest expansion runs through virtual therapy.
Delivery Mode:
Cost tier stratification separates synchronous teletherapy at premium reimbursement rates from lower-cost asynchronous and hybrid alternatives that capture maintenance-phase patients.
- In-person:Traditional clinic-based delivery retains dominance for initial diagnostic assessment and severe presentation stabilization. Urban hospital systems in Boston, London, and Sydney concentrate specialist capacity, while rural geographies face psychiatrist supply deserts exceeding sixty-minute travel thresholds.
- Online:Web-platform asynchronous modules deliver psychoeducational content and exposure homework with minimal clinician oversight. California and Texas employer health plans now mandate online anxiety intervention availability as a network adequacy requirement, displacing some traditional employee assistance program contracts.
- Teletherapy:Real-time video consultation replicates in-person rapport-building for patients with moderate symptom severity. United States state-level parity laws in New York, Florida, and Illinois lock in reimbursement equivalence with face-to-face sessions, securing platform revenue predictability.
- Hybrid:Alternating in-person and virtual touchpoints optimize resource allocation across acute and maintenance treatment phases. United Kingdom NHS digital-first targets and German statutory health insurance pilot programs are accelerating hybrid protocol adoption.
In-person delivery retains the volume base. Hybrid models are climbing the fastest as transitional care protocols mature.
End User:
Customer-type concentration splits between institutional purchasers negotiating enterprise contracts and individual practitioners selecting point solutions based on workflow integration.
- Clinics:Outpatient psychiatric clinics in United States metropolitan corridors are restructuring around platform-mediated delivery to extend geographic catchment without proportional staff expansion. HIPAA-compliant infrastructure investments strain smaller practice margins.
- Hospitals:Academic medical centers anchor clinical trial recruitment for novel digital therapeutics, leveraging patient registries and established institutional review board pathways. Mayo Clinic, Johns Hopkins, and King's College London mental health divisions dominate protocol development.
- Community Health Centers:Federally qualified health centers in United States underserved areas aggregate Medicaid and uninsured volumes, creating procurement scale for generic medication formularies.
- Private Practices:Solo and small-group psychiatrists adopt cleared exposure therapy applications to differentiate against telehealth platform competition, though workflow retraining requirements delay implementation.
Hospitals anchor research-intensive segments. Clinics are gaining share fastest as outpatient restructuring accelerates.
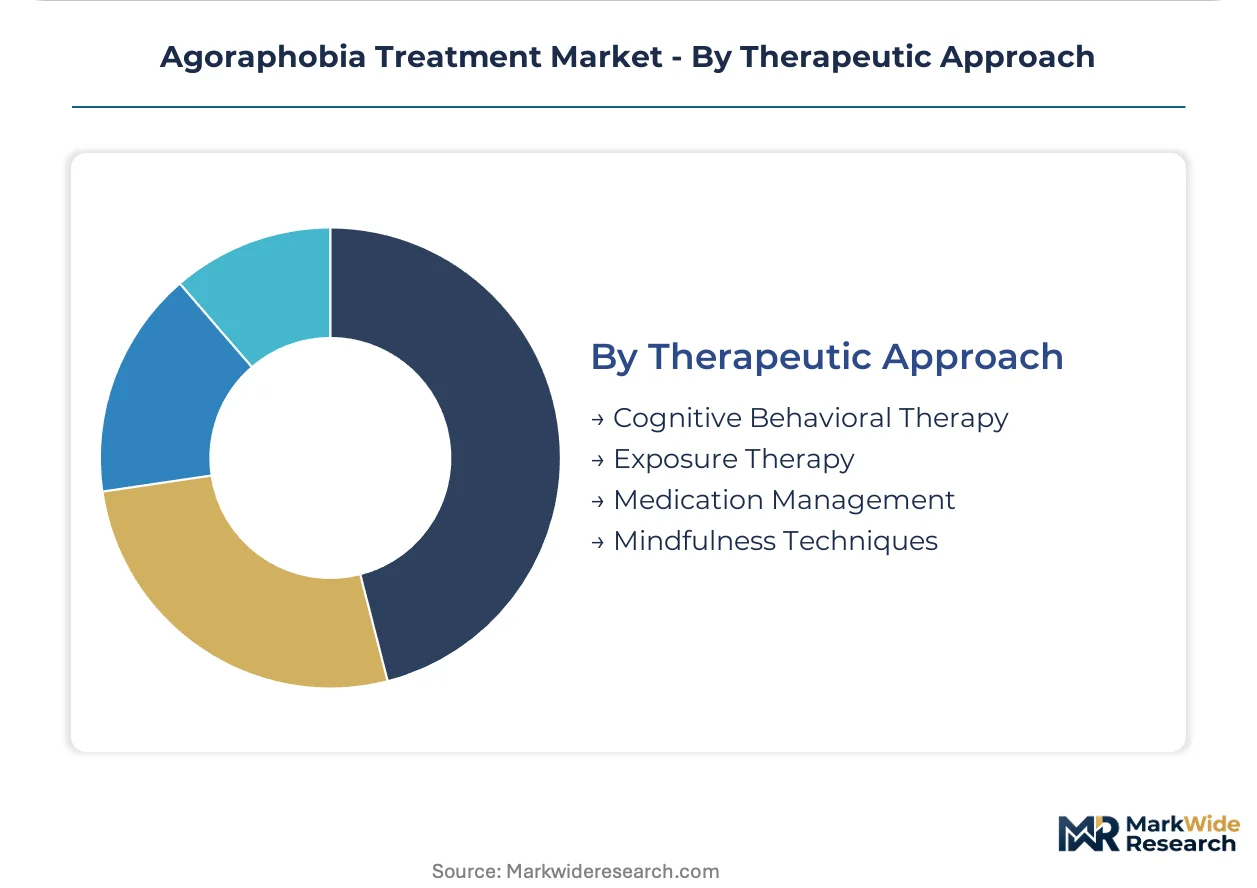
Therapeutic Approach:
Maturity differentiation separates decades-established cognitive behavioral protocols from emerging mindfulness and technology-augmented exposure modalities still accumulating payer evidence requirements.
- Cognitive Behavioral Therapy:The evidence standard for agoraphobia intervention, with manualized protocols securing the broadest insurance reimbursement. United Kingdom NICE guidelines and United States APA treatment recommendations lock in first-line status, creating sustained training demand for accredited practitioners.
- Exposure Therapy:Graduated in-vivo and imaginal confrontation with feared situations produces durable symptom reduction. Virtual reality augmentation through FDA-cleared software-as-medical-device pathways is displacing some traditional therapist-guided exposure in United States academic settings.
- Medication Management:Pharmacist-led adherence monitoring and prescriber consultation services extend SSRI protocol persistence.
- Mindfulness Techniques:Acceptance and commitment therapy derivatives attract self-pay patients seeking non-pharmacological alternatives, though reimbursement codes remain less established than CBT equivalents.
Cognitive behavioral therapy commands the established base. Exposure therapy is expanding most quickly through digital augmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for digital therapeutics anchor United States market dynamics, while state-level telehealth parity laws create sustained reimbursement conditions that reshape how agoraphobia care reaches homebound patients across multiple jurisdictions.
United States
Employer-sponsored health plans in California and Texas now contract directly with teletherapy platforms for anxiety disorder carve-outs, bypassing traditional primary care gatekeepers. Medicare Part D formularies and HIPAA mandates shape data architecture investments for platform operators. Mayo Clinic and Johns Hopkins anchor clinical trial recruitment for novel digital therapeutics in academic medical centers.
United Kingdom
NHS digital-first mental health targets create procurement openings for FDA-cleared digital therapeutics seeking European market entry. NICE guidelines lock in cognitive behavioral therapy as first-line intervention, sustaining training demand for accredited practitioners. King's College London mental health division dominates protocol development for exposure therapy augmentation.
Germany
Statutory health insurance pilot programs accelerate hybrid protocol adoption blending teletherapy with periodic in-person assessment. REACH compliance requirements force telehealth platform operators to establish localized server clusters and appoint EU-based data protection officers. Berlin and Munich concentrate psychiatric specialist capacity within urban hospital systems.
Canada
Health Canada oversight of digital therapeutic classifications determines whether software-based exposure protocols compete as medical devices or supplement traditional modalities. Provincial telehealth reimbursement frameworks vary, creating patchwork access conditions for asynchronous therapy providers. Toronto and Vancouver anchor outpatient psychiatric restructuring around platform-mediated delivery.
Australia
TGA regulatory pathways for prescription digital therapeutics influence how anxiety intervention platforms enter clinical practice. Medicare Benefits Schedule coverage for telehealth psychiatric consultations expanded during recent policy reforms, securing platform revenue predictability. Sydney and Melbourne concentrate specialist capacity while rural geographies face psychiatrist supply deserts exceeding sixty-minute travel thresholds.
Agoraphobia Treatment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical incumbents anchoring prescription volumes while digital therapeutic entrants reshape delivery economics. The structure bifurcates between SSRI manufacturers sustaining medication adherence programs and software platforms capturing asynchronous therapy growth. Three archetypes dominate: established pharmaceutical houses with psychiatric portfolios, telehealth platforms scaling virtual access, and academic medical centers anchoring clinical validation. Competitive moves concentrate on FDA clearance acquisition for digital exposure protocols and hybrid care model partnerships with outpatient clinic networks.
Among pharmaceutical incumbents, Pfizer Inc., Eli Lilly and Company, and GlaxoSmithKline plc occupy positions that exemplify distinct strategic archetypes within the agoraphobia treatment landscape. Pfizer represents the integrated volume leader leveraging established SSRI infrastructure across both virtual and in-person channels. Eli Lilly sits within the R&D-intensive tier sustaining pipeline visibility in anxiety disorders through psychiatric research investment. GlaxoSmithKline exemplifies the primary-care network competitor relying on brand recognition and physician detailing reach to defend prescription positioning.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| AstraZeneca |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| Novartis AG |
| H. Lundbeck A/S |
| Apotex Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with telehealth platform operators lock in multi-year SSRI supply commitments from Pfizer and Eli Lilly, anchoring price visibility for outpatient psychiatric clinics while securing preferential formulary positioning against generic substitution.
Pricing Analysis
Project-based pricing for FDA-cleared digital therapeutics separates reimbursable clinical interventions from direct-to-consumer wellness subscriptions. Price differentiation rests on certification grade, with FDA 510(k) clearance commanding premium reimbursement codes against enforcement-discretion alternatives. Cost compression in asynchronous therapy modules intensifies as AI-guided exposure homework reduces per-session therapist time requirements. Employer-sponsored health plans in California and Texas exhibit lowest price sensitivity, while federally qualified health centers face strict Medicaid formulary constraints.
Supply Chain Analysis
United States and Ireland anchor active pharmaceutical ingredient production for SSRI formulations, with India supplying intermediate chemical precursors. Finished dosage form manufacturing draws from Puerto Rico, Singapore, and domestic United States facilities. Single-source vulnerability concentrates around extended-release formulation technology licensed to limited contract manufacturers. Distribution runs through pharmacy benefit manager networks and direct-to-hospital contracts for academic medical center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agoraphobia treatment sits in early-cycle expansion as FDA accelerated approval pathways compress time-to-market for prescription digital therapeutics, unlocking platform economics previously tethered to traditional reimbursement timelines.
For Market Incumbents: Consolidate formulary positioning through long-term pharmacy benefit manager contracts that embed medication adherence programs, defending against generic substitution pressure. Deepen backward integration into active pharmaceutical ingredient supply to offset raw material cost volatility from Indian and Chinese intermediate suppliers. Prioritize FDA 510(k) clearance acquisition for exposure therapy software to differentiate against wellness-adjacent competitors operating under enforcement discretion.
For New Entrants and Emerging Players: Differentiate on asynchronous platform architecture that reduces therapist-time constraints per patient encounter, targeting maintenance-phase patients dropped from traditional twelve-week session caps. Penetrate United Kingdom NHS Talking Therapies procurement as FDA-cleared digital therapeutics seek European market entry under mutual recognition pathways. Pursue direct employer contracting in Texas and California self-insured markets, bypassing traditional primary care gatekeeper relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward telehealth platforms with cleared exposure therapy protocols and established HIPAA-compliant infrastructure, positioning for sustained reimbursement under state parity mandates. Long-term viability hinges on hybrid care model partnerships with outpatient clinic networks transitioning between acute and maintenance phases. Monitor FDA classification guidance for prescription digital therapeutics as the inflection signal determining whether software-based interventions compete as medical devices or supplement traditional modalities.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks reimbursable clinical positioning against wellness-adjacent competitors under enforcement discretion. |
| Pharmacy Benefit Manager Contracting | Secures Medicare Part D and employer-sponsored formulary placement against generic substitution pressure. |
| Hybrid Care Model Partnership | Captures patients transitioning between acute teletherapy and maintenance-phase in-person assessment. |
| HIPAA Infrastructure Investment | Enables multi-state platform expansion under patchwork telehealth parity reimbursement conditions. |
| NHS Digital-First Procurement | Creates European market entry for FDA-cleared exposure therapy applications under NICE guideline alignment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with telehealth platform executives, formulary directors at pharmacy benefit managers, and outpatient psychiatric clinic administrators; and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and state-level telehealth parity legislation tracking. Bottom-up patient volume estimates across delivery modes triangulated against top-down pharmaceutical prescription data from Medicare Part D and commercial insurance carve-outs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, delivery mode, end user, and therapeutic approach, with regional regulatory clusters capturing FDA, NICE, and Health Canada pathway differentiation. CAGRs derived from patient population growth assumptions, reimbursement code expansion rates, and digital therapeutic adoption curves. Industry-specific inputs included psychiatrist supply bifurcation patterns and asynchronous platform scalability metrics.
Material uncertainties — FDA classification decisions between medical device and wellness software categories, state-level telehealth parity law amendments, and exposure therapy substitution from self-directed virtual reality applications — sit outside the modeled envelope. Forecasts reflect assumptions about sustained employer-sponsored health plan contracting and NHS digital-first procurement targets. Recalibration cycles align with material shifts in regulatory guidance and reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Depression Treatment Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Schizophrenia Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Mental Health Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market