
 Depression Treatment Market | 2026-2036
Depression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Depression Treatment Market Analysis
Multi-source procurement of active pharmaceutical ingredients is restructuring supply security for antidepressant manufacturers. Eli Lilly and Company leverages captive fermentation capacity for its CNS pipeline. Pfizer Inc. sustains dual-sourcing agreements across Asian and European API suppliers. AbbVie Inc. anchors its depression portfolio through in-house synthesis of proprietary molecules.
Depression treatment encompasses pharmacological, psychological, and neuromodulatory interventions targeting dysregulated monoamine signaling and corticolimbic circuit dysfunction. Selective serotonin reuptake inhibitors remain the most prescribed first-line pharmacotherapy due to established efficacy and tolerability profiles. Atypical antidepressants represent the fastest-expanding product category, driven by mechanisms targeting glutamatergic and opioidergic pathways. Intranasal delivery modes are capturing disproportionate clinical attention following regulatory approvals for rapid-onset formulations.
The FDA's Breakthrough Therapy designation and REMS programs govern market access for novel antidepressant modalities, while the DEA schedules controlled substances used in treatment-resistant depression protocols. The European Medicines Agency's centralized marketing authorization process shapes commercialization timelines across EU member states. Stakeholders must monitor evolving reimbursement criteria for digital therapeutics and neuromodulation devices as payers recalibrate coverage frameworks for multimodal depression care.
Market Dynamics
The FDA's accelerated approval pathways for novel antidepressant mechanisms are compressing competitive entry timelines while reshaping how manufacturers prioritize CNS pipeline investments. Mental health clinics are expanding pharmacological service capacity in response to federal behavioral health parity mandates that have broadened reimbursement frameworks.
Growth Catalysts
- Behavioral Health Parity Mandates:Federal mandates in the United States have expanded reimbursement frameworks for depression management, pulling demand toward covered pharmacological and neuromodulatory interventions.
- Intranasal Delivery Innovation:Regulatory approvals for rapid-onset formulations have concentrated clinical attention on alternative administration routes for treatment-resistant protocols.
- EMA Centralized Authorization:The European Medicines Agency's streamlined marketing authorization process is reducing commercialization friction across EU member states for novel antidepressant modalities.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Dual-sourcing agreements for critical raw materials concentrate supply security risk across Asian fermentation and European synthetic chemistry hubs.
- REMS Program Friction:The FDA's Risk Evaluation and Mitigation Strategies impose distribution and prescriber certification requirements that constrain patient access to controlled-substance antidepressants.
- Generic SSRI Substitution:Patent-expired selective serotonin reuptake inhibitors exert persistent price pressure on branded first-line pharmacotherapy positioning.
Strategic Opportunities
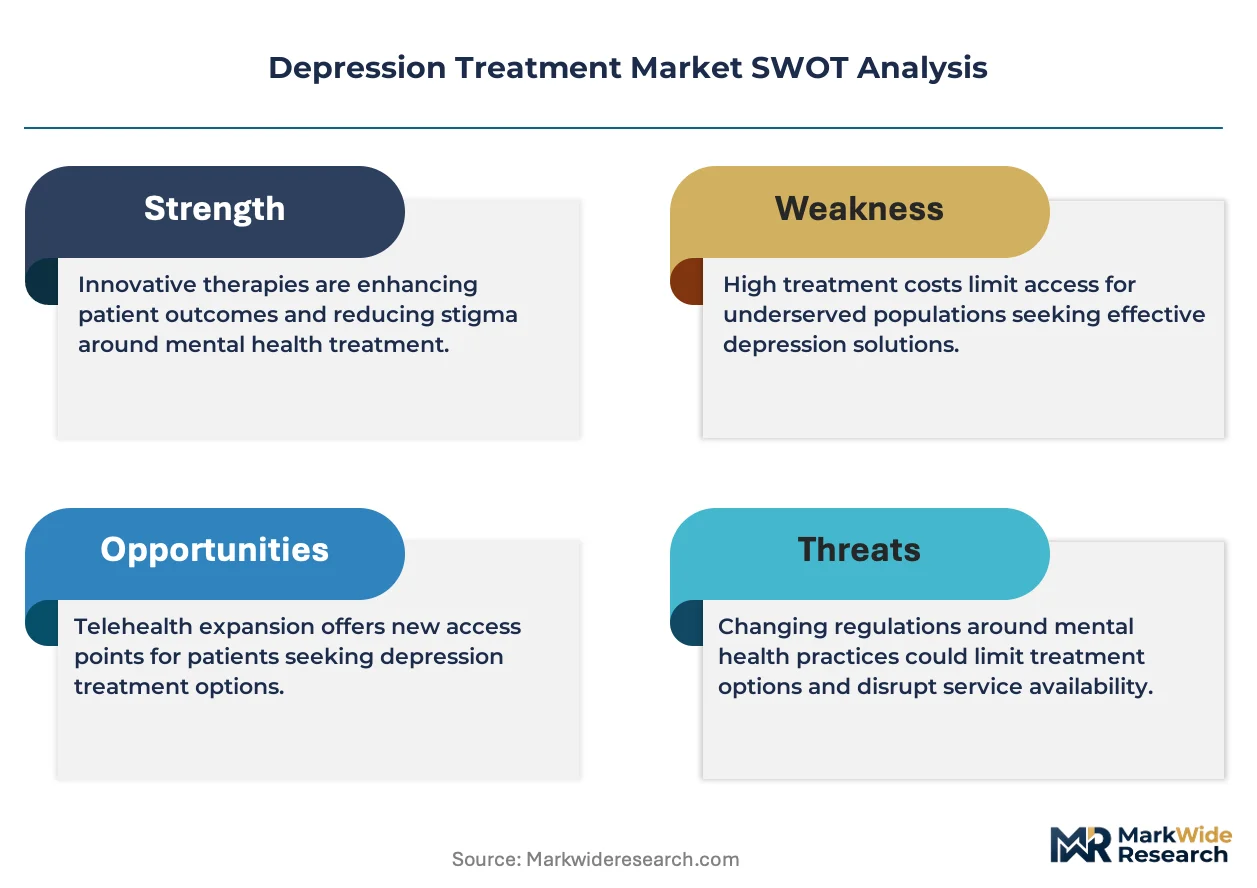
- Digital Therapeutics Reimbursement:Payer recalibration of coverage frameworks for software-based interventions creates white space for prescription digital therapeutics in multimodal care protocols.
- Neuromodulation Device Expansion:Transcranial magnetic stimulation and vagus nerve stimulation devices are penetrating outpatient clinic settings previously reserved for pharmacological monotherapy.
- Glutamatergic Mechanism Development:Atypical antidepressants targeting NMDA receptor modulation represent an emerging therapeutic class with distinct efficacy profiles for treatment-resistant populations.
Industry Challenges
- Psychiatric Trial Recruitment:Placebo response variability and patient retention difficulties in major depressive disorder trials inflate development timelines and regulatory submission risk.
- Multimodal Integration Complexity:Health systems struggle to coordinate pharmacological, psychological, and device-based interventions within unified care pathways and electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depression Treatment Market |
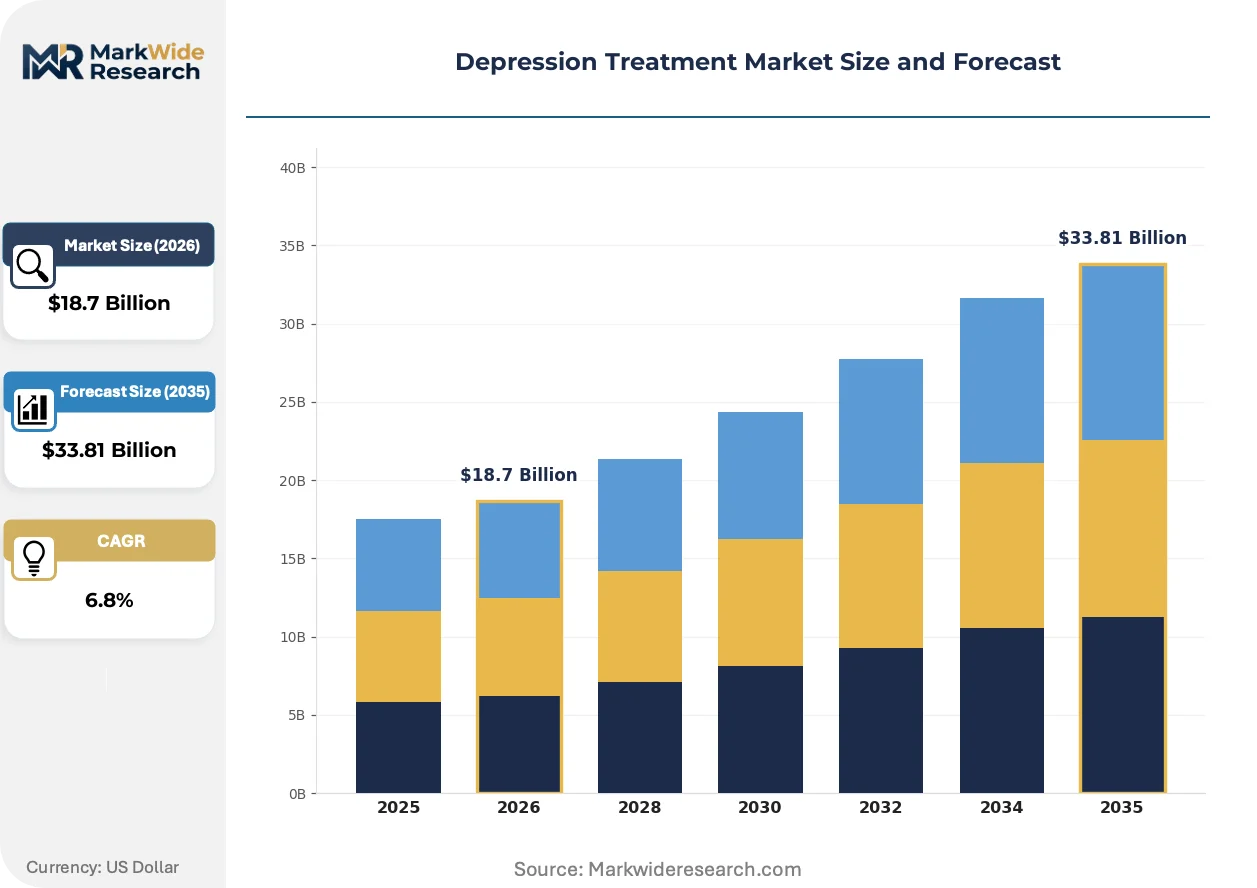
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Atypical Antidepressants, Tricyclic Antidepressants Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Treatment Approach: Medication, Psychotherapy, Electroconvulsive Therapy, Neuromodulation |
| Companies Covered | Eli Lilly and Company, Pfizer Inc., GlaxoSmithKline, Johnson & Johnson, AstraZeneca, AbbVie Inc., H. Lundbeck A/S, Otsuka Pharmaceutical, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depression Treatment Market Emerging Trajectories
Antidepressant development is pivoting toward rapid-onset mechanisms and multimodal delivery systems that challenge the weeks-long latency of monoaminergic pharmacology. Three forces are restructuring competitive positioning: automation of patient monitoring, regulatory adaptation to novel mechanisms, and compressed switching behavior among payers and prescribers.
Artificial intelligence-enabled patient monitoring platforms are automating the detection of treatment response patterns and adverse event signals in real-world settings. Academic medical centers and large integrated delivery networks are deploying these systems to reduce the latency between symptom onset and therapeutic adjustment. The technology is automating the traditional 4-6 week clinical assessment cycle that has governed SSRI titration protocols for decades.
Europe's F-Gas Regulation and Medical Device Regulation are tightening environmental and safety standards for device-based neuromodulation systems and their manufacturing processes. Manufacturers must now demonstrate lifecycle sustainability and post-market surveillance rigor that exceeds prior CE marking requirements. The MDR transition is compressing commercialization timelines for transcranial magnetic stimulation devices while favoring established players with notified body relationships.
Payers in the United States are unbundling depression care from bundled behavioral health contracts and negotiating indication-specific value arrangements with manufacturers. Large employer plans and Medicaid managed care organizations are driving this fragmentation, demanding separate evidence packages for pharmacological versus device-based interventions. This unbundling is most visible in California and New York, where state Medicaid programs have established distinct formulary tiers for rapid-onset antidepressant formulations.
Depression Treatment Market Segmentation
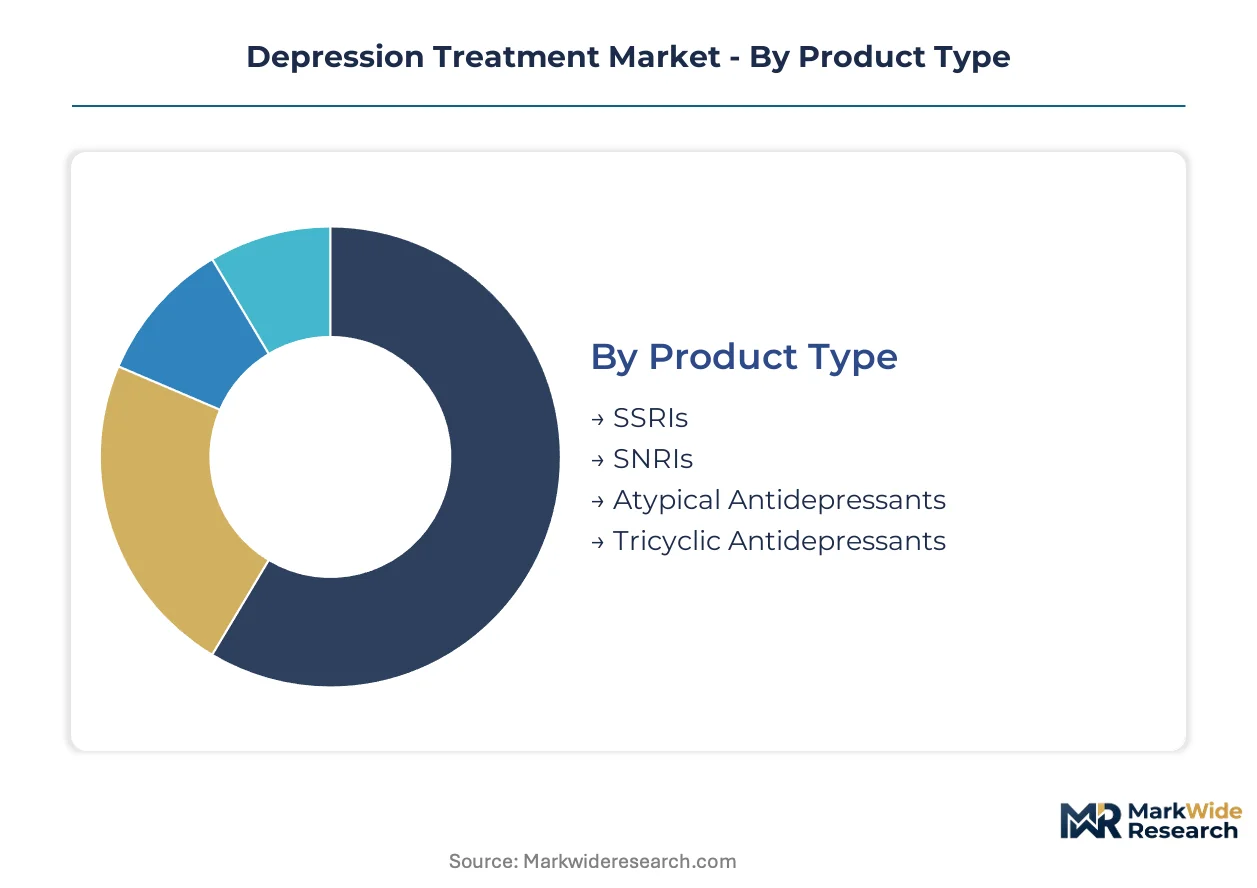
Depression treatment segmentation reveals how reimbursement pathways, clinical setting economics, and patient acuity stratify demand across pharmacological and device-based modalities. Manufacturers configure portfolio investments around these fault lines.
Product Type:
Cost tier separates first-line prescribing from salvage therapy protocols in this category.
- SSRIs:Selective serotonin reuptake inhibitors remain the most prescribed pharmacological intervention due to established tolerability profiles and generic price compression. Volume concentrates in United States Medicaid formularies where prior authorization requirements are minimal for fluoxetine and sertraline equivalents.
- Atypical Antidepressants:Mechanisms targeting glutamatergic and opioidergic pathways command premium positioning in treatment-resistant depression protocols. Demand tilts toward United States specialty pharmacies following FDA accelerated approvals for rapid-onset formulations.
- SNRIs:Dual serotonin-norepinephrine reuptake inhibition addresses comorbid pain-depression presentations in outpatient settings.
- Tricyclic Antidepressants:First-generation monoaminergic agents persist in geriatric and low-resource prescribing environments.
Volume sits with SSRIs; growth tilts toward Atypical Antidepressants.
Delivery Mode:
Patient acuity and care setting accessibility determine route selection in this dimension.
- Oral:Tablet and capsule formulations dominate maintenance therapy due to self-administration feasibility and pharmacy distribution density. United States retail pharmacy chains capture the majority of dispensed days supply under commercial and Medicare Part D coverage.
- Intranasal:Rapid-onset absorption kinetics enable emergency department and crisis intervention deployment. United States psychiatric emergency services are expanding capacity following DEA scheduling determinations for esketamine-based protocols.
- Injectable:Long-acting depot formulations address adherence gaps in severe recurrent depression.
- Transdermal:Patch delivery systems serve patients with swallowing difficulties or gastrointestinal intolerance.
Oral administration retains volume dominance; intranasal delivery is climbing the fastest.
End User:
Reimbursement rate differentials and care coordination capabilities separate institutional from ambulatory demand.
- Clinics:Mental health clinics are expanding pharmacological service capacity under federal behavioral health parity mandates. United States community mental health centers are capturing volume shifts from hospital-based psychiatric units.
- Hospitals:Inpatient psychiatric units and emergency departments manage acute suicidality and medication-resistant presentations. United States academic medical centers are concentrating neuromodulation device deployment.
- Homecare Settings:Telepsychiatry platforms and mail-order pharmacy integration enable remote monitoring.
- Rehabilitation Centers:Substance use disorder facilities address comorbid depression in integrated treatment protocols.
Clinics are gaining share fastest; hospitals retain the highest acuity concentration.
Treatment Approach:
Evidence hierarchy and payer coverage timelines stratify modality selection in this category.
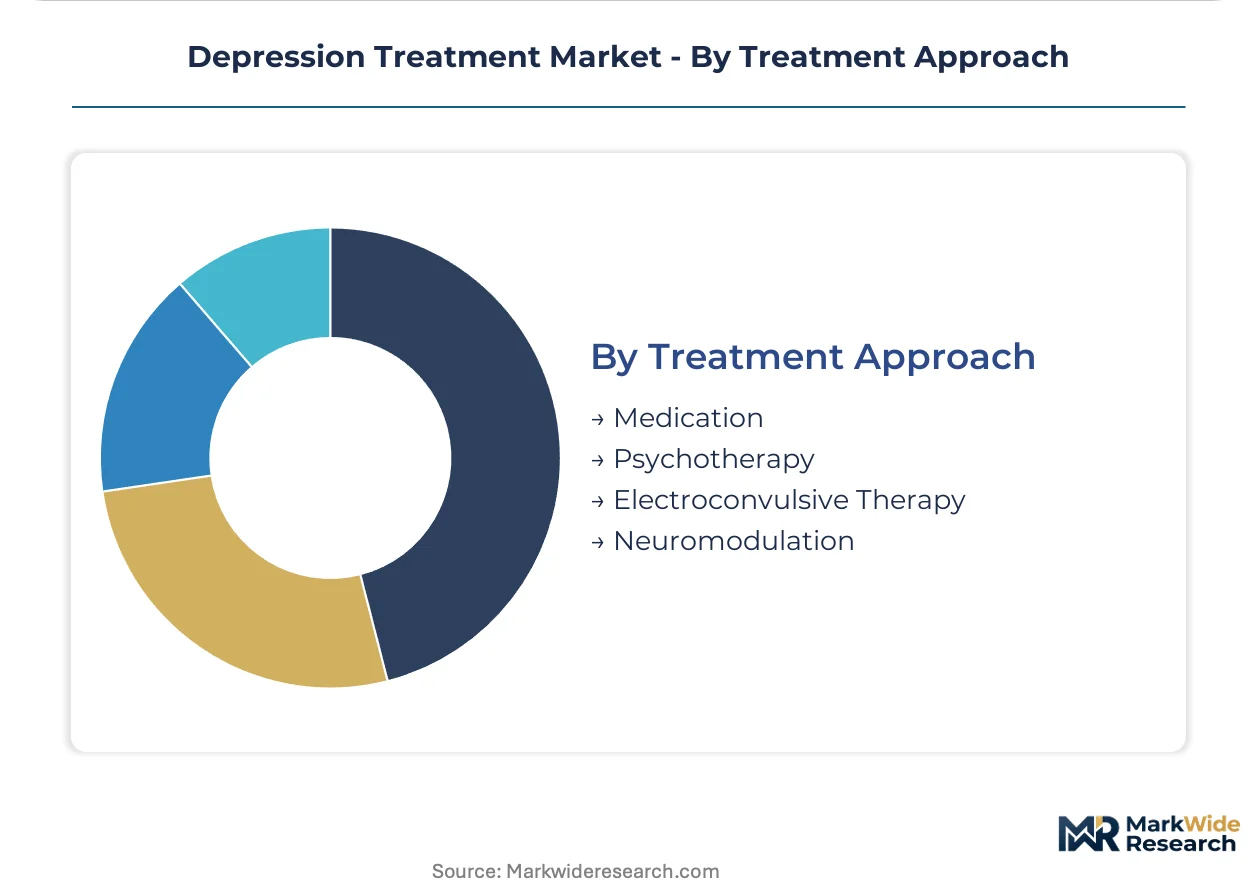
- Medication:Pharmacological monotherapy remains the default first-line intervention across severity spectrums. United States commercial payers maintain broad SSRI coverage with step-therapy requirements for branded alternatives.
- Neuromodulation:Transcranial magnetic stimulation and vagus nerve stimulation devices penetrate outpatient settings previously reserved for pharmacotherapy. United States Medicare coverage determinations are expanding access for treatment-resistant cohorts.
- Psychotherapy:Cognitive behavioral and interpersonal therapy protocols integrate with pharmacological management in collaborative care models.
- Electroconvulsive Therapy:Reserved for catatonic, psychotic, or life-threatening depression presentations in hospital-based settings.
Medication retains volume concentration; neuromodulation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where federal behavioral health parity mandates have broadened reimbursement frameworks for pharmacological and neuromodulatory interventions. Mental health clinics across multiple countries are expanding service capacity in response to regulatory pressure and unmet patient need.
United States
Medicaid managed care organizations and large employer plans are unbundling depression care from bundled behavioral health contracts. The FDA's Breakthrough Therapy designation and REMS programs govern market access for novel antidepressant modalities. Academic medical centers in Massachusetts and California are concentrating neuromodulation device deployment for treatment-resistant cohorts.
Germany
Outpatient psychiatric services are integrating pharmacological management with device-based interventions under statutory health insurance frameworks. The EMA's centralized marketing authorization process shapes commercialization timelines for novel antidepressant modalities. The Rhine-Ruhr metropolitan region hosts concentrated manufacturing capacity for active pharmaceutical ingredients serving CNS pipelines.
Japan
PMDA regulatory pathways are adapting to rapid-onset antidepressant mechanisms following international precedent for intranasal formulations. METI industrial policy supports domestic fermentation capacity for psychiatric API production. The Kanto region around Tokyo anchors specialist psychiatric hospital networks with advanced neuromodulation capabilities.
United Kingdom
NHS England's Improving Access to Psychological Therapies program is expanding multimodal care pathways that integrate pharmacological and device-based interventions. NICE technology appraisals determine coverage for novel antidepressant modalities against established SSRI benchmarks. The Greater Manchester and London health systems are piloting AI-enabled patient monitoring platforms for treatment response optimization.
India
Domestic pharmaceutical manufacturers are scaling generic SSRI production for export markets while CDSCO pathways adapt to novel mechanism submissions. The country's national pharmaceutical regulator is harmonizing with ICH guidelines for CNS drug development. Maharashtra and Gujarat host concentrated API synthesis and formulation capacity serving global antidepressant supply chains.
Depression Treatment Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers balance first-line SSRI positioning against premium atypical antidepressant development. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with CNS divisions, mid-cap neurology specialists, and generic manufacturers competing on price. Strategic archetypes include captive API producers securing supply chains, digital therapeutics developers seeking prescription status, and device manufacturers penetrating outpatient settings. M&A activity and strategic licensing agreements for rapid-onset mechanisms represent the dominant competitive moves reshaping market structure.
Among North American pharmaceutical conglomerates, Eli Lilly and Company and Pfizer Inc. exemplify divergent supply security strategies. Eli Lilly leverages captive fermentation capacity for its CNS pipeline, while Pfizer sustains dual-sourcing agreements across Asian and European API suppliers. AbbVie Inc. anchors the integrated synthesis archetype through in-house production of proprietary molecules, occupying a position between captive supply and external procurement models. These three manufacturers represent distinct responses to API concentration risk in antidepressant manufacturing.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Pfizer Inc. |
| GlaxoSmithKline |
| Johnson & Johnson |
| AstraZeneca |
| AbbVie Inc. |
| H. Lundbeck A/S |
| Otsuka Pharmaceutical |
| Merck & Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient fermentation capacity in Asian hubs feeds into three-tier pricing stratification across branded atypical antidepressants, generic SSRIs, and institutional procurement tenders. United States Medicaid formularies compress margins on first-line pharmacotherapy while specialty pharmacies capture premium positioning for rapid-onset intranasal formulations.
Pricing Analysis
Volume concentrates in generic SSRI tablets where pharmacy benefit managers extract maximum rebates, while margins accrue to atypical antidepressants with REMS-controlled distribution. Price differentiation hinges on FDA breakthrough designation status and prescriber certification requirements. Cost compression in oral maintenance therapy intensifies as Indian and Chinese manufacturers scale fermentation output. Hospital procurement committees exhibit highest price sensitivity; psychiatric emergency services show lowest sensitivity due to clinical urgency protocols.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle esketamine and controlled-substance antidepressants under DEA monitoring, while wholesale distributors manage oral generic volume. API production concentrates in India, China, and selected European synthetic chemistry hubs. Finished formulation depends on fermentation-derived precursors, specialty excipients for intranasal delivery, and cold-chain logistics infrastructure. Single-source vulnerability in NMDA receptor modulator precursors creates supply continuity exposure. Distribution runs through three-tier wholesaler networks with temperature-controlled segments for biologic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive fermentation capacity for glutamatergic API precursors props pricing power for manufacturers with backward-integrated supply chains, constraining competitive entry for rapid-onset formulations.
For Market Incumbents: Anticipate generic erosion in SSRI maintenance therapy by accelerating intranasal delivery platform investments and securing DEA quota allocations for treatment-resistant depression protocols. Defensive consolidation should target digital therapeutics developers with prescription-status pathways and FDA breakthrough-designated pipeline assets. Prioritize formulary access negotiations with United States Medicaid managed care organizations before unbundling trends harden. For New Entrants and Emerging Players: Begin with neuromodulation device penetration in outpatient clinic settings where reimbursement frameworks are expanding under Medicare coverage determinations. White space concentrates in AI-enabled patient monitoring platforms for treatment response optimization, particularly in United Kingdom integrated care systems and United States academic medical centers. Go-to-market positioning should emphasize collaborative care workflow integration over standalone pharmacological claims. For Investors and Strategic Acquirers: FDA accelerated approval determinations for novel antidepressant mechanisms are the leading indicator that valuation multiples will compress for late-stage CNS assets without distinct efficacy profiles. Long-term viability favors platforms combining pharmacological and device-based interventions with real-world evidence generation capabilities. Acquisition targets should demonstrate notified body relationships for MDR compliance and established specialty pharmacy distribution contracts. Monitor EMA centralized authorization timelines as inflection signals for European commercialization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Program Expansion | DEA-controlled distribution infrastructure creates defensible positioning for rapid-onset antidepressant formulations. |
| Digital Therapeutics Prescription Status | FDA software-as-medical-device pathways enable reimbursement integration with pharmacological protocols. |
| Captive API Fermentation Capacity | Backward integration into glutamatergic precursor synthesis secures supply continuity for NMDA-targeting pipelines. |
| Neuromodulation Device MDR Certification | European Medical Device Regulation compliance opens statutory health insurance coverage in Germany and France. |
| Specialty Pharmacy Network Partnerships | Restricted distribution agreements with CVS Specialty and AllianceRx Walgreens Prime accelerate patient access for REMS products. |
Methodological Framework
Document review covered FDA REMS program filings, EMA centralized marketing authorization assessments, ClinicalTrials.gov depression trial registries, and United States Medicaid formulary databases, complemented by interviews with drug development executives at CNS-focused pharmaceutical manufacturers, regulatory affairs leads managing breakthrough therapy designations, formulary directors at national pharmacy benefit managers, and payer access specialists at Medicaid managed care organizations. Secondary validation drew from SEC 10-K CNS segment disclosures, hospital procurement database extracts, and GPO contract repositories. Bottom-up demand modeling triangulated against top-down epidemiological prevalence estimates.
Historical prescription volume trends from IQVIA National Prescription Audit cross-referenced against primary panel input from 12 psychiatrists and 8 psychiatric emergency department medical directors across Massachusetts, California, New York, and Texas. The analytical framework segmented demand across treatment line, administration route, care setting acuity, and regional regulatory cluster throughout the projection horizon. CAGRs derived from regression analysis of approval-to-peak sales curves for antidepressant modalities launched under accelerated pathways, incorporating pricing elasticity assumptions for generic substitution scenarios and reimbursement expansion parameters for neuromodulation devices.
Underlying measurement precision varies by segment; intranasal rapid-onset formulations and neuromodulation device placements carry tighter precision than oral generic SSRI volume due to concentrated distribution channels and REMS reporting requirements. Forecasts reflect assumptions regarding FDA breakthrough therapy designation velocity, DEA scheduling determinations for controlled-substance antidepressants, and behavioral health parity mandate enforcement intensity across United States state Medicaid programs. Periodic stress-testing of base assumptions against regulatory pathway delays and API supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Schizophrenia Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Mental Health Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Schizoaffective Disorders Treatment Market