
 Novel Vaccine Delivery Systems Market | 2026-2036
Novel Vaccine Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Novel Vaccine Delivery Systems Market Analysis
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for combination products. Becton Dickinson & Company leverages its pre-filled syringe infrastructure to sustain leadership in integrated delivery platforms. Gerresheimer AG anchors its position through specialized glass and polymer primary packaging for temperature-sensitive biologics. SCHOTT AG competes via controlled manufacturing of borosilicate cartridges that meet stringent pharmacopeial standards.
Novel vaccine delivery systems encompass engineered platforms—microneedle arrays, lipid nanoparticle formulations, dry-powder inhalers, and dissolvable implants—that enable antigen presentation through non-conventional physiological routes, typically requiring stabilization excipients or controlled-release matrices to maintain immunogenicity across variable storage conditions. These systems serve the commercial purpose of improving patient compliance, reducing cold-chain dependency, and enabling rapid deployment in resource-limited settings. Microneedles and nanoparticles capture concentrated R&D investment as platforms with demonstrated thermostability advantages over conventional liquid formulations. Intranasal administration routes are gaining fastest traction among non-parenteral alternatives, driven by mucosal immune response activation and elimination of sharps waste.
The FDA's Center for Biologics Evaluation and Research and the EMA's Committee for Medicinal Products for Human Use enforce divergent evidentiary standards for device-drug combinations, compelling manufacturers to maintain parallel regulatory track strategies. WHO prequalification pathways further condition access to procurement programs in low-income country immunization schedules. Stakeholders must monitor evolving pharmacovigilance requirements for patient-administered delivery systems, as post-market surveillance obligations are expanding beyond traditional sponsor responsibilities.
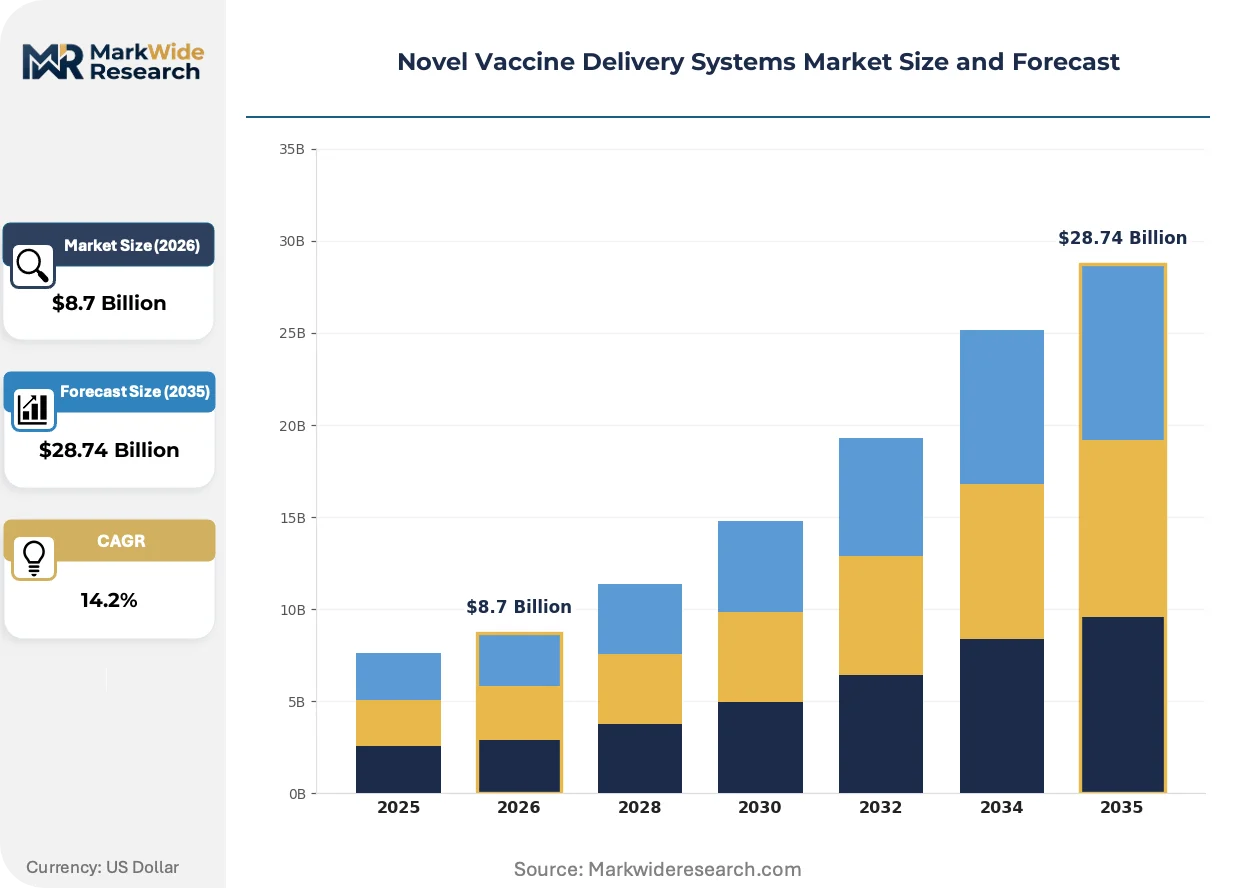
Market Dynamics
FDA's evolving guidance on combination product classification is forcing manufacturers to restructure R&D pipelines around device-drug integration requirements, compressing timelines for platform commercialization and elevating capital barriers for market entry.
Growth Catalysts
- Pediatric immunization programs:National health ministries in India and Nigeria are expanding needle-free platform procurement for school-based vaccination campaigns, reducing sharps waste disposal burdens.
- CE marking under MDR:The EU Medical Device Regulation's harmonized conformity assessment is accelerating cross-border market access for microneedle array manufacturers seeking pan-European distribution.
- Lipid nanoparticle thermostability:Stabilization excipient advances are enabling ambient-temperature storage for mRNA formulations, eliminating cold-chain infrastructure requirements in resource-limited settings.
Market Restraints
- Borosilicate glass supply concentration:Controlled manufacturing of pharmacopeial-grade cartridges depends on concentrated German and Japanese specialty glass producers, creating input bottlenecks.
- Divergent evidentiary standards:FDA's Center for Biologics Evaluation and Research and EMA's Committee for Medicinal Products for Human Use maintain non-harmonized clinical requirements, forcing parallel regulatory track investments.
- Dry-powder inhaler technical ceiling:Particle engineering limitations restrict antigen payload consistency for intranasal platforms above threshold dose volumes.
Strategic Opportunities
- Underpenetrated sub-Saharan Africa:WHO prequalification pathways for thermostable microneedle patches remain sparsely utilized by manufacturers targeting Gavi procurement programs.
- Convergence of microneedles with dissolvable implants:Controlled-release matrix integration enables multi-dose antigen presentation through single-administration platforms.
- Direct-to-pharmacy distribution:Bypassing centralized cold-chain depots for patient-administered delivery systems reduces last-mile logistics costs in Southeast Asian urban corridors.
Industry Challenges
- Biologics-device integration talent scarcity:Cross-functional expertise spanning formulation science and mechanical engineering remains concentrated among a narrow specialist pool.
- Post-market surveillance expansion:Pharmacovigilance obligations for patient-administered systems now extend beyond traditional sponsor responsibilities to healthcare provider reporting mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Novel Vaccine Delivery Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Technology: Microneedles, Nanoparticles, Liposomes, Inhalation Devices Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Vaccine Type: Inactivated, Live Attenuated, mRNA, Subunit Target Population: Pediatric, Adult, Geriatric, Immunocompromised |
| Companies Covered | Becton Dickinson & Company, Gerresheimer AG, SCHOTT AG, Inovio Pharmaceuticals Inc., Vaxxas, PharmaJet Inc., Corium International Inc., 3M Company, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Novel Vaccine Delivery Systems Market Emerging Trajectories
Microneedle array platforms are fragmenting competitive boundaries between pharmaceutical and medical device value chains, creating new partnership architectures that bypass traditional formulation-only contract manufacturers.
Solid-matrix microneedle technology is fragmenting the dominance of liquid-fill syringes by enabling antigen stabilization without refrigeration. Pediatric clinics in Brazil and Indonesia are piloting self-administered patch programs for booster doses. This platform compression is collapsing the distinction between clinical and home settings for routine immunization.
EMA's Medical Device Regulation enforcement is elevating conformity assessment costs for combination products seeking European market access. Manufacturers must now submit technical documentation through notified bodies with expanded pharmaceutical expertise scopes. Small-cap device developers without captive regulatory affairs functions are retreating from CE marking applications.
Buyer concentration among federal procurement agencies is compressing vendor negotiation leverage for novel delivery platform pricing. The United States Department of Health and Human Services now mandates thermostability thresholds in next-generation delivery technology contracts. Suppliers without demonstrated 40-degree Celsius stability data are excluded from tender consideration.
Novel Vaccine Delivery Systems Market Segmentation
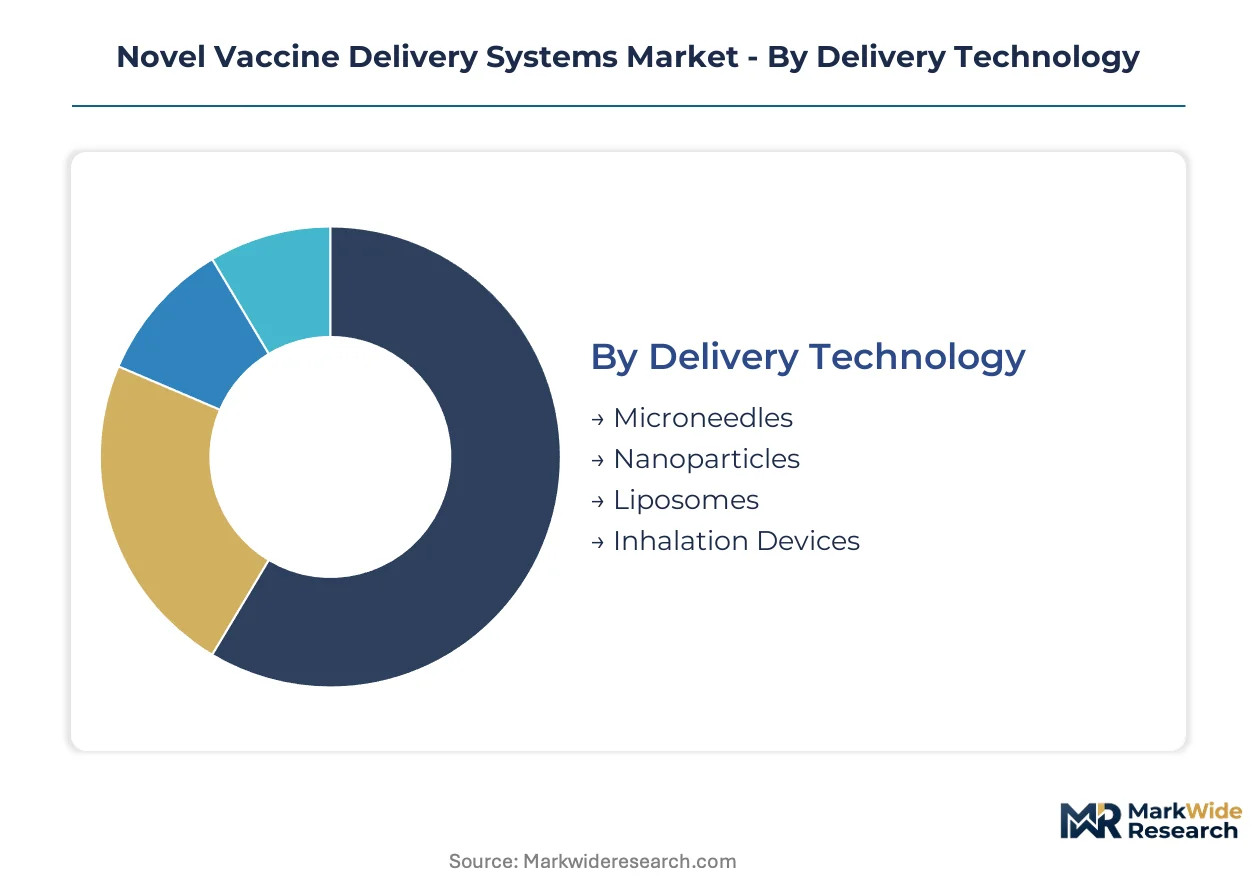
Segmentation in novel vaccine delivery systems reveals where substitution pressures and regulatory arbitrage reshape competitive boundaries. Platform choice determines cold-chain requirements, patient compliance economics, and procurement eligibility across divergent national immunization programs.
Delivery Technology:
Microneedle arrays face the most acute substitution pressure from lipid nanoparticle formulations as mRNA platform thermostability improves, while inhalation devices confront technical ceilings in dose consistency that nanoparticles circumvent through parenteral precision.
- Microneedles:Solid-matrix arrays enable antigen stabilization without refrigeration through dissolvable polymer backings. Pediatric clinics in Brazil and Indonesia pilot self-administered patch programs for booster doses, collapsing distinctions between clinical and home settings.
- Nanoparticles:Lipid-based carriers facilitate intracellular delivery and targeted immune cell uptake. FDA procurement contracts for next-generation delivery technologies now mandate thermostability thresholds that nanoparticle platforms increasingly satisfy.
- Liposomes:Phospholipid vesicles encapsulate hydrophilic and hydrophobic antigens simultaneously.
- Inhalation Devices:Dry-powder platforms activate mucosal immunity through pulmonary deposition.
Microneedles anchor the volume base while nanoparticles gain share at the steepest rate.
Administration Route:
Cost tier stratification separates parenteral routes requiring healthcare administration from patient-administered alternatives that eliminate labor costs but demand higher device sophistication.
- Intranasal:Mucosal administration induces IgA responses at pathogen entry points. Nigeria's school-based vaccination campaigns prioritize needle-free procurement, reducing sharps waste disposal burdens in resource-constrained settings.
- Intramuscular:Deep tissue deposition remains the gold standard for adjuvanted formulations. Federal procurement contracts in the United States specify intramuscular delivery as the default requirement for pandemic stockpile acquisitions.
- Subcutaneous:Shorter needle requirements suit mass vaccination throughput.
- Oral:Enteric-coated formulations bypass cold-chain infrastructure entirely.
Intramuscular administration retains dominant volume position while intranasal routes expand most quickly through pediatric program adoption.
Vaccine Type:
Application-specific requirements differentiate platform stability needs, with live attenuated formulations imposing the most stringent cold-chain constraints that novel delivery systems must overcome.
- mRNA:Encapsulated nucleic acid requires lipid nanoparticle protection against ribonuclease degradation. Stabilization excipient advances enable ambient-temperature storage, eliminating infrastructure requirements in sub-Saharan African distribution corridors.
- Subunit:Purified antigen components tolerate broader temperature ranges than live platforms. India's national immunization program evaluates subunit-loaded microneedle patches for last-mile deployment.
- Inactivated:Chemically treated pathogens maintain immunogenicity across variable storage.
- Live Attenuated:Replication-competent strains demand stringent temperature control.
Inactivated vaccines anchor current volume while mRNA platforms climb the fastest through thermostability breakthroughs.
Target Population:
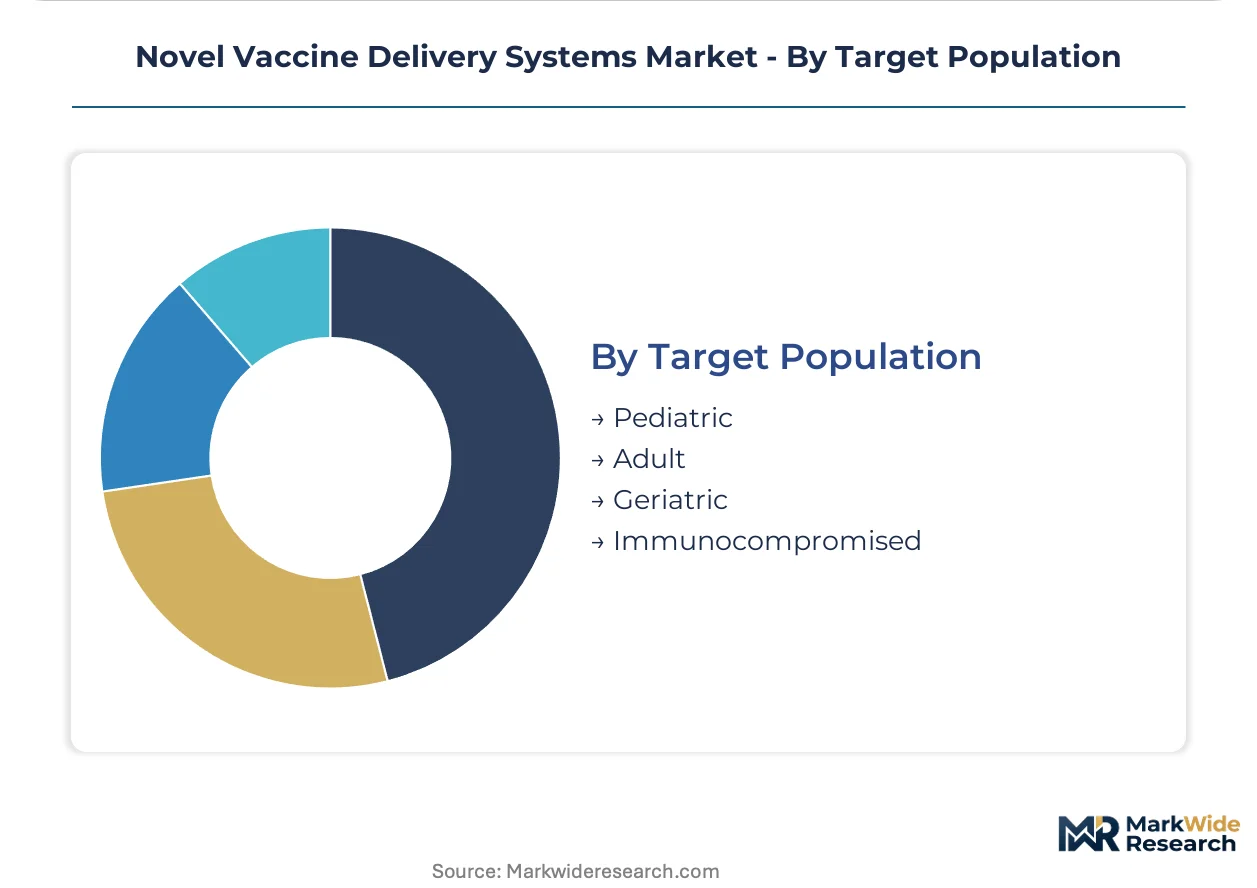
Customer type segmentation reveals divergent compliance economics, with pediatric programs prioritizing needle-free acceptance and geriatric populations requiring simplified self-administration.
- Pediatric:School-based delivery platforms reduce healthcare worker requirements. National health ministries in India and Nigeria expand needle-free procurement specifically for childhood immunization schedules.
- Immunocompromised:Non-replicating platform suitability opens specialized market access. EMA's Medical Device Regulation elevates conformity assessment costs for combination products targeting this vulnerable population.
- Adult:Workforce vaccination programs drive employer-sponsored delivery adoption.
- Geriatric:Polypharmacy interactions necessitate simplified administration protocols.
Adult populations anchor current volume while pediatric segments gain share fastest through national program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold-chain logistics corridor linking Mumbai to sub-Saharan African ports underwrites India's emergence as a manufacturing hub for thermostable delivery platforms. Federal procurement networks in the United States and EU Medical Device Regulation harmonization efforts are redrawing competitive access across major immunization markets.
United States
The Biomedical Advanced Research and Development Authority channels procurement contracts toward next-generation delivery technologies with mandated thermostability thresholds. FDA's Center for Biologics Evaluation and Research enforces combination product classification requirements that compress commercialization timelines. Boston-Cambridge clusters concentrate device-drug integration R&D for pandemic stockpile applications.
Germany
Specialty glass manufacturers anchor supply security for pharmacopeial-grade borosilicate cartridges used in temperature-sensitive biologics. CE marking under the EU Medical Device Regulation elevates conformity assessment costs for combination products seeking pan-European distribution. Baden-Württemberg industrial corridors host precision polymer engineering for microneedle array substrates.
India
National health ministries expand needle-free platform procurement for school-based vaccination campaigns across Maharashtra and Gujarat. CDSCO accelerates regulatory pathways for novel delivery systems targeting universal immunization program inclusion. Hyderabad-Bengaluru pharma corridors concentrate lipid nanoparticle formulation capacity for ambient-temperature mRNA storage.
Brazil
Pediatric clinics pilot self-administered microneedle patch programs for booster doses in São Paulo municipal health networks. ANVISA aligns post-market surveillance obligations with expanding pharmacovigilance mandates for patient-administered systems. Southeast regional manufacturing zones develop dissolvable polymer backings for tropical climate stability requirements.
Japan
PMDA maintains stringent evidentiary standards for device-drug combinations that diverge from FDA and EMA requirements. METI funding programs target microneedle thermostability research for disaster-preparedness stockpiles. Kansai industrial belts concentrate precision molding capacity for intranasal dry-powder inhaler components.
Novel Vaccine Delivery Systems Market Vendor Landscape
Listed leaders compete with private specialists across capital access and regulatory bandwidth, producing a tiered structure where scale advantages in pre-filled syringe infrastructure confront nimble innovation in solid-matrix platforms. The vendor base stratifies across three archetypes: diversified medical device conglomerates with captive pharmaceutical packaging divisions, pure-play delivery technology developers, and contract manufacturing organizations with specialized combination product expertise. Dominant competitive moves include strategic partnerships bridging formulation science and mechanical engineering capabilities, plus geographic expansion through WHO prequalification pathway navigation.
Within the diversified device tier, Becton Dickinson & Company and Terumo Corporation occupy positions anchored by pre-filled syringe infrastructure that sustains leadership in integrated delivery platforms. Among specialized packaging fabricators, Gerresheimer AG and SCHOTT AG exemplify the glass-and-polymer primary packaging archetype for temperature-sensitive biologics. Vaxxas represents the pure-play microneedle developer segment targeting procurement program eligibility through thermostability demonstration.
| Leading Market Players |
|---|
| Becton Dickinson & Company |
| Gerresheimer AG |
| SCHOTT AG |
| Inovio Pharmaceuticals Inc. |
| Vaxxas |
| PharmaJet Inc. |
| Corium International Inc. |
| 3M Company |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term federal procurement contracts with mandated thermostability thresholds lock in supply access for borosilicate glass cartridges and polymer microneedle substrates while anchoring price visibility across multi-year immunization schedules. These structures concentrate purchasing power among US Department of Health and Human Services agencies and Gavi procurement programs, compressing margin flexibility for device-drug combination suppliers without demonstrated stability data.
Pricing Analysis
Certification level (FDA-grade, CE-marked, WHO-prequalified) creates the primary spread between premium and standard tiers, with combination products commanding substantial premiums over standalone devices. Three-tier pricing structure separates validated cold-chain-independent platforms from conventional liquid-fill systems and unproven early-stage formats. Cost compression in standard-tier pre-filled syringes intensifies as Becton Dickinson and Terumo leverage captive manufacturing scale. Pediatric procurement programs demonstrate highest price sensitivity, while pandemic stockpile buyers prioritize thermostability performance over unit economics.
Supply Chain Analysis
Germany and Japan anchor pharmacopeial-grade borosilicate glass production for temperature-sensitive biologics, while India and China concentrate polymer substrate fabrication for microneedle arrays. Specialty glass draws from concentrated German and Japanese feedstock, with polymer substrates sourcing from Southeast Asian petrochemical corridors. Single-source vulnerability concentrates in SCHOTT AG and Nipro Pharma packaging divisions for cartridge supply. Distribution runs through centralized cold-chain depots in mature markets and direct-to-pharmacy channels in Southeast Asian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face acute substitution pressure from lipid nanoparticle thermostability advances that threaten microneedle array dominance in pediatric segments. Defense requires rapid capability consolidation around device-drug integration.
For Market Incumbents: Fortify pre-filled syringe infrastructure through backward integration into polymer substrate production, locking in supply security as borosilicate glass bottlenecks intensify. Accelerate CE marking investments under EU MDR to defend European market access against retreating small-cap competitors. Prioritize thermostability validation partnerships with mRNA platform developers to neutralize lipid nanoparticle substitution threats. For New Entrants and Emerging Players: WHO prequalification fast-tracks offer the most penetrable regulatory pathway for thermostable microneedle patches targeting Gavi procurement programs in sub-Saharan Africa. Underpenetrated school-based vaccination campaigns in Nigeria and India present white-space demand with reduced competitive density. Lead with direct-to-pharmacy distribution models that bypass incumbent cold-chain depot networks. For Investors and Strategic Acquirers: Pure-play delivery technology developers with demonstrated thermostability data and active WHO prequalification submissions represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory bandwidth expansion rather than manufacturing scale alone. Watch FDA combination product classification guidance revisions as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR harmonization accelerates pan-European distribution for microneedle array manufacturers. |
| Backward Integration | Captive polymer substrate production reduces dependency on concentrated German glass suppliers. |
| WHO Prequalification | Prequalification unlocks Gavi procurement eligibility for sub-Saharan African immunization programs. |
| Hospital System Partnership | Pediatric clinic networks in Brazil and Indonesia pilot self-administered patch programs. |
| Reimbursement Strategy | Federal procurement contract structures mandate thermostability thresholds for pandemic stockpile inclusion. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across formulation science, mechanical engineering, and regulatory affairs functions. Primary interviews captured device-drug integration specialists, combination product regulatory leads, and pediatric immunization program procurement managers at national health ministries. Secondary validation drew from FDA Center for Biologics Evaluation and Research guidance documents, EMA Medical Device Regulation technical documentation requirements, WHO prequalification pathway filings, and Gavi procurement tender databases. Bottom-up platform adoption modeling triangulated against top-down immunization program budget allocations.
Across the analysis window, forecasts employed segmented modeling across delivery technology, administration route, vaccine type, and target population dimensions. CAGRs were derived from elasticity-adjusted adoption curves for thermostable platforms in resource-limited settings. Industry-specific inputs included cold-chain infrastructure density indices, pediatric program expansion timelines, and divergent evidentiary standard compliance costs across FDA and EMA jurisdictions.
Underlying assumptions cover stabilization excipient advancement rates and procurement program budget continuity, with deviation risk concentrated in regulatory harmonization failures and borosilicate glass supply disruptions. Forecasts reflect these documented conditions with acknowledged sensitivity to pharmacovigilance mandate expansions. Recalibration cycles align with material shifts in FDA combination product classification guidance and WHO prequalification pathway revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Submucosal Injections Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Corneal Implants Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Medical Device Regulatory Affairs Market