
 US Veterinary Oncology Market | 2026-2036
US Veterinary Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
US Veterinary Oncology Market Intelligence
Specialized equipment leasing and pay-per-procedure financing is narrowing the capital barrier for independent veterinary practices entering radiation therapy. Zoetis leverages its pharmaceutical portfolio to anchor comprehensive oncology protocols across multi-site hospital networks. PetCure Oncology dominates mobile stereotactic radiosurgery deployment, extending advanced treatment access to secondary markets without fixed-installation overhead. Accuray Incorporated competes on precision delivery systems calibrated for companion-animal anatomy.
US veterinary oncology encompasses the diagnosis, staging, and multimodal treatment of malignant neoplasms in companion and production animals, employing cytotoxic agents, immunomodulatory biologics, ionizing radiation, and targeted small-molecule inhibitors formulated for species-specific metabolism and body surface area dosing. Chemotherapy retains the largest patient volume share due to established protocols for lymphoproliferative disorders, while immunotherapy represents the fastest-expanding product type as canine melanoma vaccines and checkpoint inhibitors gain conditional approvals. Dogs anchor absolute demand across all treatment stages, though feline oncology services command premium pricing reflecting diagnostic complexity and anesthesia risk management.
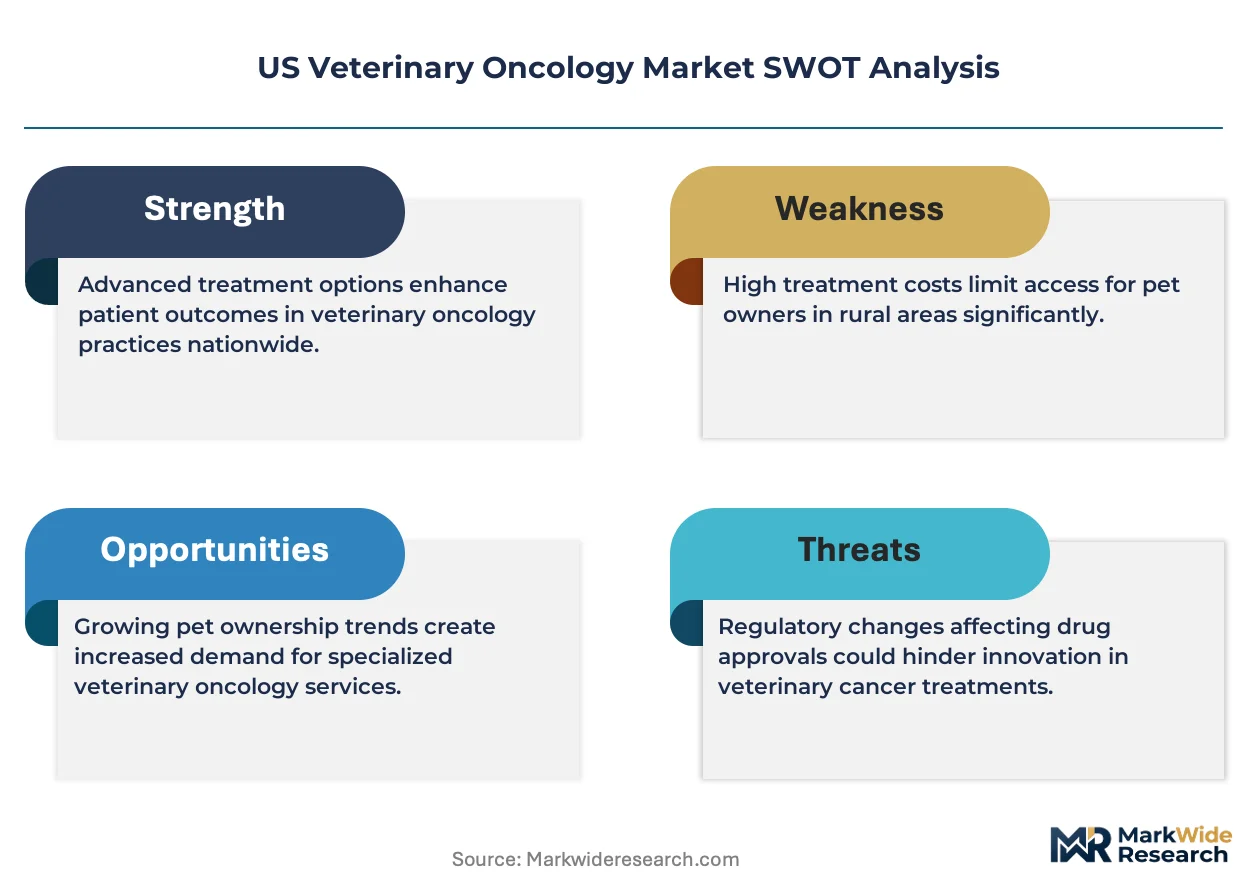
FDA Center for Veterinary Medicine regulates veterinary oncology drugs under the New Animal Drug Application pathway, with the USDA Center for Veterinary Biologics overseeing autologous and allogeneic cancer vaccines that shape product development timelines and label claims. State veterinary medical boards enforce practice act provisions governing chemotherapy administration, radiation safety certification, and telemedicine prescribing that determine service delivery models and geographic expansion feasibility. Stakeholders must monitor evolving compounding pharmacy enforcement, reimbursement coding alignment with pet insurance policies, and specialty credentialing standards as these collectively determine which practice configurations capture margin in curative versus palliative care segments.
Market Dynamics
Pet insurance penetration above 25% in US coastal states is compressing payment cycles and shifting treatment decisions toward curative-intent protocols previously deferred due to cost sensitivity.
Growth Catalysts
- FDA Center for Veterinary Medicine:Accelerated conditional approval pathways for canine melanoma vaccines and checkpoint inhibitors are compressing development timelines for domestic biologics manufacturers.
- Specialty hospital networks:California and Northeast corridor referral centers are consolidating oncology service lines to capture insured pet volume seeking multimodal cancer care.
- Mobile stereotactic radiosurgery:Deployment of truck-mounted linear accelerators is virtualizing fixed-installation radiation infrastructure and extending advanced treatment access to secondary US markets.
Market Restraints
- Isotope supply concentration:Molybdenum-99 for diagnostic imaging depends on aging North American reactors and foreign enrichment facilities, creating vulnerability in staging protocols.
- USDA Center for Veterinary Biologics:Autologous vaccine approval timelines extend 18-24 months, delaying revenue recognition for personalized immunotherapy developers.
- Anesthesia mortality risk:Feline patients carry threefold higher periprocedural mortality versus canines, restricting service expansion in premium feline oncology segments.
Strategic Opportunities
- Telemedicine prescribing:State veterinary medical boards in Texas and Florida are relaxing interstate consultation rules, enabling remote oncology case management for rural practices.
- Compounding pharmacy enforcement:FDA scrutiny of bulk ingredient sourcing is creating compliance-driven demand for certified 503B facilities producing patient-specific chemotherapy.
- Pet insurance coding alignment:Standardized reimbursement categories for staging diagnostics are reducing claims friction and accelerating treatment authorization cycles.
Industry Challenges
- Radiation safety certification:State-level requirements for veterinary radiation therapy physicists vary widely, constraining workforce mobility and service expansion timelines.
- Chemotherapy administration protocols:OSHA exposure limits for cytotoxic handling require engineered containment systems that elevate fixed costs for independent practice entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Veterinary Oncology Market |
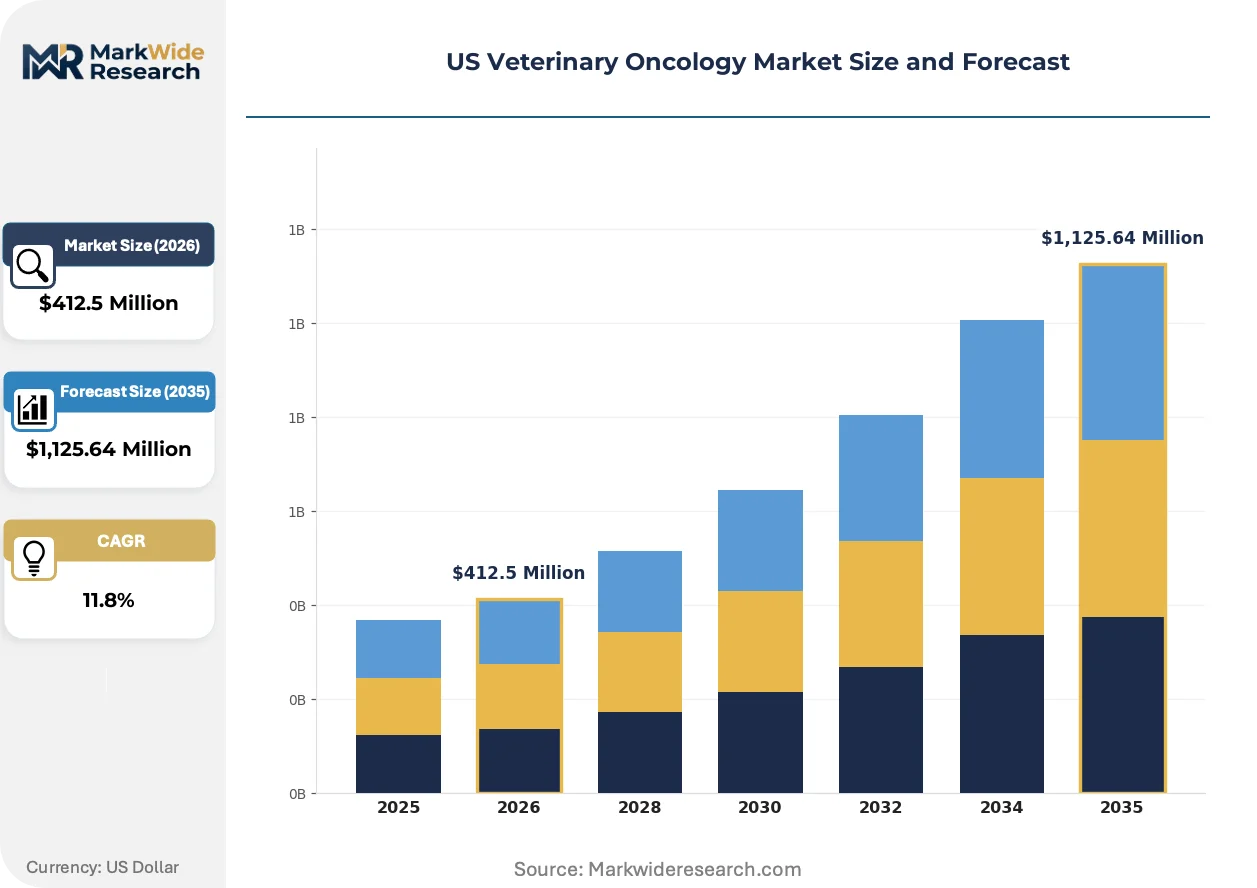
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Animal Type: Dogs, Cats, Horses, Exotic Pets Treatment Stage: Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care, Maintenance Treatment Distribution Channel: Veterinary Clinics, Hospitals, Online Retail, Pharmacies |
| Companies Covered | Merck Animal Health, Accuray Incorporated, Zoetis, Virbac, Elekta AB, Elanco, PetCure Oncology, Ardent Animal Health, Boehringer Ingelheim International GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Veterinary Oncology Market Strategic Shifts & Innovations
Artificial intelligence staging algorithms and species-specific biologics are converging to compress diagnostic timelines and personalize treatment selection in ways that reshape referral patterns between primary and specialty care.
Teleradiology platforms employing convolutional neural networks are virtualizing the interpretation of thoracic and abdominal imaging for metastasis detection. General practice veterinarians in the Midwest and Mountain West are adopting these tools at accelerating rates, reducing referral lag time from days to hours. This virtualization is compressing the window between suspicion and definitive staging, shifting competitive advantage toward practices integrating rapid diagnostic workflows.
The FDA Center for Veterinary Medicine's expanded use of pilot programs under the MUMS pathway is accelerating conditional approvals for minor-use species oncology drugs. This regulatory flexibility is drawing pharmaceutical investment toward feline lymphoma and equine sarcoid indications previously deprioritized due to market size constraints. Specialty compounding pharmacies are responding by developing species-specific formulation capabilities that align with evolving label claims.
Subscription-based wellness plans bundled with catastrophic coverage are displacing fee-for-service payment in metropolitan veterinary markets. Pet owners in Seattle, Denver, and Austin are enrolling at rates that shift treatment conversations from cost containment toward outcome optimization. This behavioral pivot is elevating willingness-to-pay for adjuvant chemotherapy and hypofractionated radiation protocols in insured populations.
US Veterinary Oncology Market Segmentation
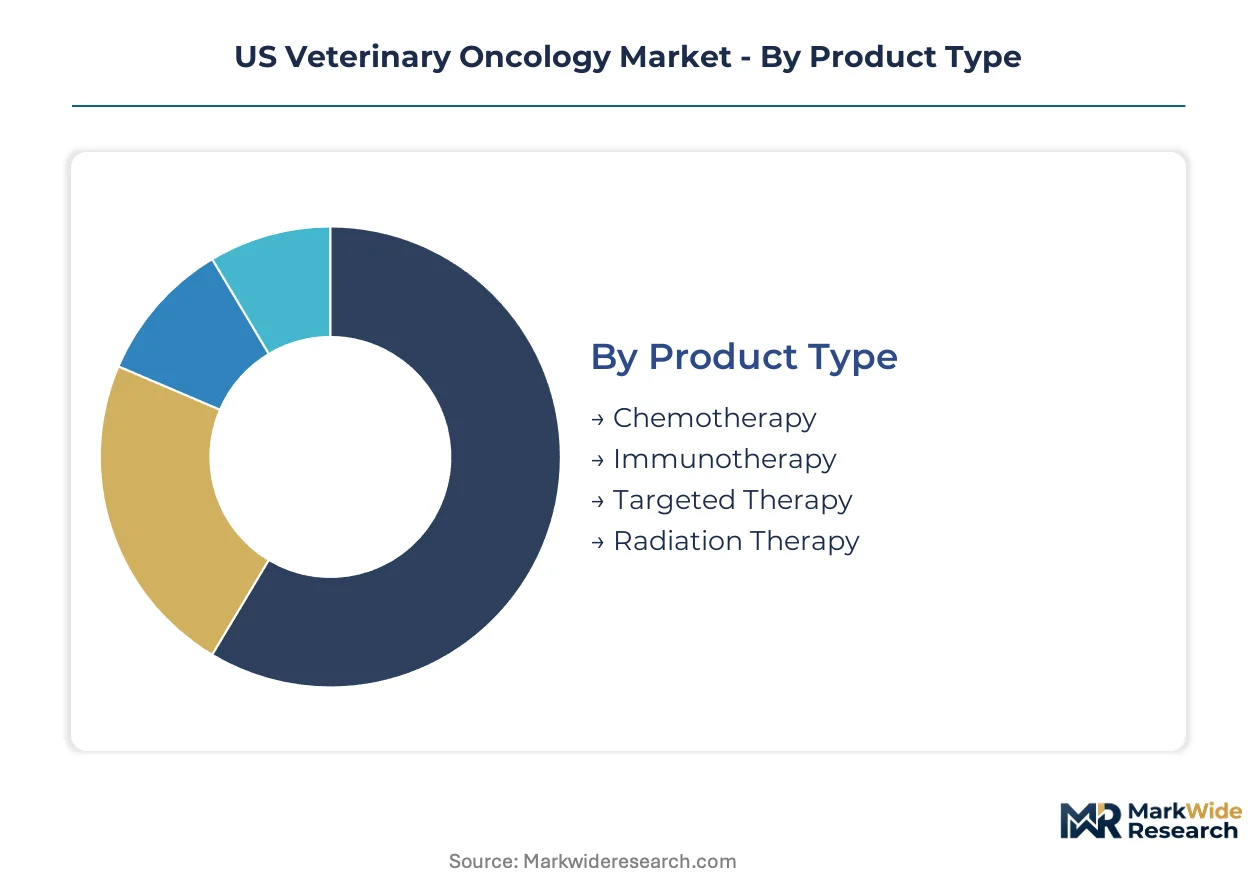
Treatment modality selection in US veterinary oncology hinges on tumor histology, staging completeness, and owner financial commitment. Segmentation reveals where capital investment concentrates and which patient populations command premium protocol pricing.
Product Type:
Cost tier determines accessibility and margin structure across therapeutic categories, with biologics carrying higher development amortization than cytotoxic agents.
- Chemotherapy:Alkylating agents, anthracyclines, and vinca alkaloids formulated for species-specific body surface area dosing anchor patient volume in lymphoproliferative protocols. Demand concentrates at specialty hospitals in California and the Northeast corridor where insured canine lymphoma cases drive protocol adherence.
- Immunotherapy:Canine melanoma vaccines and checkpoint inhibitors represent the steepest expansion trajectory as FDA Center for Veterinary Medicine conditional approvals compress development timelines. Investment from domestic biologics manufacturers is accelerating following recent pilot program expansions.
- Targeted Therapy:Small-molecule inhibitors calibrated for companion-animal metabolism address mast cell tumors and osteosarcoma with reduced systemic toxicity versus cytotoxic alternatives.
- Radiation Therapy:Stereotactic radiosurgery and conventional fractionated protocols require capital-intensive linear accelerator deployment, with mobile units extending access to secondary markets.
Chemotherapy holds installed capacity. Immunotherapy is rotating up the share rankings.
Animal Type:
Patient physiology and anesthesia risk profile shape service pricing and protocol selection across species.
- Dogs:Canine patients anchor absolute demand across all treatment stages, with lymphoma and mast cell tumor segments demonstrating highest owner willingness-to-pay for curative-intent multimodal care.
- Cats:Feline oncology commands premium pricing reflecting diagnostic complexity, anesthesia mortality risk threefold higher than canines, and specialized formulation requirements for species-specific metabolism.
- Horses:Equine sarcoid and melanoma indications are gaining pharmaceutical investment following FDA MUMS pathway flexibility for minor-use species.
- Exotic Pets:Ferret lymphoma and rabbit thymoma cases represent niche demand concentrated at academic veterinary medical centers with specialized anesthesia and surgical capabilities.
Dogs hold installed capacity. Cats are rotating up the share rankings.
Treatment Stage:
Margin structure varies sharply between curative-intent and comfort-focused protocol endpoints.
- Adjuvant Therapy:Post-surgical chemotherapy and radiation protocols target microscopic residual disease, with completion rates rising among insured populations in coastal states where pet insurance penetration exceeds 25 percent.
- Neoadjuvant Therapy:Pre-surgical cytoreduction shrinks unresectable tumors to operable margins, requiring tight coordination between medical and surgical oncology services.
- Palliative Care:Pain management and quality-of-life protocols address advanced disease with reduced toxicity emphasis, often employing hypofractionated radiation and metronomic chemotherapy.
- Maintenance Treatment:Low-dose continuous or intermittent therapy extends remission duration in lymphoma and mast cell tumor patients following initial response.
Adjuvant Therapy holds installed capacity. Palliative Care is rotating up the share rankings.
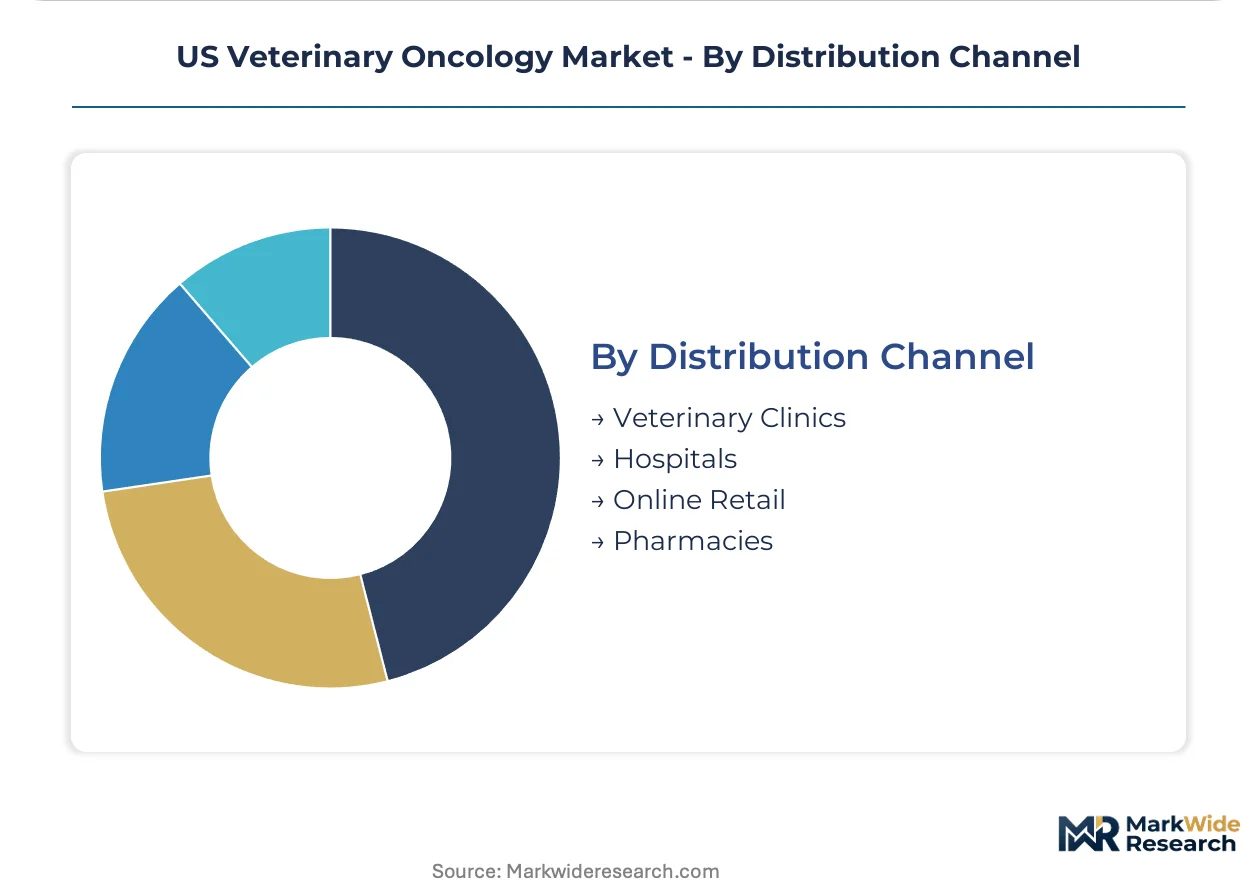
Distribution Channel:
Channel selection determines regulatory compliance burden and patient access speed.
- Veterinary Clinics:Primary care practices administer chemotherapy and coordinate referrals, with OSHA exposure limits for cytotoxic handling requiring engineered containment systems that elevate fixed costs.
- Hospitals:Specialty referral centers in Texas and Florida consolidate multimodal oncology service lines, capturing insured pet volume seeking definitive staging and curative protocols.
- Online Retail:Compounded oral medications and supportive care products reach rural practices through verified 503B facilities responding to FDA bulk ingredient sourcing scrutiny.
- Pharmacies:Certified veterinary pharmacies manage controlled substance dispensing and chemotherapy preparation under state board oversight.
Hospitals hold installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the California-Northeast corridor where pet insurance penetration exceeds 25 percent, while Mountain West and Southwest markets operate on compressed margins and referral-dependent staging workflows.
California
Specialty hospital networks in Los Angeles and San Francisco Bay Area dominate multimodal oncology service lines, capturing insured canine lymphoma volume seeking curative-intent protocols. FDA Center for Veterinary Medicine oversight of novel biologics accelerates clinical trial investment by domestic manufacturers headquartered in San Diego biotech clusters. The Golden State anchors absolute demand for stereotactic radiosurgery and immunotherapy administration.
Northeast Corridor
Metropolitan veterinary referral centers from Boston through New York to Philadelphia consolidate radiation therapy and chemotherapy administration for insured pet populations. State veterinary medical boards enforce stringent OSHA exposure limits for cytotoxic handling, elevating compliance costs for independent practice entry. Academic veterinary medical centers at Cornell and University of Pennsylvania drive protocol standardization and specialist credentialing density.
Texas
Dallas-Fort Worth and Houston specialty hospitals expand oncology service lines to capture migrating insured pet volume from coastal markets. The Texas State Board of Veterinary Medical Examiners relaxes interstate telemedicine consultation rules, enabling remote case management for rural practices. Mobile stereotactic radiosurgery units deploy through secondary markets including Austin and San Antonio.
Florida
Southeast retirement corridors concentrate geriatric pet populations with elevated cancer incidence, driving demand for palliative care and quality-of-life protocols. Florida's veterinary medical board aligns with Texas on telemedicine flexibility, supporting remote oncology consultation for Panhandle and Central Florida practices. Miami and Tampa specialty centers capture seasonal insured pet volume from Northeast snowbird migration.
Pacific Northwest
Seattle and Portland metropolitan areas exhibit highest subscription wellness plan enrollment rates, shifting treatment conversations from cost containment toward outcome optimization. Washington and Oregon state veterinary boards emphasize radiation safety certification requirements that constrain workforce mobility. Academic partnerships between Washington State University and private specialty hospitals accelerate teleradiology adoption for metastasis detection.
US Veterinary Oncology Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying precision delivery systems and species-specific biologics. The vendor base organizes around three strategic archetypes: pharmaceutical conglomerates anchoring comprehensive protocol portfolios, radiation equipment manufacturers competing on anatomical calibration, and mobile service providers virtualizing fixed-installation infrastructure. Consolidation concentrates among multi-site hospital networks acquiring independent oncology practices, while technology licensing agreements accelerate biologics development timelines.
Within the pharmaceutical integrator tier, Zoetis and Merck Animal Health exemplify platform dominance through vertically aligned oncology portfolios spanning diagnostics to therapeutics. Among radiation equipment specialists, Accuray Incorporated occupies a position calibrated for companion-animal anatomical precision. PetCure Oncology represents the mobile service archetype, extending advanced stereotactic radiosurgery access to secondary markets without fixed-installation capital requirements.
| Leading Market Players |
|---|
| Merck Animal Health |
| Accuray Incorporated |
| Zoetis |
| Virbac |
| Elekta AB |
| Elanco |
| PetCure Oncology |
| Ardent Animal Health |
| Boehringer Ingelheim International GmbH |
| Others |
Cost & Logistics Intelligence
Underutilized linear accelerator capacity in Mountain West specialty hospitals is compressing per-procedure pricing for radiation therapy while forcing equipment lessors to extend financing terms for independent practice entry. This capacity glut simultaneously elevates bargaining leverage for consolidated hospital networks in California and the Northeast corridor, where insured pet density sustains premium pricing for curative-intent protocols.
Pricing Analysis
The customization-premium spread between standard chemotherapy protocols and patient-specific immunotherapy dosing separates economy-tier lymphoma management from premium melanoma vaccine regimens. Three-tier pricing structure across premium, standard, and economy levels reflects FDA approval status, with conditional biologics commanding 40-60% markups over established cytotoxic agents. Cost compression in standard chemotherapy is intensifying because compounded generic alternatives displace branded formulations in price-sensitive rural markets. Independent veterinary clinics exhibit highest price sensitivity due to OSHA-mandated containment capital requirements, while multi-site hospital networks absorb premium pricing through insurance-backed volume.
Supply Chain Analysis
Extended payment terms from 30 to 90 days for isotope sourcing are straining working capital at diagnostic imaging distributors serving secondary markets. Molybdenum-99 supply concentrates in Canada and the Netherlands, with secondary enrichment capabilities in South Africa and Australia providing geographic redundancy. Cold-chain logistics for canine melanoma vaccines hinge on domestic biologics manufacturing in Massachusetts and California, creating single-source vulnerability for personalized immunotherapy developers. Distribution runs through specialty veterinary distributors with regional cold-storage infrastructure, though direct-to-hospital contracting is displacing traditional wholesale channels for high-value biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pet insurance carriers standardizing reimbursement codes, compressing margins for practices unable to demonstrate outcome metrics. This consolidation shifts negotiation leverage from individual veterinarians toward pooled purchasing entities.
For Market Incumbents: Insulate oncology service margins by deepening backward integration into compounding pharmacy capabilities, capturing 503B certification revenue streams threatened by FDA bulk ingredient enforcement. Anchor multimodal protocol loyalty through subscription wellness plan bundling, preempting price-transparent insurance marketplaces from commoditizing standalone chemotherapy administration.
For New Entrants and Emerging Players: Geographic underpenetration in the Intermountain West and Upper Midwest presents white-space opportunity for mobile stereotactic radiosurgery deployment, extending advanced treatment access without fixed-installation capital. Target telemedicine-enabled case management for rural practices in Texas and Florida, leveraging relaxed interstate consultation rules to capture referral revenue from primary care veterinarians lacking oncology specialization.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mobile radiation service providers as truck-mounted linear accelerator manufacturing achieves scale economies. Acquisition targets should demonstrate established pet insurance contracts with standardized coding alignment, as reimbursement friction determines cash conversion cycles across the analysis window. Monitor FDA Center for Veterinary Medicine pilot program expansion as inflection indicator for biologics development timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Radiation Service Expansion | Truck-mounted linear accelerators virtualize fixed-installation infrastructure for secondary market access. |
| Biologics Pipeline Diversification | FDA MUMS pathway flexibility accelerates conditional approvals for feline lymphoma indications. |
| Telemedicine Platform Integration | Remote case management captures rural referral volume under Texas and Florida regulatory frameworks. |
| Compounding Pharmacy Certification | 503B facility investment responds to FDA bulk ingredient sourcing scrutiny and elevates compliance barriers. |
| Pet Insurance Coding Alignment | Standardized reimbursement categories reduce claims friction and accelerate treatment authorization cycles. |
Research Approach
Desk research of FDA Center for Veterinary Medicine approval databases, USDA biologics licensing records, and pet insurance claims datasets preceded structured interviews with veterinary oncologists, specialty hospital operations directors, pharmaceutical regulatory affairs leads, and 503B compounding pharmacy managers. Primary fieldwork combined with secondary validation against state veterinary medical board enforcement actions and OSHA cytotoxic handling inspection records. Bottom-up procedure volume estimates triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Assumptions regarding pet insurance penetration trajectories and FDA pilot program expansion timelines were held fixed across baseline scenarios, with alternative cases testing accelerated biologics approval and telemedicine regulatory relaxation. Segmentation modeling incorporated treatment modality, animal species, disease histology, and regional insurance density dimensions. CAGRs derived from logistic diffusion curves fitted to historical procedure adoption patterns, with veterinary oncology-specific inputs including anesthesia mortality risk adjustments and species-specific metabolism dosing factors.
Practitioners should monitor isotope reactor maintenance schedules and state telemedicine rulemaking for early signals of supply constraint or service delivery model disruption. Forecasts reflect documented assumptions; macroeconomic recession impacting pet owner discretionary spending, regulatory restriction on compounded chemotherapy, or breakthrough immunotherapy efficacy data would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
France Radiation Oncology Market
Oncology
Cancer Supportive Care Products Market
Oncology
Radiation Therapy Software Market
Oncology
Sterile Oncology Injectable Market
Oncology
America Cancer Immunotherapy Market
Oncology
AI in Oncology Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Angiosarcomas Treatment Market
Oncology
Particle Therapy Systems Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Tumor Embolization Market
Oncology
Global Veterinary Oncology Market
Oncology
Osteosarcoma Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Asia-Pacific Cancer Biomarkers Market