
 Radiation Therapy Software Market | 2026-2036
Radiation Therapy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Therapy Software Market Outlook
Subscription-based financing and software-as-a-service leasing is fragmenting capital barriers for smaller oncology clinics that previously could not afford enterprise treatment planning licenses. Varian Medical Systems leverages its installed base of linear accelerators to bundle planning software with hardware service contracts. Elekta anchors its competitiveness through deep integration of its Monaco planning system with proprietary delivery hardware across European and Asian hospital networks.
Radiation therapy software encompasses computational platforms that calculate dose distributions, optimize beam angles, and manage patient treatment workflows using algorithms ranging from pencil-beam convolution to Monte Carlo simulations. Treatment Planning Systems command the largest revenue share due to their complexity and regulatory certification requirements, while Machine Learning-enabled modules represent the fastest-expanding technology segment as vendors train models on institutional imaging archives. Cloud-Based deployment is gaining traction among mid-sized clinics seeking to avoid on-premises IT infrastructure costs, though On-Premises installations persist at major cancer centers with stringent data sovereignty policies.
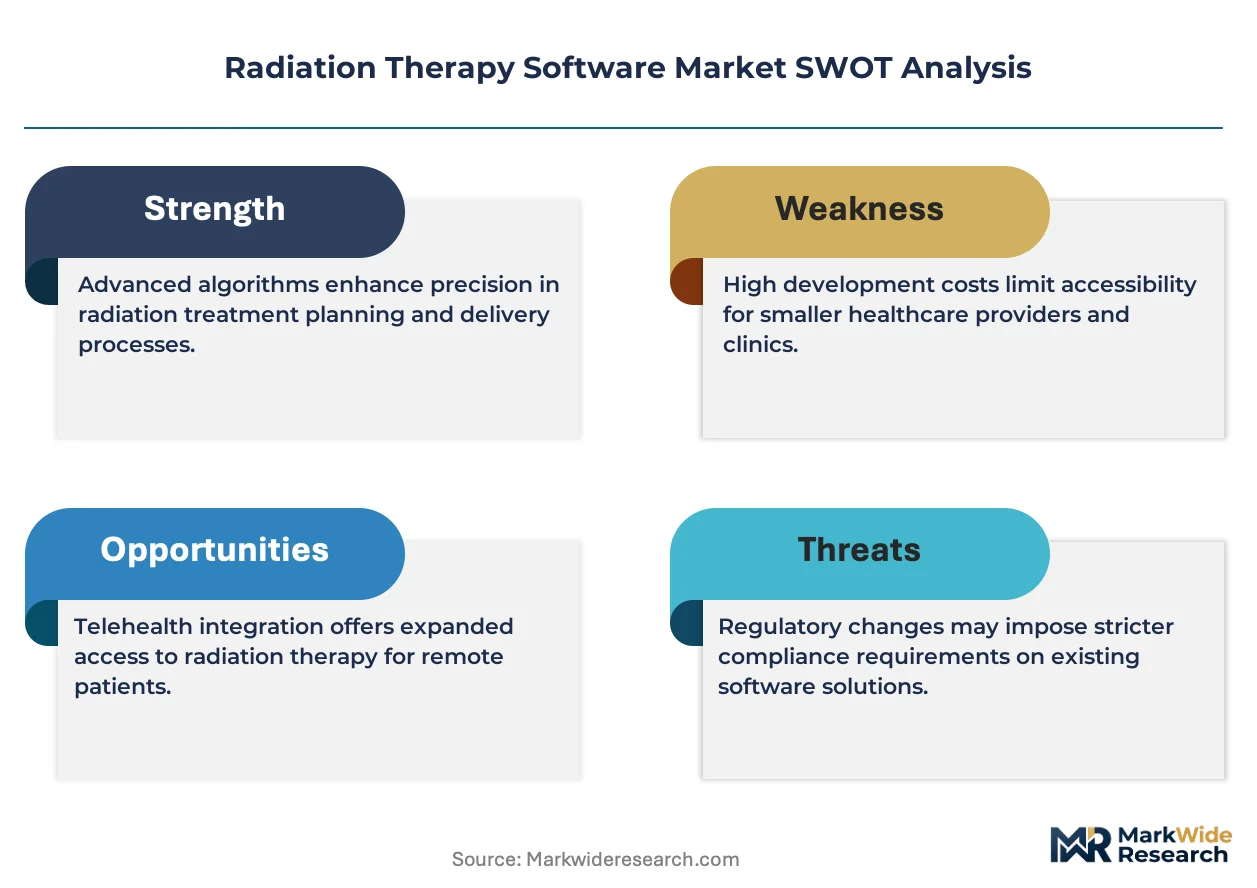
FDA 510(k) premarket notification requirements govern software modifications that affect dose calculation accuracy in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for algorithm-based planning tools sold under CE marking. HIPAA and GDPR compliance frameworks shape how patient imaging data traverses Cloud-Based platforms across transatlantic deployments. Stakeholders must weigh the pace of algorithmic innovation against the lag of multi-jurisdictional regulatory validation cycles.
Market Dynamics
AI-assisted contouring tools are compressing treatment planning timelines at academic medical centers, forcing incumbent vendors to restructure software licensing models around recurring revenue streams rather than perpetual licenses.
Growth Catalysts
- Medicare reimbursement policies:US Centers for Medicare & Medicaid Services incentivize adoption of advanced radiotherapy modalities through differential reimbursement rates for VMAT and SBRT procedures.
- Cloud-based deployment architectures:Mid-sized oncology clinics in Texas and Florida are migrating treatment planning systems to hosted environments to eliminate on-premises IT infrastructure capital expenditure.
- EU Medical Device Regulation harmonization:Stricter clinical evidence standards for algorithm-based planning tools are creating competitive moats for vendors with established quality management systems.
Market Restraints
- Data sovereignty compliance costs:German and French cancer centers face duplicated infrastructure expenditure to satisfy GDPR requirements for cross-border patient imaging transfers.
- Specialized medical physics talent scarcity:Dose calculation algorithm validation requires credentialed professionals whose training pipelines produce insufficient annual graduates.
- Legacy hardware lock-in:Linear accelerator replacement cycles extending beyond fifteen years constrain software upgrade revenue at installed-base accounts.
Strategic Opportunities
- India's underserved tier-2 cities:Telemedicine-enabled teleradiotherapy planning hubs can serve distributed cancer centers lacking on-site physics expertise.
- Adaptive therapy workflows:Integration of daily CBCT imaging with automated plan adaptation creates new software subscription tiers for high-volume proton centers.
- Japan's aging demographics:METI-supported hospital digitization subsidies accelerate replacement of film-based verification systems with electronic portal imaging.
Industry Challenges
- 510(k) clearance timeline variability:FDA review cycles for machine learning-based dose calculation modules extend unpredictably when predicate device equivalence is contested.
- Interoperability with legacy oncology information systems:HL7 FHIR implementation gaps force expensive custom interface development at each deployment site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Therapy Software Market |
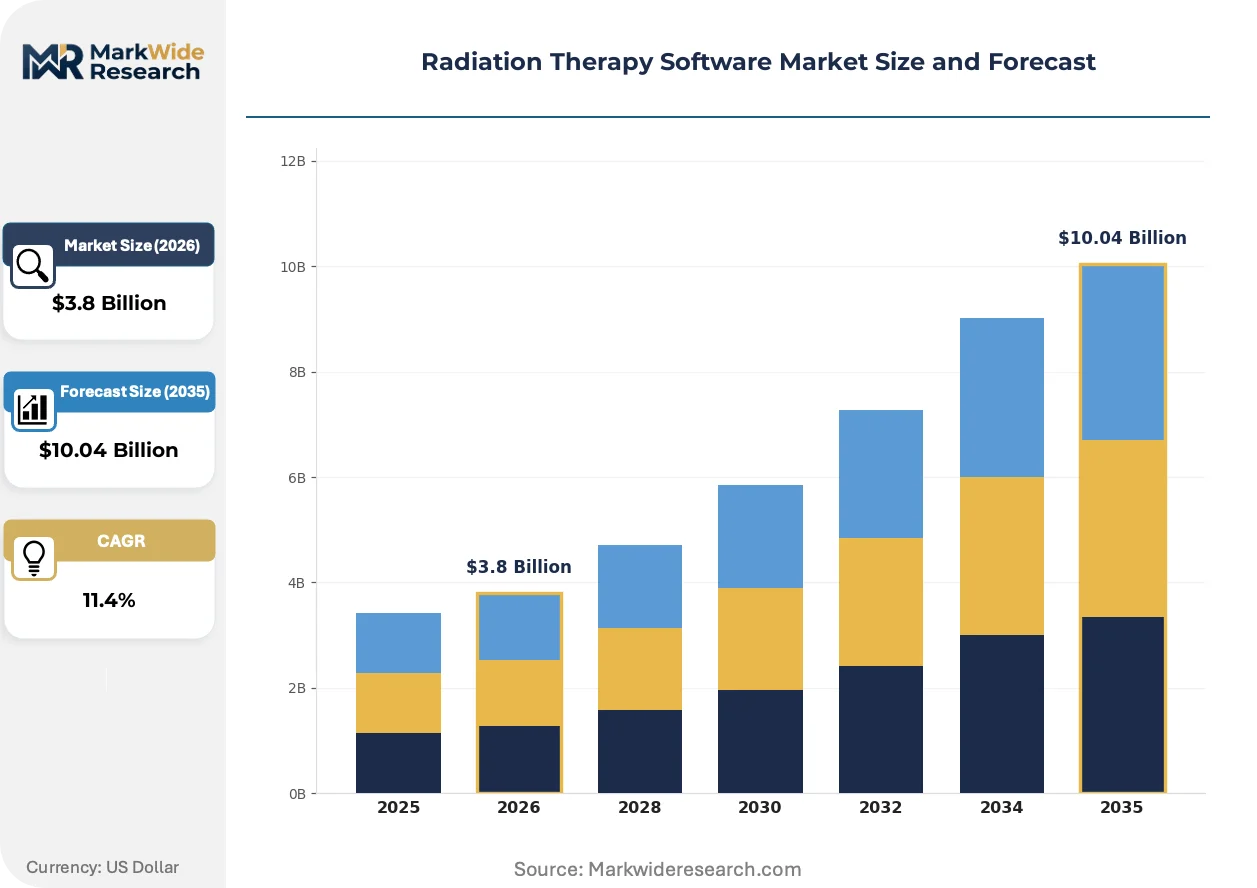
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treatment Planning Systems, Patient Management Systems, Analytics Software, Workflow Automation Tools End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Image Processing, Machine Learning, Monte Carlo Simulations, Cloud Computing Deployment: On-Premises, Cloud-Based, Hybrid, Web-Based |
| Companies Covered | Varian Medical Systems, Elekta, RaySearch Laboratories, Brainlab AG, Siemens Healthineers, Koninklijke Philips, Accuray Incorporated, MIM Software, DOSIsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Therapy Software Market Strategic Shifts
Algorithmic automation is penetrating every layer of radiation therapy workflow, from contour generation through plan quality assurance, while regulatory frameworks scramble to keep pace with validation requirements for continuously learning systems.
Monte Carlo dose calculation engines are rendering obsolete pencil-beam convolution methods for electron and proton transport modeling. Community cancer centers in California and Arizona are deploying GPU-accelerated Monte Carlo implementations to match academic center plan quality without physics staff expansion. This capability compression is collapsing the historical performance gap between high-volume and mid-tier treatment planning operations.
The EU AI Act's risk classification system imposes conformity assessment obligations on software performing automated contouring of organs-at-risk. Vendors must maintain post-market surveillance systems and algorithm change control protocols that exceed MDR requirements alone. European hospital procurement committees now demand AI Act compliance documentation alongside traditional CE marking certificates.
Subscription financing for treatment planning licenses is displacing capital purchase models at independent radiation oncology practices. Equipment finance companies in the United States are structuring software-as-a-service leases with bundled hardware maintenance, transferring technology obsolescence risk from clinic balance sheets to vendor retained ownership. This shift concentrates most visibly in the southeastern states where private equity-backed practice consolidation accelerates standardization decisions.
Radiation Therapy Software Market Segmentation
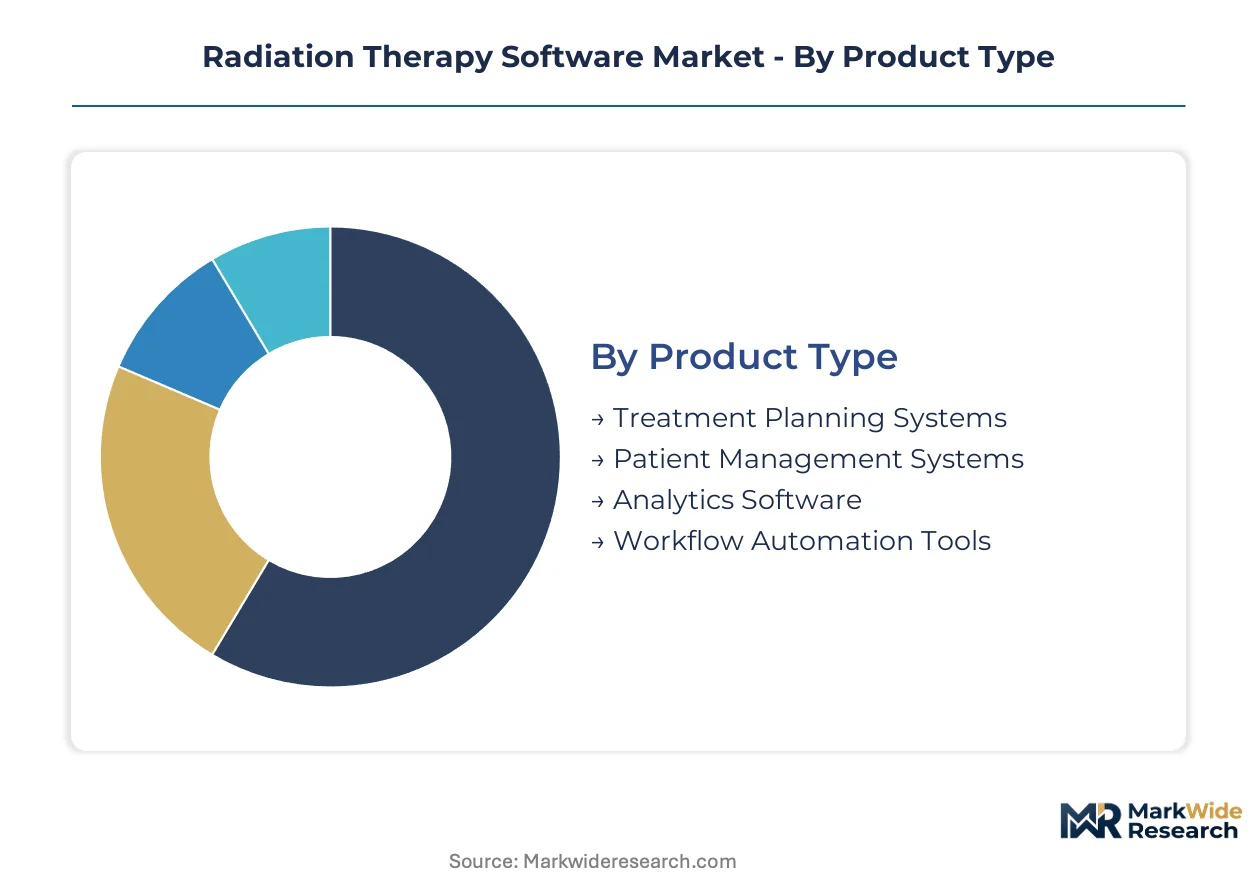
Radiation therapy software vendors structure product portfolios around distinct clinical workflows, from dose calculation engines to patient scheduling interfaces. Segmentation reveals how procurement decisions split between capital-intensive treatment planning infrastructure and recurring SaaS subscriptions for workflow optimization.
Product Type:
Clinical workflow demands span from high-stakes dose calculation to administrative patient tracking, creating divergent margin profiles across software categories.
- Treatment Planning Systems:These platforms execute dose distribution algorithms and beam angle optimization using pencil-beam convolution or Monte Carlo methods. Academic medical centers in the United States prioritize FDA 510(k)-cleared systems for VMAT and SBRT reimbursement eligibility. Established volume favors Treatment Planning Systems; emerging adoption favors Workflow Automation Tools.
- Patient Management Systems:Scheduling, documentation, and billing modules integrate with oncology information systems through HL7 FHIR protocols. Community cancer centers in Texas and Florida deploy these to coordinate multi-fraction treatment courses across dispersed sites.
- Analytics Software:Outcome tracking and plan quality dashboards aggregate institutional data for protocol refinement. German cancer centers leverage these for GDPR-compliant retrospective studies on toxicity profiles.
- Workflow Automation Tools:Automated contouring and plan quality assurance compress physics staff time per patient. AI-assisted modules are gaining traction fastest among mid-sized clinics facing medical physics talent scarcity.
Capital purchase concentration persists in Treatment Planning Systems; subscription migration accelerates in Workflow Automation Tools.
End User:
Procurement authority and reimbursement structure vary sharply across institutional settings, shaping software packaging and pricing architecture.
- Hospitals:Integrated delivery networks command enterprise licenses spanning radiation oncology, medical oncology, and surgical departments. Major cancer centers in California maintain on-premises infrastructure for data sovereignty compliance.
- Ambulatory Surgical Centers:Freestanding radiation facilities prioritize cloud-based deployment to minimize IT overhead. Medicare reimbursement differentials for advanced modalities drive software upgrade decisions at these sites.
- Clinics:Independent practices in the southeastern United States adopt SaaS financing models through equipment lease bundling. Private equity-backed consolidation standardizes platform choices across regional networks.
- Research Institutions:Protocol development and clinical trial execution demand customizable APIs and algorithm transparency. NIH-funded centers require audit trails for investigational device exemptions.
Revenue concentration sits with Hospitals; steepest expansion trajectory belongs to Ambulatory Surgical Centers.
Technology:
Algorithmic sophistication determines competitive differentiation, with legacy methods yielding to GPU-accelerated and machine-learning approaches.
- Image Processing:CT, MRI, and PET fusion engines enable multi-modality contouring for complex anatomical sites. European installations under EU AI Act risk classification face heightened conformity assessment for automated segmentation.
- Machine Learning:Deep learning models trained on institutional imaging archives accelerate organ-at-risk delineation. FDA review cycles for these modules extend unpredictably when predicate device equivalence is contested.
- Monte Carlo Simulations:Stochastic dose calculation methods supersede analytical approximations for electron and proton transport. GPU implementations at Arizona community centers match academic plan quality without physics staff expansion.
- Cloud Computing:Hosted infrastructure eliminates capital expenditure for mid-tier clinics while introducing HIPAA and GDPR compliance complexity for transatlantic deployments.
Proven accuracy anchors Monte Carlo Simulations; capability compression favors Machine Learning.
Deployment:
Infrastructure ownership models fragment between retained control and vendor-managed environments, with hybrid architectures emerging as compromise.
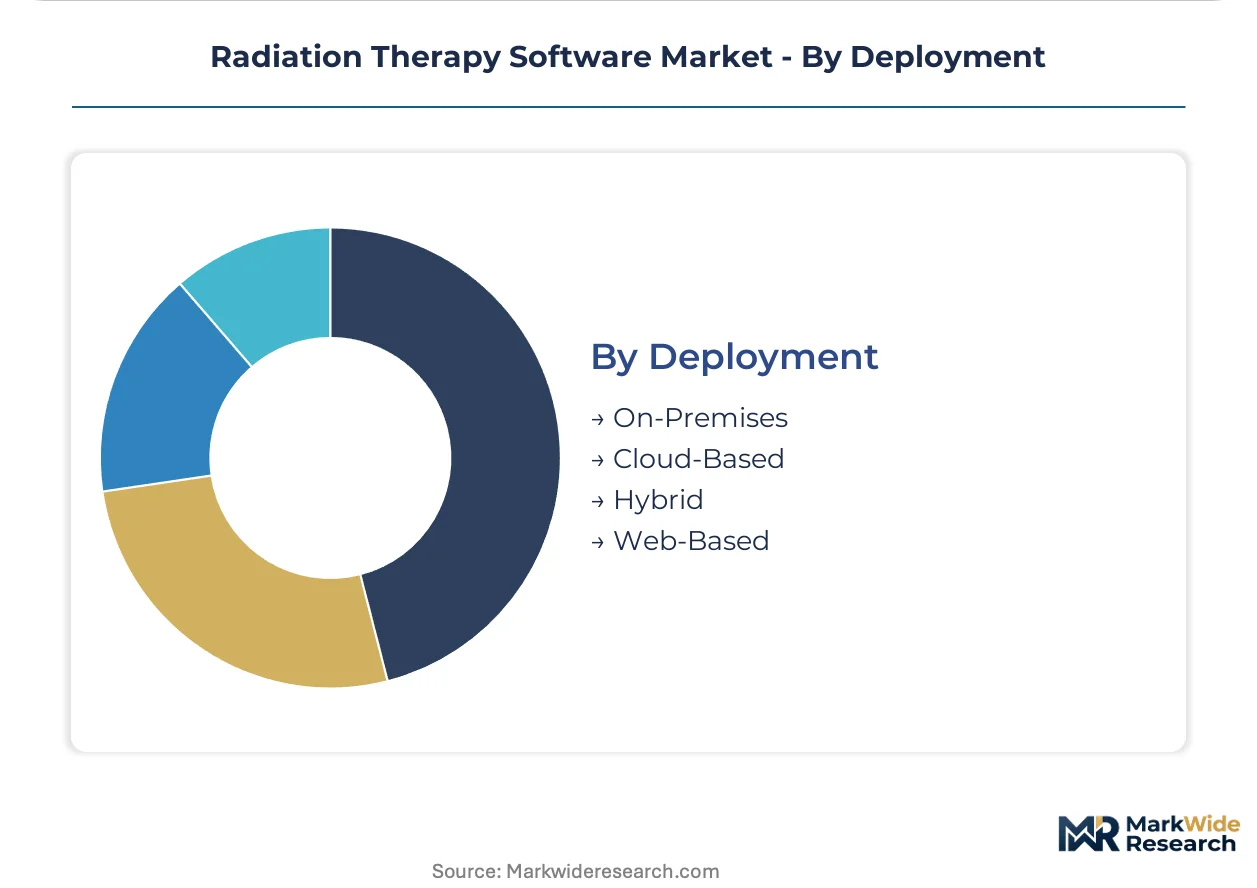
- On-Premises:Local server installations satisfy stringent data sovereignty policies at major cancer centers. German and French institutions maintain duplicated infrastructure for GDPR-compliant cross-border imaging transfers.
- Cloud-Based:Vendor-hosted environments transfer technology obsolescence risk from clinic balance sheets to software providers. Mid-sized oncology clinics in Florida migrate here to eliminate IT capital expenditure.
- Hybrid:Sensitive dose calculation executes locally while administrative functions shift to hosted platforms. This architecture addresses both regulatory scrutiny and cost pressure simultaneously.
- Web-Based:Browser-accessible interfaces enable teleradiotherapy planning for underserved tier-2 cities in India lacking on-site physics expertise.
Legacy dominance persists in On-Premises; flexibility premiums accrue to Hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement differentials for advanced radiotherapy modalities position the United States as the dominant demand center, while regulatory harmonization efforts across the European Union and targeted digitization subsidies in Asia reshape procurement timelines elsewhere.
United States
The Centers for Medicare & Medicaid Services incentivize VMAT and SBRT adoption through differential reimbursement rates, compressing upgrade cycles at community cancer centers. HIPAA compliance frameworks govern cross-state patient imaging transfers, creating infrastructure complexity for multi-site networks. Texas and Florida oncology clusters migrate fastest to cloud-hosted planning environments to eliminate capital expenditure.
Germany
German cancer centers face duplicated infrastructure expenditure to satisfy GDPR requirements for cross-border patient imaging transfers, slowing pan-European network formation. The EU AI Act's risk classification system imposes additional conformity assessment obligations on automated contouring software. Bavarian university hospitals anchor algorithm validation research, producing credentialed medical physics graduates for continental distribution.
Japan
METI-supported hospital digitization subsidies accelerate replacement of film-based verification systems with electronic portal imaging at regional cancer centers. The PMDA maintains stringent clinical evidence standards for machine learning-based planning modules, extending premarket review timelines. Kanto region proton therapy centers pioneer adaptive workflow integration between daily CBCT imaging and automated plan adjustment.
India
Tier-2 cities lack on-site physics expertise, creating structural demand for teleradiotherapy planning hubs connected through telemedicine infrastructure. The CDSCO regulates software imports under medical device classification rules, though enforcement capacity varies by state. Maharashtra and Karnataka urban cancer centers concentrate purchasing authority for multi-site network procurement.
United Kingdom
NHS England's specialized commissioning frameworks concentrate advanced radiotherapy capacity at designated cancer centers, standardizing software procurement across regional networks. MHRA post-Brexit regulatory divergence from EU MDR creates dual compliance obligations for vendors serving both markets. London and Manchester academic medical centers anchor AI-assisted contouring pilot programs with institutional imaging archive access.
Radiation Therapy Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct value capture positions. The market structure consolidates around hardware-integrated software ecosystems and independent planning specialists, with tiered competitive intensity between enterprise licenses and subscription SaaS offerings. Three archetypes dominate: linear accelerator vendors bundling planning software with service contracts, standalone algorithm developers licensing to multiple hardware platforms, and cloud-native workflow automation specialists. M&A activity concentrates on AI contouring capabilities, while strategic partnerships bridge interoperability gaps with legacy oncology information systems.
Among hardware-integrated ecosystem players, Varian Medical Systems and Elekta occupy positions defined by captive installed bases of linear accelerators. RaySearch Laboratories exemplifies the independent planning specialist archetype, developing algorithm platforms deployable across heterogeneous hardware environments. These three anchors illustrate how competitive positioning fragments between vertical integration strategies and horizontal software licensing models.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta |
| RaySearch Laboratories |
| Brainlab AG |
| Siemens Healthineers |
| Koninklijke Philips |
| Accuray Incorporated |
| MIM Software |
| DOSIsoft |
| Others |
Value Chain & Pricing Dynamics
Transatlantic data center corridors linking Frankfurt to Virginia carry escalating bandwidth costs that compress margins for cloud-native radiation therapy software vendors, concentrating pricing power among incumbents with captive hardware-service bundling while forcing mid-tier SaaS providers toward three-tier certification-grade differentiation.
Pricing Analysis
Certification level creates the primary spread between FDA 510(k)-cleared enterprise licenses and uncertified workflow modules. Three-tier pricing structure across premium, standard, and economy levels anchors on regulatory validation depth, with after-sales physics support bundling commanding additional premiums. Cost compression in the standard tier is intensifying because GPU-accelerated Monte Carlo implementations democratize academic-grade dose calculation. Ambulatory surgical centers exhibit highest price sensitivity; major cancer centers with research mandates show lowest.
Supply Chain Analysis
Contract manufacturing for radiation therapy software concentrates among specialized medical device EMS providers in Germany, Ireland, and Singapore. Algorithm development draws from NVIDIA GPU clusters, institutional imaging archives, and credentialed medical physics labor pools. Single-source vulnerability in Monte Carlo simulation licensing from European academic institutions creates concentration risk. Distribution runs through direct enterprise sales teams for hospital networks and equipment finance intermediaries for independent clinic SaaS leasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiation therapy software market functions as a talent-scarcity arena where credentialed medical physicists capable of algorithm validation represent the constraining asset, creating asymmetric returns for vendors who capture this expertise through training pipelines or acquisition.
For Market Incumbents: Build regulatory data moats through post-market surveillance systems that exceed EU AI Act requirements. Capture physics talent scarcity by underwriting university hospital training fellowships in exchange for exclusive recruitment pipelines. FDA 510(k) clearance velocity serves as the critical defensive lever against cloud-native entrants. For New Entrants and Emerging Players: Tier-2 Indian cities lacking on-site physics expertise represent the most penetrable entry point for teleradiotherapy planning hubs. Mid-sized oncology clinics in Florida and Texas facing IT capital constraints offer SaaS-first conversion opportunities. Go-to-market through equipment finance bundling transfers technology obsolescence risk from clinic balance sheets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-assisted contouring specialists with institutional imaging archive access and proven FDA submission track records. Long-term viability hinges on adaptive therapy workflow integration capabilities. The signal to watch is Medicare reimbursement expansion for automated plan adaptation procedures.| Strategic Initiative | Industry Significance |
|---|---|
| AI Contouring Module Launch | FDA 510(k) clearance for organ-at-risk segmentation compresses treatment planning timelines at academic medical centers. |
| Cloud Platform Integration | Hybrid deployment architectures address HIPAA compliance while eliminating on-premises IT infrastructure capital expenditure. |
| Hospital System Partnership | Integrated delivery network enterprise licenses span radiation oncology, medical oncology, and surgical departments. |
| Acquisition of Physics Specialist | Credentialed medical physics talent scarcity constrains algorithm validation capacity across vendor R&D pipelines. |
| Geographic Expansion | METI-supported digitization subsidies in Japan accelerate replacement of film-based verification systems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiation oncology department heads, medical physics directors, hospital procurement committee members, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EU MDR conformity assessment records, and hospital capital expenditure disclosures. Bottom-up installation base modeling and top-down reimbursement flow analysis were triangulated against vendor-reported subscription metrics.
Calibration against historical adoption curves for VMAT and SBRT modalities anchored growth assumptions across the analysis window. Segmentation dimensions modeled include product type, end-user institution category, deployment architecture, algorithmic technology tier, and regional regulatory cluster. CAGRs were derived from installed base expansion rates multiplied by average revenue per account trajectories, with Monte Carlo simulation adoption curves and AI-assisted contouring penetration schedules serving as key forecast inputs.
Practitioners should monitor FDA 510(k) review timeline variability and EU AI Act conformity assessment backlog for early signals of competitive positioning shifts. Forecasts embed assumptions regarding Medicare reimbursement stability and medical physics graduate pipeline capacity. Quarterly review of hospital capital expenditure commitments and cloud migration announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Interventional Oncology Ablation Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
Gynecological Cancers Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
US Veterinary Oncology Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Global Cancer Profiling Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Sterile Oncology Injectable Market