
 Global Veterinary Oncology Market | 2026-2036
Global Veterinary Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Oncology Market Foresight
Subscription-based maintenance contracts for linear accelerators and imaging systems is pivoting how radiation equipment vendors capture recurring revenue. Zoetis leverages its pharmaceutical portfolio to anchor oncology drug distribution across North American veterinary hospitals. Boehringer Ingelheim International GmbH competes through in-house production of biologic therapies for companion animals.
Veterinary oncology encompasses the diagnosis, treatment, and management of neoplastic diseases in non-human animals, employing chemotherapeutic agents with species-specific dosing protocols, radiation therapy calibrated to anatomical scale, and immunomodulatory biologics targeting tumor microenvironments. Canine tumors dominate application demand due to higher pet dog populations and owner willingness to pursue multi-modal therapy. Diagnostic devices represent a fast-growing segment as liquid biopsy platforms and point-of-care imaging expand access to early cancer detection in veterinary settings.
The FDA Center for Veterinary Medicine governs chemotherapy agent approvals in the United States, while the EU Veterinary Medicines Regulation harmonizes oncology drug authorization across member states, with EMA scientific committees evaluating novel immunotherapy submissions. Japan's Ministry of Agriculture, Forestry and Fisheries oversees animal pharmaceutical safety through PMDA-aligned review pathways. Stakeholders must monitor regulatory divergence between jurisdictions as gene therapy and CAR-T approaches enter veterinary development pipelines.
Market Dynamics
The veterinary oncology sector is experiencing a fundamental restructuring as specialty referral networks consolidate diagnostic and therapeutic capabilities under single ownership, compressing the traditional multi-veterinarian care pathway into streamlined service hubs.
Growth Catalysts
- Companion animal insurance penetration:Pet insurance coverage in the United States, Germany, and Japan now reimburses advanced oncology protocols, removing cost barriers that previously limited treatment access for mid-market pet owners.
- EMA harmonization under EU Veterinary Medicines Regulation:Centralized oncology drug authorization across European member states accelerates commercial launch timelines and reduces regulatory duplication costs for biologic therapy developers.
- Liquid biopsy platform maturation:Point-of-care genomic profiling in veterinary clinics enables same-day treatment stratification, collapsing the diagnostic-to-therapy interval from weeks to hours.
Market Restraints
- Linear accelerator supply concentration:Radiation therapy hardware production concentrates among three dominant equipment vendors, creating procurement bottlenecks and extended installation lead times for expanding specialty clinics.
- Isotope sourcing fragility:Cyclotron-produced radioisotopes for veterinary theranostics depend on aging North American and European production facilities with limited geographic redundancy.
- Species-specific pharmacokinetic validation requirements:FDA Center for Veterinary Medicine mandates separate efficacy trials for each target species, multiplying development costs for multi-species oncology indications.
Strategic Opportunities
- Brazilian specialty clinic expansion:São Paulo and Rio de Janeiro veterinary referral centers are adopting North American-style oncology service lines ahead of local regulatory framework maturation.
- CAR-T manufacturing standardization:Autologous cell therapy production protocols developed for human medicine are being adapted to canine lymphoma with reduced cleanroom infrastructure requirements.
- Telemedicine-integrated second opinion networks:Remote pathology review and treatment planning services connect rural veterinarians to board-certified oncologists, extending specialty reach without physical infrastructure investment.
Industry Challenges
- Radiation safety certification scarcity:Board-certified veterinary radiation oncologists require dual credentialing in radiation physics and clinical oncology, constraining clinic expansion in underserved metropolitan markets.
- Chemotherapy compounding compliance complexity:USP 800 hazardous drug handling standards impose facility renovation costs on general practices attempting to administer systemic oncology agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Oncology Market |
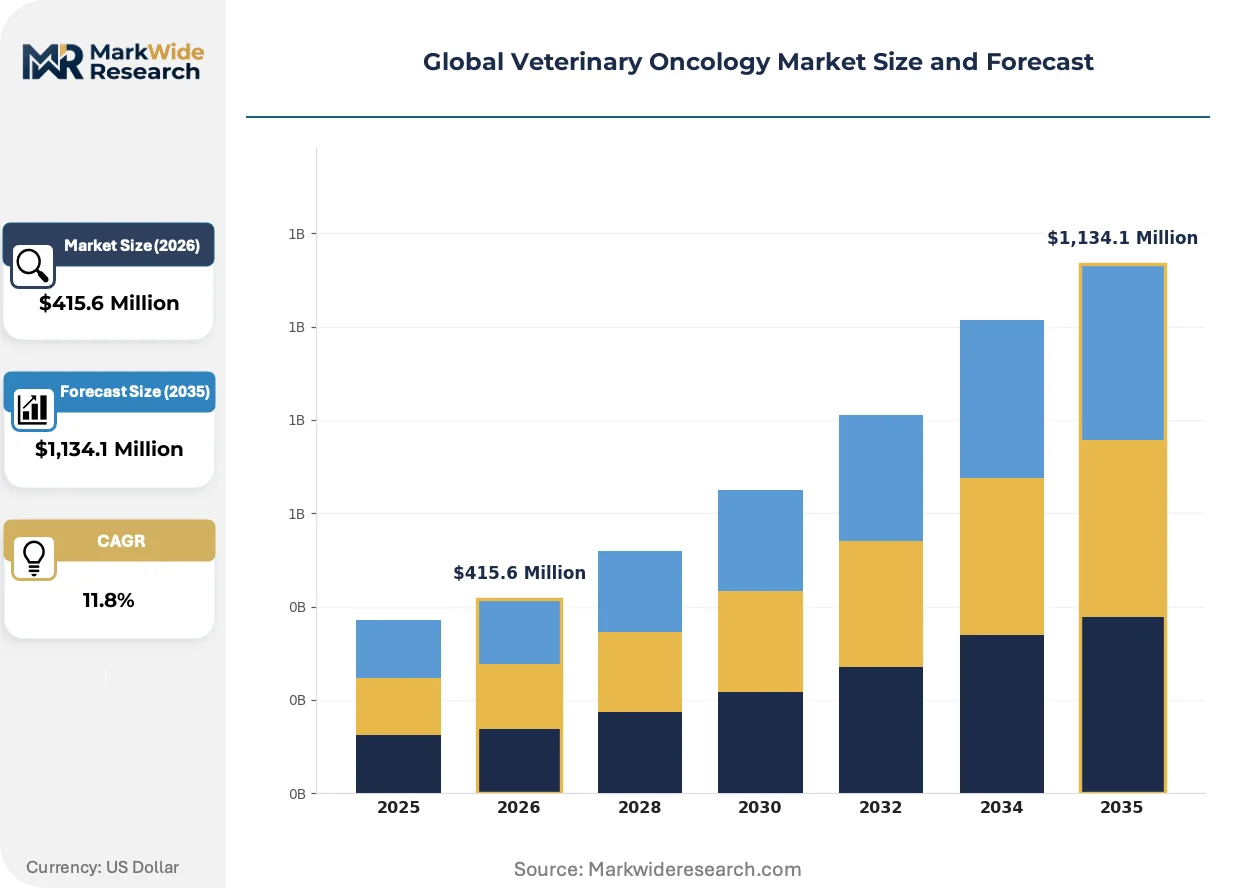
| Market Size in 2026 | $415.6 Million |
| Market Size in 2035 | $1,134.1 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Radiation Equipment, Immunotherapy Drugs, Surgical Instruments, Diagnostic Devices Application: Canine Tumors, Feline Cancers, Equine Oncology, Exotic Animal Neoplasms, Avian Tumors End User: Veterinary Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutions, Mobile Veterinary Services Treatment Method: Cytotoxic Therapy, Targeted Therapy, Immunomodulation, Radiotherapy, Palliative Care |
| Companies Covered | Zoetis, Elanco, Boehringer Ingelheim International GmbH, IDEXX Laboratories, Inc., Merck Animal Health, Siemens Healthineers (Varian Medical Systems), Accuray Incorporated, PetCure Oncology, VolitionRx Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Oncology Market Shifts & Advancements
Technology convergence between human and veterinary medicine is collapsing development timelines, with diagnostic platforms and therapeutic modalities crossing species boundaries faster than regulatory frameworks can adapt.
Portable imaging systems incorporating cone-beam CT and fluoroscopic guidance are modularizing radiation therapy delivery, enabling same-day simulation and treatment initiation. Specialty veterinary clinics in the United States and Japan are deploying these systems in retrofitted surgical suites rather than purpose-built bunkers. This hardware miniaturization is modularizing the capital barrier to radiation service entry, allowing mid-tier referral hospitals to compete with academic centers.
EMA scientific committees are tightening immunotherapy safety thresholds through enhanced pharmacovigilance requirements for novel biologic submissions. Veterinary pharmaceutical developers must now submit real-world evidence protocols alongside traditional efficacy trials. European oncology drug sponsors are responding by embedding post-market surveillance systems into product launch strategies, anticipating regulator data demands.
Subscription-based equipment maintenance and software licensing is displacing traditional capital purchase models for diagnostic imaging and treatment planning systems. Veterinary hospital groups in Germany and Japan are consolidating vendor relationships through enterprise service agreements that bundle hardware, training, and predictive analytics. This procurement transformation concentrates purchasing power among multi-site operators while marginalizing independent specialty practices.
Global Veterinary Oncology Market Segmentation
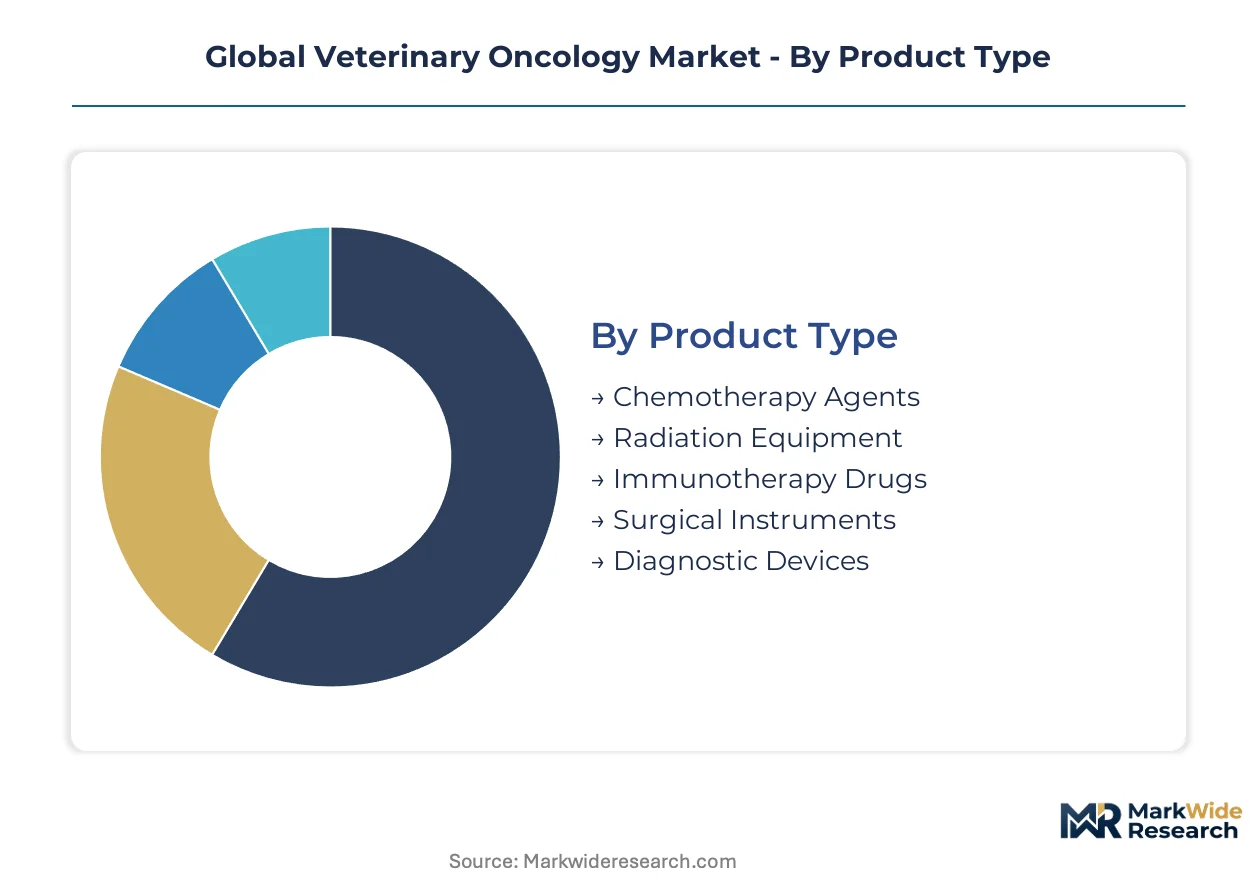
Veterinary oncology segmentation reflects divergent capital intensity across treatment modalities. Product categories span disposable pharmaceuticals through million-dollar radiation installations, while application demand clusters around species-specific tumor biology and owner willingness-to-pay.
Product Type:
Chemotherapy agents operate as standalone consumables requiring minimal infrastructure, whereas radiation equipment embeds into purpose-built clinical suites with decade-long depreciation cycles.
- Chemotherapy Agents:Cytotoxic and antimetabolite formulations calibrated to species-specific pharmacokinetics dominate pharmaceutical revenue. Demand concentrates in United States specialty clinics where pet insurance reimbursement protocols remove cost barriers for alkylating agent regimens.
- Radiation Equipment:Linear accelerators and cobalt-60 units deliver fractionated dose protocols with millimeter precision. Procurement bottlenecks persist in Germany and Japan as three dominant equipment vendors control cyclotron production capacity.
- Immunotherapy Drugs:Checkpoint inhibitors and monoclonal antibodies targeting canine lymphoma microenvironments.
- Surgical Instruments:Electrosurgical units and tumor margin assessment tools for excisional procedures.
- Diagnostic Devices:Liquid biopsy platforms and point-of-care imaging systems enabling same-day staging.
Volume placements concentrate in Chemotherapy Agents; the faster expansion belongs to Diagnostic Devices.
Application:
Species segmentation tracks tumor incidence rates against owner expenditure patterns, with companion animals commanding per-case economics that exceed production livestock by orders of magnitude.
- Canine Tumors:Mast cell neoplasms, lymphoma, and osteosarcoma drive multi-modal treatment protocols. United States and Japanese pet owners demonstrate highest willingness-to-pay for limb-sparing surgery combined with adjuvant chemotherapy.
- Feline Cancers:Injection-site sarcomas and gastrointestinal lymphoma predominate. German specialty clinics report expanding demand for feline-specific radiation planning protocols that accommodate smaller anatomical scale.
- Equine Oncology:Sarcoids and melanomas in performance horses.
- Exotic Animal Neoplasms:Reptile and small mammal tumors in zoological and private collections.
- Avian Tumors:Fibrosarcomas and renal carcinomas in companion birds.
Revenue concentration sits with Canine Tumors; Feline Cancers are climbing the fastest as diagnostic access improves.
End User:
Facility type determines service complexity and capital deployment, with referral networks consolidating capabilities that once dispersed across general practices.
- Veterinary Hospitals:Academic and tertiary centers housing comprehensive oncology departments with in-house radiation capability. Germany's university veterinary hospitals anchor regional referral networks.
- Specialty Clinics:Private referral practices focusing exclusively on oncology with board-certified diplomates. São Paulo and Rio de Janeiro centers are adopting North American service models ahead of regulatory maturation.
- Diagnostic Laboratories:External pathology and molecular testing services.
- Research Institutions:Comparative oncology trials bridging human and veterinary drug development.
- Mobile Veterinary Services:Ultrasound-guided biopsy and chemotherapy administration in home settings.
Patient volume aggregates at Veterinary Hospitals; Specialty Clinics show the steepest expansion trajectory as referral networks consolidate.
Treatment Method:
Therapeutic approach selection hinges on tumor stage, species metabolism, and facility capability matrices.
- Cytotoxic Therapy:Conventional chemotherapy with established efficacy protocols across lymphoma and carcinoma indications. FDA Center for Veterinary Medicine mandates species-specific safety trials that extend development timelines.
- Targeted Therapy:Tyrosine kinase inhibitors and receptor antagonists with reduced systemic toxicity. Japanese Ministry of Agriculture, Forestry and Fisheries review pathways align with PMDA pharmaceutical standards.
- Immunomodulation:Cytokine therapies and cancer vaccines.
- Radiotherapy:External beam and brachytherapy protocols.
- Palliative Care:Pain management and quality-of-life protocols for terminal cases.
Procedure volume concentrates in Cytotoxic Therapy; Targeted Therapy is gaining share fastest as biomarker stratification matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American veterinary oncology service density, hosting multiple specialty referral centers with in-house linear accelerator capacity. Regulatory frameworks and reimbursement structures diverge sharply across major markets, shaping where capital deploys fastest.
United States
Pet insurance penetration at specialty clinics now covers multi-modal cancer protocols, removing cost barriers for mid-market dog owners. The FDA Center for Veterinary Medicine mandates species-specific pharmacokinetic trials for chemotherapy approvals, extending development timelines. The Philadelphia-Baltimore corridor concentrates academic veterinary hospitals bridging comparative oncology research.
Germany
University veterinary hospitals in Leipzig and Munich anchor regional referral networks with comprehensive radiation capability. The EU Veterinary Medicines Regulation harmonizes oncology drug authorization across member states, accelerating commercial launch timelines. The Baden-Württemberg cluster houses precision imaging equipment vendors serving Central European specialty clinics.
Japan
Tokyo and Osaka metropolitan areas demonstrate highest per-case expenditure on canine limb-sparing surgery combined with adjuvant protocols. The Ministry of Agriculture, Forestry and Fisheries aligns animal pharmaceutical safety review with PMDA standards. Yokohama-based specialty clinics pioneer feline-specific radiation planning for smaller anatomical scale.
Brazil
São Paulo veterinary referral centers adopt North American-style oncology service lines ahead of local regulatory framework maturation. ANVISA oversees animal pharmaceutical registration with evolving guidelines for biologic therapies. The Rio de Janeiro corridor attracts investment in diagnostic imaging platforms for early cancer detection.
United Kingdom
London and Southeast England concentrate private equity-backed specialty clinic chains consolidating diagnostic and therapeutic capabilities. The Veterinary Medicines Directorate implements EU-legacy oncology drug standards with post-Brexit adaptation. The Cambridge-Oxford arc hosts comparative oncology research institutions bridging human and veterinary drug development.
Global Veterinary Oncology Market Competitive Landscape
Capital-heavy equipment manufacturers compete with asset-light pharmaceutical developers for veterinary oncology revenue pools. The market structures around three vendor tiers: diversified animal health conglomerates with integrated distribution, pure-play radiation hardware specialists with subscription service models, and emerging diagnostic platform developers with liquid biopsy technologies. Consolidation accelerates through multi-site hospital group acquisitions and cross-border equipment service agreements.
Among diversified animal health conglomerates, Zoetis and Elanco anchor the pharmaceutical-distribution tier with North American hospital network penetration. Boehringer Ingelheim International GmbH represents the European-integrated biologic therapy archetype with in-house manufacturing capabilities. These three entities exemplify contrasting geographic anchoring strategies—US-based portfolio breadth versus German-focused production depth—while competing for specialty clinic formulary placement.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Boehringer Ingelheim International GmbH |
| IDEXX Laboratories, Inc. |
| Merck Animal Health |
| Siemens Healthineers (Varian Medical Systems) |
| Accuray Incorporated |
| PetCure Oncology |
| VolitionRx Limited |
| Others |
Supply & Pricing Matrix
EMA pharmacovigilance mandates for novel biologic submissions gate qualified supply access and premium-tier pricing for veterinary immunotherapy developers, compressing margins for sponsors lacking embedded post-market surveillance infrastructure while rewarding European-integrated manufacturers with formulary placement leverage.
Pricing Analysis
Subscription-based maintenance contracts anchored to linear accelerator uptime metrics dominate radiation equipment pricing, with Siemens Healthineers and Accuray bundling predictive analytics and training into enterprise service agreements. Price differentiation rests on cleanroom certification tier and after-sales response guarantees, with academic medical centers in Germany and Japan demonstrating lowest price sensitivity due to research grant offsets. Cost compression in mid-tier diagnostic imaging stems from portable system commoditization, squeezing standalone hardware vendors without software recurring revenue. Independent specialty clinics in Brazil exhibit highest price sensitivity, deferring capital purchases until regulatory reimbursement frameworks mature.
Supply Chain Analysis
Domestic-content requirements under EU Veterinary Medicines Regulation and Japan's PMDA-aligned review pathways are reshaping sourcing strategies for biologic therapy developers, favoring in-house manufacturing investments over contract manufacturing organization reliance. Cyclotron-produced radioisotopes for veterinary theranostics concentrate production in aging North American and European facilities, with molybdenum-99 and iodine-131 supply anchored in Belgium, the Netherlands, and Canada. Single-source vulnerability pervades linear accelerator magnet and klystron component supply, with three dominant equipment vendors controlling global installation capacity. Distribution runs through consolidated multi-site hospital groups in Germany and Japan, marginalizing independent specialty practices without enterprise purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary oncology sector sits in a technology-transition phase as liquid biopsy platforms and portable imaging systems displace centralized laboratory referral pathways, collapsing diagnostic-to-therapy intervals from weeks to hours.
For Market Incumbents: Extend subscription service models into predictive maintenance and AI-assisted treatment planning, locking in multi-year enterprise agreements with expanding specialty clinic chains. Backward integration into cyclotron isotope production mitigates sourcing fragility threatening radiation therapy service continuity. Defend formulary position by embedding real-world evidence collection systems ahead of EMA pharmacovigilance tightening. For New Entrants and Emerging Players: Point-of-care genomic profiling platforms offer technology-first wedge into underserved metropolitan markets lacking board-certified radiation oncologists. Brazilian specialty clinics in São Paulo and Rio de Janeiro represent most penetrable geography, adopting North American service models ahead of ANVISA regulatory maturation. Partner with telemedicine-integrated second opinion networks to extend reach without physical infrastructure investment. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine approval of first canine CAR-T therapy is the leading indicator that manufacturing standardization protocols will unlock scalable autologous cell therapy platforms. Long-term viability favors vertically integrated biologic developers with in-house production capabilities spanning chemotherapy, immunotherapy, and diagnostic reagents. Watch for consolidation signals among German university veterinary hospitals anchoring regional referral networks.| Strategic Initiative | Industry Significance |
|---|---|
| CAR-T Manufacturing Standardization | Autologous cell therapy protocols adapted from human medicine reduce cleanroom infrastructure requirements for canine lymphoma. |
| Telemedicine-Integrated Second Opinion Networks | Remote pathology review connects rural veterinarians to board-certified oncologists, extending specialty reach without capital deployment. |
| Liquid Biopsy Platform Commercialization | Same-day genomic profiling collapses diagnostic-to-therapy intervals, enabling treatment stratification at point-of-care. |
| Enterprise Service Agreement Consolidation | Multi-site hospital groups in Germany and Japan bundle hardware, training, and predictive analytics, concentrating purchasing power. |
| Comparative Oncology Trial Expansion | Academic veterinary hospitals in the Philadelphia-Baltimore corridor bridge human and veterinary drug development pipelines. |
Research Methodology
Multi-period observation of FDA Center for Veterinary Medicine approval timelines, EMA scientific committee submission patterns, and specialty clinic capital expenditure cycles anchored the trend analysis, supplemented by interviews with veterinary pharmaceutical development executives, radiation oncology equipment procurement directors, and animal health insurance reimbursement specialists. Secondary validation drew from FDA Center for Veterinary Medicine filings, EMA centralized procedure databases, Japanese Ministry of Agriculture review pathway disclosures, and comparative oncology trial registries. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across geographic markets.
Segment-weighting approaches applied differential growth assumptions across chemotherapy agents, radiation equipment, immunotherapy drugs, and diagnostic devices, with species-specific tumor incidence rates and owner willingness-to-pay informing application-level projections. Treatment method segmentation incorporated cytotoxic therapy volume concentration against targeted therapy biomarker stratification trajectories. CAGRs derived from installed base expansion rates, reimbursement policy evolution, and regulatory approval velocity across the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence for gene therapy and CAR-T approaches, cyclotron facility closures disrupting isotope supply, and macroeconomic shocks affecting pet insurance penetration. Forecasts reflect documented assumptions regarding specialty clinic consolidation pace and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Cancer Profiling Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Throat Cancer Market
Oncology
Metastatic Cancer Drug Market
Oncology
Colorectal Cancer Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Cancer Supportive Care Products Market
Oncology
Hadron Therapy Market
Oncology
Liposarcoma Treatment Market
Oncology
North America Bone Metastasis Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Precision Oncology Market
Oncology
Asia-Pacific Proton Therapy Market