
 Cancer Supportive Care Products Market | 2026-2036
Cancer Supportive Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Supportive Care Products Market Analysis
The EU MDR is restructuring compliance requirements for cancer supportive care devices and combination products, forcing manufacturers to recertify legacy portfolios under stricter clinical evidence standards. Amgen Inc. leverages its biologics manufacturing scale to maintain supply continuity across European markets. Helsinn Healthcare SA specializes in anti-nausea formulations, anchoring its position through deep oncology channel relationships. Teva Pharmaceutical Industries Ltd. competes on generic injectable access, extending cost-efficient alternatives to hospital formularies.
Cancer supportive care products encompass pharmaceutical and nutritional interventions designed to mitigate chemotherapy-induced adverse effects, maintain patient functional status, and preserve treatment adherence through defined dosing regimens and delivery mechanisms. These products integrate active pharmaceutical ingredients with supportive excipients to address myelosuppression, mucositis, and cachexia across standardized oncology protocols. Pain management and anti-nausea agents dominate current revenue pools, reflecting entrenched hospital purchasing patterns and established reimbursement pathways. Nutritional supplements represent the fastest-expanding category, driven by rising home care utilization and patient-directed recovery protocols. The delivery mode dimension shows oral formulations commanding volume leadership while injectable routes capture premium pricing in acute care settings.
FDA, EMA, and WHO frameworks collectively govern oncology supportive care standards, with FDA bioequivalence requirements shaping generic substitution patterns and WHO essential medicines lists influencing procurement in emerging markets. These regulatory layers determine market access timelines, label expansion opportunities, and manufacturing quality benchmarks across jurisdictions. Stakeholders must monitor evolving MDR transition deadlines and biosimilar interchangeability designations to anticipate competitive displacement in core therapeutic categories.
Market Dynamics
The EU MDR's clinical evidence requirements are forcing manufacturers to rebuild legacy certification dossiers, compressing commercial timelines for combination products and reshaping competitive entry barriers across oncology supportive care.
Growth Catalysts
- Home infusion protocols:Hospital-at-home reimbursement expansion in Germany and France is pulling acute anti-nausea and pain management therapies into ambulatory settings, expanding addressable patient days.
- FDA bioequivalence pathways:Streamlined generic injectable approvals for supportive care agents are accelerating formulary access and price competition in US hospital procurement.
- WHO essential medicines designation:Listing of core antiemetics and analgesics is standardizing procurement budgets in emerging market oncology programs.
Market Restraints
- API supply concentration:China dominates active pharmaceutical ingredient manufacturing for generic ondansetron and granisetron, exposing formulators to single-source disruption risk.
- EMA MDR transition costs:Legacy device recertification under stricter clinical evidence standards is consuming 18-24 month regulatory bandwidth for combination delivery systems.
- Biosimilar interchangeability uncertainty:FDA's evolving substitution guidelines for supportive care biologics are freezing payer contract negotiations and formulary placement decisions.
Strategic Opportunities
- Oral film strip delivery:Mucoadhesive dissolvable formats for anti-nausea agents are opening pediatric and dysphagia patient segments previously served only by injectables.
- India's PLI scheme for pharmaceuticals:Production-linked incentives for critical care drugs are attracting contract manufacturing investment for export-oriented supportive care API and finished dose production.
- Japan's PMDA Sakigake designation:Expedited review pathways for novel supportive care mechanisms are incentivizing first-in-class development for chemotherapy-induced peripheral neuropathy.
Industry Challenges
- Qualified pharmacovigilance talent scarcity:MDR-mandated post-market surveillance for combination products requires specialized safety data science capabilities that outpace current workforce supply.
- Cold chain integrity for biologics:Temperature-controlled distribution of growth factor support agents demands capital-intensive last-mile infrastructure expansion into community oncology settings.
- Legacy ERP integration with track-and-trace:Serialization compliance for EU FMD and US DSCSA is forcing mid-tier manufacturers into disruptive supply chain IT overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Supportive Care Products Market |
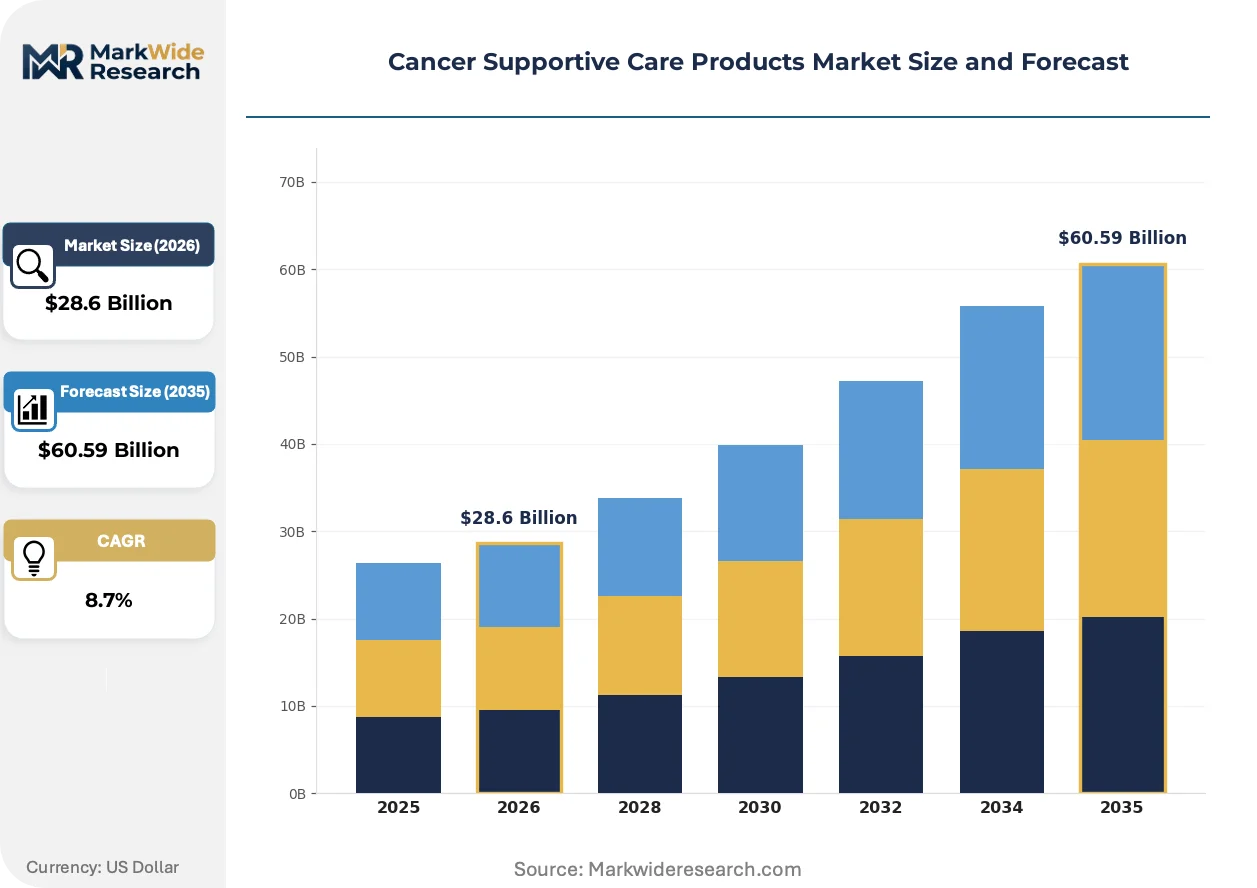
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Supplements, Pain Management, Anti-nausea Agents, Emotional Well-being Products Application: Chemotherapy Support, Radiation Therapy Aid, Palliative Care, Symptom Management End User: Hospitals, Home Care, Outpatient Clinics, Oncology Centers Delivery Mode: Oral, Injectable, Topical, Transdermal |
| Companies Covered | Amgen Inc., Johnson & Johnson, F. Hoffmann-La Roche Ltd., Novartis AG, Merck & Co. Inc., GSK plc, Teva Pharmaceutical Industries Ltd., Helsinn Healthcare SA, Heron Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Supportive Care Products Market Emerging Trajectories
Digital biomarker integration and patient-reported outcome capture are rewiring how supportive care efficacy is measured, shifting value demonstration from clinical endpoints to functional status preservation during chemotherapy cycles.
Subcutaneous auto-injector platforms for granulocyte colony-stimulating factors are modularizing administration workflows, enabling oncology practices to delegate delivery to home health nurses and reducing chair time in infusion centers. Community clinics in the United States are adopting these devices fastest, compressing the acute care revenue capture window for hospital outpatient departments.
EMA's tightened MDR clinical evidence requirements for combination drug-device products are extending development timelines for novel delivery mechanisms, forcing developers to front-load human factors studies and post-market surveillance commitments. Injectable anti-nausea therapies with integrated needle safety systems face the steepest compliance burden, with manufacturers rebuilding technical documentation for legacy portfolios originally cleared under withdrawn directives.
Home care agencies are capturing a growing share of supportive care product administration, displacing traditional hospital-based procurement relationships with direct-to-patient distribution models. This channel rotation is most pronounced in the United Kingdom and Netherlands, where integrated care boards are bundling supportive care into capitated oncology pathways and selecting logistics partners based on cold chain reliability metrics rather than historical hospital vendor status.
Cancer Supportive Care Products Market Segmentation
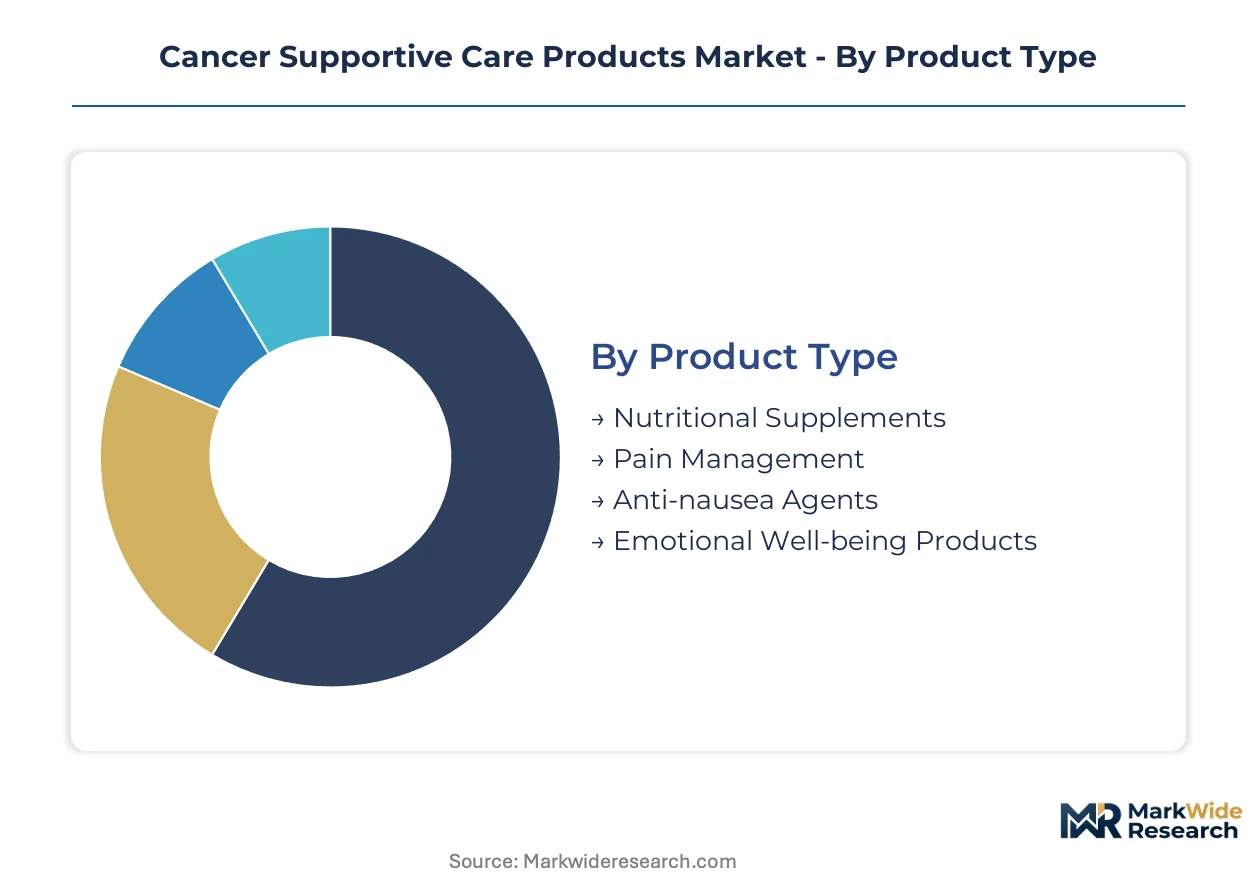
Segmentation in cancer supportive care reveals how procurement authority, reimbursement pathways, and patient acuity reshape product form and channel strategy. Manufacturers must align formulation development with the specific constraints of hospital formularies, home care logistics, and outpatient workflow efficiency.
Product Type:
Hospital procurement committees weight clinical evidence tiers and formulary placement history when selecting supportive care portfolios for contract negotiation.
- Pain Management:Opioid and non-opioid analgesics combined with adjuvant neuropathic agents address chemotherapy-induced peripheral neuropathy and breakthrough cancer pain. US hospital systems anchor volume through FDA-approved extended-release morphine and fentanyl patch protocols, though EMA pressure on opioid stewardship is tightening prescribing guidelines across German oncology networks.
- Anti-nausea Agents:5-HT3 receptor antagonists and NK1 receptor antagonists form the pharmacological backbone of emesis control, with palonosetron and aprepitant commanding premium positioning in acute care. Demand concentrates in US infusion centers where ASCO antiemetic guidelines drive prophylactic administration prior to highly emetogenic chemotherapy regimens.
- Nutritional Supplements:Enteral and parenteral nutrition formulations combat cancer cachexia and maintain lean body mass during treatment cycles. Home care agencies in the Netherlands and United Kingdom are expanding direct-to-patient distribution of high-protein oral supplements as integrated care boards bundle nutritional support into capitated oncology pathways.
- Emotional Well-being Products:Anxiolytics, sleep aids, and complementary formulations address psychological distress parallel to physical symptom management. Japanese oncology practices under PMDA guidance are integrating these into supportive care protocols more systematically than European counterparts.
Pain management leads on scale; nutritional supplements lead on momentum.
Application:
Reimbursement coding specificity determines which applications attract manufacturer investment and clinical trial prioritization.
- Chemotherapy Support:Myelosuppression prophylaxis, mucositis management, and emesis control dominate this application, with granulocyte colony-stimulating factors and oral cryotherapy devices representing high-volume categories. German oncology centers under EMA integrated care protocols are standardizing pre-chemotherapy supportive care bundles to reduce emergency department utilization.
- Palliative Care:Symptom relief in terminal disease stages emphasizes comfort over curative intent, driving demand for long-acting analgesics and anxiolytics. Hospice agencies across US Medicare Advantage plans are expanding supportive care product formularies as value-based oncology contracts extend into end-of-life care.
- Radiation Therapy Aid:Mucositis prophylaxis and dermatitis management address tissue damage from external beam and brachytherapy protocols. French radiation oncology departments are piloting topical amifostine formulations under ANSM expanded access programs.
- Symptom Management:Cross-cutting interventions for fatigue, insomnia, and cognitive impairment operate outside protocol-specific chemotherapy or radiation frameworks. Community oncology practices in the United States are capturing this application through nurse navigator programs that triage patients to appropriate supportive care resources.
Chemotherapy support captures the largest revenue pool; palliative care is climbing the fastest as hospice integration accelerates.
End User:
Channel economics and purchasing authority fragmentation create distinct competitive dynamics across institutional and ambulatory settings.
- Hospitals:Inpatient oncology units and emergency departments command acute supportive care volumes, with pharmacy and therapeutics committees controlling formulary access through contract negotiations with group purchasing organizations. US health systems are consolidating vendor relationships to reduce therapeutic duplication across affiliated facilities.
- Home Care:Skilled nursing agencies and home infusion providers are displacing hospital-based administration for stable patients, requiring cold chain logistics and patient education infrastructure. Germany's hospital-at-home reimbursement expansion under statutory health insurance reform is accelerating this channel shift.
- Oncology Centers:Dedicated cancer treatment facilities combine infusion services with on-site supportive care dispensing, capturing patient volume through convenience and care coordination. Japanese designated cancer hospitals under Ministry of Health, Labour and Welfare certification standards maintain the tightest integration of supportive care into treatment protocols.
- Outpatient Clinics:Community-based oncology practices and ambulatory surgery centers handle lower-acuity supportive care needs with limited on-site pharmacy capabilities. These settings in France and the Netherlands rely heavily on specialty pharmacy distribution for injectable supportive care agents.
Hospitals retain volume leadership; home care gains share fastest as reimbursement shifts toward ambulatory models.
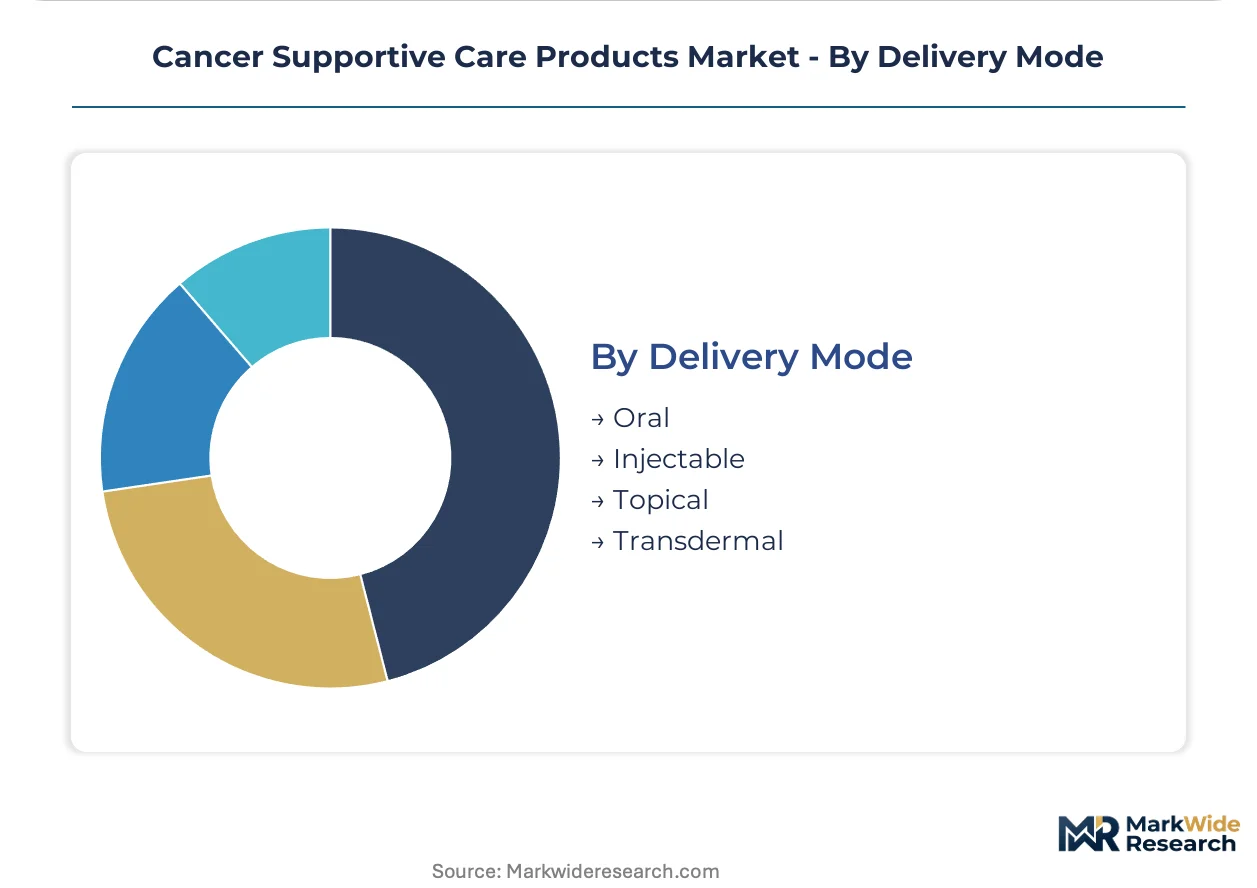
Delivery Mode:
Patient functional status and caregiver availability determine route selection, with formulation technology enabling channel migration.
- Oral:Tablets, capsules, and liquid formulations dominate patient-directed administration, with mucoadhesive film strips emerging for dysphagia and pediatric populations. FDA approval of novel oral antiemetic formulations is expanding home-based prophylaxis options previously limited to injectable routes.
- Injectable:Intravenous and subcutaneous delivery ensures bioavailability for acute symptoms and patients with compromised gastrointestinal function, commanding premium pricing in hospital settings. Subcutaneous auto-injector platforms for granulocyte colony-stimulating factors are modularizing administration workflows across US community oncology practices.
- Topical:Creams, gels, and rinses target localized symptoms including mucositis, dermatitis, and peripheral neuropathy with minimal systemic exposure. EMA MDR recertification requirements are extending timelines for novel topical combination products incorporating device elements.
- Transdermal:Patch delivery systems provide sustained release for chronic pain and nausea management, improving adherence in home care settings. Fentanyl and scopolamine patches face tightening controlled substance tracking requirements under US DSCSA serialization mandates.
Oral formulations dominate patient days; injectable routes command the highest revenue per dose.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oncology pharmacists and palliative care nurses concentrate in Germany, the United States, Japan, the United Kingdom, and India, anchoring regional capability clusters that shape supportive care product access and protocol design.
United States
Hospital-at-home reimbursement expansion and Medicare Advantage value-based oncology contracts are pulling acute supportive care into ambulatory settings. FDA bioequivalence pathways for generic injectables accelerate formulary access and price competition. The Texas Medical Center in Houston anchors one of the largest oncology supportive care research and training complexes.
Germany
Statutory health insurance reform is expanding hospital-at-home protocols for anti-nausea and pain management therapies. EMA integrated care guidelines under the EU MDR are standardizing pre-chemotherapy supportive care bundles. Heidelberg and Munich host dense clusters of university oncology centers pioneering supportive care protocol integration.
Japan
PMDA Sakigake designation expedites review for novel supportive care mechanisms targeting chemotherapy-induced peripheral neuropathy. Ministry of Health, Labour and Welfare certification standards for designated cancer hospitals mandate tight supportive care integration. The Kansai region around Osaka concentrates specialized oncology nursing workforce development programs.
United Kingdom
Integrated care boards are bundling supportive care into capitated oncology pathways and selecting logistics partners based on cold chain reliability. NHS England cancer strategy documents emphasize home-based supportive care administration. The Manchester cancer research cluster is piloting digital biomarker integration for remote symptom monitoring.
India
PLI scheme production-linked incentives for critical care drugs are attracting contract manufacturing investment for export-oriented supportive care API production. CDSCO streamlined approval pathways for oncology supportive care generics reduce market entry timelines. Hyderabad and Ahmedabad host expanding formulation facilities serving Middle East and African export markets.
Cancer Supportive Care Products Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the cancer supportive care products market, creating a tiered structure where scale-driven portfolios face pressure from agile niche developers. Large pharmaceutical groups leverage integrated manufacturing and distribution infrastructure to secure hospital formulary placement through contract breadth. Three archetypes dominate: biologics manufacturers with growth factor franchises, generic injectable specialists competing on cost efficiency, and antiemetic-focused developers with deep oncology channel relationships. Competitive moves concentrate on M&A for delivery technology assets and strategic partnerships with home care logistics providers.
Within the biologics manufacturing tier, Amgen Inc. and Novartis AG occupy positions defined by scale and therapeutic breadth. Among generic injectable specialists, Teva Pharmaceutical Industries Ltd. exemplifies cost-competitive positioning in hospital procurement channels. In the focused antiemetic developer segment, Helsinn Healthcare SA represents pure-play specialization with concentrated oncology relationships. These three companies illustrate how competitive positioning stratifies across manufacturing scale, portfolio breadth, and channel depth rather than converging on a single winning formula.
| Leading Market Players |
|---|
| Amgen Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Merck & Co. Inc. |
| GSK plc |
| Teva Pharmaceutical Industries Ltd. |
| Helsinn Healthcare SA |
| Heron Therapeutics Inc. |
| Others |
Supply Flow & Price Mechanics
EMA MDR sustainability and clinical evidence mandates gate qualified supply access for combination drug-device products, with manufacturers bearing recertification costs that pass through as premium-tier pricing for injectable anti-nausea therapies with integrated needle safety systems. Hospital procurement committees in Germany and the United States leverage volume scale to compress margins on standard oral formulations while paying premiums for cold-chain biologics with traceable compliance documentation.
Pricing Analysis
The bundled-vs-unbundled service split separates hospital formulary contracts from home care direct-to-patient models. Three-tier pricing structure across premium, standard, and economy levels reflects EMA MDR certification status, FDA bioequivalence tier, and cold chain reliability grade. Pricing pressure stems from generic injectable competition in US hospital procurement, with Medicare Advantage value-based contracts demanding cost-efficient alternatives. Community oncology practices exhibit highest price sensitivity; designated cancer hospitals in Japan show lowest sensitivity due to Ministry of Health, Labour and Welfare certification requirements.
Supply Chain Analysis
Workforce-availability constraints in pharmaceutical manufacturing concentrate API production in China and India, with formulation finishing in Germany and the United States. Active pharmaceutical ingredient supply draws from concentrated onshore chemical synthesis in Shandong province and Hyderabad industrial corridors, while excipient sourcing rests on European specialty chemical suppliers. Single-source vulnerability pervades generic ondansetron and granisetron API supply. Distribution runs through hospital group purchasing organizations in acute care and specialty pharmacy networks in home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU MDR transition deadlines and FDA biosimilar interchangeability rulings accelerating procurement system overhauls that expand qualified supplier rosters and displace legacy portfolios lacking refreshed clinical evidence packages.
For Market Incumbents: To counter API supply concentration risk, secure backward integration into critical excipient manufacturing or establish dual-source API contracts with CDSCO-registered Indian suppliers. Defend hospital formulary placement by front-loading human factors studies for combination delivery systems ahead of EMA MDR recertification deadlines. For New Entrants and Emerging Players: Begin with oral film strip delivery formats for pediatric and dysphagia anti-nausea segments, where FDA approval pathways for novel formulations remain less congested than injectable generics. Target home care agency procurement relationships in the Netherlands and United Kingdom, where integrated care boards prioritize cold chain reliability over historical vendor status. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier generic injectable specialists lacking MDR-compliant combination product portfolios. Long-term viability hinges on regulatory compliance infrastructure rather than molecule exclusivity. Watch FDA biosimilar interchangeability designation announcements as the inflection signal for payer contract renegotiation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Recertification Investment | Legacy device dossier rebuilding secures European market access for combination anti-nausea delivery systems. |
| Home Care Logistics Partnership | Cold chain reliability metrics determine vendor selection by UK and Netherlands integrated care boards. |
| Oral Film Strip Formulation Development | Mucoadhesive dissolvable formats open pediatric and dysphagia segments previously served only by injectables. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives attract export-oriented API and finished dose capacity for Middle East and African markets. |
| Digital Biomarker Integration | Remote symptom monitoring platforms shift value demonstration from clinical endpoints to functional status preservation. |
Methodological Framework
Multiple input streams — primary interviews with formulary directors, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases; and customs trade data — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates and competitive positioning maps.
Data-stream reconciliation across product type, application, end user, delivery mode, and regional regulatory cluster dimensions fed analytical frameworks projecting volume and value trajectories over the projection horizon. CAGRs were derived from modeled patient population growth, treatment protocol penetration rates, and pricing elasticity assumptions specific to oncology supportive care reimbursement pathways.
Several conditions sit outside the modeled scope, including pandemic-related treatment disruption, sudden API supply embargo, and radical biosimilar substitution policy shifts. Forecasts reflect assumptions about regulatory timeline adherence and reimbursement stability. Material deviation in EMA MDR enforcement intensity or FDA interchangeability designation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Lung Cancer Treatment Market
Oncology
Head and Neck Cancer Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Colorectal Cancer Market
Oncology
Osteosarcoma Market
Oncology
North America Proton Therapy Market
Oncology
Glottic Cancer Treatment Market
Oncology
North America Bone Metastasis Market
Oncology
AI in Oncology Market
Oncology
Tumor Embolization Market
Oncology
Germany Radiotherapy Market
Oncology
Glioblastoma Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Asia-Pacific Cancer Therapy Market