
 Low-Grade Central Osteosarcoma Treatment Market | 2026-2036
Low-Grade Central Osteosarcoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Grade Central Osteosarcoma Treatment Market Foresight
Cancer centers are rotating toward targeted therapy and immunotherapy protocols as first-line options for low-grade central osteosarcoma, displacing older chemotherapy-heavy regimens. Pfizer Inc leverages its kinase inhibitor portfolio to compete in this evolving treatment paradigm. Novartis AG anchors its position through sustained R&D investment in bone malignancy pathways. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor platforms that address refractory cases.
Low-grade central osteosarcoma represents a rare, slow-growing primary bone tumor arising from intramedullary osteoid-producing spindle cells, typically affecting the metaphysis of long bones with low metastatic potential. Its primary clinical purpose centers on limb-sparing intervention combined with systemic therapy to prevent local recurrence. Chemotherapy retains the largest patient volume share, while immunotherapy captures the fastest expansion as checkpoint inhibitors gain trial data. Intravenous delivery dominates hospital administration, though oral formulations are gaining traction in maintenance settings.
FDA orphan drug designation and EMA pediatric investigation plans shape clinical trial economics and accelerate regulatory pathways for novel agents. ISO 14155 standards govern international trial conduct, ensuring data integrity across multi-site sarcoma studies. Stakeholders must monitor biomarker-defined patient stratification as it reconfigures reimbursement and prescribing decisions across major oncology markets.
Market Dynamics
The transition from cytotoxic chemotherapy to targeted kinase inhibition and checkpoint blockade is compressing treatment timelines while elevating biomarker requirements for patient selection. This therapeutic pivot demands reconfigured clinical infrastructure and reimbursement frameworks across major oncology centers.
Growth Catalysts
- FDA Orphan Drug Incentives:The seven-year market exclusivity and tax credits for qualified clinical trials accelerate enrollment in rare sarcoma studies, reducing sponsor risk for bone malignancy programs.
- Pediatric Investigation Plans:EMA-mandated PIPs ensure dedicated development pathways for adolescent patients, expanding addressable populations in European tertiary hospitals.
- Biomarker Stratification:Next-generation sequencing panels at sarcoma referral networks enable precision matching of patients to targeted agents, improving response signal detection.
Market Restraints
- Clinical Trial Recruitment Friction:The ultra-rare incidence of low-grade central osteosarcoma stretches enrollment timelines across multi-site studies, inflating per-patient development costs.
- Reimbursement Uncertainty:Payers in Germany and Japan apply distinct health technology assessment criteria for novel bone tumor therapies, creating access delays post-approval.
- Pathology Diagnostic Variability:Inter-observer disagreement in distinguishing low-grade central osteosarcoma from benign fibro-osseous lesions complicates trial eligibility and registry accuracy.
Strategic Opportunities
- Maintenance Oral Formulations:Transitioning intravenous checkpoint inhibitors to oral small-molecule alternatives would shift treatment locus from infusion centers to community oncology practices.
- Japan's Sakigake Designation:Japan's PMDA priority review pathway for innovative oncology drugs offers truncated regulatory timelines for first-in-class bone malignancy agents.
- Real-World Evidence Infrastructure:Integration of prospective registries at US sarcoma centers enables label expansion through post-marketing outcome collection without incremental trial costs.
Industry Challenges
- Sarcoma Pathology Specialist Scarcity:The limited pool of board-certified bone tumor pathologists concentrates diagnostic review at a handful of US academic medical centers, creating bottlenecks.
- Cross-Border Trial Harmonization:Divergent ISO 14155 interpretations between US and EU competent authorities generate protocol amendment cycles that delay study activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Grade Central Osteosarcoma Treatment Market |
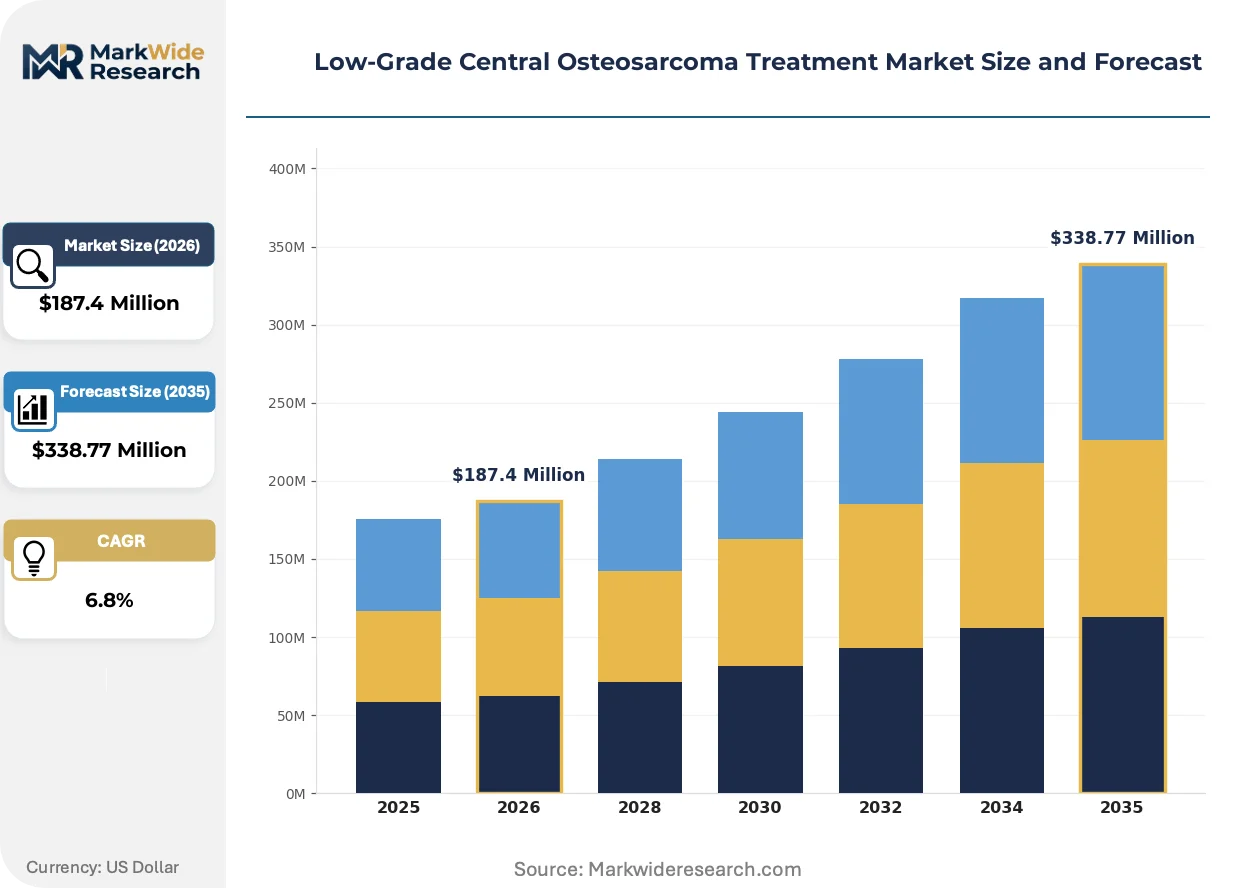
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Cancer Centers, Homecare Providers Product Type: Antineoplastics, Antibodies, Hormonal Agents, Other |
| Companies Covered | Pfizer Inc, Novartis AG, Bayer AG, Amgen Inc, Bristol-Myers Squibb Company, GSK plc, Johnson & Johnson, Y-mAbs Therapeutics, OS Therapies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Grade Central Osteosarcoma Treatment Market Shifts & Advancements
Biomarker-driven patient segmentation is fragmenting the historical chemotherapy monolith into discrete molecular subpopulations, each demanding tailored therapeutic approaches and companion diagnostic infrastructure.
Liquid biopsy circulating tumor DNA platforms are miniaturizing the surveillance paradigm for bone malignancy recurrence detection. Pediatric oncology departments at tertiary hospitals are piloting these assays for post-surgical monitoring. This technology is miniaturizing the interval between biochemical progression and radiographic confirmation, compressing therapeutic decision windows.
EMA's Clinical Trial Regulation (CTR) harmonizes submission formats across EU member states, eliminating redundant national competent authority reviews. Sponsor organizations are consolidating European trial operations into single regulatory submissions. Sarcoma studies with sites in Germany, France, and Italy are capturing the earliest operational benefits from this framework consolidation.
Hospital pharmacy committees are tightening formulary controls on high-cost oncology agents, demanding outcomes-based contracting for novel bone tumor therapies. US cancer centers are negotiating indication-specific rebates with manufacturers rather than accepting standard wholesale acquisition cost. This recalibration is most visible at NCI-designated comprehensive cancer centers with dedicated sarcoma programs.
Low-Grade Central Osteosarcoma Treatment Market Segmentation
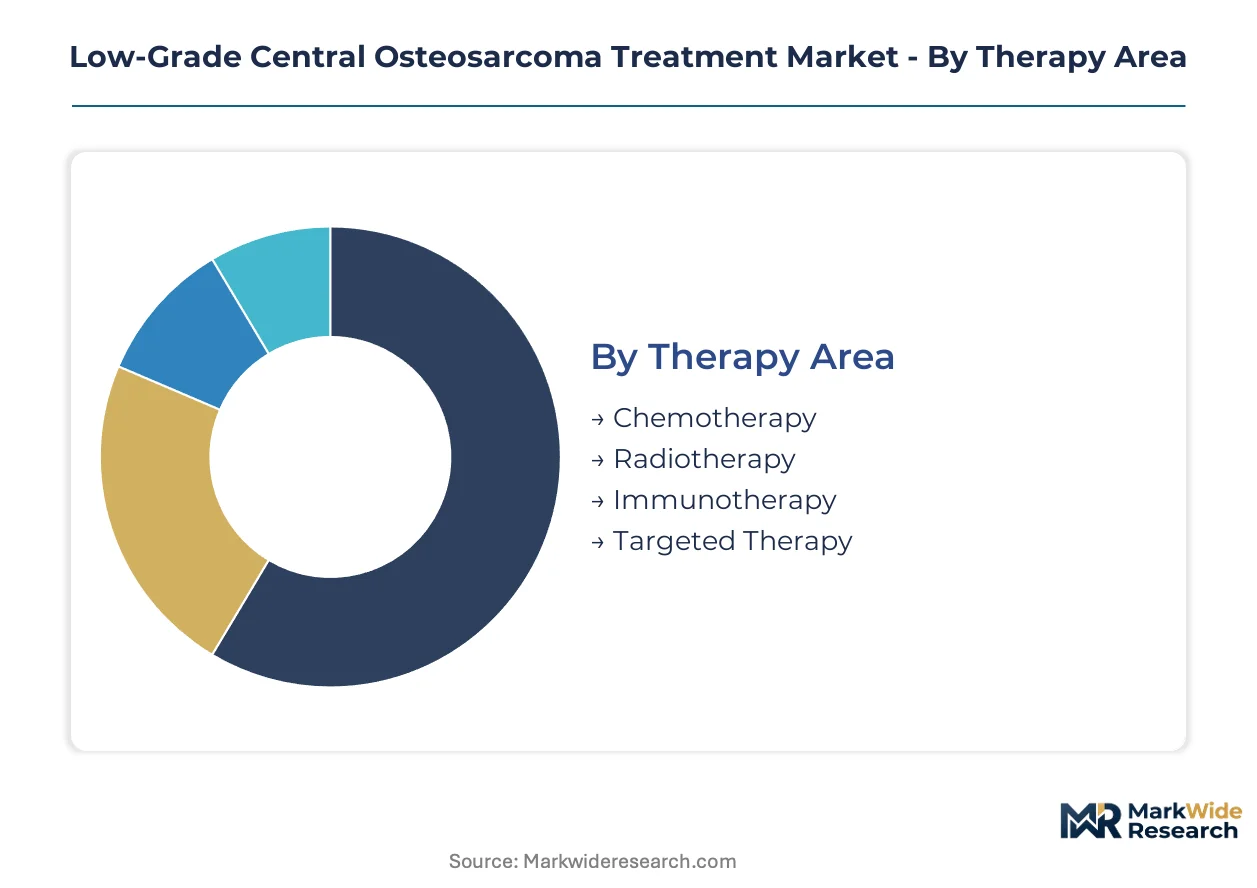
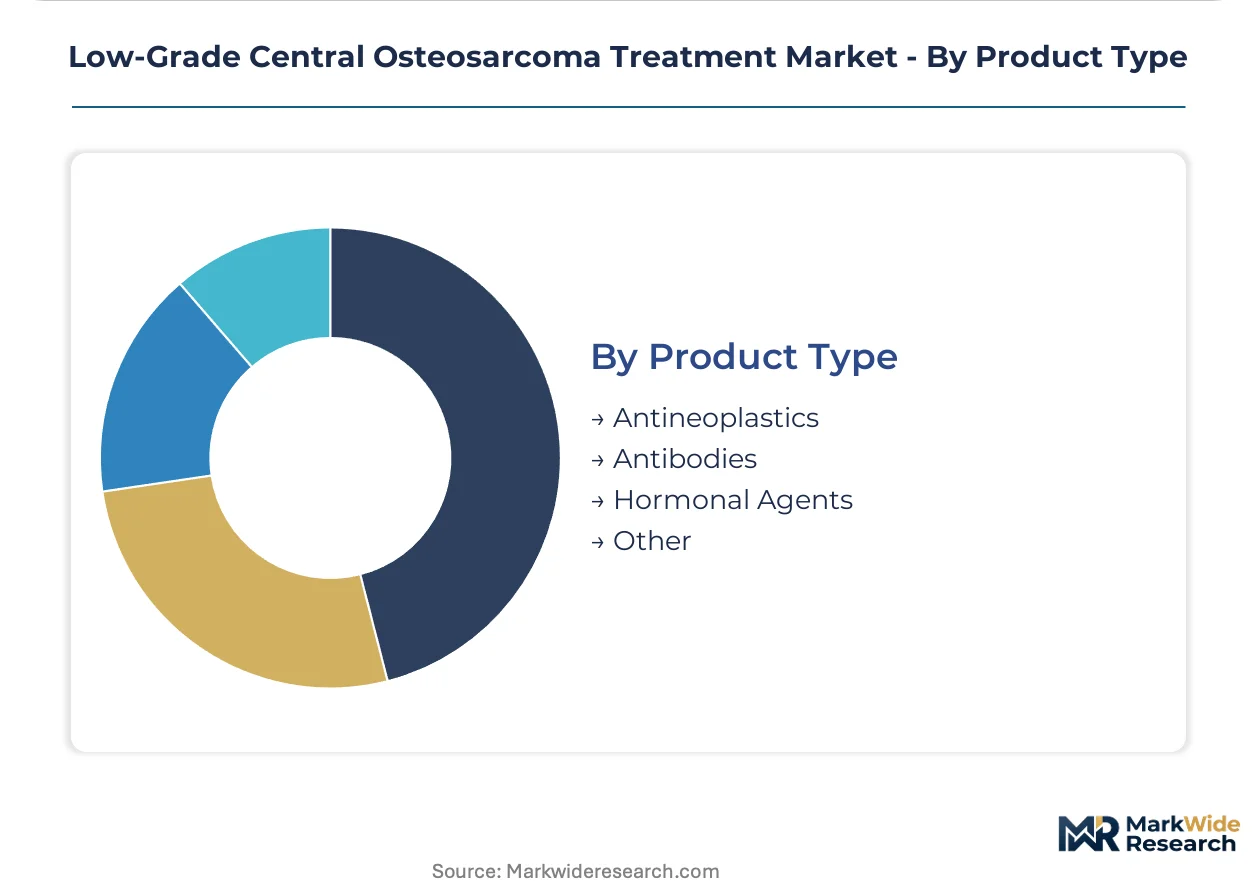
Low-grade central osteosarcoma treatment segmentation reveals distinct regulatory, reimbursement, and clinical infrastructure requirements across therapy modalities and delivery formats. Each category carries specific FDA and EMA pathway implications that shape commercial strategy and patient access.
Therapy Area:
FDA orphan drug designation and EMA pediatric investigation plans create divergent approval timelines and post-market obligations across therapeutic categories.
- Chemotherapy:Cytotoxic agents retain the largest patient volume through established adjuvant protocols at NCI-designated cancer centers. Demand concentrates in United States tertiary hospitals where methotrexate-cisplatin-doxorubicin regimens remain standard of care, constrained by cumulative cardiotoxicity monitoring requirements.
- Immunotherapy:Checkpoint inhibitors capture the steepest expansion trajectory through PD-1/PD-L1 blockade trials for refractory cases. Enrollment accelerates at German sarcoma referral networks where biomarker-stratified protocols enable precision patient matching.
- Targeted Therapy:Kinase inhibitors address specific molecular alterations with companion diagnostic requirements.
- Radiotherapy:External beam and proton modalities serve localized disease control in limb-sparing surgical protocols.
Established volume favors chemotherapy; emerging adoption favors immunotherapy.
Delivery Mode:
Hospital reimbursement structures and pharmacy benefit design create cost tier differentiation between infusion-dependent and self-administered formats.
- Intravenous:Infusion center administration dominates hospital-based oncology departments with structured nursing oversight and adverse event monitoring. United States cancer centers maintain this preference for cytotoxic agents requiring hydration protocols.
- Oral:Small-molecule formulations shift treatment locus toward community oncology practices and maintenance settings. Japanese tertiary hospitals pilot oral checkpoint inhibitor alternatives under PMDA Sakigake priority review pathways.
- Subcutaneous:Reduced infusion time appeals to pediatric departments with limited vascular access.
- Topical:Localized application serves palliative skin lesion management in advanced disease.
Hospital formulary control favors intravenous; patient convenience and cost containment favor oral expansion.
End User:
Site-of-care regulations and accreditation requirements fragment purchasing authority and clinical trial access across institutional types.
- Cancer Centers:NCI-designated comprehensive centers anchor sarcoma-specific research infrastructure and early-phase trial enrollment. United States academic medical centers concentrate pathology expertise and molecular tumor board review.
- Hospitals:General oncology departments manage the majority of incident cases through standardized chemotherapy protocols. German university hospitals integrate EMA-mandated pediatric investigation plans into adolescent treatment pathways.
- Specialty Clinics:Orthopedic oncology practices coordinate surgical resection with systemic therapy referral.
- Homecare Providers:Subcutaneous and oral administration enable outpatient maintenance monitoring.
Clinical trial density favors cancer centers; incident case volume favors hospital systems.
Product Type:
Manufacturing complexity and biosimilar competition create margin differentiation across molecular formats.
- Antineoplastics:Small-molecule cytotoxics face generic erosion but maintain volume through protocol standardization. Methotrexate and doxorubicin supply chains concentrate with contract manufacturers serving United States hospital purchasing organizations.
- Antibodies:Monoclonal constructs command premium pricing through checkpoint and kinase-targeted mechanisms. Japanese PMDA accelerated approval pathways truncate development timelines for novel bone malignancy biologics.
- Hormonal Agents:Limited application in osteosarcoma histology restricts commercial development.
- Other:Investigational cellular therapies and oncolytic vectors occupy preclinical and early-phase pipelines.
Generic pressure constrains antineoplastics; biologic innovation investment concentrates in antibodies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Memorial Sloan Kettering Cancer Center sarcoma referral network underwrites the United States' dominance in low-grade central osteosarcoma treatment infrastructure, connecting 70-plus academic medical centers through standardized pathology review protocols.
United States
NCI-designated comprehensive cancer centers concentrate incident case volume and early-phase trial enrollment for kinase inhibitor programs. FDA orphan drug designation accelerates sponsor timelines through tax credits and seven-year exclusivity provisions. The MD Anderson-Boston Children's dyad anchors pediatric bone malignancy research, with Houston and Boston metropolitan areas hosting the largest concentration of board-certified orthopedic oncologists.
Germany
University hospital networks integrate EMA-mandated pediatric investigation plans into adolescent treatment pathways, expanding addressable populations. The country's national pharmaceutical regulator applies distinct health technology assessment criteria for novel bone tumor therapies, creating post-approval access negotiations. The Berlin-Heidelberg-Munich triangle concentrates sarcoma pathology expertise, with Charité and German Cancer Research Center coordinating multi-site biomarker-stratified protocols.
Japan
PMDA Sakigake priority review pathways truncate regulatory timelines for first-in-class bone malignancy agents, attracting sponsor investment. Oral checkpoint inhibitor alternatives are piloting at Tokyo and Osaka tertiary hospitals under accelerated approval frameworks. The Kanto region's National Cancer Center anchors real-world evidence collection for post-marketing outcome studies without incremental trial costs.
United Kingdom
NHS England's specialized commissioning framework concentrates rare sarcoma treatment at designated supra-regional centers, standardizing referral pathways. The Medicines and Healthcare products Regulatory Agency aligns with EMA centralized procedures while maintaining national variation in reimbursement timing. The Royal National Orthopaedic Hospital in Stanmore and Birmingham's Queen Elizabeth Hospital host the largest surgical volumes for limb-sparing interventions.
Switzerland
Swissmedic's accelerated access pathways for innovative oncology drugs complement EMA marketing authorizations, reducing time-to-treatment for pediatric populations. University Hospital Zurich and Geneva University Hospital integrate molecular tumor boards with the country's dense pharmaceutical R&D cluster. Basel's proximity to Novartis AG headquarters facilitates investigator-initiated trials for bone malignancy pathways.
Low-Grade Central Osteosarcoma Treatment Market Competitive Landscape
Listed leaders compete with private specialists across regulatory strategy and portfolio breadth, creating a tiered structure where large-cap pharmaceutical companies anchor immunotherapy development while boutique biotechs occupy targeted therapy niches. The vendor base fragments across kinase inhibitor, checkpoint inhibitor, and cytotoxic chemotherapy vectors. Three archetypes dominate: diversified oncology majors with bone malignancy divisions, rare disease specialists leveraging FDA orphan incentives, and radiopharmaceutical developers addressing localized disease control. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with parties seeking to secure sarcoma referral network access.
Within the diversified oncology major tier, Pfizer Inc and Novartis AG exemplify scale-driven platform approaches, while Bristol-Myers Squibb Company occupies a distinct position through checkpoint inhibitor infrastructure. These three entities represent contrasting strategic postures: Pfizer Inc leverages kinase inhibitor portfolio breadth, Novartis AG anchors sustained R&D investment in bone malignancy pathways, and Bristol-Myers Squibb Company differentiates via refractory-case addressing mechanisms.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis AG |
| Bayer AG |
| Amgen Inc |
| Bristol-Myers Squibb Company |
| GSK plc |
| Johnson & Johnson |
| Y-mAbs Therapeutics |
| OS Therapies |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between NCI-designated cancer centers and monoclonal antibody manufacturers lock in supply access for checkpoint inhibitors while anchoring price visibility across multi-year procurement cycles. These contracts concentrate purchasing power at United States academic medical centers, compressing margins for biosimilar entrants while securing volume commitments for innovator biologics.
Pricing Analysis
Volume-discount tiering structures separate NCI-designated comprehensive cancer centers from community oncology practices and homecare providers, with the largest institutions commanding rebates tied to indication-specific patient volume. Pricing stratifies across premium innovator biologics, standard-of-care cytotoxics, and economy-tier generics, with differentiation driven by companion diagnostic bundling and biomarker stratification requirements. Cost compression in the cytotoxic segment intensifies as methotrexate and doxorubicin face generic erosion, while checkpoint inhibitors maintain pricing power through orphan exclusivity. Community oncology practices exhibit the highest price sensitivity due to formulary committee constraints, whereas pediatric departments at tertiary hospitals prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate intravenous biologic distribution, with hospital pharmacy committees minimizing on-hand stock of high-cost checkpoint inhibitors due to cold-chain requirements and expiration risk. Manufacturing concentration rests on United States, Switzerland, and Japan for monoclonal antibody production, with active pharmaceutical ingredient sourcing drawn from contract manufacturers in Ireland and Singapore. Supply chain vulnerability centers on single-source dependency for proprietary cell lines used in biologic production, with tariff exposure on Chinese-sourced filtration media creating input cost volatility. Distribution runs through specialty oncology distributors with temperature-controlled logistics, bypassing general pharmaceutical wholesalers for high-value biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across molecular subpopulations creates niche entry points, as biomarker-driven patient segmentation splinters the historical chemotherapy monolith into addressable micro-markets with distinct companion diagnostic and therapeutic requirements.
For Market Incumbents: Shield kinase inhibitor portfolios from biosimilar pressure by deepening backward integration into companion diagnostic development, locking in pathology laboratory partnerships at Memorial Sloan Kettering and MD Anderson. Prioritize EMA pediatric investigation plan compliance to secure European adolescent market access before competitor enrollment accelerates. Counter emerging radiopharmaceutical developers by expanding real-world evidence infrastructure for label expansion without incremental trial costs. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks offer the most penetrable regulatory pathway for first-in-class bone malignancy agents, truncating development timelines relative to standard review. Target oral small-molecule checkpoint inhibitor development for Japanese PMDA Sakigake priority review, where maintenance therapy demand concentrates at Tokyo and Osaka tertiary hospitals. Pursue investigator-initiated trial partnerships with Basel-based pharmaceutical clusters to leverage existing sarcoma referral network relationships. For Investors and Strategic Acquirers: Capital is best deployed toward rare disease specialists with FDA orphan drug exclusivity moats and biomarker-stratified trial infrastructure, positioned for sustained pricing power across the analysis window. Acquisition targets should demonstrate existing pediatric investigation plan compliance and molecular tumor board integration at NCI-designated centers. Watch enrollment velocity in German sarcoma referral networks as the inflection indicator for checkpoint inhibitor platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA pediatric investigation plan compliance accelerates European adolescent patient access. |
| Regulatory Approval Pathway | Japan PMDA Sakigake designation truncates timelines for novel bone malignancy agents. |
| Backward Integration | In-house companion diagnostic production secures biomarker-stratified patient matching. |
| Licensing Agreement | Investigator-initiated trials with Basel clusters leverage Novartis proximity advantages. |
| Manufacturing Scale-Up | Cold-chain capacity expansion serves NCI-designated center volume commitments. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with sarcoma pathologists, pediatric oncology department heads, formulary directors at NCI-designated centers, and regulatory affairs specialists; alongside secondary validation through FDA orphan drug filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov sarcoma protocol registries, and hospital procurement databases. Bottom-up patient volume estimates triangulated against top-down pharmaceutical revenue attribution across therapy modalities.
Across the analysis window, the forecasting framework modeled treatment line progression, administration route preference shifts, patient age stratification, and regional regulatory cluster differentiation to derive expansion trajectories. CAGRs emerged from segmented patient flow analysis incorporating biomarker adoption curves and reimbursement pathway maturation, with inputs from ISO 14155 trial conduct standards and health technology assessment timelines in Germany and Japan.
Underlying assumptions cover sustained orphan drug incentive continuity and biomarker test reimbursement stability, with deviation risk concentrated in pathology diagnostic variability and cross-border trial harmonization friction. Revision becomes warranted when checkpoint inhibitor trial enrollment velocity at German sarcoma networks crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Esophageal Cancer Market
Oncology
Bone Cancer Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Ovarian Cancer Market
Oncology
Vulvar Cancer Market
Oncology
Hadron Therapy Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Pituitary Cancer Market
Oncology
America Cancer Immunotherapy Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Global Proton Therapy Market
Oncology
Particle Therapy Systems Market
Oncology
Colorectal Cancer Screening Market