
 Osteosarcoma Market | 2026-2036
Osteosarcoma Market Size, Share, and Industry Trends Forecast 2026-2036
Osteosarcoma Market Outlook
Multi-source clinical supply for osteosarcoma combination regimens is hardening as trial sponsors diversify beyond single API dependencies. Pfizer Inc leverages its established oncology manufacturing footprint to sustain cisplatin-doxorubicin combination availability. Bristol-Myers Squibb Company anchors immuno-oncology development through checkpoint inhibitor programs in bone malignancies. Novartis AG differentiates via targeted therapy pipelines directed at specific sarcoma molecular subtypes.
Osteosarcoma constitutes a primary malignant bone tumor arising from mesenchymal osteoid-producing cells, typically manifesting in the metaphyseal regions of long bones with peak incidence in adolescents and young adults; its clinical management demands multimodal intervention combining cytotoxic agents, limb-salvage surgery, and increasingly molecularly directed approaches. Chemotherapy retains dominant position in first-line protocols while immunotherapy represents the fastest-expanding segment as PD-1/PD-L1 inhibitors enter Phase II sarcoma trials. Treatment stage segmentation shows neoadjuvant protocols commanding concentrated margin pools due to higher per-patient drug intensity and monitoring requirements.
FDA orphan drug designations and EMA's PRIME eligibility for pediatric oncology indications shape development prioritization and market access timelines for osteosarcoma therapeutics. The European Medicines Agency enforces pediatric investigation plan requirements that mandate age-appropriate formulation development. Stakeholders must monitor biomarker-driven patient stratification advances that will redefine reimbursable treatment populations and contractable endpoints.
Market Dynamics
Accelerated FDA orphan drug pathways are compressing clinical development timelines for osteosarcoma therapeutics while simultaneously fragmenting trial design standards across regulatory jurisdictions. This structural pressure forces sponsors to reconcile divergent pediatric investigation requirements between the FDA and EMA.
Growth Catalysts
- Orphan Drug Incentives:FDA's seven-year market exclusivity and tax credits for pediatric oncology trials redirect capital toward osteosarcoma indications previously deemed commercially marginal.
- Biomarker Stratification:Molecular subtyping of sarcoma specimens enables precision enrollment in targeted therapy cohorts, expanding addressable patient populations for investigational agents.
- Germany:The country's centralized sarcoma reference networks aggregate sufficient case volumes to support single-arm registration trials that would fail in fragmented markets.
Market Restraints
- API Supply Concentration:Cisplatin and doxorubicin active pharmaceutical ingredients concentrate among Chinese and Indian contract manufacturers, exposing combination protocols to import disruption.
- EMA Pediatric Investigation Plans:Mandatory age-appropriate formulation development for all oncology applications extends preclinical timelines by 18-24 months regardless of adult approval status.
- Tumor Heterogeneity:Inter-patient genomic variability in osteosarcoma limits predictive biomarker utility, constraining patient selection for targeted therapy trials.
Strategic Opportunities
- Japan:PMDA's Sakigake designation system offers priority review for pediatric bone malignancy innovations with limited domestic development activity.
- Neoadjuvant Immunotherapy:Checkpoint inhibitor administration prior to limb-salvage surgery creates measurable response endpoints that accelerate regulatory pathways.
- Academic-Industry Consortia:European Network for Cancer Research in Children and Adolescents pools multinational trial infrastructure, reducing per-site activation costs.
Industry Challenges
- Pediatric Trial Enrollment:Sarcoma rarity across age groups necessitates transcontinental patient referral networks that strain site coordination capabilities.
- Companion Diagnostic Development:Parallel validation of biomarker assays with therapeutic candidates doubles regulatory submission complexity and review uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteosarcoma Market |
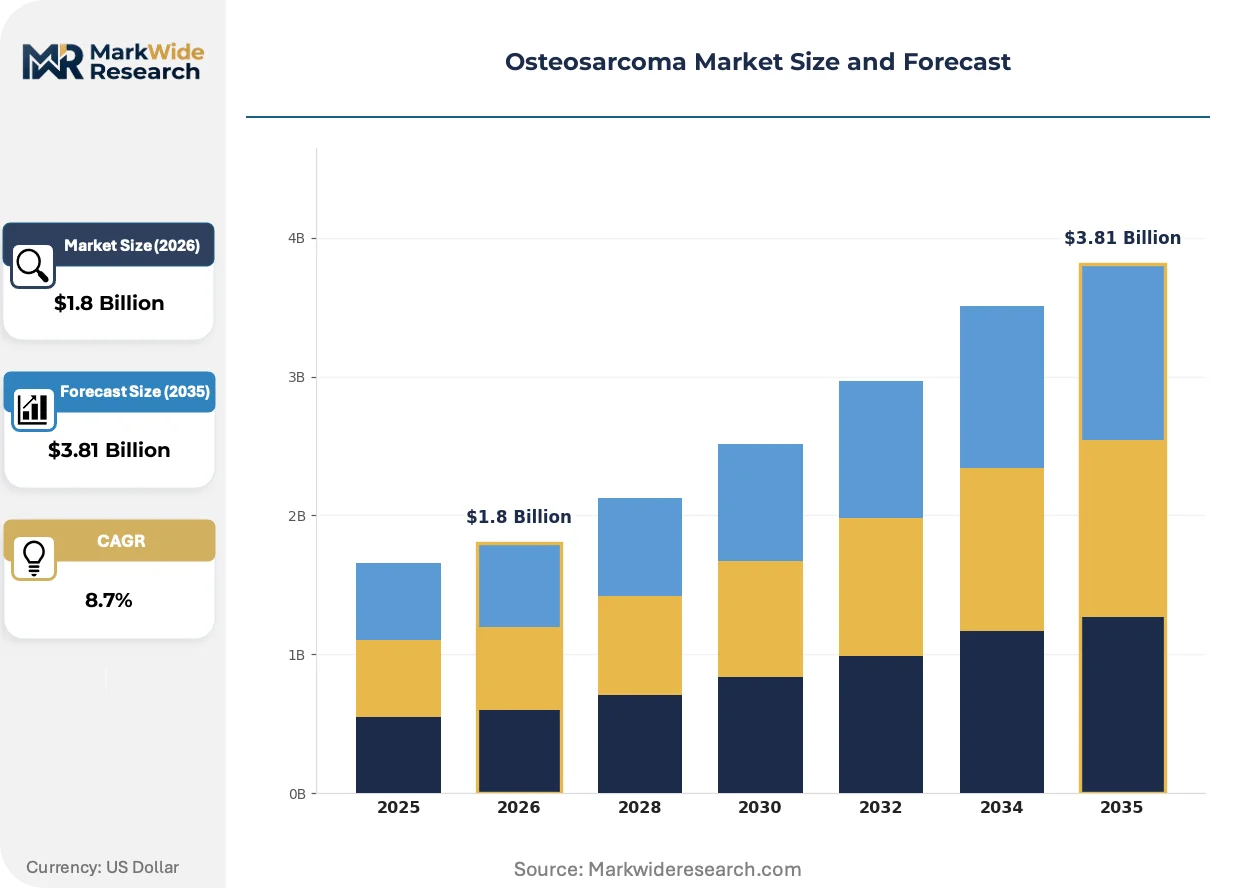
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy Treatment Stage: Adjuvant, Neoadjuvant, Palliative, Maintenance End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | Pfizer Inc, Novartis AG, Bristol-Myers Squibb Company, Bayer AG, Merck & Co., Amgen Inc, Eli Lilly and Company, AstraZeneca PLC, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteosarcoma Market Strategic Shifts
Next-generation sequencing platforms are redefining patient stratification in bone malignancy trials, compressing the gap between molecular characterization and protocol assignment. This convergence of diagnostic and therapeutic development timelines is restructuring how sponsors design registration pathways.
Liquid biopsy technologies for circulating tumor DNA detection are integrating into osteosarcoma monitoring protocols. Pediatric oncology centers in the United States adopt these platforms to track minimal residual disease post-surgery, enabling earlier intervention for metastatic recurrence. The technology is integrating longitudinal molecular surveillance into standard-of-care workflows previously dependent on radiographic progression alone.
EMA's revised Pediatric Regulation implementation guidelines tighten evidentiary requirements for extrapolation from adult efficacy data. Sponsors must now generate osteosarcoma-specific pharmacokinetic data rather than relying on allometric scaling from adult sarcoma trials. Early-phase programs targeting adolescents face expanded preclinical juvenile toxicology obligations that extend IND-enabling timelines.
Hospital procurement departments in Germany and Japan are consolidating oncology drug purchasing through centralized tender mechanisms. Single-source contracts for platinum-based chemotherapy now cover three-year supply horizons, displacing quarterly spot purchasing. This concentration shifts negotiating leverage toward large academic medical centers with sufficient case volumes to justify sole-supplier arrangements.
Osteosarcoma Market Segmentation
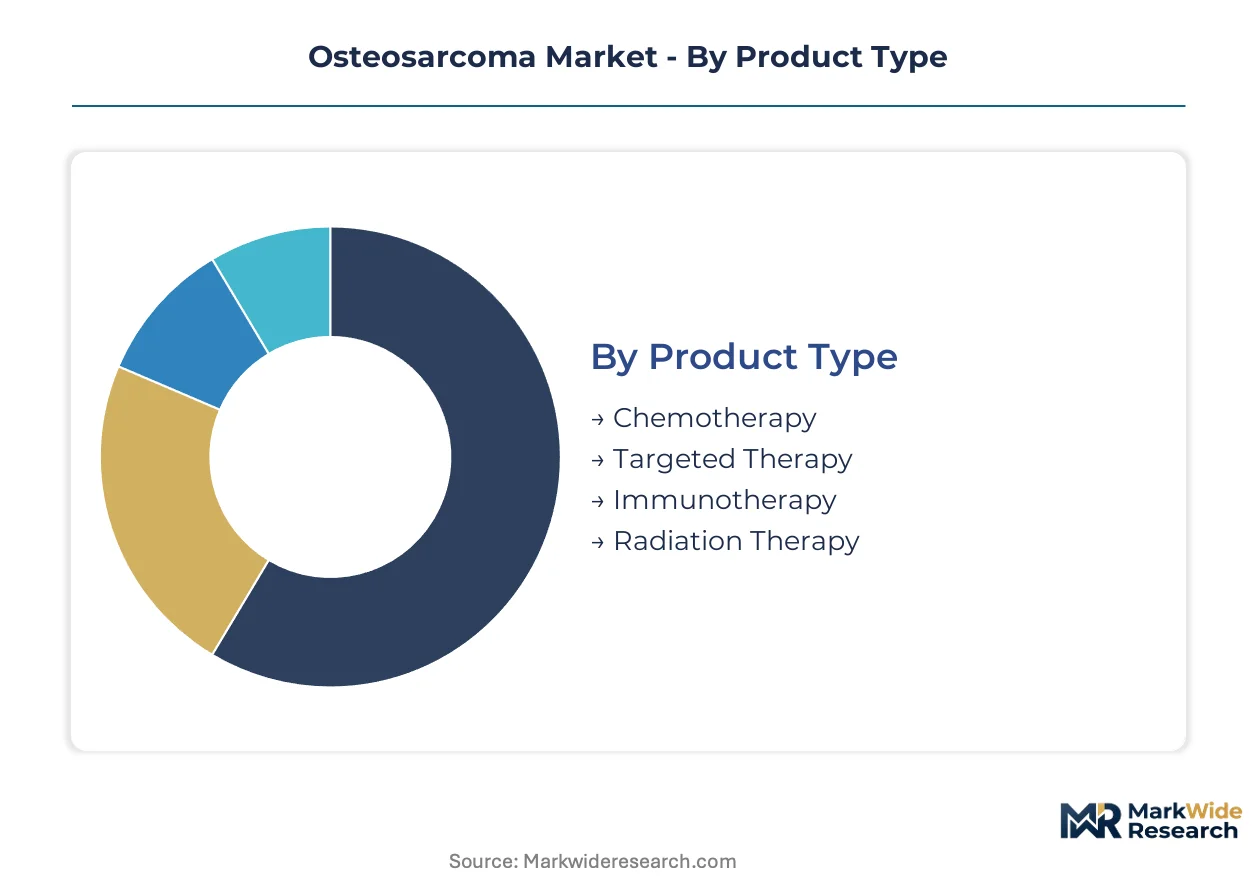
Osteosarcoma treatment protocols demand precise patient stratification across therapeutic modalities and care settings. Supply concentration for platinum-based chemotherapies and checkpoint inhibitors shapes how segments compete for manufacturing capacity and clinical trial enrollment.
Product Type:
API manufacturing for osteosarcoma therapeutics concentrates among Chinese and Indian contract producers, exposing combination regimens to single-source vulnerabilities.
- Chemotherapy:Cisplatin-doxorubicin-methotrexate protocols retain first-line dominance through established manufacturing scale and limb-salvage surgery integration. Demand clusters at pediatric oncology centers in the United States where reference networks standardize dosing algorithms.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors represent the most rapidly advancing modality, with Bristol-Myers Squibb and Merck anchoring Phase II bone sarcoma programs through accelerated FDA orphan pathways. Enrollment concentrates in Germany's centralized sarcoma reference networks.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR pathway modulators address molecular subtypes with defined genomic alterations.
- Radiation Therapy:Proton beam and intensity-modulated modalities serve unresectable or metastatic presentations.
Chemotherapy absorbs the bulk of installed capacity; immunotherapy is expanding most quickly.
Treatment Stage:
Margin structures vary sharply across intervention timing, with pre-surgical protocols commanding premium pricing due to intensive monitoring requirements.
- Neoadjuvant:Pre-operative chemotherapy cycles enable tumor response assessment and limb-salvage planning. United States pediatric centers favor this approach for measurable endpoints that accelerate regulatory pathways.
- Adjuvant:Post-surgical protocols eradicate micrometastatic disease through standardized multi-agent regimens. German sarcoma networks aggregate sufficient volumes to support protocol optimization studies.
- Palliative:Focuses on symptom management and quality-of-life preservation in metastatic or recurrent disease.
- Maintenance:Extended low-intensity therapy aims to prolong remission duration in high-risk patients.
Neoadjuvant protocols capture concentrated margin pools; maintenance is gaining share fastest as risk-stratification improves.
End User:
Procurement authority concentrates at large academic medical centers with dedicated sarcoma programs, displacing fragmented purchasing across community settings.
- Hospitals:Tertiary centers with orthopedic oncology units perform limb-salvage surgery alongside systemic therapy. Japan's National Cancer Center Hospital anchors regional referral patterns.
- Oncology Clinics:Specialized outpatient facilities manage chemotherapy cycles and toxicity monitoring. United States freestanding cancer centers compete through trial access and patient navigation services.
- Research Institutions:Academic medical centers conduct early-phase investigations and correlative science studies.
- Homecare:Oral targeted agents and supportive care enable treatment delivery outside institutional settings.
Hospitals anchor volume throughput; oncology clinics are climbing the fastest as ambulatory reimbursement expands.
Administration Route:
Formulation development timelines diverge across delivery mechanisms, with EMA pediatric investigation plans mandating age-appropriate alternatives regardless of adult approval status.
- Intravenous:Platinum agents and anthracyclines require infusion center infrastructure with cardiac monitoring capabilities. German hospital procurement departments consolidate purchasing through multi-year tender mechanisms.
- Oral:Targeted small molecules and metronomic chemotherapy improve patient compliance and reduce institutional burden. Japan's PMDA prioritizes pediatric-friendly formulations through Sakigake designation.
- Subcutaneous:Supports select biologic agents and supportive care medications.
- Intramuscular:Limited application for specific supportive care agents in resource-constrained settings.
Intravenous retains dominant volume share; oral formulations are gaining share fastest as molecularly targeted pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum and anthracycline API manufacturing concentrates in Chinese and Indian contract facilities, creating geographic dependencies for combination chemotherapy supply chains serving osteosarcoma protocols worldwide.
United States
Pediatric oncology centers at Memorial Sloan Kettering and MD Anderson anchor demand for neoadjuvant cisplatin-doxorubicin regimens. FDA accelerated approval pathways compress development timelines for orphan oncology indications. Boston's Dana-Farber Cancer Institute coordinates multi-site immuno-oncology trials through the Children's Oncology Group network.
Germany
Centralized sarcoma reference networks in Essen and Heidelberg aggregate sufficient case volumes to support single-arm registration trials. EMA pediatric investigation plans mandate age-appropriate formulation development extending preclinical timelines. The German Cancer Research Center pools multinational trial infrastructure through European academic-industry consortia.
Japan
National Cancer Center Hospital in Tokyo anchors regional referral patterns for limb-salvage surgery protocols. PMDA's Sakigake designation system offers priority review for pediatric bone malignancy innovations with limited domestic development. Osaka's pharmaceutical corridor houses formulation specialists addressing pediatric-friendly delivery mechanisms.
China
API contract manufacturers in Jiangsu and Zhejiang provinces supply concentrated volumes of cisplatin and doxorubicin active ingredients. NMPA oncology guidelines increasingly align with international pediatric trial standards. Shanghai's Fudan University Cancer Hospital participates in multinational Phase II checkpoint inhibitor studies.
India
Hyderabad and Ahmedabad API producers serve as secondary sources for platinum-based chemotherapy raw materials. CDSCO streamlined approval pathways for orphan oncology indications mirror FDA acceleration mechanisms. Tata Memorial Hospital in Mumbai coordinates South Asian enrollment for global osteosarcoma trials.
Osteosarcoma Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and targeted therapy specialization. The vendor base stratifies into three tiers: large-cap pharmaceutical conglomerates with established oncology footprints, mid-size biotech firms advancing immuno-oncology pipelines, and niche API suppliers concentrated in Asian contract manufacturing. Strategic moves center on portfolio diversification into pediatric indications and backward integration into platinum compound supply security.
Among the large-cap pharmaceutical tier, Pfizer Inc and Novartis AG occupy positions anchoring conventional chemotherapy availability and targeted therapy development respectively. Bristol-Myers Squibb Company exemplifies the immuno-oncology specialist archetype advancing checkpoint inhibitor programs. These three entities represent distinct strategic postures: manufacturing-scale chemotherapy supply, molecularly targeted pipeline investment, and immunotherapy clinical development acceleration.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Merck & Co. |
| Amgen Inc |
| Eli Lilly and Company |
| AstraZeneca PLC |
| Roche |
| Others |
Value Chain & Pricing Dynamics
Family-owned Indian API producers operating in Hyderabad and Ahmedabad anchor platinum-based chemotherapy supply, translating concentrated ownership into disciplined contract pricing that resists spot-market volatility even when hospital procurement departments press for quarterly discounts.
Pricing Analysis
Service bundling separates contract manufacturers offering validated stability data and regulatory documentation from commodity suppliers selling bare API. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification tier and FDA establishment inspection history. Pricing pressure stems from German hospital procurement departments consolidating oncology drug purchasing through multi-year tender mechanisms. Pediatric oncology centers in the United States demonstrate lowest price sensitivity due to orphan drug reimbursement guarantees, while Indian contract manufacturers face acute margin compression from CDSCO cost-control directives.
Supply Chain Analysis
cGMP certification and FDA pre-approval inspection status gate entry into supply chains serving neoadjuvant cisplatin-doxorubicin protocols. Active pharmaceutical ingredient manufacturing concentrates in Jiangsu and Zhejiang provinces of China, with secondary capacity in Hyderabad and Ahmedabad, India. Platinum salts and anthracycline fermentation feedstocks draw from concentrated mining and bioprocessing operations. Single-source vulnerability pervades the cisplatin intermediate market, where one Jiangsu facility supplies multiple formulation specialists. Distribution runs through pharmaceutical distributors holding cold-chain licenses for cytotoxic agents, with hospital procurement departments in Germany and Japan consolidating direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Osteosarcoma therapeutics constitute a consolidation play where API supply concentration and EMA pediatric investigation plan compliance burdens force sub-scale developers toward acquisition or alliance.
For Market Incumbents: Hedge against cisplatin supply disruption through backward integration into platinum salt refining or captive contracts with Jiangsu producers holding FDA establishment registration. Secure neoadjuvant protocol market share by embedding liquid biopsy platforms into limb-salvage surgery workflows at Memorial Sloan Kettering and Dana-Farber, creating switching costs for rival checkpoint inhibitor programs. For New Entrants and Emerging Players: Launch via Japan's PMDA Sakigake designation pathway, which offers priority review for pediatric bone malignancy innovations with limited domestic development activity. Target oral formulation development for tyrosine kinase inhibitors, where EMA pediatric investigation plans have left unmet need for age-appropriate delivery mechanisms. White-space exists in maintenance therapy protocols, where risk-stratification advances are expanding addressable populations faster than incumbent pipeline investment. For Investors and Strategic Acquirers: FDA breakthrough therapy designation for neoadjuvant checkpoint inhibitor protocols is the leading indicator that immuno-oncology valuation multiples will compress conventional chemotherapy assets. Over the medium-term horizon, acquisition targets should display validated pediatric pharmacokinetic data packages that satisfy EMA extrapolation restrictions without requiring juvenile toxicology study repetition. The signal to monitor is consolidation among Chinese API contract manufacturers, which would trigger supply security premiums for Western formulation specialists with qualified secondary sources.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Neoadjuvant checkpoint inhibitor protocols at Dana-Farber compress regulatory timelines through measurable response endpoints. |
| Regulatory Approval Pathway | PMDA Sakigake designation in Japan accelerates pediatric bone malignancy innovations with limited domestic competition. |
| Manufacturing Scale-Up | Backward integration into platinum salt supply secures cisplatin-doxorubicin combination availability against Jiangsu concentration risk. |
| Pipeline Diversification | Targeted therapy investment in mTOR pathway modulators addresses molecular subtypes beyond conventional chemotherapy reach. |
| Strategic Partnership | European Network for Cancer Research in Children and Adolescents pools multinational trial infrastructure, reducing per-site activation costs. |
Study Parameters
Independent corroboration across drug development executives at Bristol-Myers Squibb and Novartis, regulatory affairs leads navigating FDA orphan drug pathways, hospital procurement managers at German sarcoma reference networks, and payer access specialists at US pediatric oncology centers underwrites the qualitative findings. Secondary validation drew from FDA orphan drug designations, EMA pediatric investigation plan submissions, ClinicalTrials.gov osteosarcoma protocol registrations, and formulary databases maintained by German hospital purchasing consortia. Bottom-up patient-flow modeling and top-down therapeutic class expenditure analysis were cross-referenced for triangulation.
Comparable historical periods anchored the forecast window to pre-pandemic enrollment baselines and post-acceleration pathway implementation trajectories. The analytical framework segmented by treatment stage, therapeutic modality, administration route, and regional regulatory cluster across the analysis window. CAGRs were derived from patient incidence projections, protocol penetration curves, and per-patient drug intensity assumptions. Forecast inputs included biomarker stratification adoption rates and centralized tender mechanism expansion in Germany and Japan.
Regulatory pathway delays, API supply disruption from Chinese manufacturing inspections, and biomarker assay validation failures are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about pediatric investigation plan compliance timelines and checkpoint inhibitor response rates in bone sarcoma histologies. A model refresh is warranted upon material change in FDA breakthrough therapy designation frequency or EMA pediatric regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Gallbladder Cancer Treatment Market
Oncology
Metastases Spinal Tumor Market
Oncology
Oncology Devices Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Metastatic Breast Cancer Market
Oncology
Cancer Cachexia Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Cancer Supportive Care Products Market
Oncology
Internal Radiation Therapy Market
Oncology
AI in Oncology Market
Oncology
Glioblastoma Market