
 Tumor Embolization Market | 2026-2036
Tumor Embolization Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Embolization Market Analytics
The end-use mix for tumor embolization is broadening as ambulatory surgery centers and outpatient clinics build dedicated interventional radiology suites alongside traditional hospital oncology departments. Boston Scientific Corporation leverages its integrated embolic agent and delivery system portfolio to capture procedural pull-through across multiple therapy areas. Medtronic plc anchors its position through deep catheter and navigation technology expertise that sustains physician loyalty in complex tumor interventions. Terumo Corporation competes aggressively in Asia-Pacific markets through localized manufacturing and tailored embolic agent formulations.
Tumor embolization encompasses the percutaneous delivery of occlusive materials—polyvinyl alcohol particles, calibrated microspheres, or liquid embolics—via catheter-based systems to selectively devascularize neoplastic tissue while preserving surrounding parenchyma. Embolic agents represent the largest revenue pool given recurring consumable demand and continuous formulation advances in drug-eluting and radiopaque variants. Support catheters and delivery systems command premium pricing where trackability and distal navigation capabilities determine procedural success in tortuous vasculature. Liver cancer applications lead therapy area segmentation due to established transarterial chemoembolization protocols, while uterine fibroid embolization registers the fastest expansion as gynecologists and interventional radiologists collaborate on minimally invasive alternatives to hysterectomy.
FDA premarket notification pathways and EMA medical device regulation compliance requirements shape product development timelines and clinical evidence standards for embolic device commercialization. ISO 13485 quality management certification and country-specific sterilization validation protocols create additional barriers for new entrants seeking hospital procurement approval. Stakeholders must monitor evolving CMS and national payer coverage determinations for outpatient embolization procedures, as site-of-service reimbursement differentials will directly influence capital allocation between hospital-based and freestanding interventional radiology settings.
Market Dynamics
The migration of tumor embolization procedures from inpatient hospital settings to ambulatory surgery centers compresses reimbursement rates while expanding procedural volume, forcing manufacturers to reconfigure pricing architectures and service models around lower-acuity care delivery sites.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review timelines for novel embolic agents accelerate commercialization pathways, compressing development-to-revenue cycles from five years to under three for qualifying innovations.
- Drug-Eluting Microsphere Technology:Sustained local chemotherapy release improves tumor response rates versus conventional embolics, driving protocol adoption at comprehensive cancer centers in the United States and Germany.
- Ambulatory Surgery Center Expansion:Dedicated interventional radiology suites at freestanding outpatient facilities widen addressable procedure volume for uterine fibroid and liver cancer interventions.
Market Restraints
- Platinum-Iridium Alloy Cost Volatility:Microcatheter construction depends on precious metal marker bands, exposing manufacturers to commodity price swings that compress gross margins on delivery systems.
- Single-Source Calibration Bead Supply:Precision microsphere manufacturing concentrates among three European contract manufacturers, creating vulnerability to geopolitical trade friction or facility disruption.
- Transarterial Radioembolization Substitution:Yttrium-90 glass microsphere therapy competes directly with conventional chemoembolization for hepatocellular carcinoma, siphoning high-value liver cancer cases in tertiary referral networks.
Strategic Opportunities
- India Interventional Radiology Infrastructure:Underpenetrated oncology catheterization capacity in tier-two cities creates first-mover advantage for localized embolic agent distribution partnerships.
- EU Medical Device Regulation (MDR) Compliance Services:Post-market surveillance and clinical evidence requirements generate recurring revenue streams for contract research organizations supporting legacy device recertification.
- Artificial Intelligence-Fluoroscopy Integration:Real-time vessel mapping algorithms combined with robotic catheter navigation reduce radiation exposure and procedure time, opening premium positioning for integrated system vendors.
Industry Challenges
- Interventional Radiologist Training Pipeline:Fellowship program capacity constraints limit qualified operator supply, creating procedural bottlenecks at expanding ambulatory sites despite installed equipment availability.
- ISO 13485 Sterilization Validation Timelines:Ethylene oxide residue testing and packaging integrity verification extend new product introduction cycles by eight to fourteen months.
- Legacy Hospital Information System Integration:Proprietary imaging archive formats and departmental workflow software impede seamless adoption of cloud-based procedure documentation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Embolization Market |
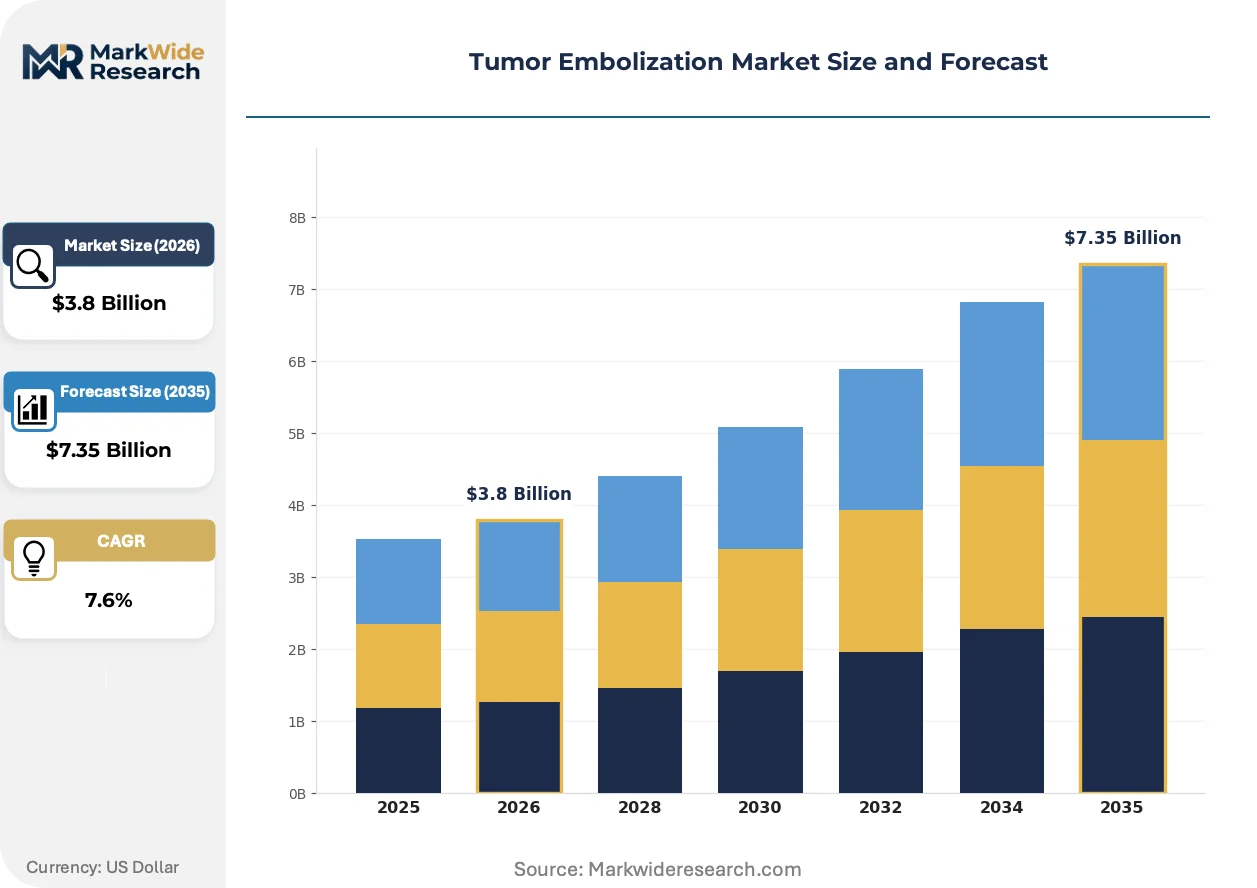
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embolic Agents, Support Catheters, Delivery Systems, Imaging Devices Therapy Area: Liver Cancer, Kidney Tumors, Uterine Fibroids, Prostate Tumors End User: Hospitals, Outpatient Clinics, Cancer Treatment Centers, Ambulatory Surgery Centers Application: Palliative Care, Tumor Treatment, Diagnostic Procedures, Interventional Radiology |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Stryker Corporation, Terumo Corporation, Johnson & Johnson, Cook Medical, Sirtex Medical, Merit Medical Systems, Penumbra, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Embolization Market Evolving Landscape
Embolic agent formulation science and procedural navigation technology are converging to enable more distal vessel occlusion with reduced non-target embolization risk, compressing the gap between therapeutic efficacy and safety margins.
Radiopaque calibrated microspheres loaded with doxorubicin or irinotecan enable real-time fluoroscopic visualization during delivery, eliminating the uncertainty of non-contrast embolic distribution. Academic medical centers in Japan and the United States are adopting these agents for segmental liver perfusion mapping. This visualization capability is expanding into personalized dosing protocols based on tumor vascularity assessment.
EMA's 2021 Medical Device Regulation recast imposes stricter clinical evidence requirements for Class III implantable devices, including permanent embolic agents. Manufacturers must now submit post-market surveillance data and biocompatibility testing under ISO 10993-18 chemical characterization standards. European notified bodies have extended review timelines, compressing product launch windows and forcing portfolio prioritization toward highest-revenue indications.
Hospital procurement committees are consolidating embolic agent purchasing through single-source agreements tied to catheter system volume commitments, displacing the previous multi-vendor spot-buying model. Interventional radiology departments at integrated delivery networks in the United States now negotiate two-to-three year sole-source contracts. This concentration trend is most visible in Texas and Florida health systems where ambulatory expansion has outpaced independent practice growth.
Tumor Embolization Market Segmentation
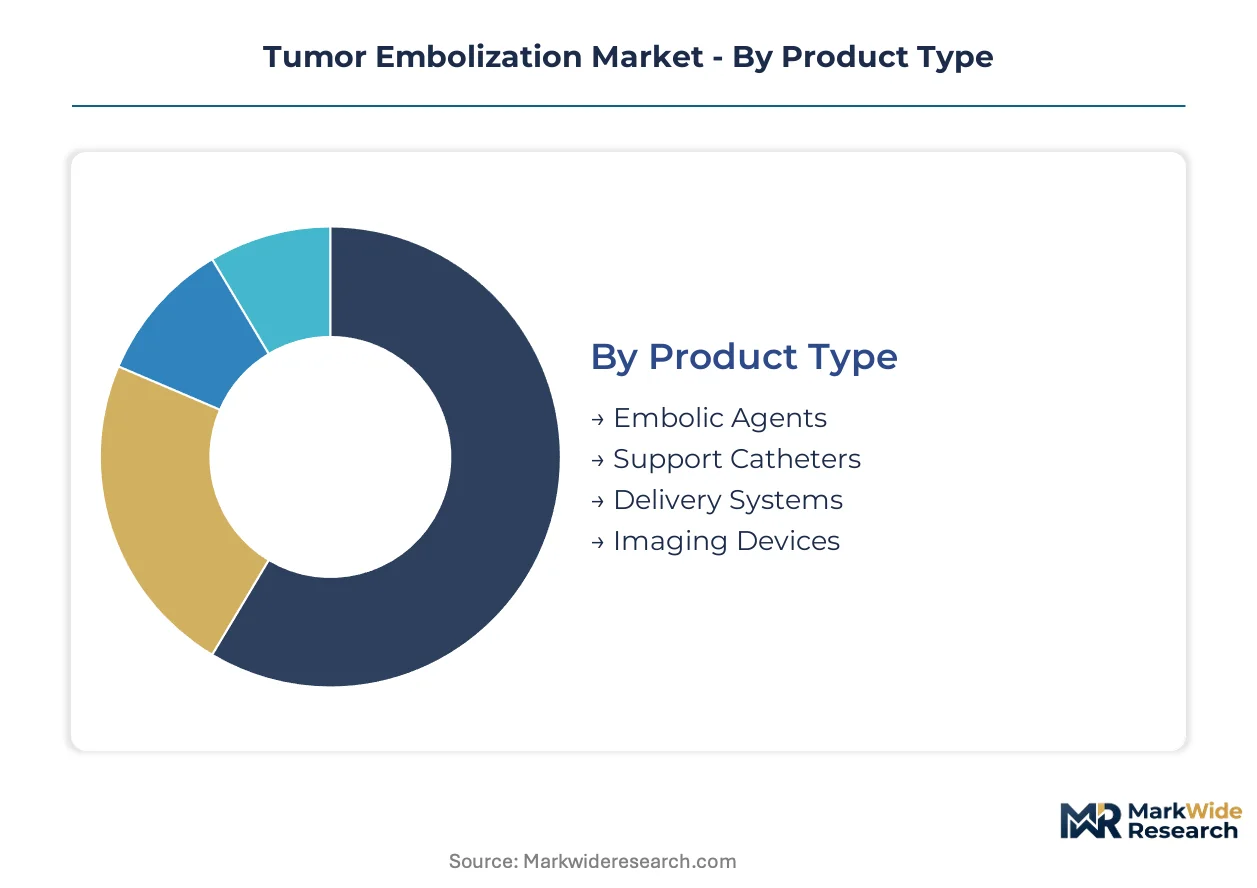
Segmentation in tumor embolization reveals distinct procurement patterns between high-volume consumable categories and capital-intensive navigation equipment. Manufacturers configure pricing architectures and service models differently across these splits to capture recurring revenue versus one-time system sales.
Product Type:
Volume-driven consumables dominate procedure economics while premium navigation systems anchor capital budgets.
- Embolic Agents:Polyvinyl alcohol particles, calibrated microspheres, and liquid embolics constitute the recurring revenue foundation. Demand concentrates in United States comprehensive cancer centers and German university hospitals where drug-eluting formulations command protocol preference.
- Support Catheters:Variable-stiffness delivery platforms with hydrophilic coatings enable distal vessel access. Japanese interventional radiology departments prioritize trackability specifications for tortuous hepatic arterial anatomy.
- Delivery Systems:Microcatheter and guidewire combinations with radiopaque marker bands.
- Imaging Devices:C-arm fluoroscopy and cone-beam CT integration for real-time procedural guidance.
Mature deployment sits with Embolic Agents. Newer deployment is concentrated in Delivery Systems.
Therapy Area:
Application maturity varies sharply between established oncology protocols and emerging gynecological interventions.
- Liver Cancer:Transarterial chemoembolization represents the most established reimbursement pathway. United States Medicare coverage determinations and German statutory health insurance recognition sustain procedural volume in tertiary referral networks.
- Uterine Fibroids:Minimally invasive alternatives to hysterectomy are expanding fastest. United States ambulatory surgery centers and Japanese women's health clinics drive adoption through gynecologist-interventional radiologist collaboration models.
- Kidney Tumors:Selective arterial embolization for renal cell carcinoma and angiomyolipoma.
- Prostate Tumors:Emerging prostatic artery embolization for benign prostatic hyperplasia.
Established protocols anchor Liver Cancer. Uterine Fibroids are climbing the fastest.
End User:
Site-of-service migration is fragmenting purchasing authority between integrated hospital systems and independent outpatient operators.
- Hospitals:Inpatient oncology departments retain complex case referrals and salvage procedures. German maximum-care hospitals and Japanese national university hospitals maintain embedded interventional radiology residency programs.
- Ambulatory Surgery Centers:Freestanding facilities capture elective uterine fibroid and selected liver cancer cases. United States certificate-of-need states with ambulatory waiver provisions see fastest facility licensing.
- Outpatient Clinics:Office-based interventional radiology suites in mixed-specialty settings.
- Cancer Treatment Centers:Dedicated oncology campuses with comprehensive embolization protocols.
Capital concentration remains with Hospitals. Volume expansion is shifting toward Ambulatory Surgery Centers.
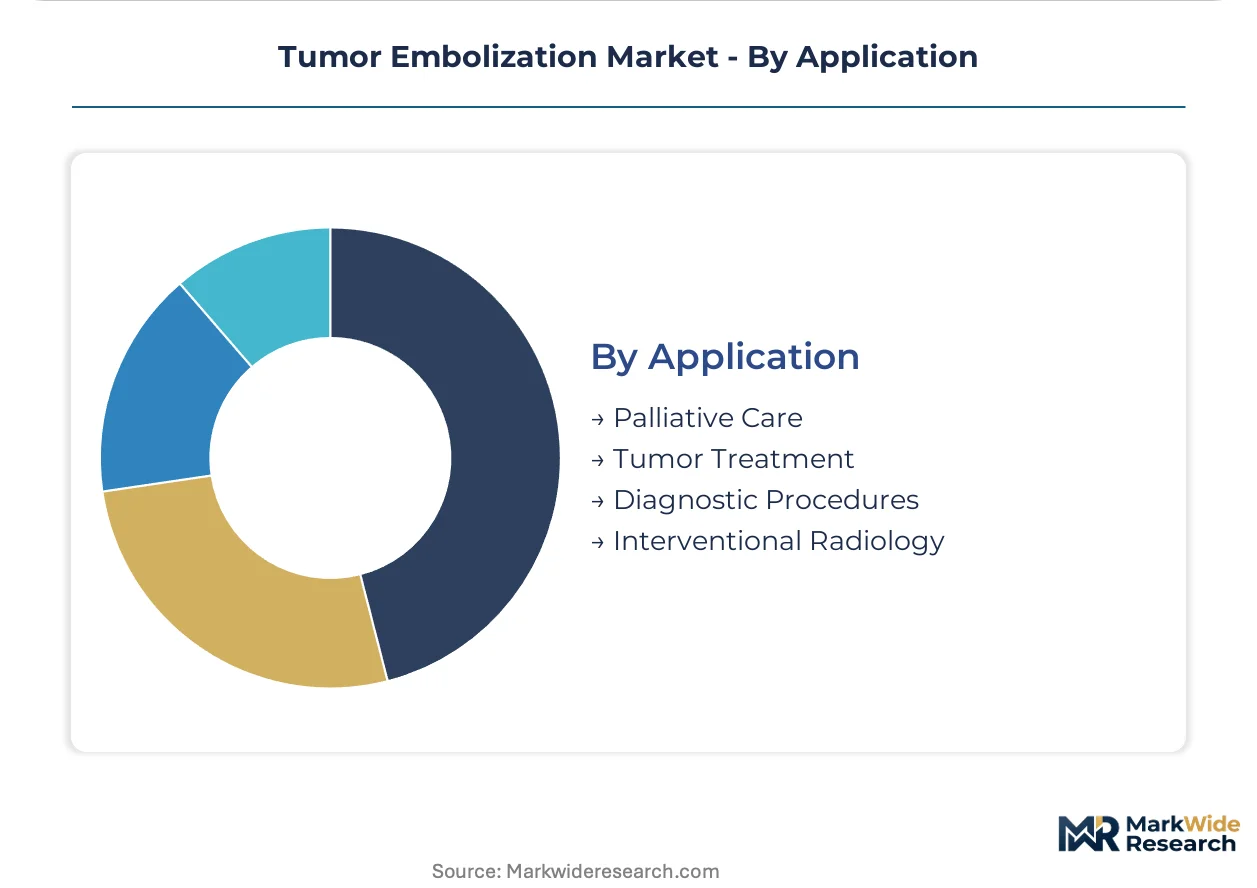
Application:
Clinical intent separates curative-intent tumor devascularization from symptom-management procedures with distinct reimbursement profiles.
- Tumor Treatment:Curative or cytoreductive embolization with measurable oncologic endpoints. United States National Comprehensive Cancer Network guidelines and German S3 guideline recognition determine protocol reimbursement eligibility.
- Palliative Care:Symptom control for unresectable malignancies with quality-of-life endpoints. Japanese hospice-interventional radiology integration programs and United States Medicare hospice carve-out provisions shape access.
- Interventional Radiology:Training and research applications with protocol development focus.
- Diagnostic Procedures:Pre-operative mapping and vascular territory assessment.
Revenue concentration aligns with Tumor Treatment. Palliative Care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of embolic agents concentrates in European contract facilities, while procedural demand concentrates in interventional radiology networks across the United States, Germany, and Japan. This production-consumption divide shapes regulatory compliance burdens and distribution economics for device suppliers.
United States
Comprehensive cancer centers in Houston, Dallas, and Miami drive procedural volume for liver cancer and uterine fibroid interventions. FDA breakthrough device designations compress review timelines for novel embolic formulations. Interventional radiology suites at ambulatory surgery centers in Texas and Florida expand fastest under state waiver provisions.
Germany
University hospitals in Munich, Heidelberg, and Berlin anchor European adoption of drug-eluting microsphere protocols. EMA accelerated assessment pathways and MDR compliance requirements shape product launch timelines for embolic device manufacturers. Statutory health insurance recognition of transarterial chemoembolization sustains reimbursement stability.
Japan
Metropolitan Tokyo and Osaka clusters concentrate interventional radiology capacity for hepatocellular carcinoma treatment. PMDA regulatory frameworks govern embolic agent approval pathways with distinct biocompatibility testing standards. Women's health clinics in Kanagawa and Aichi prefectures drive uterine fibroid embolization volume through gynecologist-radiologist collaboration models.
India
Tier-two cities including Pune, Hyderabad, and Chennai present underpenetrated catheterization capacity for oncology interventions. CDSCO medical device registration requirements create compliance thresholds for imported embolic agents. Localized distribution partnerships in Maharashtra and Telangana offer first-mover positioning for consumable suppliers.
United Kingdom
London and Manchester academic medical centers pilot personalized dosing protocols using radiopaque microsphere visualization. NHS England coverage determinations for outpatient embolization procedures influence site-of-service migration. Integrated care systems in the Southeast negotiate consolidated procurement agreements spanning embolic agents and delivery systems.
Tumor Embolization Market Competitive Landscape
Top-tier vendors anchor the premium consumables segment, while mid-scale specialists occupy catheter and navigation technology niches. The market exhibits tiered concentration with integrated multinationals commanding embolic agent portfolios and focused device manufacturers controlling delivery system innovations. Two strategic archetypes dominate: diversified medical technology conglomerates with interventional radiology breadth, and specialized embolization-focused developers with concentrated therapy expertise. Competitive moves center on sole-source procurement contract capture and ambulatory surgery center service model reconfiguration.
Within the diversified multinational tier, Boston Scientific Corporation, Medtronic plc, and Terumo Corporation occupy positions that exemplify contrasting geographic and technological anchoring strategies. Boston Scientific Corporation represents the integrated portfolio approach spanning embolic agents through delivery systems. Medtronic plc anchors catheter and navigation expertise that sustains physician loyalty in complex tumor interventions. Terumo Corporation exemplifies Asia-Pacific market penetration through localized manufacturing and tailored formulation development. These three entities collectively illustrate how scale, specialization, and regional focus create distinct competitive positioning vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Stryker Corporation |
| Terumo Corporation |
| Johnson & Johnson |
| Cook Medical |
| Sirtex Medical |
| Merit Medical Systems |
| Penumbra, Inc. |
| Others |
Value Network & Pricing Analysis
Platinum-iridium alloy price indices cascade through microcatheter manufacturing into three-tier pricing stratification across premium navigation systems, standard delivery platforms, and economy embolic agent formulations. This commodity pass-through mechanism concentrates pricing power with European contract manufacturers who calibrate precision microspheres, while hospital procurement committees exploit volume commitments to compress margins on consumables.
Pricing Analysis
Margin tightening in standard-tier delivery systems reflects platinum-iridium marker band cost pass-through and ambulatory surgery center purchasing consolidation. Three-tier pricing structure across premium, standard, and economy levels segments by trackability specifications and drug-eluting formulation complexity. Cost-down pressure on economy embolic agents accelerates because Indian and Southeast Asian manufacturers compete on polyvinyl alcohol particle commoditization. Ambulatory surgery centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while Japanese university hospitals accept premium positioning for distal navigation capabilities.
Supply Chain Analysis
Dual-sourcing mandates from integrated delivery networks in the United States and Germany force qualification of secondary microsphere contract manufacturers beyond the three dominant European suppliers. Manufacturing concentrates in Germany, Ireland, and Japan for precision-calibrated beads, while platinum-iridium alloy feedstock draws from South African and Russian mining operations. Single-source vulnerability concentrates in ethylene oxide sterilization capacity, where facility closures would disrupt new product introduction cycles. Distribution runs through regional specialty distributors serving hospital procurement committees and ambulatory surgery center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
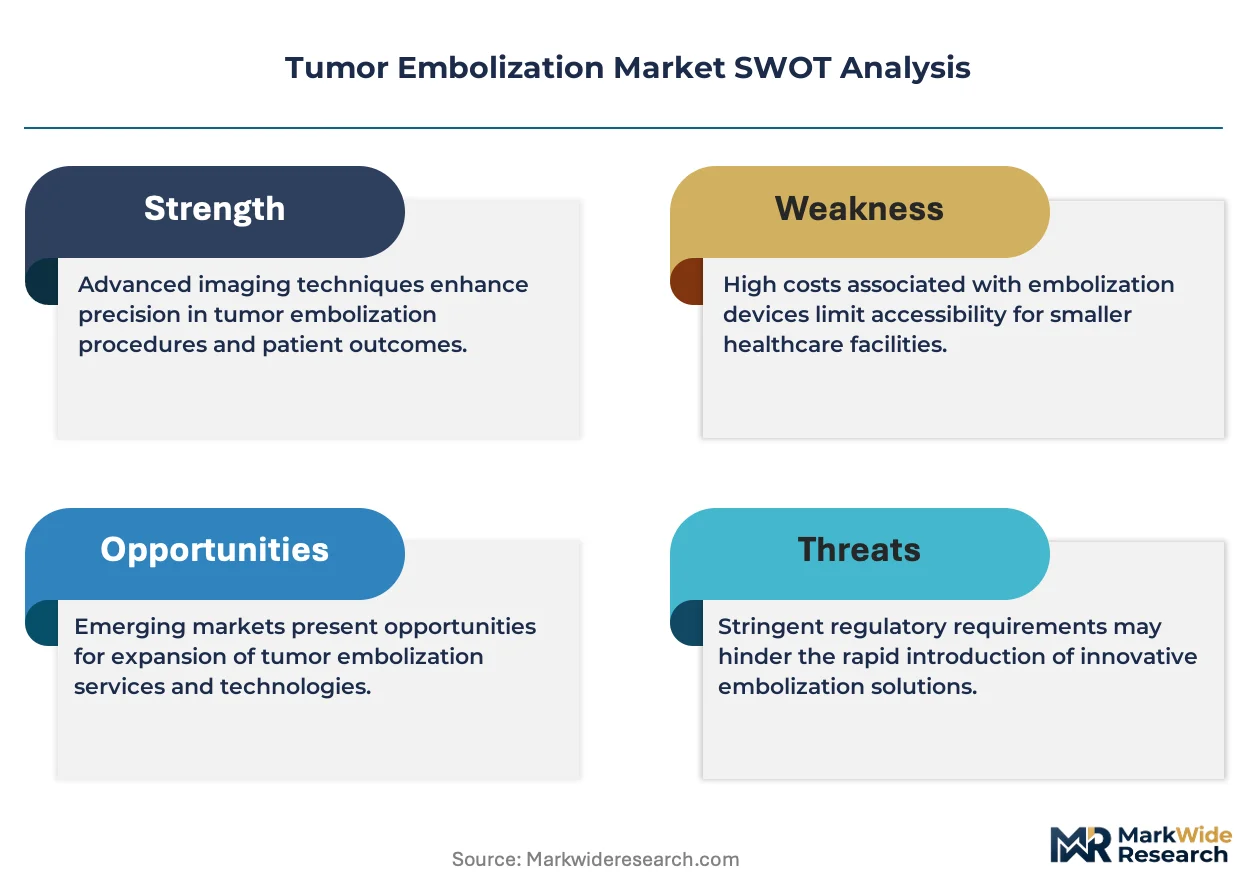
This market functions as a cost-of-compliance story where EMA Medical Device Regulation recertification timelines and FDA breakthrough device evidentiary standards erect barrier-to-entry moats favoring incumbent players with established quality management systems.
For Market Incumbents: Cement sole-source procurement relationships through multi-year catheter-embolic agent bundling contracts with Texas and Florida ambulatory surgery center networks. Lock in platinum-iridium alloy forward purchasing agreements to defend gross margins against commodity volatility. Prioritize ISO 13485 sterilization validation capacity expansion to compress new product introduction cycles threatened by ethylene oxide facility constraints.
For New Entrants and Emerging Players: Capture underpenetrated tier-two Indian cities through CDSCO-registered localized distribution partnerships bypassing European supply chain chokepoints. Target uterine fibroid embolization protocols at Japanese women's health clinics where gynecologist-radiologist collaboration models create service-based differentiation opportunities. Pursue drug-eluting microsphere co-development agreements with comprehensive cancer centers seeking personalized dosing protocols.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale catheter specialists with FDA 510(k) clearance backlogs and stranded sterilization validation assets in Germany. Long-term viability centers on ambulatory surgery center service model reconfiguration capability and artificial intelligence-fluoroscopy integration pipelines. Monitor EMA notified body review timeline compression as inflection signal for European market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses commercialization timelines for novel radiopaque microsphere formulations. |
| Hospital System Partnership | Sole-source agreements with integrated delivery networks lock out competing vendors for catheter-embolic bundles. |
| Reimbursement Strategy | CMS outpatient procedure coverage determinations dictate capital allocation between hospital and ambulatory sites. |
| Software Companion Development | Real-time vessel mapping algorithms reduce radiation exposure and enable premium system positioning. |
| CE Marking Pathway | MDR clinical evidence requirements force portfolio prioritization toward highest-revenue oncology indications. |
Research Methodology
Independent corroboration across interventional radiologists, hospital purchasing committee directors, GPO contracts managers, and embolic agent manufacturing quality leads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare coverage determinations establishes market sizing boundaries. Bottom-up procedure volume triangulation against top-down manufacturer revenue reconciliation anchors the analytical framework.
Rate-of-change decomposition across the projection horizon segments by embolic agent formulation tier, catheter navigation complexity, therapy area maturity, and end-user site-of-service migration. CAGRs derive from installed base expansion modeling, procedure volume elasticity to reimbursement shifts, and replacement cycle dynamics for navigation equipment. Drug-eluting microsphere protocol adoption curves and ambulatory surgery center licensing velocity in certificate-of-need states inform forecast sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum-iridium alloy supply disruptions, EMA notified body capacity constraints, and interventional radiologist fellowship pipeline bottlenecks. Deviation in FDA breakthrough device designation velocity or CMS outpatient reimbursement parity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Bone Cancer Treatment Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Global Veterinary Oncology Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Bone Cancer Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Liposarcoma Treatment Market
Oncology
Precision Oncology Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Cancer Supportive Care Products Market
Oncology
North America Tumor Ablation Market
Oncology
Vulvar Cancer Market
Oncology
France Radiation Oncology Market
Oncology
Tumor Ablation Market
Oncology
Colorectal Cancer Treatment Market