
 Sterile Oncology Injectable Market | 2026-2036
Sterile Oncology Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Oncology Injectable Market Analytics
USP <797> and EU GMP Annex 1 compliance upgrades is reorganizing capital deployment across sterile oncology manufacturing networks. Pfizer Inc. leverages its integrated fill-finish infrastructure to sustain supply security for high-potency cytotoxics. Roche Holding AG anchors its position through biologics specialization in oncology injectables. Eli Lilly and Company differentiates via end-to-end cold-chain control for temperature-sensitive biologic therapies.
Sterile oncology injectables are aqueous or lyophilized drug products administered parenterally for cancer treatment, requiring endotoxin levels below 0.5 EU/mL, particulate matter control per USP <788>, and validated aseptic processing or terminal sterilization. These products serve primarily as systemic cancer therapies where oral bioavailability is insufficient or immediate therapeutic plasma levels are clinically necessary. Chemotherapy agents remain the largest volume category though margin pools are migrating toward biologics and immunotherapies where manufacturing complexity creates higher barriers to entry. Intravenous delivery dominates current administration patterns while subcutaneous formulations represent the fastest-growing delivery mode as patient preference shifts toward reduced infusion center burden.
FDA aseptic processing guidance, EMA Annex 1 revisions, and ISO 14644 cleanroom classifications collectively govern facility design, environmental monitoring, and contamination control strategy for sterile oncology manufacturing. These frameworks shape demand by elevating compliance costs that favor manufacturers with scaled quality systems and disqualifying smaller facilities from high-value product segments. Stakeholders must monitor evolving regulatory expectations around closed-system drug-transfer devices and containment performance qualification as oncology workforce exposure limits tighten.
Market Dynamics
The biologics transition is compressing manufacturing economics for sterile oncology injectables, as high-complexity monoclonal antibodies and antibody-drug conjugates displace small-molecule cytotoxics in first-line protocols. This molecular shift elevates cold-chain infrastructure requirements and disqualifies legacy facilities lacking isolator-based aseptic processing capabilities.
Growth Catalysts
- FDA Aseptic Processing Guidance:Updated contamination control expectations are accelerating facility modernization investments, creating demand for closed-system isolator technology and automated vial handling systems.
- Subcutaneous formulation engineering:Patient-administered biologics reduce infusion center burden and expand addressable populations beyond hospital outpatient departments into specialty pharmacy networks.
- EMA Annex 1 Revision:Barrier technology mandates and continuous environmental monitoring requirements favor manufacturers with validated contamination control strategies, consolidating supply toward compliant facilities.
Market Restraints
- API supply concentration:High-potency cytotoxic active pharmaceutical ingredients concentrate among specialized chemical manufacturers in India and China, exposing fill-finish networks to geopolitical trade friction and customs delays.
- Isolator technology capex thresholds:Restricted access barrier systems and robotic filling platforms require capital deployment exceeding legacy cleanroom investments by multiples, excluding mid-scale contract manufacturers from high-value biologics segments.
- Workforce exposure limits:OSHA and EU occupational exposure band classifications for cytotoxic compounds tighten containment performance qualification standards, extending facility commissioning timelines.
Strategic Opportunities
- Home administration infrastructure:Subcutaneous immunotherapy formulations create white space for cold-chain logistics providers and home healthcare nursing networks in the United States and Germany.
- Continuous manufacturing adoption:Perfusion cell culture and integrated continuous bioprocessing converge with single-use technologies to compress batch cycle times and facility footprints.
- Biosimilar substitution mandates:Payer-driven reference product switching protocols in France and the United Kingdom accelerate demand for sterile injectable manufacturing capacity dedicated to oncology biosimilars.
Industry Challenges
- Containment engineering specialization:Qualified personnel for high-potency compound handling, isolator qualification, and robotic fill-finish programming remain scarce relative to facility expansion timelines.
- Legacy system integration:Paper-based batch records and disconnected manufacturing execution systems obstruct real-time release testing and continuous process verification adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Oncology Injectable Market |
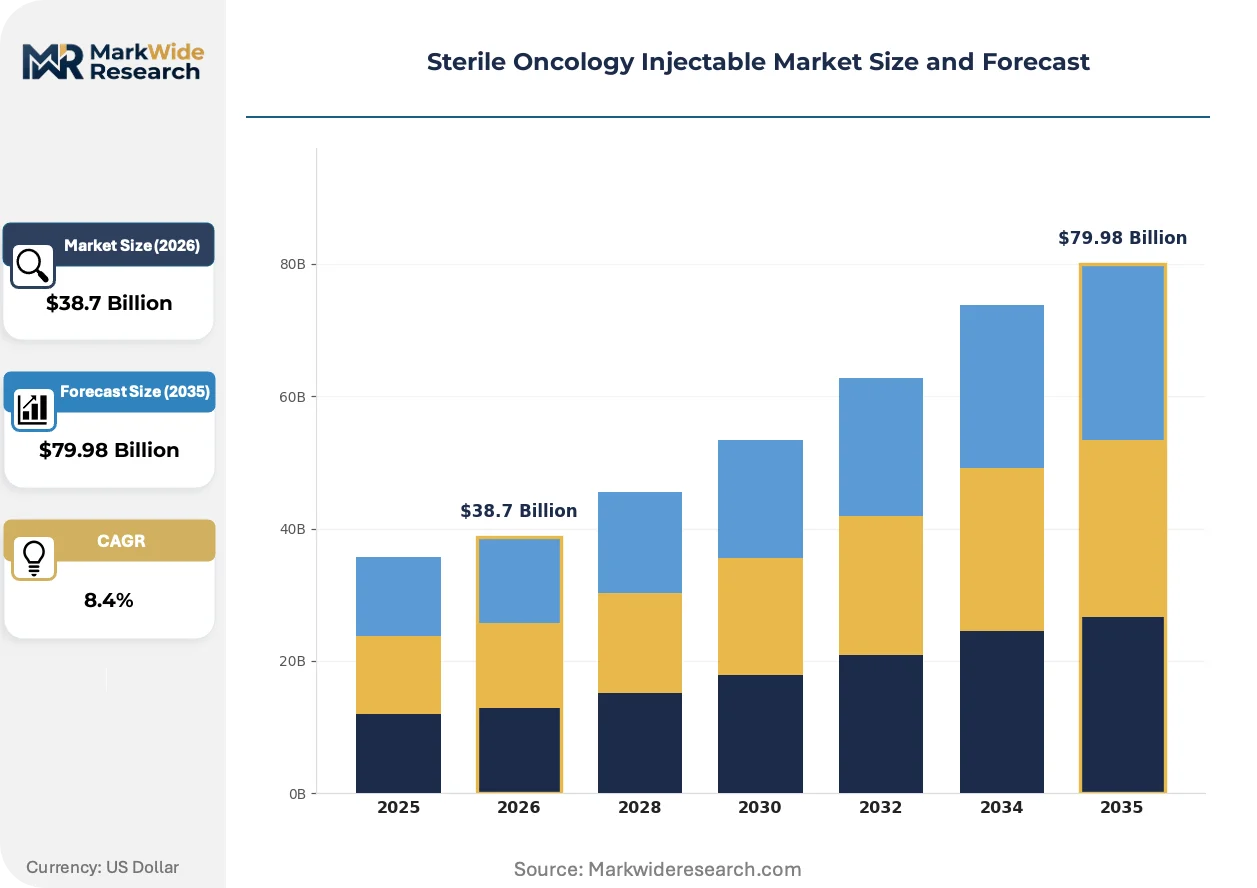
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Biologics, Targeted Therapies, Immunotherapies Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-arterial End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Packaging Type: Vials, Prefilled Syringes, Ampoules, Multi-Dose Containers |
| Companies Covered | Pfizer Inc., Roche Holding AG, Eli Lilly and Company, Novartis AG, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd, Sandoz International GmbH, Hikma Pharmaceuticals PLC, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Oncology Injectable Market Evolving Landscape
Bioprocessing intensification and delivery mode diversification are compressing the gap between upstream production and patient administration. These forces reshape facility design priorities, regulatory submission strategies, and competitive positioning across the sterile oncology value chain.
Single-use bioreactor technology is miniaturizing stainless steel infrastructure requirements while expanding production flexibility. Contract manufacturers in Singapore and Switzerland deploy 2,000-liter disposable systems for clinical-stage biologics, enabling rapid product changeover without CIP/SIP validation burden. This configuration compresses capital deployment timelines and permits multi-product facilities that stainless steel architectures cannot economically support.
EMA's Annex 1 revision mandates barrier technology and continuous viable particle monitoring for all Grade A operations, effective August 2023 with staggered compliance deadlines. Sterile oncology manufacturers face facility redesign costs and extended shutdowns for isolator retrofit installation. German and Swiss facilities lead adaptation pace, while southern European contract manufacturers lag in barrier technology procurement.
Hospital outpatient departments consolidate purchasing through specialty pharmacy benefit managers and group purchasing organizations, compressing price negotiation cycles and unbundling clinical service fees from drug acquisition costs. This procurement restructuring concentrates volume among integrated delivery networks in the United States and hospital pharmacy centralization programs in England, displacing traditional wholesale distribution relationships.
Sterile Oncology Injectable Market Segmentation
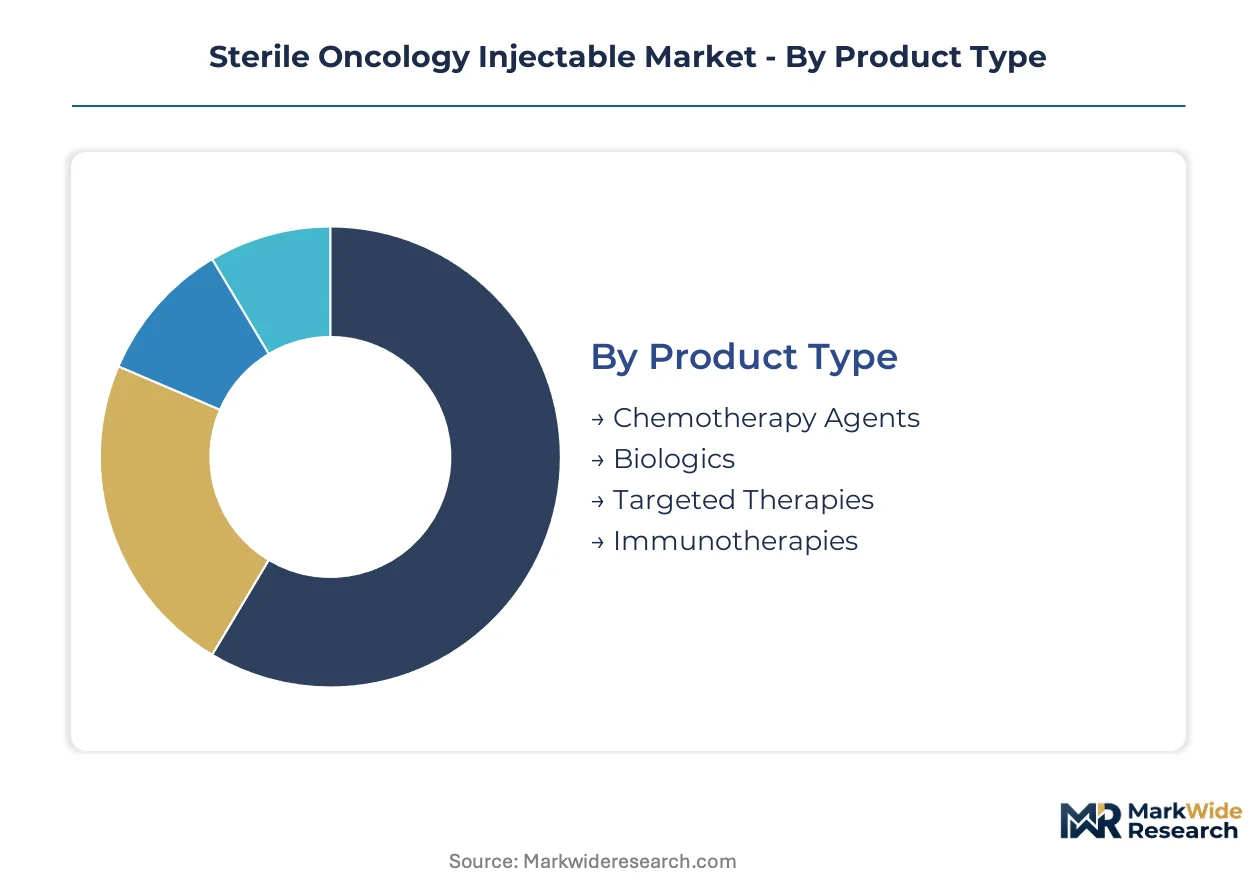
Sterile oncology injectables fragment across molecular class, administration route, and care setting with distinct margin profiles. Product type and delivery mode determine manufacturing complexity and cold-chain infrastructure requirements. Packaging format selection increasingly shapes patient safety outcomes and pharmacy workflow efficiency.
Product Type:
Margin pools concentrate in biologics and immunotherapies where manufacturing complexity erects entry barriers and sustains price premiums.
- Chemotherapy Agents:Small-molecule cytotoxic compounds requiring terminal sterilization or validated aseptic processing with endotoxin limits below 0.5 EU/mL. Demand concentrates in hospital outpatient departments across the United States and Germany as first-line protocols, though biosimilar competition compresses price realization.
- Biologics:Monoclonal antibodies and antibody-drug conjugates manufactured through mammalian cell culture with stringent cold-chain requirements from fill-finish through administration. Oncology clinics in Switzerland and Singapore anchor demand for these high-complexity products where isolator-based processing capabilities filter supplier pools.
- Targeted Therapies:Tyrosine kinase inhibitors and signal pathway modulators formulated for parenteral delivery when oral bioavailability proves insufficient.
- Immunotherapies:Checkpoint inhibitors and CAR-T cell therapies requiring cryogenic or controlled-temperature logistics throughout distribution.
The dominant share belongs to Chemotherapy Agents, while Biologics is closing the gap fastest.
Delivery Mode:
Volume distribution skews toward infusion-center administration, though patient preference and formulary design are redistributing share across routes.
- Intravenous:Direct vascular administration enabling immediate therapeutic plasma levels with established nursing protocols and reimbursement pathways. Hospital oncology departments in the United States and England process the majority of volume through outpatient infusion centers where specialty pharmacy benefit managers consolidate purchasing.
- Subcutaneous:Patient-administered or home-health-delivered injections reducing infusion center burden and enabling community-based care models. German and French markets show steepest expansion trajectory as biosimilar formulations and patient convenience drive formulary placement.
- Intramuscular:Depot formulations and sustained-release injectables for hormonal and supportive oncology therapies.
- Intra-arterial:Regional chemotherapy delivery for hepatocellular carcinoma and limb perfusion procedures in specialized interventional radiology settings.
Intravenous retains the largest volume position, while Subcutaneous gains share most rapidly through patient-administered biologics expansion.
End User:
Procurement concentration and reimbursement structure determine channel profitability, with integrated delivery networks extracting price concessions unavailable to fragmented purchasers.
- Hospitals:Acute-care and outpatient oncology departments with centralized pharmacy operations and group purchasing organization affiliation. United States hospital systems leverage specialty pharmacy networks to capture 340B pricing advantages and unbundle clinical fees from drug acquisition.
- Oncology Clinics:Physician-owned or hospital-affiliated infusion centers specializing in chemotherapy and biologic administration. Swiss and Belgian clinic networks concentrate volume for high-complexity therapies where nursing expertise and cold-chain infrastructure differentiate service quality.
- Research Institutions:Academic medical centers and phase I-III clinical trial sites managing investigational sterile injectables under FDA and EMA IND/CTA frameworks.
- Homecare:Home health nursing services and specialty pharmacy direct-to-patient delivery for subcutaneous immunotherapies and supportive care agents.
Hospitals command the dominant procurement volume, though Homecare is expanding most quickly through subcutaneous formulation proliferation.
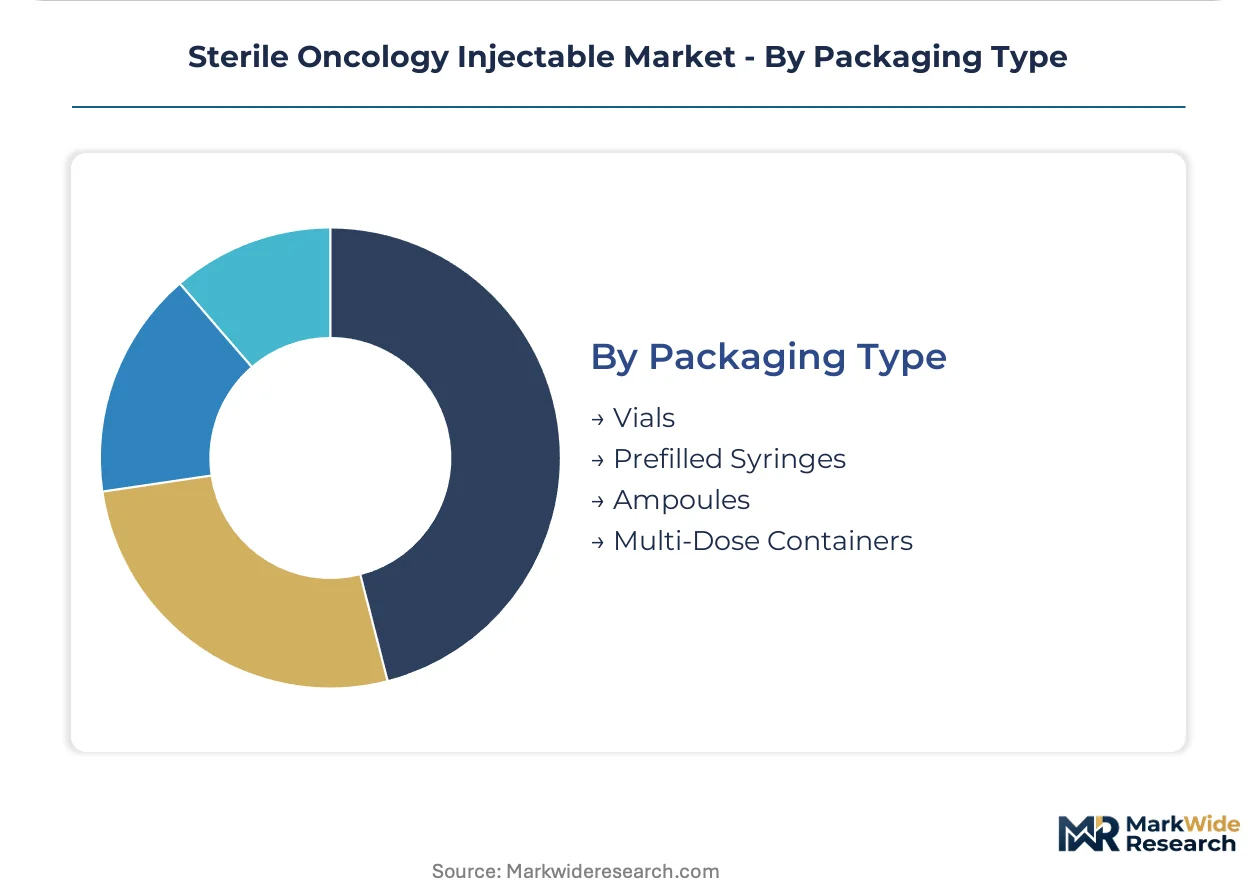
Packaging Type:
Container selection balances sterility assurance, dosing accuracy, and pharmacy operational efficiency with distinct cost structures across formats.
- Vials:Multi-dose glass or polymer containers requiring reconstitution and transfer to infusion bags, dominant for chemotherapy agents and clinical-trial materials. German and Indian contract manufacturers supply vial-based fill-finish at scale, though EMA Annex 1 barrier technology mandates elevate capital requirements.
- Prefilled Syringes:Ready-to-administer single-unit presentations reducing dosing errors and pharmacy compounding burden. United States specialty pharmacies and homecare networks drive demand for biologic prefilled presentations where patient self-administration protocols apply.
- Ampoules:Single-dose glass containers for emergency and perioperative oncology indications requiring immediate availability.
- Multi-Dose Containers:Bulk presentations for high-volume chemotherapy agents with validated antimicrobial preservation systems.
Vials maintain the largest installed base, while Prefilled Syringes climbs fastest on patient safety and convenience prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit the lowest price elasticity, absorbing premium biologics through integrated hospital networks, while Indian and Chinese procurement channels remain acutely sensitive to cost differentials in cytotoxic generics.
United States
Hospital outpatient departments and specialty pharmacy networks concentrate demand for high-potency cytotoxics and temperature-sensitive biologics. FDA aseptic processing guidance and 340B pricing programs reshape procurement patterns across integrated delivery networks. The Boston-Cambridge corridor anchors biologics manufacturing expansion with isolator-based fill-finish investments.
Germany
Oncology clinics and hospital central pharmacies drive prefilled syringe adoption for subcutaneous immunotherapies. EMA Annex 1 barrier technology mandates accelerate facility modernization in Baden-Württemberg and Bavaria. The Rhine-Main biopharma cluster concentrates contract manufacturing investments for clinical-stage biologics.
Switzerland
Swissmedic oversight and premium reimbursement structures sustain demand for high-complexity antibody-drug conjugates. Basel and Zürich anchor biologics fill-finish specialization with isolator technology deployment. The country's occupational exposure band classifications exceed EU minimums, tightening containment engineering standards.
India
Domestic hospital procurement and export-oriented contract manufacturing shape demand for vial-based cytotoxic generics. CDSCO manufacturing license requirements and state-level pharmacy council regulations govern facility operations. Hyderabad and Ahmedabad concentrate API-to-finish integration for high-potency oncology compounds.
China
NMPA marketing authorization reforms and volume-based procurement compress price realization for established chemotherapy agents. Shanghai and Suzhou biopharma parks attract multinational fill-finish partnerships for clinical-stage biologics. The Yangtze River Delta leads barrier technology adoption among domestic manufacturers.
Sterile Oncology Injectable Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sterile oncology injectable value chain. The market structures around three tiers: multinational innovators with integrated biologics capabilities, mid-scale specialists in high-potency cytotoxics, and regional generic manufacturers serving price-sensitive procurement channels. Dominant competitive moves include isolator technology licensing partnerships and backward integration into API supply.
Among the integrated multinational tier, Pfizer Inc. and Roche Holding AG exemplify divergent strategic positions—Pfizer leveraging legacy fill-finish infrastructure for cytotoxic supply security, Roche anchoring biologics specialization through mammalian cell culture depth. Eli Lilly and Company occupies a distinct position on cold-chain control and patient-administered formulation development. These three represent the primary competitive anchors shaping facility investment patterns and regulatory submission strategies across the sterile oncology landscape.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Roche Holding AG |
| Eli Lilly and Company |
| Novartis AG |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd |
| Sandoz International GmbH |
| Hikma Pharmaceuticals PLC |
| Baxter International Inc. |
| Others |
Value Network & Pricing Analysis
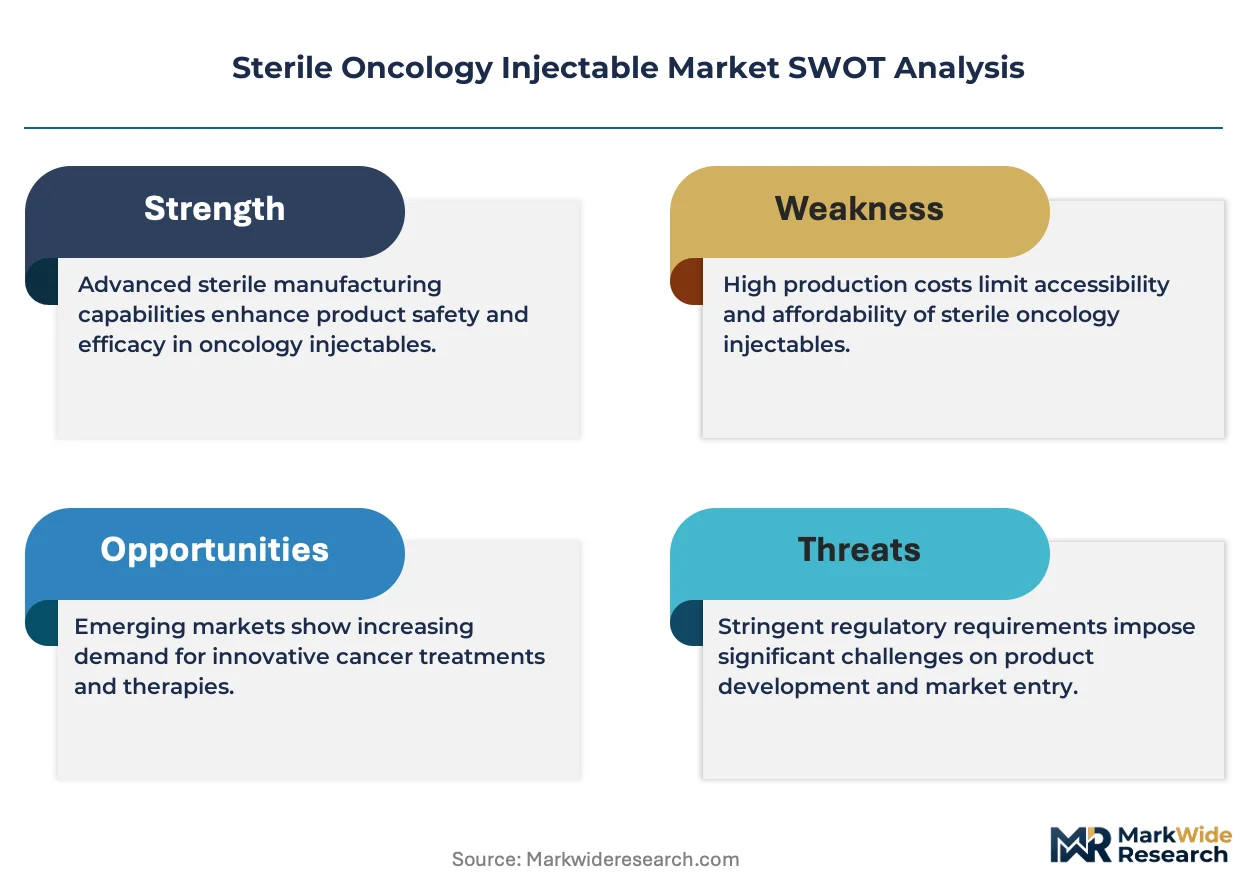
Isolator technology capex thresholds reshape competitive economics across sterile oncology manufacturing, concentrating supply among scaled operators while compressing margin floors for legacy cleanroom facilities. EMA Annex 1 barrier mandates and FDA aseptic processing guidance elevate fixed-cost structures that filter supplier pools toward compliant networks in Switzerland, Germany, and the United States.
Pricing Analysis
FDA aseptic processing guidance dictates the pricing tier structure across sterile oncology injectables, separating isolator-certified biologics manufacturers from conventional cleanroom operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and cold-chain infrastructure depth. Cost compression in cytotoxic generics intensifies because volume-based procurement in China and India accelerates biosimilar substitution. Hospital procurement through 340B programs and group purchasing organizations exhibits lowest price sensitivity, while Indian domestic hospital channels remain most elastic.
Supply Chain Analysis
Just-in-time inventory preferences dominate biologics distribution, though high-potency cytotoxics require strategic stockpiling against API supply disruption. Active pharmaceutical ingredient production concentrates in India and China, with fill-finish capabilities clustering in Switzerland, Germany, and Singapore. Supply chain risk centers on single-source vulnerability for specialized chemical manufacturers in Hyderabad and Ahmedabad. Distribution runs through hospital outpatient departments, specialty pharmacy networks, and integrated delivery networks in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterile oncology injectable market tracks a cyclical recovery anchored to biologics pipeline maturation and facility modernization capex cycles. EMA Annex 1 compliance deadlines and FDA guidance updates compress supply expansion timelines, creating cyclical capacity tightness.
For Market Incumbents: Shield market position through isolator technology licensing partnerships and backward integration into high-potency API supply. Pfizer's integrated fill-finish infrastructure exemplifies defensive positioning against biosimilar margin erosion. Capacity addition in Singapore and Switzerland captures premium biologics demand while regulatory compliance filters competitor entry. For New Entrants and Emerging Players: Differentiate on subcutaneous formulation engineering and home administration cold-chain logistics. German and French markets present most penetrable geographies for patient-administered biologics expansion. Direct-to-patient specialty pharmacy partnerships offer the clearest go-to-market angle outside hospital consolidation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with validated isolator capabilities and multi-product flexibility. Long-term viability over the coming decade rests on barrier technology deployment pace and continuous bioprocessing adoption. Watch EMA Annex 1 compliance deadline extensions as inflection signal for facility valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | EMA Annex 1 mandates barrier systems for Grade A operations, filtering supplier pools toward compliant facilities in Germany and Switzerland. |
| Subcutaneous Formulation Development | Patient-administered biologics reduce infusion center burden and expand addressable populations through specialty pharmacy networks. |
| Continuous Manufacturing Adoption | Perfusion cell culture and single-use technologies compress batch cycle times for clinical-stage biologics in Singapore. |
| Backward API Integration | Captive supply of high-potency cytotoxic compounds mitigates geopolitical exposure to Indian and Chinese chemical manufacturers. |
| Homecare Cold-Chain Expansion | Direct-to-patient logistics networks in the United States and Germany capture subcutaneous immunotherapy administration volume. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in this study. Conversations with fill-finish operations directors, regulatory affairs leads, hospital pharmacy procurement managers, and specialty pharmacy network executives informed facility investment patterns. Secondary validation drew from FDA aseptic processing guidance documents, EMA Annex 1 revision texts, Swissmedic inspection reports, and CDSCO manufacturing license databases. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level projections.
Sensitivity analysis around regulatory compliance timelines and biologics pipeline maturation rates tested forecast robustness across the projection horizon. Segmentation dimensions modeled include molecular class, delivery mode, packaging format, and care setting, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from installed capacity expansion schedules, patent expiry profiles, and formulary placement trajectories. Forecast inputs incorporated isolator technology adoption curves and cold-chain infrastructure deployment rates.
Material uncertainties — regulatory deadline extensions, API supply disruptions, and biosimilar substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about EMA Annex 1 staggered compliance and FDA inspection prioritization. Revision becomes warranted when barrier technology procurement backlogs or workforce exposure limit tightening cross thresholds that materially extend facility commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Thymus Cancer Market
Oncology
Interventional Oncology Ablation Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Angiosarcomas Treatment Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Cancer Cachexia Market
Oncology
Throat Cancer Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Europe Radiotherapy Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Cancer API Market
Oncology
Esophageal Cancer Market
Oncology
Immuno-Oncology Market