
 Global Skin Cancer Diagnostics and Therapeutics Market | 2026-2036
Global Skin Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skin Cancer Diagnostics and Therapeutics Market Foresight
Modular diagnostic-therapeutic bundling is consolidating purchasing decisions across hospital systems and specialty clinic networks. F. Hoffmann-La Roche Ltd leverages its dual diagnostics-pharmaceutical footprint to anchor integrated melanoma care pathways. Bristol-Myers Squibb Company competes through checkpoint inhibitor specialization that sustains high R&D intensity in immuno-oncology. Thermo Fisher Scientific Inc. differentiates its position with molecular diagnostic platforms that control companion testing workflows.
Skin cancer diagnostics and therapeutics encompasses imaging, tissue analysis, surgical intervention, and systemic pharmacologic modalities directed at malignant cutaneous neoplasms, with immunohistochemistry and next-generation sequencing serving as core pathological classification tools. The field addresses rising incidence of melanoma and non-melanoma lesions through stage-stratified intervention protocols. Immunotherapy drugs command substantial margin pools as PD-1 and CTLA-4 inhibitors reshape advanced melanoma standards, while diagnostic imaging systems face price compression amid platform commoditization. Mohs surgery tools occupy a mature niche with steady replacement demand tied to dermatologic surgery volume.
FDA premarket approval requirements and EMA centralized assessment pathways shape clinical evidence thresholds for novel diagnostic claims and therapeutic indications. ISO 13485 quality management standards govern manufacturing compliance across device segments, while HIPAA and GDPR frameworks constrain real-world data utilization in algorithmic diagnostic development. Stakeholders must monitor evolving payer evidence requirements for combined diagnostic-therapeutic reimbursement as health technology assessment bodies tighten value demonstration standards.
Market Dynamics
Companion diagnostic co-development mandates from FDA and EMA are compressing product launch timelines and forcing diagnostics-pharmaceutical alignment across melanoma care pathways.
Growth Catalysts
- Immunotherapy protocol expansion:PD-1 and CTLA-4 inhibitor pipelines are pulling molecular diagnostic testing into standard-of-care sequences across tertiary oncology centers in the United States and Germany.
- EMA centralized assessment harmonization:Streamlined CE marking under MDR is reducing regulatory fragmentation for in vitro diagnostic manufacturers seeking multi-country market access.
- Next-generation sequencing cost curves:Falling per-sample sequencing economics are enabling comprehensive genomic profiling as a frontline classification tool in community dermatology practices.
Market Restraints
- Reimbursement compression:Medicare and commercial payers in the United States are tightening coverage determinations for advanced imaging modalities without demonstrated outcome differentiation.
- Supply concentration in rare isotopes:Diagnostic radiopharmaceutical production depends on aging nuclear reactor infrastructure concentrated in Belgium and the Netherlands.
- Algorithmic validation bottlenecks:FDA software-as-medical-device pathways impose substantial clinical evidence requirements on machine learning-based lesion classification tools.
Strategic Opportunities
- India dermatology network buildout:Private hospital chains in Mumbai and Delhi are investing in dedicated skin cancer units with integrated Mohs surgery and pathology capabilities.
- Point-of-care molecular testing:Portable PCR and CRISPR-based platforms are enabling same-day BRAF mutation analysis in outpatient clinic settings.
- Australia TGA priority review:Expedited pathways for breakthrough diagnostics are accelerating market entry for novel companion tests aligned with immunotherapy launches.
Industry Challenges
- Dermatopathologist workforce constraints:Fellowship-trained specialists are concentrated in academic medical centers, creating diagnostic backlogs in community settings.
- Interoperability fragmentation:Electronic health record integration for multi-modal diagnostic data requires costly custom engineering across hospital IT environments.
- Real-world evidence collection:HIPAA and GDPR constraints limit retrospective algorithm training on clinical image repositories held by US and European health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skin Cancer Diagnostics and Therapeutics Market |
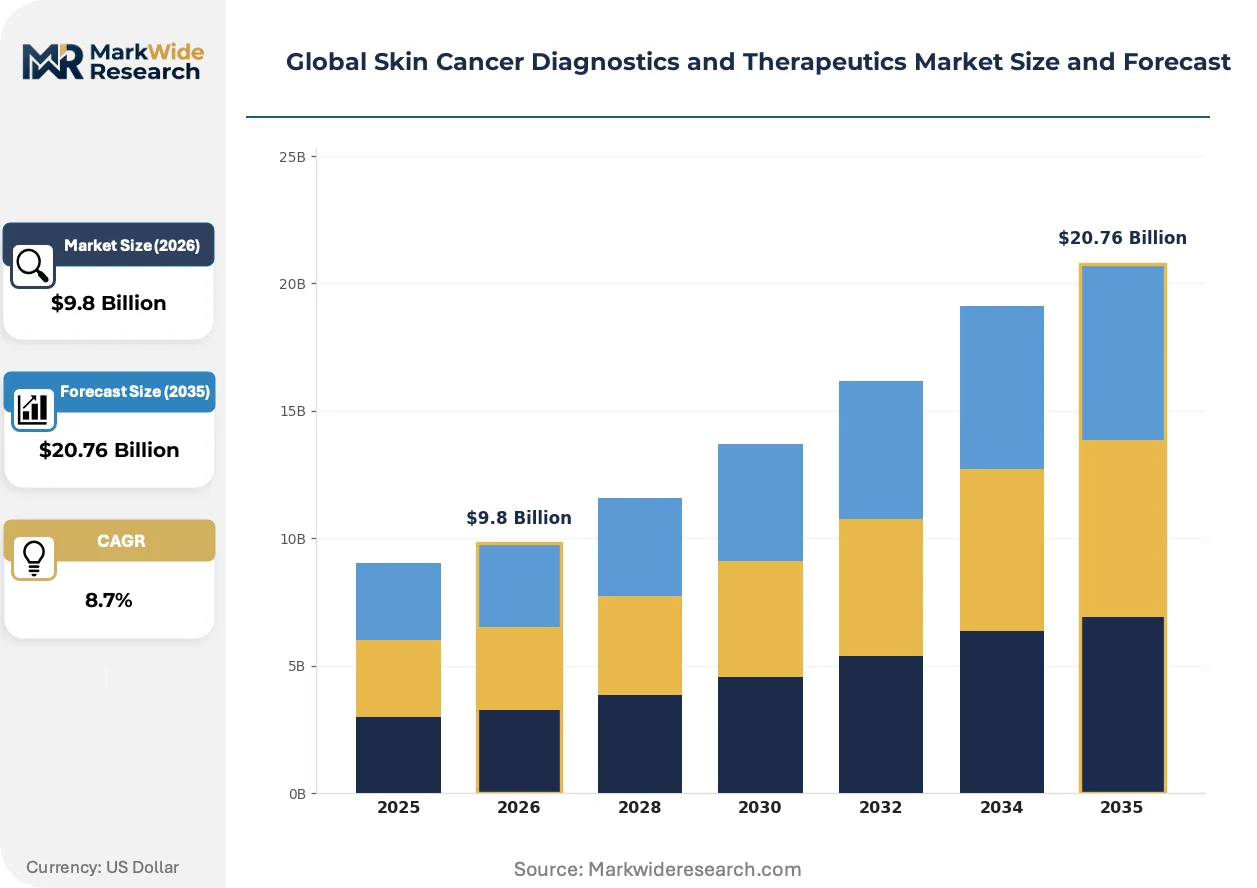
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging Systems, Biopsy Devices, Immunotherapy Drugs, Targeted Therapy Agents, Mohs Surgery Tools Application: Early Detection, Treatment Monitoring, Post-Therapy Follow-up, Recurrence Assessment End User: Dermatology Clinics, Oncology Centers, Pathology Laboratories, Ambulatory Surgery Centers Technology: Confocal Microscopy, Optical Coherence Tomography, Photodynamic Therapy, Cryotherapy, Radiotherapy |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Bristol-Myers Squibb Company, Amgen, Inc., Sun Pharmaceutical Industries Ltd, Novartis AG, Thermo Fisher Scientific Inc., Illumina, Inc., Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skin Cancer Diagnostics and Therapeutics Market Shifts & Advancements
Artificial intelligence and multi-omics integration are displacing single-modality diagnostic paradigms across melanoma staging and treatment selection workflows.
Multispectral imaging systems with embedded convolutional neural networks are rewriting lesion characterization standards by enabling non-invasive melanoma depth prediction. Academic dermatology departments in the United States and Australia are piloting these platforms for pre-biopsy triage. The technology is compressing unnecessary excision rates while creating new training requirements for clinic staff.
EU AI Act risk classification rules are mandating conformity assessments for diagnostic algorithms deployed in clinical decision-support roles. Device manufacturers must now document training data provenance and performance across demographic subgroups. High-risk AI system designations are extending CE marking timelines for computer-aided detection platforms targeting melanoma.
Consolidated purchasing by US hospital networks is unbundling diagnostic imaging from therapeutic service contracts. Integrated delivery systems in Texas and Florida are negotiating direct equipment financing arrangements with manufacturers. This shift is compressing distributor margins while favoring vendors with captive leasing capabilities.
Global Skin Cancer Diagnostics and Therapeutics Market Segmentation
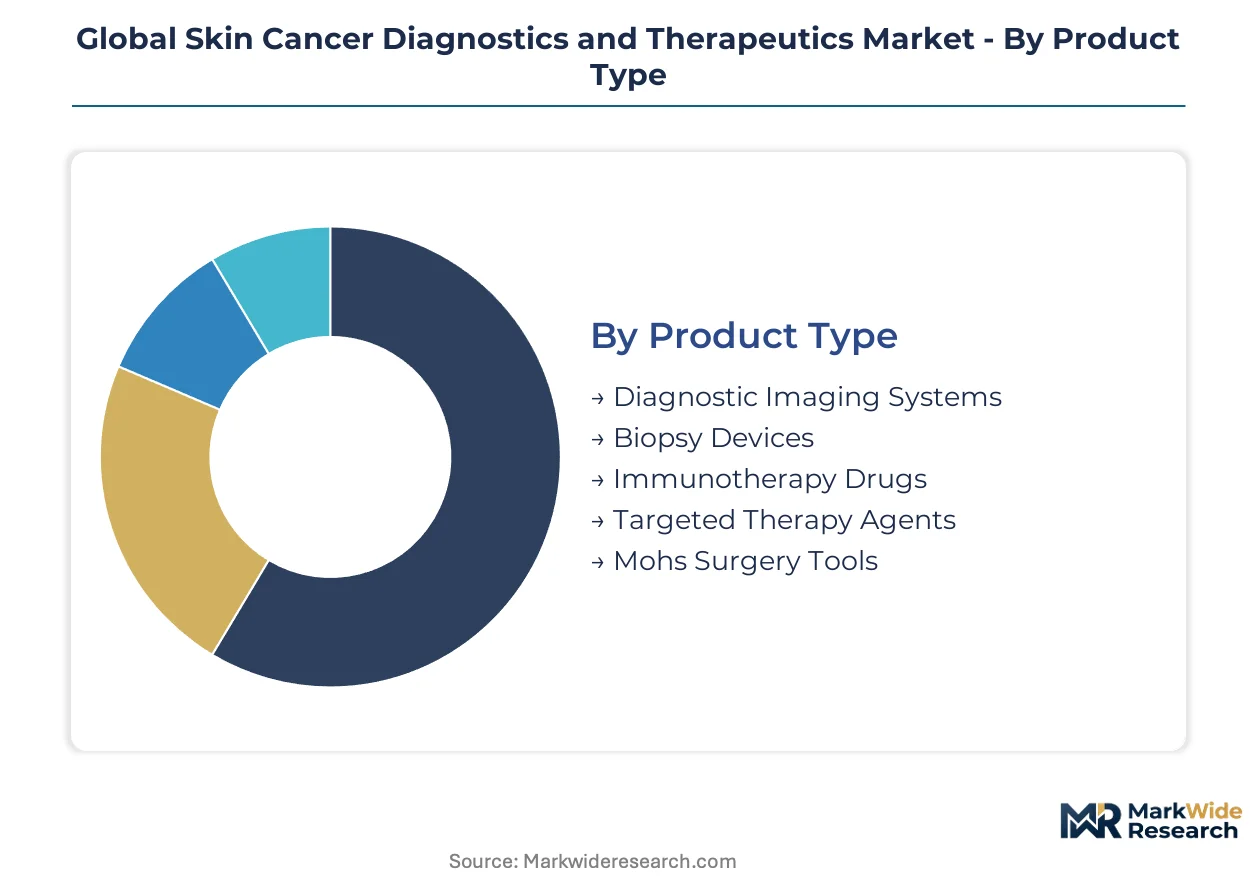
Segmentation in skin cancer care reveals divergent margin structures across diagnostic hardware and therapeutic biologics. Product type splits expose where capital equipment depreciation cycles clash with recurring pharmaceutical revenues. Application and end-user dimensions track how clinical workflow integration reshapes procurement authority.
Product Type:
Customization intensity varies sharply across this category, from standardized small-molecule inhibitors to patient-matched diagnostic configurations.
- Diagnostic Imaging Systems:Multispectral and dermoscopy platforms integrate convolutional neural networks for non-invasive depth assessment. Demand clusters in United States academic dermatology departments pursuing AI-augmented triage protocols, though Medicare reimbursement compression constrains community clinic adoption.
- Immunotherapy Drugs:PD-1 and CTLA-4 checkpoint inhibitors command premium pricing through demonstrated survival extension in metastatic melanoma. Oncology centers in Germany and Australia anchor demand as these agents displace chemotherapy in first-line protocols, with companion diagnostic mandates tightening prescriber workflow integration.
- Biopsy Devices:Punch and shave instruments with integrated specimen handling.
- Targeted Therapy Agents:BRAF and MEK inhibitor combinations for mutation-positive cases.
- Mohs Surgery Tools:Frozen section microtomes and margin mapping systems for dermatologic surgery suites.
Most installed capacity flows through Immunotherapy Drugs. Expansion is steepest in Diagnostic Imaging Systems.
Application:
Clinical utility and reimbursement density concentrate in frontline detection versus surveillance phases.
- Early Detection:Screening protocols for high-risk populations using dermoscopy and total body photography. Dermatology clinics in Australia deploy these systems at scale given elevated melanoma incidence, with TGA streamlined pathways accelerating device registration.
- Treatment Monitoring:Response assessment through sequential imaging and circulating tumor DNA analysis. United States oncology centers drive adoption as RECIST criteria evolve to incorporate immune-related response patterns, creating demand for standardized measurement tools.
- Post-Therapy Follow-up:Scheduled surveillance for surgical and medical completers.
- Recurrence Assessment:Local and distant relapse detection in previously treated patients.
Procedure volume peaks in Early Detection. Value capture is climbing fastest in Treatment Monitoring.
End User:
Purchasing sophistication and capital access separate institutional settings from distributed practice models.
- Dermatology Clinics:Primary diagnostic sites with concentrated biopsy volume and Mohs surgery capacity. Private hospital chains in India are building dedicated skin cancer units in Mumbai and Delhi with integrated pathology, though dermatopathologist shortages constrain throughput.
- Oncology Centers:Tertiary sites managing systemic therapy and clinical trial enrollment. German comprehensive cancer centers anchor European immunotherapy adoption, with EMA centralized assessments harmonizing access across member states.
- Pathology Laboratories:Centralized histology and molecular testing services.
- Ambulatory Surgery Centers:Outpatient excision and limited reconstruction facilities.
Patient encounter volume concentrates in Dermatology Clinics. Investment intensity is expanding most quickly in Oncology Centers.
Technology:
Platform maturity and regulatory burden fragment competitive positioning across optical, thermal, and radiologic modalities.
- Confocal Microscopy:In vivo cellular resolution imaging for non-invasive melanoma diagnosis. Academic departments in the United States and Australia pilot these systems for pre-biopsy triage, reducing unnecessary excisions while requiring new staff training protocols.
- Photodynamic Therapy:Photosensitizer activation for superficial non-melanoma lesions. Outpatient clinics in Germany utilize these protocols for actinic keratosis field treatment, with CE marking under MDR streamlining multi-country commercialization.
- Optical Coherence Tomography:Cross-sectional subsurface imaging for margin assessment.
- Cryotherapy:Liquid nitrogen destruction of precancerous and low-risk lesions.
- Radiotherapy:External beam and brachytherapy for non-surgical candidates.
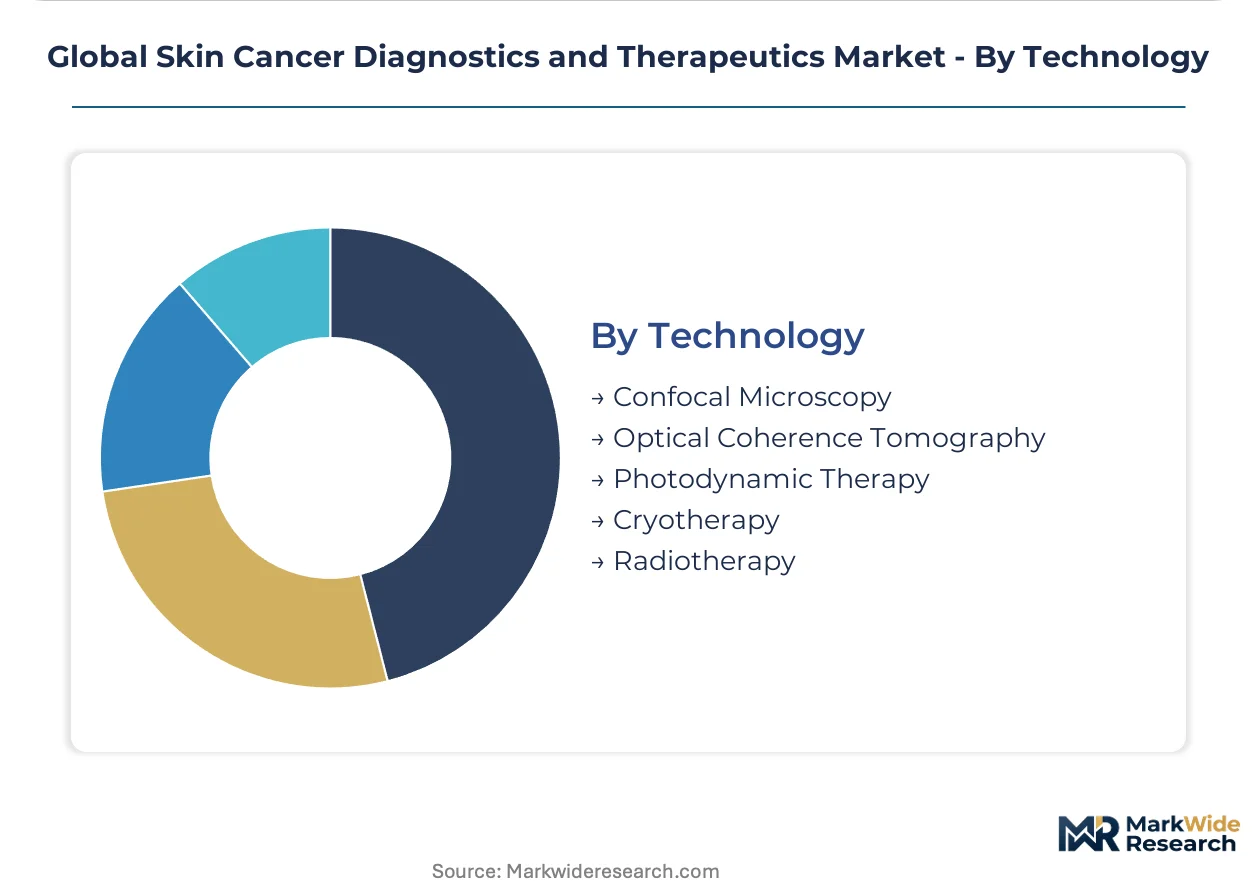
Clinical evidence depth is greatest in Confocal Microscopy. Regulatory approval velocity is fastest in Photodynamic Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melanoma immunotherapy protocols first achieved regulatory scale in the United States during the early 2010s, establishing clinical templates that German and Australian tertiary centers subsequently adapted. Diagnostic-therapeutic integration now concentrates purchasing decisions in hospital networks across five national markets.
United States
FDA companion diagnostic mandates and Medicare coverage determinations shape melanoma care pathways at Memorial Sloan Kettering and MD Anderson. The agency's premarket approval requirements compress development timelines for PD-1 inhibitor paired tests. Texas and Florida integrated delivery systems negotiate direct equipment financing with imaging manufacturers.
Germany
EMA centralized assessments harmonize immunotherapy access across comprehensive cancer centers in Heidelberg and Munich. The country's dermatology societies publish evidence frameworks that influence statutory health insurance reimbursement. Baden-Württemberg and Bavaria host the highest density of Mohs surgery training programs.
Australia
TGA priority review pathways accelerate breakthrough diagnostic registration aligned with immunotherapy launches. The world's highest melanoma incidence drives screening protocol innovation at Sydney and Melbourne academic departments. Queensland deploys total body photography networks at scale in regional clinic chains.
India
Private hospital chains in Mumbai and Delhi construct dedicated skin cancer units with integrated pathology and surgical capabilities. CDSCO regulatory pathways for in vitro diagnostics are streamlining multi-city commercialization. Maharashtra and Karnataka concentrate dermatopathologist training capacity.
United Kingdom
NICE technology appraisals constrain reimbursement for advanced imaging without outcome differentiation demonstrated in NHS trials. The country's cancer strategy directs suspected melanoma referrals to specialized skin cancer multidisciplinary teams. London and Manchester academic centers pilot AI-augmented dermoscopy triage protocols.
Global Skin Cancer Diagnostics and Therapeutics Market Competitive Landscape
The competitive structure tilts toward dual diagnostics-pharmaceutical conglomerates with integrated melanoma care pathway control. Tiered specialization separates checkpoint inhibitor pure-plays from molecular diagnostic platform vendors. Three archetypes dominate: bundled solution providers, immuno-oncology specialists, and testing workflow controllers. Consolidation through companion diagnostic co-development partnerships and direct hospital system contracting represents the primary competitive dynamic.
Within the bundled solution tier, F. Hoffmann-La Roche Ltd anchors integrated pathway positioning through combined diagnostics and therapeutic assets. Bristol-Myers Squibb Company exemplifies the immuno-oncology specialist archetype with concentrated checkpoint inhibitor development. Thermo Fisher Scientific Inc. occupies the testing workflow controller position, representing platform vendors that structure companion diagnostic standardization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Amgen, Inc. |
| Sun Pharmaceutical Industries Ltd |
| Novartis AG |
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Abbott |
| Others |
Supply & Pricing Matrix
Companion diagnostic co-development mandates from FDA and EMA are compressing procurement timelines and forcing diagnostics-pharmaceutical alignment that reshapes supplier pricing power across melanoma care pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PD-1 inhibitor brands from BRAF/MEK combinations from commoditized biopsy devices. Certification under FDA premarket approval and CE marking under MDR creates tier boundaries that academic medical centers pay premiums to cross. Cost compression in diagnostic imaging intensifies as Medicare tightens coverage without outcome differentiation. Community dermatology clinics exhibit highest price sensitivity, while tertiary oncology centers prioritize workflow integration over unit economics.
Supply Chain Analysis
Freight costs for temperature-controlled biologics and diagnostic reagents have risen sharply, compressing margins on cross-continental immunotherapy distribution. Manufacturing concentrates in Belgium and the Netherlands for radiopharmaceutical isotopes, Switzerland and Germany for checkpoint inhibitor production, and the United States for next-generation sequencing platforms. Supply rests on aging nuclear reactor infrastructure for diagnostic isotopes and single-source fermentation capacity for monoclonal antibodies. Tariff exposure on Chinese-sourced PCR consumables threatens point-of-care molecular testing economics. Distribution runs through integrated delivery systems in Texas and Florida that negotiate direct manufacturer financing, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA companion diagnostic mandates and EMA centralized assessments continuously expand addressable demand through protocol standardization.
For Market Incumbents: Cement integrated pathway control by locking in exclusive companion diagnostic partnerships with emerging immunotherapy developers before regulatory submission. Deepen backward integration into next-generation sequencing consumables manufacturing to offset tariff exposure on Asian-sourced reagents. Defend against molecular diagnostic platform vendors by embedding AI-augmented imaging algorithms directly into hospital system electronic health records.
For New Entrants and Emerging Players: Enter via point-of-care BRAF mutation testing in Indian private hospital chains where dermatopathologist shortages create diagnostic backlogs and price elasticity favors rapid-turnaround alternatives. Target Australia's TGA priority review pathway for breakthrough device designation aligned with immunotherapy launch windows. Pursue white-label manufacturing partnerships with established IVD platforms rather than building captive sales infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with molecular diagnostic platform vendors controlling companion testing workflows for late-stage checkpoint inhibitor pipelines. Five-to-ten year viability hinges on FDA software-as-medical-device clearance velocity for machine learning-based lesion classification. Monitor EMA MDR implementation timelines as the inflection signal for European market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Aligns molecular testing launch with FDA approval of paired checkpoint inhibitors. |
| CE Marking Pathway Under MDR | Streamlines multi-country European commercialization for in vitro diagnostic manufacturers. |
| Hospital System Direct Contracting | Bypasses distributor margins through captive equipment financing with Texas and Florida IDNs. |
| Software Companion Development | Embeds AI lesion classification directly into EHR workflows at US academic dermatology departments. |
| Reimbursement Strategy | Secures Medicare coverage determination for advanced imaging through outcome differentiation trials. |
Research Methodology
Bottom-up dermatology clinic and oncology center modeling reconciled against top-down pharmaceutical and diagnostic device production tracking forms the analytical core of this study. Primary interviews with dermatopathologists, hospital procurement managers, regulatory affairs leads at IVD manufacturers, and payer access specialists were validated against secondary sources including FDA 510(k) and PMA filings, EMA centralized assessment reports, ClinicalTrials.gov melanoma protocol registries, and CMS Medicare coverage determination databases. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map immunotherapy drug volume to companion diagnostic test demand, surgical procedure counts to Mohs surgery tool replacement cycles, and sequencing platform placements to reagent consumption rates across the projection horizon. Segmentation dimensions include product type, application stage, end-user setting, and technology platform, with CAGRs derived from regression analysis of historical regulatory approval velocity and reimbursement expansion patterns. Forecast inputs incorporate dermatopathologist workforce growth projections and nuclear isotope reactor maintenance schedules.
Inputs from FDA and EMA regulatory filing databases were available through the study window; gaps in real-world companion diagnostic utilization rates from European comprehensive cancer centers introduce uncertainty bands around market penetration assumptions. Forecasts reflect documented assumptions about immunotherapy protocol expansion and software-as-medical-device clearance timelines. Stakeholders should weight these assumptions against their own operating context and local reimbursement environments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Pharyngeal Neoplasm Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Immuno-Oncology Market
Oncology
Ovarian Cancer Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Global Cancer Profiling Market
Oncology
Liposarcoma Treatment Market
Oncology
Glottic Cancer Treatment Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Global Veterinary Oncology Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Global Cancer Supportive Care Drugs Market