
 Kinase Inhibitors for Cancer Treatment Market | 2026-2036
Kinase Inhibitors for Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Kinase Inhibitors for Cancer Treatment Market Foresight
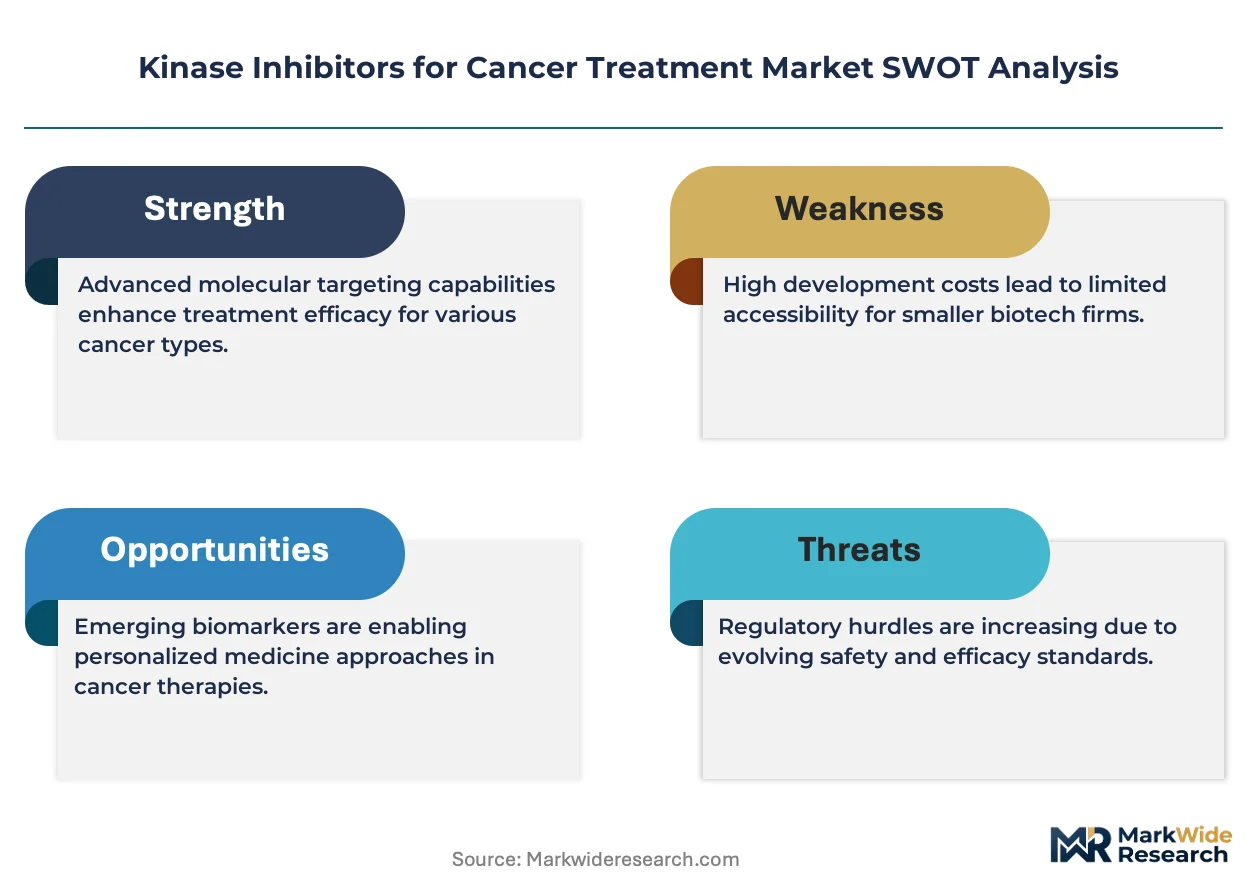
Project finance partnerships between biotech innovators and institutional investors is reconfiguring capital access for mid-stage kinase inhibitor developers. Pfizer leverages its manufacturing scale to dominate commercial supply of established tyrosine kinase inhibitors. Novartis anchors its position through sustained R&D intensity in next-generation compound discovery. Bristol Myers Squibb differentiates via geographic dominance in immuno-oncology combination protocols.
Kinase inhibitors for cancer treatment are targeted small-molecule or biologic agents that block specific protein kinase enzymes driving malignant cell proliferation, typically formulated as oral tablets or intravenous solutions requiring bioavailability above 80 percent and selectivity indices exceeding 100-fold versus off-target kinases. Small molecules command the largest revenue pool due to mature manufacturing routes and broad prescriber familiarity, while combination therapies represent the fastest-expanding segment as clinicians seek to overcome resistance mechanisms through dual-pathway blockade. Monoclonal antibodies occupy a premium tier where manufacturing complexity and cold-chain logistics create natural margin barriers.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and reshape competitive entry sequencing for novel kinase targets. The FDA's accelerated approval framework demands confirmatory trial execution, creating post-market surveillance obligations that influence portfolio risk calculations. REACH compliance in Europe adds manufacturing and environmental safety constraints on active pharmaceutical ingredient synthesis. Stakeholders must monitor evolving biomarker coverage policies by CMS and national health technology assessment bodies to anticipate reimbursement-driven demand shifts.
Market Dynamics
Resistance-driven combination protocols are restructuring clinical practice patterns, forcing developers to engineer dual-target molecules rather than single-pathway blockers. This shift compresses development timelines while elevating manufacturing complexity for co-formulated products.
Growth Catalysts
- FDA Accelerated Approval:The breakthrough therapy designation compresses Phase II-to-market timelines for novel kinase targets. Confirmatory trial obligations create predictable regulatory roadmaps for portfolio planning.
- Companion Diagnostic Integration:Biomarker-driven patient stratification improves response rates and anchors reimbursement justification. CMS coverage determinations for NGS-based testing expand addressable patient pools.
- China NMPA Reform:Priority review pathways for innovative oncology drugs accelerate market entry for foreign-origin compounds. Domestic clinical trial data requirements are harmonizing with ICH standards.
Market Restraints
- API Synthesis Concentration:Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces create single-source vulnerability. REACH compliance adds environmental safety costs for European synthesis operations.
- Off-Target Liability:Cardiotoxicity signals in BCR-ABL inhibitors trigger black-box warnings that constrain prescriber enthusiasm. QT prolongation monitoring requirements complicate outpatient administration protocols.
- Biosimilar Erosion:Patent cliffs for first-generation tyrosine kinase inhibitors expose revenue pools to substitutable competition. Oncology formularies increasingly mandate step-therapy through generic equivalents.
Strategic Opportunities
- Brain Metastasis Indications:Blood-brain barrier penetration remains underserved for EGFR-mutant lung cancer. CNS-penetrant compound variants command premium pricing in academic medical centers.
- Japan PMDA Sakigake:The pioneer designation grants priority consultation and shortened review timelines. Early engagement with PMDA scientific advisors de-risks Japan-first development strategies.
- Allosteric Inhibition Modalities:Non-ATP competitive binding sites circumvent resistance mutations in kinase hinge regions. Cryo-EM structural biology is virtualizing target validation workflows.
Industry Challenges
- Translational Biology Talent:Scarcity of investigators bridging structural biology and clinical pharmacology delays IND-enabling studies. Academic-industry fellowship programs compete for limited PhD-level candidates.
- Multi-Regional Clinical Trial Coordination:Divergent regulatory requirements across FDA, EMA, and NMPA fragment patient recruitment. Protocol amendment cycles consume 14-18 months for global harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kinase Inhibitors for Cancer Treatment Market |
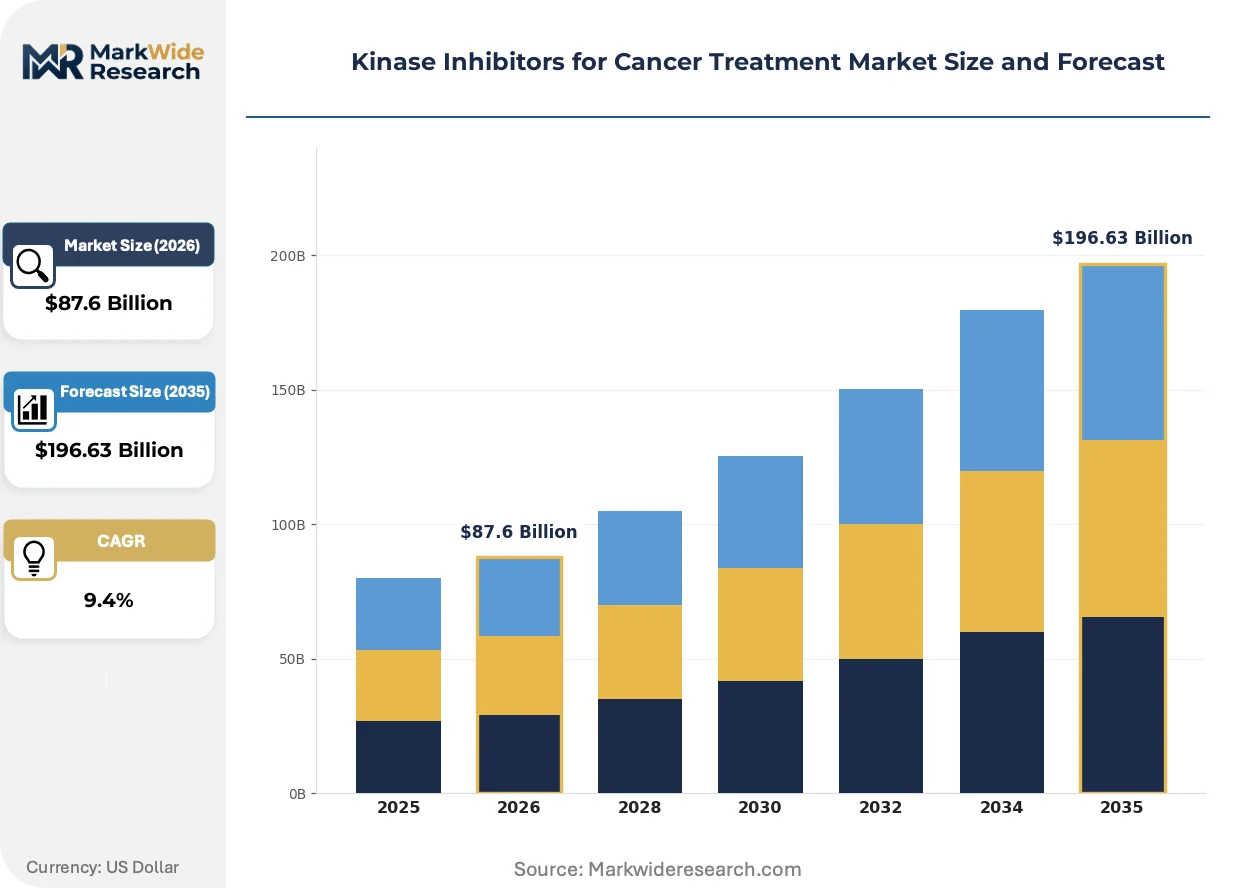
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Combination Therapies, Biosimilars Application: Targeted Therapy, Immunotherapy, Chemotherapy, Precision Medicine Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Oncology Clinics, Research Institutions, Homecare |
| Companies Covered | Pfizer, Roche, Novartis, AstraZeneca, Bristol Myers Squibb, Eli Lilly and Company, Bayer, Takeda Pharmaceutical, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kinase Inhibitors for Cancer Treatment Market Shifts & Advancements
Computational target identification and patient-derived model systems are compressing the validation-to-IND timeline. These tools reshape how developers prioritize kinase targets and design first-in-human protocols.
Artificial intelligence-driven molecular dynamics simulation is virtualizing lead optimization cycles for kinase selectivity profiling. Large pharma discovery groups deploy these platforms to triage 10,000-compound libraries against mutant kinase conformations. The technology compresses 18-month SAR cycles into 4-6 month iterations.
EMA's PRIME designation and adaptive pathway frameworks reward developers generating real-world evidence post-authorization. Oncology drug sponsors now embed patient registries within initial approval packages. This regulatory evolution most affects mid-stage biotechs seeking European market access ahead of confirmatory readouts.
Oncology procurement groups at integrated delivery networks now unbundle pharmacy benefit management from medical oncology purchasing. Third-party specialty pharmacies capture dispensing margins previously retained by hospital outpatient departments. This channel shift concentrates in United States markets where 340B pricing differentials drive site-of-care migration.
Kinase Inhibitors for Cancer Treatment Market Segmentation
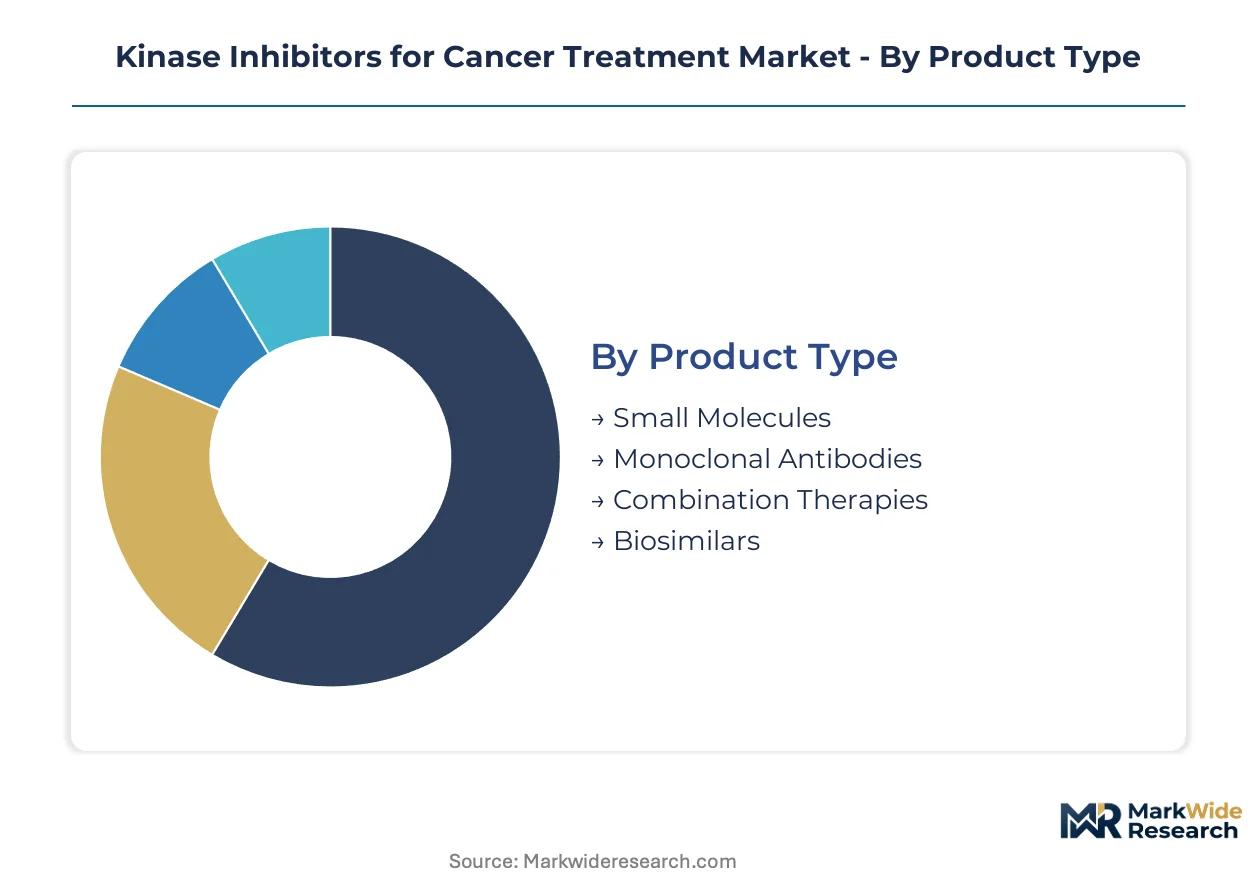
Kinase inhibitor developers engineer portfolio breadth across molecular modalities and clinical settings to capture reimbursement value. Segmentation strategy determines manufacturing investment priorities and regulatory pathway selection.
Product Type:
Mature oral small molecules anchor commercial revenue while emerging modalities reshape competitive positioning.
- Small Molecules:Oral ATP-competitive inhibitors dominate prescriber familiarity and manufacturing scale. United States oncology clinics concentrate demand here for outpatient administration protocols. Mature chemistry routes compress COGS below biologic alternatives.
- Combination Therapies:Dual-pathway blockade protocols address resistance mechanisms in EGFR-mutant lung cancer and BCR-ABL leukemias. Academic medical centers drive adoption where biomarker testing infrastructure supports patient stratification. Co-formulation complexity elevates technical barriers for mid-stage developers.
- Monoclonal Antibodies:Biologic kinase inhibitors command premium pricing tiers through manufacturing sophistication and cold-chain logistics requirements.
- Biosimilars:Substitutable competition targets patent-expired tyrosine kinase inhibitors with abbreviated development pathways.
Small molecules handle the majority of throughput; combination therapies are gaining share fastest as resistance protocols proliferate.
Application:
Cost tier stratification separates premium precision indications from commoditized chemotherapy adjuvant use.
- Targeted Therapy:Biomarker-driven patient selection improves response rates and anchors CMS reimbursement justification. Companion diagnostic integration is mandatory for FDA breakthrough therapy designation eligibility.
- Precision Medicine:NGS-guided kinase inhibitor matching expands addressable populations in solid tumor indications. Integrated delivery networks concentrate procurement for these protocols where 340B pricing differentials apply.
- Immunotherapy:Checkpoint inhibitor combinations with kinase blockade reshape first-line lung cancer protocols.
- Chemotherapy:Adjuvant kinase inhibition in combination cytotoxic regimens faces biosimilar pricing pressure.
Targeted therapy commands the largest revenue pool; precision medicine shows the steepest expansion trajectory as NGS coverage broadens.
Delivery Mode:
Volume concentration favors oral administration while margin capture concentrates in hospital-based parenteral formats.
- Oral:Tablet formulations achieve bioavailability above 80 percent with once-daily dosing convenience. Outpatient dispensing through specialty pharmacies reduces site-of-care costs for payers.
- Intravenous:Infusion center administration captures hospital outpatient department margins where 340B pricing applies. QT prolongation monitoring requirements complicate clinic workflows.
- Injectable:Subcutaneous and intramuscular routes bridge bioavailability gaps for large-molecule kinase inhibitors.
- Subcutaneous:Self-administration potential reduces infusion center burden in maintenance therapy settings.
Oral delivery handles the majority of prescription volume; intravenous administration retains the highest per-dose revenue capture.
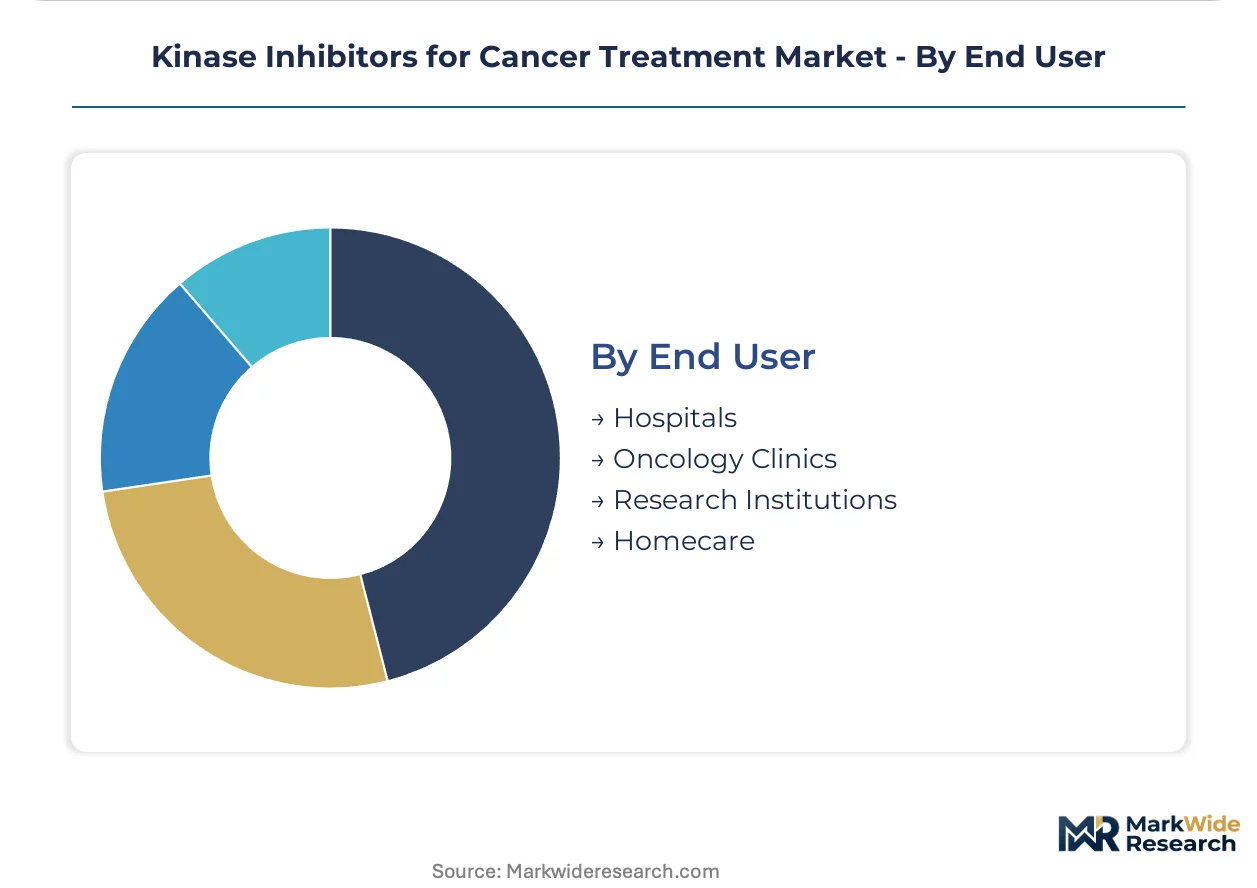
End User:
Customer type determines procurement channel strategy and clinical trial site selection for registrational studies.
- Oncology Clinics:Community-based practices drive volume for established tyrosine kinase inhibitors with predictable safety profiles. Third-party specialty pharmacy dispensing is displacing hospital outpatient capture.
- Hospitals:Academic medical centers concentrate demand for investigational kinase inhibitors and combination protocols. Clinical trial infrastructure anchors investigator-initiated studies for novel targets.
- Research Institutions:Translational biology programs supply patient-derived models for target validation and resistance mechanism studies.
- Homecare:Oral kinase inhibitor administration shifts site-of-care for maintenance therapy in stable disease populations.
Oncology clinics process the majority of commercial prescriptions; research institutions are expanding most quickly as sponsored trial activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for active pharmaceutical ingredients concentrates supply risk in Asian manufacturing clusters, while finished kinase inhibitor formulations flow toward markets with advanced precision medicine infrastructure. Export revenues from established oral small molecules partially offset biologics import costs in developed economies. The United States, Germany, Japan, China, and the United Kingdom represent the primary demand centers where regulatory pathways and reimbursement frameworks determine market access sequencing.
United States
FDA breakthrough therapy designation accelerates Phase II-to-market timelines for novel kinase targets, compressing development cycles by 12-18 months. CMS coverage determinations for NGS-based companion diagnostics expand reimbursable patient pools for biomarker-driven protocols. The Greater Boston and San Francisco Bay Area biotech clusters concentrate translational biology talent and early-stage kinase inhibitor discovery programs.
Germany
EMA centralized marketing authorization procedures position German oncology clinics as early adopters for novel kinase inhibitors seeking European access. REACH compliance adds environmental safety costs for active pharmaceutical ingredient synthesis operations, reshaping manufacturing investment decisions. The Rhine-Main and Munich metropolitan regions host integrated delivery networks with dedicated precision medicine units for EGFR-mutant lung cancer protocols.
Japan
PMDA Sakigake pioneer designation grants priority consultation and shortened review timelines for first-in-class kinase inhibitors. Domestic clinical trial infrastructure supports Japan-first development strategies for CNS-penetrant compound variants. The Kanto region around Tokyo concentrates pharmaceutical R&D facilities and academic medical center trial sites for brain metastasis indications.
China
NMPA priority review pathways for innovative oncology drugs accelerate market entry for foreign-origin kinase inhibitors while domestic manufacturers expand biosimilar portfolios. Clinical trial data requirements harmonize with ICH standards, enabling multi-regional study participation. Zhejiang and Jiangsu provinces host active pharmaceutical ingredient manufacturing clusters that supply global tyrosine kinase inhibitor production.
United Kingdom
NICE technology appraisals determine NHS reimbursement for combination kinase inhibitor protocols, creating post-market access uncertainty for premium-priced therapies. MHRA independent recognition pathways maintain regulatory agility post-Brexit for accelerated approvals. The Cambridge-London corridor anchors structural biology research programs advancing allosteric inhibition modalities for resistance mutation circumvention.
Kinase Inhibitors for Cancer Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with manufacturing scale or target-specific expertise. The kinase inhibitor market consolidates around large pharmaceutical conglomerates with established oncology franchises, while mid-stage biotech innovators occupy niche indication spaces. Three archetypes dominate: diversified pharma majors with global commercial infrastructure, targeted therapy specialists with deep kinase biology expertise, and biosimilar manufacturers exploiting patent cliff exposure. Competitive moves center on co-development partnerships for combination protocols and geographic licensing arrangements for emerging market access.
Among diversified pharmaceutical majors, Pfizer, Novartis, and Bristol Myers Squibb occupy positions representing distinct strategic archetypes. Pfizer exemplifies manufacturing scale dominance in established tyrosine kinase inhibitor supply. Novartis anchors next-generation compound discovery through sustained R&D intensity. Bristol Myers Squibb sits within the immuno-oncology combination protocol segment, differentiating via geographic positioning in dual-pathway blockade development.
| Leading Market Players |
|---|
| Pfizer |
| Roche |
| Novartis |
| AstraZeneca |
| Bristol Myers Squibb |
| Eli Lilly and Company |
| Bayer |
| Takeda Pharmaceutical |
| Merck |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries active pharmaceutical ingredient shipments from Zhejiang manufacturing clusters to European formulation facilities, with freight cost volatility amplifying margin pressure on generic tyrosine kinase inhibitors while reinforcing premium pricing power for cold-chain biologics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the kinase inhibitor market. Academic medical centers purchasing CNS-penetrant EGFR inhibitors face limited price sensitivity due to orphan indication status and restricted prescriber pools, while community oncology clinics exhibit acute sensitivity to biosimilar substitution for patent-expired BCR-ABL therapies. Price differentiation separates FDA breakthrough-designated compounds with companion diagnostic mandates from commodity oral small molecules facing step-therapy formulary restrictions. Cost compression in the first-generation TKI tier intensifies as Indian and Chinese manufacturers expand abbreviated new drug application filings.
Supply Chain Analysis
Contract manufacturing organizations including Lonza, Catalent, and Samsung Biologics concentrate biologic kinase inhibitor production capacity across Switzerland, Singapore, and South Korea. Active pharmaceutical ingredient synthesis for small-molecule inhibitors draws from Zhejiang and Jiangsu provinces in China, with ketone and pyridine derivative feedstocks sourced from domestic petrochemical complexes. Single-source vulnerability in high-potency API containment facilities creates supply chain risk for cytotoxic kinase conjugates. Distribution runs through third-party specialty pharmacy networks that disperse oral formulations directly to patients, bypassing hospital outpatient department capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kinase inhibitor market operates as a regulatory entrenchment story where FDA breakthrough therapy designation and companion diagnostic integration create switching costs that lock in prescriber behavior across treatment lines.
For Market Incumbents: Harden defensive positioning through captive supply of critical starting materials for ATP-competitive scaffolds and exclusive partnerships with NGS diagnostic platforms. Biosimilar erosion in the imatinib and erlotinib franchises demands capacity rationalization toward next-generation allosteric inhibitors. Vertical integration into cryo-EM structural biology capabilities accelerates resistance mutation response cycles. For New Entrants and Emerging Players: Brain metastasis indications in EGFR-mutant lung cancer represent the most penetrable entry point, with blood-brain barrier penetration metrics offering differentiation where large pharma has underinvested. Japan PMDA Sakigake pioneer designation pathways enable accelerated revenue recognition for CNS-penetrant variants. A go-to-market strategy anchored in academic medical center investigator-initiated trials bypasses the formulary access barriers that constrain community clinic penetration. For Investors and Strategic Acquirers: Mid-stage biotechs with validated allosteric binding platforms and existing FDA IND clearances offer the strongest acquisition profile for portfolio expansion. Long-term viability across the analysis window depends on pipeline diversification beyond single-kinase targets toward multi-specific modalities. The signal to watch is confirmatory trial failure rates for accelerated approval compounds, which would trigger reimbursement clawback exposure and compress valuation multiples for late-stage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II basket trials in rare kinase fusions accelerate biomarker-driven patient identification for FDA breakthrough submissions. |
| Regulatory Approval Pathway | PMDA Sakigake pioneer designation compresses Japan market entry timelines for CNS-penetrant compound variants. |
| Licensing Agreement | Companion diagnostic co-development with NGS platform vendors anchors CMS reimbursement justification. |
| Manufacturing Scale-Up | High-potency API containment capacity expansion in Switzerland de-risks supply for antibody-drug conjugate payloads. |
| Pipeline Diversification | Multi-specific kinase degraders circumvent resistance mutations that limit ATP-competitive inhibitor durability. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists anchored the qualitative base for this study. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS national coverage determinations. Bottom-up patient-flow modeling and top-down revenue triangulation cross-checked segmentation outputs across molecular modality, treatment line, and regional regulatory cluster dimensions.
Scenario-bracketing framed analytical outputs across the projection horizon, with base, upside, and downside cases reflecting differential assumptions for biosimilar erosion velocity and breakthrough therapy designation success rates. Segmentation dimensions modeled included administration route, patient population stratification, and regional reimbursement framework clusters. CAGRs derived from fitted growth curves applied to addressable patient pools adjusted for companion diagnostic penetration. Forecast inputs incorporated real-world evidence generation requirements under FDA accelerated approval and EMA adaptive pathway frameworks.
Practitioners should monitor confirmatory trial readout schedules and CMS biomarker coverage policy updates for early signals of reimbursement-driven demand shifts. Forecasts reflect assumptions regarding regulatory pathway continuity and competitive entry sequencing that industry-specific risk factors could materially revise. Quarterly review of FDA accelerated approval withdrawal patterns and NGS testing volume trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Testicular Cancer Treatment Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Thyroid Cancer Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Radiation Therapy Software Market
Oncology
Pharyngeal Neoplasm Market
Oncology
Global Interventional Oncology Market
Oncology
Global Genomics in Cancer Care Market
Oncology
North America Proton Therapy Market
Oncology
Glottic Cancer Treatment Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Sterile Oncology Injectable Market
Oncology
Tumor Ablation Market