
 South America Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
South America Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Bladder Cancer Therapeutics and Diagnostics Market Analytics
Hospital procurement departments across South America are unwinding their historical reliance on centralized ministry tenders toward direct manufacturer negotiations. Bristol-Myers Squibb Company leverages its immuno-oncology portfolio to anchor relationships with major cancer institutes in São Paulo and Buenos Aires. Roche Holding AG dominates molecular diagnostics through integrated pathology workflow systems deployed across Brazilian reference laboratories. Pfizer Inc. competes on chemotherapy volume contracts with regional distributors serving second-tier cities.
Bladder cancer therapeutics and diagnostics encompasses pharmaceutical interventions and detection modalities targeting urothelial malignancies, where immunotherapy agents such as PD-1/PD-L1 inhibitors demonstrate durable response rates in muscle-invasive disease and cystoscopy remains the structural gold standard for visual tumor assessment. Immunotherapy within the treatment type dimension captures expanding margin pools as payers reassess reimbursement for checkpoint inhibitors against platinum-refractory metastatic cases. Urinary biomarkers in the diagnostic method category sustain faster volume growth than tissue-based alternatives by enabling non-invasive surveillance protocols that reduce cystoscopy frequency in low-risk patient cohorts.
ANVISA governs pharmaceutical registration and post-market surveillance in Brazil, while Argentina's national pharmac regulator administers comparable oversight through INAME, and each framework dictates clinical trial acceptance standards that determine which therapeutic classes reach reimbursement lists first. These regulatory gatekeepers shape demand by conditioning market access on local evidence generation requirements that extend development timelines for novel agents. Stakeholders must monitor how national health technology assessment bodies across Chile, Peru, and Colombia harmonize their evidentiary thresholds for biomarker-guided therapy selection.
Market Dynamics
ANVISA's accelerated pathway for breakthrough therapies is compressing registration timelines for immuno-oncology agents, forcing multinational manufacturers to restructure their Brazil-first launch sequencing while local hospitals build molecular diagnostic procurement capabilities ahead of reimbursement approvals.
Growth Catalysts
- ANVISA Accelerated Review:Brazil's regulatory fast-track for breakthrough oncology therapies reduces time-to-market for PD-1/PD-L1 inhibitors, expanding eligible patient pools in São Paulo's public hospital networks.
- Urinary Biomarker Adoption:Non-invasive surveillance protocols using NMP22 and UroVysion FISH testing are displacing scheduled cystoscopies in low-risk bladder cancer cohorts across Argentine urology clinics.
- Reference Laboratory Consolidation:Brazilian diagnostic networks are centralizing molecular pathology workflows into automated platforms, creating captive demand for integrated immunohistochemistry and fluorescence in situ hybridization systems.
Market Restraints
- Reimbursement Fragmentation:Colombia's POS and Argentina's PAMI maintain divergent coverage criteria for biomarker-guided therapy selection, forcing manufacturers to negotiate parallel value demonstration frameworks.
- Import Dependency:Chile and Peru lack domestic manufacturing for cystoscopy optics and resectoscopes, exposing procurement budgets to currency volatility against dollar-denominated supplier contracts.
- Cold Chain Limitations:Temperature-controlled distribution for temperature-sensitive immunotherapy biologics remains underdeveloped in Amazon basin states, constraining patient access outside coastal metropolitan corridors.
Strategic Opportunities
- Colombia Regional Expansion:Bogotá and Medellín oncology centers are underpenetrated for next-generation sequencing-based companion diagnostics, creating first-mover positioning for integrated test-and-treat service models.
- Telepathology Networks:Remote diagnostic consultation platforms are converging with cloud-based image analysis to extend specialist pathology coverage into Ecuador and Paraguay without capital-intensive laboratory builds.
- INAME Harmonization:Argentina's national pharmac regulator is aligning clinical trial data requirements with MERCOSUR standards, reducing redundant evidence generation for sponsors seeking multi-country registration.
Industry Challenges
- Molecular Pathology Talent Scarcity:Brazil's reference laboratories face recruitment bottlenecks for certified molecular biologists capable of interpreting complex biomarker panels for therapy selection.
- Legacy Cystoscopy Infrastructure:Second-tier hospitals in Colombia and Peru maintain rigid capital replacement cycles for endoscopic equipment, delaying adoption of narrow-band imaging and photodynamic diagnostic enhancements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Bladder Cancer Therapeutics and Diagnostics Market |
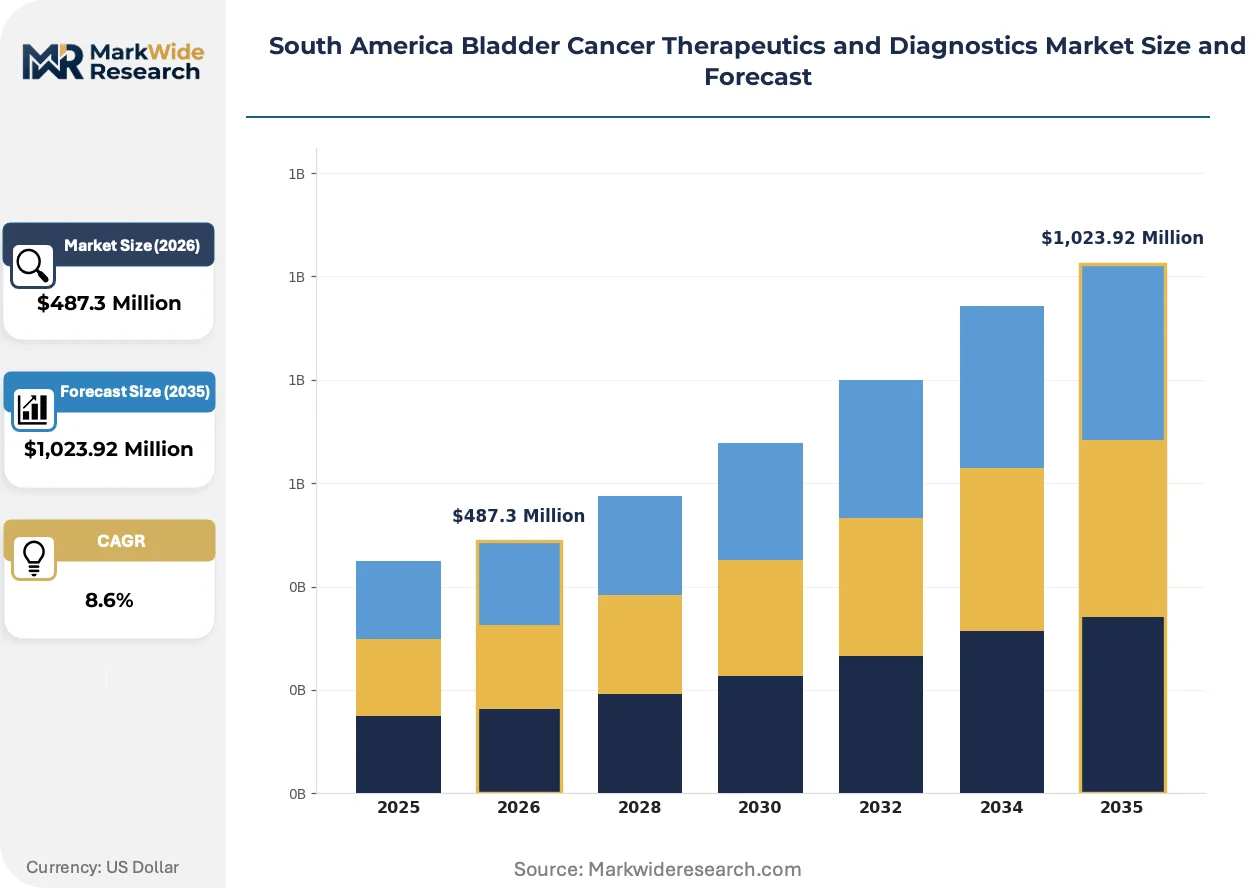
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Chemotherapy, Immunotherapy, Surgery, Radiotherapy Diagnostic Method: Cystoscopy, Urinary Biomarkers, Imaging Techniques, Biopsy End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Drug Class: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Others |
| Companies Covered | Pfizer Inc., Johnson & Johnson, AstraZeneca, Bristol-Myers Squibb Company, Merck & Co., Inc., Roche Holding AG, Novartis AG, Eli Lilly and Company, Bayer AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Bladder Cancer Therapeutics and Diagnostics Market Evolving Landscape
Liquid biopsy platforms and artificial intelligence-assisted cystoscopy are restructuring competitive positioning across South American urology practices, while procurement departments unwind centralized ministry tenders toward direct manufacturer negotiations.
Multiplex urinary biomarker panels combining cytology with genomic alteration detection are fragmenting the diagnostic workflow in Brazilian cancer institutes. São Paulo's Hospital das Clínicas and Barretos Cancer Hospital have adopted sequential testing algorithms that triage patients between surveillance intervals based on combined risk scores. This technology is fragmenting the historical monopoly of white-light cystoscopy in low-risk patient management, compressing revenue per procedure while expanding total addressable testing volume.
ANVISA's updated guidance on real-world evidence for oncology drug registration is tightening evidentiary requirements for post-approval safety monitoring. Manufacturers must now submit patient registry data from Brazilian treatment centers as a condition of maintained reimbursement listing. Muscle-invasive bladder cancer immunotherapy indications face the steepest compliance burden, with sponsors investing in dedicated local observational study infrastructure to satisfy pharmacovigilance mandates.
Hospital procurement departments across the region are consolidating vendor relationships through multi-year managed service contracts for diagnostic equipment. Rio de Janeiro's state oncology network and Buenos Aires' public hospital system have shifted from capital purchase models to per-procedure leasing arrangements that bundle maintenance, consumables, and software updates. This restructuring is most visible in cystoscopy and pathology workflow systems, where operational expenditure budgets now accommodate technology refresh cycles previously deferred due to fiscal constraints.
South America Bladder Cancer Therapeutics and Diagnostics Market Segmentation
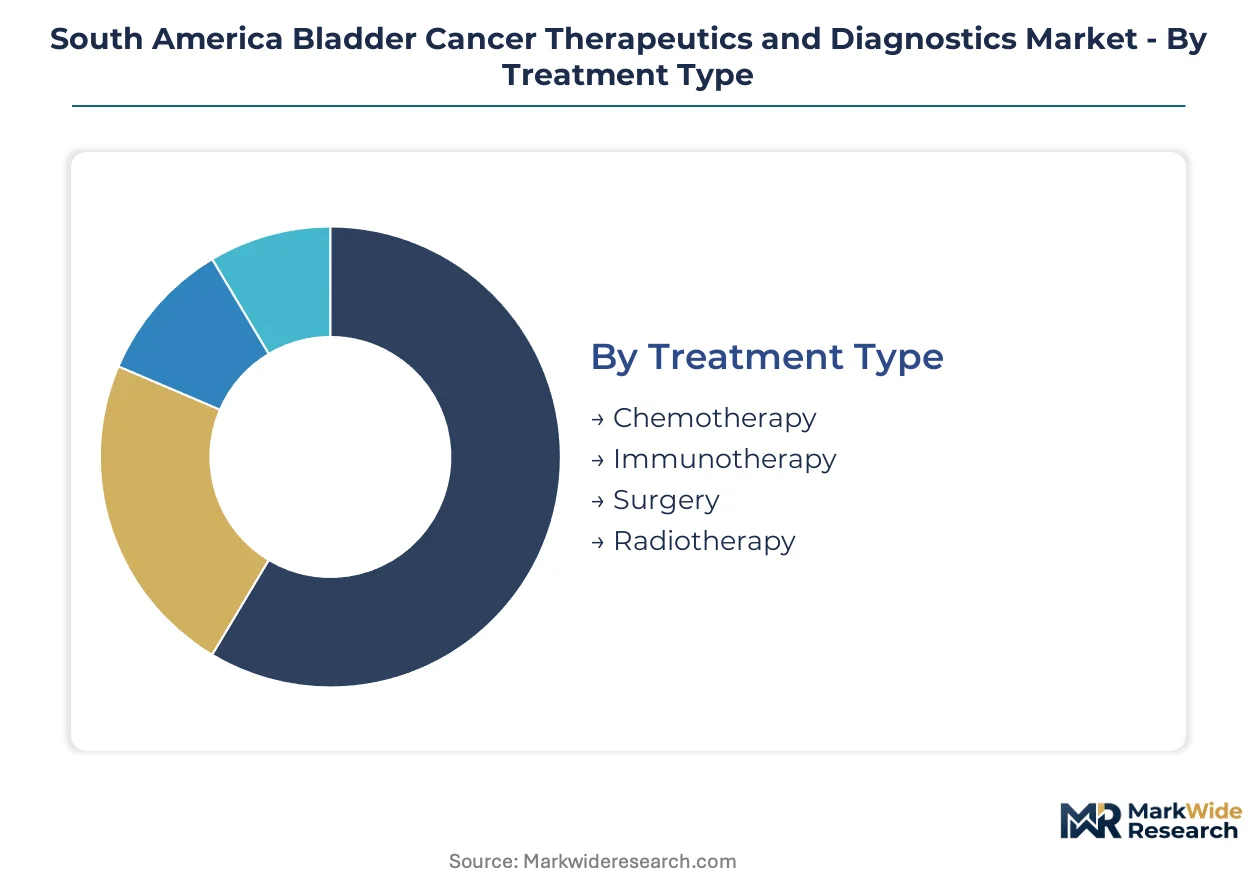
Segmentation in the South America bladder cancer market reveals divergent margin structures across therapeutic modalities and diagnostic workflows. Procurement patterns in São Paulo and Buenos Aires oncology networks concentrate spending on immunotherapy agents and molecular diagnostics, while regional distributors capture volume in chemotherapy and conventional cystoscopy services.
Treatment Type:
Margin pools concentrate in immunotherapy agents where checkpoint inhibitors command premium pricing against platinum-refractory disease, while chemotherapy contracts compete on volume throughput.
- Immunotherapy:PD-1/PD-L1 inhibitors demonstrate durable response rates in muscle-invasive bladder cancer. ANVISA's accelerated pathway is compressing registration timelines for these agents, expanding eligible patient pools in Brazilian public hospital networks ahead of full reimbursement harmonization.
- Chemotherapy:Cisplatin and gemcitabine regimens remain the backbone of first-line systemic therapy. Regional distributors serving Colombia's second-tier cities capture procurement volume through ministry tender participation, though margin compression intensifies with generic substitution.
- Surgery:Transurethral resection of bladder tumor (TURBT) procedures anchor early-stage disease management. Argentine urology clinics maintain rigid capital replacement cycles for resectoscope equipment, delaying adoption of enhanced visualization technologies.
- Radiotherapy:External beam and brachytherapy protocols serve muscle-invasive cases unsuitable for cystectomy. Chilean oncology centers face equipment utilization constraints due to geographic patient dispersion across the Andean corridor.
The dominant share belongs to chemotherapy, while immunotherapy is closing the gap fastest as ANVISA fast-track approvals reshape reimbursement negotiations.
Diagnostic Method:
Volume growth rates diverge sharply between invasive procedural modalities and non-invasive surveillance alternatives, with biomarker testing expanding most quickly in low-risk patient triage protocols.
- Urinary Biomarkers:NMP22 enzyme-linked immunosorbent assays and UroVysion FISH testing enable non-invasive surveillance. Argentine and Colombian urology practices are displacing scheduled cystoscopies in low-risk cohorts, compressing revenue per procedure while expanding total addressable testing volume.
- Cystoscopy:White-light and narrow-band imaging remain the structural gold standard for visual tumor assessment. Brazilian reference laboratories consolidate procurement through multi-year managed service contracts that bundle maintenance and software updates.
- Imaging Techniques:Computed tomography urography and magnetic resonance imaging stage muscle-invasive disease. Peru's diagnostic networks face cold chain and equipment maintenance constraints outside coastal metropolitan corridors.
- Biopsy:Transurethral and image-guided tissue acquisition confirms histological grade and stage. Pathology workflow backlogs in Ecuador and Paraguay create demand for telepathology consultation platforms.
Cystoscopy retains the dominant share, though urinary biomarkers are climbing the fastest as risk-stratified surveillance protocols gain clinical acceptance.
End User:
Procurement authority is shifting from centralized ministry tenders toward direct hospital negotiations, with reference laboratories capturing molecular diagnostic margin expansion.
- Hospitals:Tertiary oncology institutes in São Paulo and Buenos Aires anchor demand for integrated test-and-treat service models. These institutions are restructuring vendor relationships through per-procedure leasing arrangements that operationalize technology refresh cycles.
- Diagnostic Laboratories:Brazilian networks centralize molecular pathology workflows into automated immunohistochemistry and fluorescence in situ hybridization platforms. Talent scarcity for certified molecular biologists constrains capacity expansion in Porto Alegre and Curitiba.
- Clinics:Urology specialty practices in Bogotá and Medellín drive adoption of sequential testing algorithms. Colombian POS reimbursement fragmentation forces parallel value demonstration frameworks for biomarker-guided therapy selection.
- Research Institutions:Academic medical centers generate real-world evidence for ANVISA post-approval safety monitoring. Sponsors invest in dedicated observational study infrastructure to satisfy pharmacovigilance mandates for muscle-invasive immunotherapy indications.
Hospitals command the dominant share, while diagnostic laboratories are gaining share fastest through reference network consolidation.
Drug Class:
Development pipelines and reimbursement negotiations concentrate on targeted mechanisms with companion diagnostic requirements, reshaping competitive positioning across the region.
- Monoclonal Antibodies:Checkpoint inhibitors targeting PD-1 and PD-L1 pathways anchor immuno-oncology portfolios. Bristol-Myers Squibb leverages these relationships with major cancer institutes to secure preferred formulary positioning.
- Targeted Therapies:FGFR inhibitor programs require next-generation sequencing companion diagnostics. Underpenetration in Colombia's regional oncology centers creates first-mover positioning for integrated service models.
- Chemotherapy Agents:Platinum-based and taxane regimens compete on procurement contract scale. Pfizer's volume agreements with regional distributors capture second-tier city access in Argentina and Peru.
- Others:Bacillus Calmette-Guérin intravesical immunotherapy maintains adjuvant positioning in high-risk non-muscle-invasive disease. Supply security concerns persist due to manufacturing concentration outside the region.
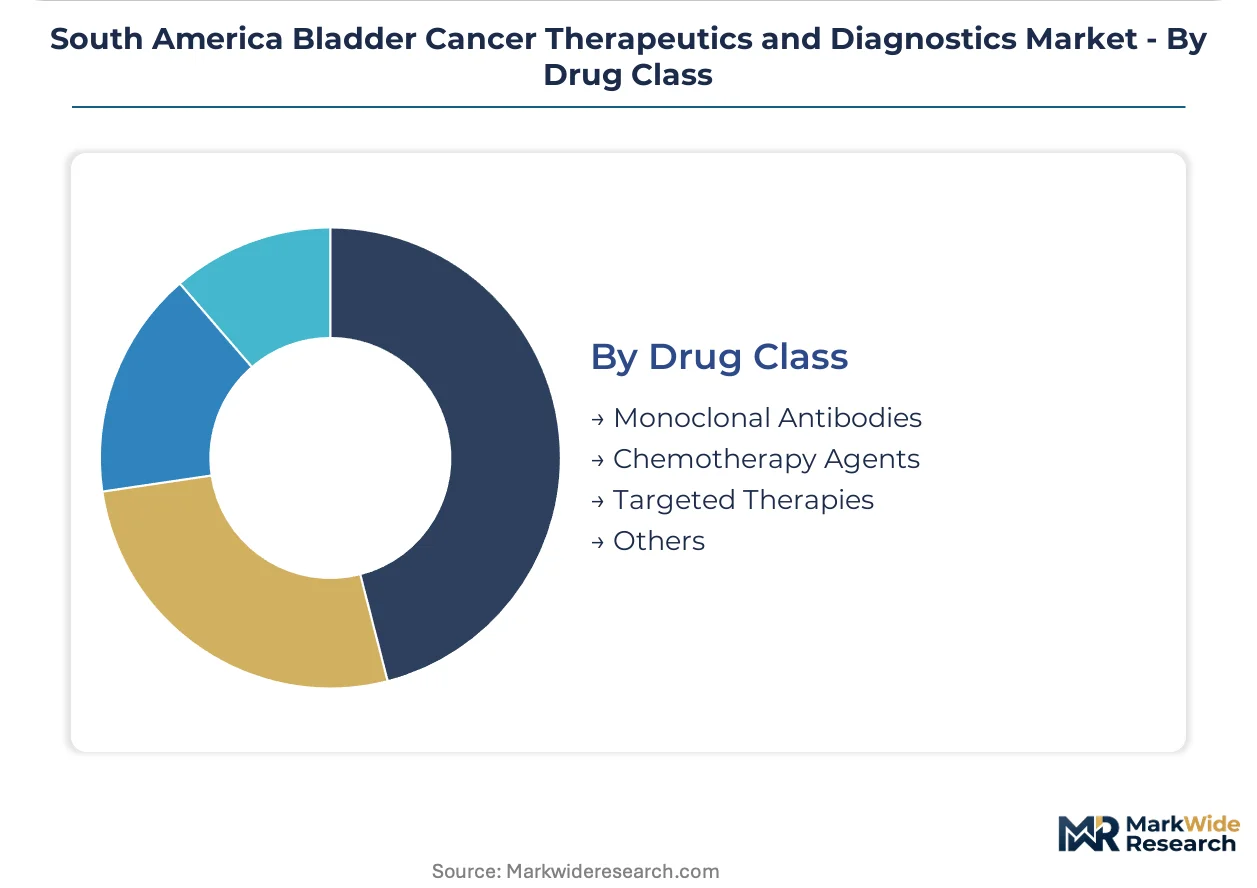
Monoclonal antibodies hold the dominant share, with targeted therapies showing the steepest expansion trajectory as biomarker-guided patient selection protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's pharmaceutical import infrastructure, handling temperature-sensitive immunotherapy biologics destined for São Paulo's oncology networks. This maritime corridor underwrites the country's dominance in regional therapeutic distribution.
Brazil
ANVISA's accelerated pathway for breakthrough therapies compresses registration timelines for PD-1/PD-L1 inhibitors. São Paulo's Hospital das Clínicas and Barretos Cancer Hospital anchor molecular diagnostic procurement through integrated pathology workflow systems. Rio de Janeiro's state oncology network has shifted to per-procedure leasing arrangements for cystoscopy equipment.
Argentina
INAME governs pharmaceutical registration through clinical trial acceptance standards that determine reimbursement list priority. Buenos Aires' public hospital system drives demand for non-invasive surveillance protocols using NMP22 and UroVysion FISH testing. Urology clinics in the capital maintain rigid capital replacement cycles for resectoscope equipment.
Colombia
The POS maintains divergent coverage criteria for biomarker-guided therapy selection compared to regional counterparts. Bogotá and Medellín oncology centers remain underpenetrated for next-generation sequencing-based companion diagnostics. Regional distributors capture chemotherapy volume through ministry tender participation in second-tier cities.
Chile
The country's national pharmaceutical regulator administers oversight comparable to ANVISA and INAME frameworks. Diagnostic networks face cold chain limitations for temperature-sensitive biologics outside coastal metropolitan corridors. Santiago's oncology centers contend with geographic patient dispersion across the Andean corridor.
Peru
Import dependency for cystoscopy optics and resectoscopes exposes procurement budgets to currency volatility against dollar-denominated contracts. Lima's diagnostic networks maintain equipment maintenance constraints outside coastal metropolitan areas. The central bank's monetary policy directly impacts hospital capital expenditure cycles for endoscopic equipment.
South America Bladder Cancer Therapeutics and Diagnostics Market Competitive Landscape
Concentration sits with multinational pharmaceutical conglomerates that leverage immuno-oncology portfolios and integrated diagnostic platforms. Three structural tiers define competitive positioning: checkpoint inhibitor specialists anchoring relationships with major cancer institutes, molecular diagnostics providers consolidating reference laboratory workflows, and regional distributors capturing chemotherapy volume in second-tier cities. Dominant competitive moves include multi-year managed service contracts bundling maintenance and consumables, plus direct hospital negotiations unwinding centralized ministry tenders.
Among North American pharmaceutical conglomerates, Pfizer Inc. and Bristol-Myers Squibb Company occupy positions within distinct competitive archetypes. Pfizer exemplifies the volume-contract specialist serving regional distributors, while Bristol-Myers Squibb represents the immuno-oncology portfolio anchor securing preferred formulary positioning. Swiss-based Roche Holding AG sits within the molecular diagnostics tier, consolidating automated pathology workflows. These three entities collectively illustrate how geographic origin and corporate structure map to divergent strategic positioning across Brazilian and Argentine oncology networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Roche Holding AG |
| Novartis AG |
| Eli Lilly and Company |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Scale economies in immunotherapy biologics manufacturing concentrate production among North American and European facilities, compressing procurement timelines for Brazilian oncology networks while elevating price floors for temperature-sensitive agents that demand specialized cold chain infrastructure. This concentration dynamic anchors vendor negotiation leverage for multinational pharmaceutical conglomerates serving São Paulo's reference laboratories.
Pricing Analysis
Volume-discount tiering structures separate checkpoint inhibitor contracts serving tertiary oncology institutes from generic chemotherapy procurement by regional distributors in second-tier cities. Price differentiation rests on ANVISA registration status and cold chain certification tier, with branded immunotherapy agents commanding substantial premiums over platinum-based regimens. Cost compression in the chemotherapy segment is intensifying because generic substitution pressures from Indian and Chinese API suppliers are eroding margins for regional distributors. Public hospital procurement committees in Brazil exhibit the highest price sensitivity due to ministry tender constraints, while private oncology centers in Buenos Aires demonstrate lower sensitivity for biomarker-guided therapy selection.
Supply Chain Analysis
The Port of Santos transit underwrites distribution of temperature-sensitive biologics to São Paulo's oncology networks, creating a critical chokepoint for immunotherapy agents entering South America. Manufacturing concentration in the United States, Switzerland, and Germany feeds the region's dependence on imported monoclonal antibodies and molecular diagnostic platforms. Raw material dependencies span recombinant protein production cell lines, specialized reagents for immunohistochemistry workflows, and optical components for cystoscopy systems. Single-source vulnerability persists for FGFR inhibitor companion diagnostics manufactured at limited European facilities. Distribution runs through multi-tier structures: direct manufacturer relationships with Brazilian reference laboratories, regional distributors capturing Argentine and Colombian volume, and ministry tender channels serving public hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from non-invasive urinary biomarker surveillance protocols that are displacing cystoscopy revenue in low-risk patient cohorts across Argentine and Colombian urology practices.
For Market Incumbents: Secure molecular diagnostic procurement relationships with São Paulo's Hospital das Clínicas and Barretos Cancer Hospital through multi-year managed service contracts that bundle equipment maintenance with consumable supply. Anchor preferred formulary positioning for checkpoint inhibitors by investing in real-world evidence generation infrastructure that satisfies ANVISA post-approval pharmacovigilance mandates. Backward integration into cold chain logistics capabilities mitigates distribution constraints in Amazon basin states. For New Entrants and Emerging Players: ANVISA's accelerated review pathway for breakthrough oncology therapies enables faster market access for novel immuno-oncology agents than comparable INAME processes in Argentina. Target Bogotá and Medellín oncology centers for next-generation sequencing-based companion diagnostic deployment, as these facilities remain underpenetrated for integrated test-and-treat service models. A telepathology platform go-to-market angle bypasses capital-intensive laboratory builds in Ecuador and Paraguay while extending specialist pathology coverage. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors molecular diagnostics providers consolidating automated pathology workflows in Brazilian reference networks over standalone therapeutic developers facing reimbursement fragmentation. Long-term viability hinges on regulatory harmonization progress across MERCOSUR member states and the depth of real-world evidence infrastructure supporting post-approval safety monitoring. Acquisition targets should demonstrate established relationships with tertiary oncology institutes and captive demand from per-procedure leasing arrangements. The signal to watch is INAME's alignment with MERCOSUR clinical trial data standards, which would reduce redundant evidence generation costs and accelerate multi-country registration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Accelerated Review Pathway | Compresses registration timelines for PD-1/PD-L1 inhibitors ahead of full reimbursement harmonization. |
| Multi-Year Managed Service Contracts | Bundles cystoscopy maintenance and software updates for Rio de Janeiro's state oncology network. |
| Telepathology Network Expansion | Extends specialist pathology coverage into Ecuador and Paraguay without capital-intensive laboratory builds. |
| Real-World Evidence Infrastructure | Satisfies ANVISA pharmacovigilance mandates for muscle-invasive bladder cancer immunotherapy indications. |
| Next-Generation Sequencing Deployment | Captures first-mover positioning in underpenetrated Bogotá and Medellín oncology centers. |
Research Methodology
Desk research of ANVISA registration databases, INAME pharmaceutical filings, and ClinicalTrials.gov oncology trial records preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across Brazilian and Argentine oncology networks. Secondary validation drew from hospital procurement databases, GPO contracts, and formulary listing records. Bottom-up therapeutic volume modeling triangulated against top-down market sizing from regional distributor revenue disclosures.
Variance decomposition across treatment type, diagnostic method, end user, and drug class dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and pricing trend analysis. Forecast inputs incorporated ANVISA approval velocity metrics, urinary biomarker adoption curves in Argentine urology clinics, and reference laboratory consolidation patterns in Brazilian diagnostic networks.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA accelerated pathway utilization or cold chain infrastructure investment in northern Brazil would require recalibration. Forecasts reflect documented assumptions regarding reimbursement harmonization progress and molecular pathology talent pipeline development. Practitioners should keep alternative scenarios live as INAME regulatory alignment and regional currency volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Vulvar Cancer Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Europe Proton Therapy Market
Oncology
Paranasal Sinus Cancer Market
Oncology
North America Proton Therapy Market
Oncology
Pancreatic Cancer Market
Oncology
Europe Radiotherapy Market
Oncology
Metastatic Cancer Drug Market
Oncology
Global Cancer Profiling Market
Oncology
Global Interventional Oncology Market
Oncology
Gynecological Cancers Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Laser Cancer Therapy Market
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
Glottic Cancer Treatment Market
Oncology
Asia-Pacific Proton Therapy Market