
 Particle Therapy Systems Market | 2026-2036
Particle Therapy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Particle Therapy Systems Market Insights
The capital-intensity divergence between compact single-room proton systems and multi-gantry heavy-ion centers is collapsing as cyclotron miniaturization cuts facility costs by half. Varian Medical Systems leverages its installed base of ProBeam platforms to sustain service revenue across North American hospital networks. IBA Worldwide anchors European proton therapy expansion through its ProteusONE compact system architecture. Mevion Medical Systems differentiates via superconducting synchrocyclotron technology that eliminates the need for beam transport lines.
Particle therapy systems deliver precisely targeted radiation using protons or heavier ions, with Bragg peak energy deposition enabling dose conformity within millimeters of tumor boundaries while sparing adjacent healthy tissue. The primary commercial purpose centers on treating pediatric cancers, ocular melanomas, and skull-base tumors where photon toxicity risks exceed therapeutic margins. Particle accelerators dominate capital expenditure allocation, while treatment planning systems capture recurring software license revenue as institutions upgrade Monte Carlo algorithms. Proton therapy leads treatment technique adoption, though heavy ion therapy commands premium reimbursement in select Japanese and German centers where carbon-ion efficacy data has matured.
FDA radiation-emitting product regulations and NRC radioactive materials licensing requirements shape system design standards and installation timelines across United States facilities. CE marking under EU MDR and ISO 13485 quality management frameworks govern European market access, with EMA clinical evidence expectations influencing reimbursement negotiations in member states. Stakeholders must monitor how FDA breakthrough device designations for combined modality platforms reshape competitive dynamics between established proton vendors and emerging boron neutron capture therapy developers.
Market Dynamics
Cyclotron miniaturization is collapsing the capital-intensity gap between compact single-room proton systems and multi-gantry heavy-ion centers, forcing vendors to restructure pricing architectures and facility partnership models.
Growth Catalysts
- Reimbursement Stabilization:CMS proton therapy coverage determinations in the United States have clarified billing codes, reducing institutional uncertainty and accelerating capital commitment cycles at academic medical centers.
- Pediatric Oncology Protocols:Bragg peak dose conformity drives adoption for pediatric CNS tumors where photon scatter toxicity carries lifetime morbidity consequences, concentrating demand at children's hospitals with dedicated proton suites.
- Heavy-Ion Efficacy Maturation:Carbon-ion clinical data accumulation in Japan and Germany commands premium reimbursement rates, validating multi-ion facility economics and attracting institutional investment in dual-modality centers.
Market Restraints
- Superconducting Magnet Supply Concentration:Niobium-titanium superconductor fabrication capacity concentrates among three specialized foundries, creating procurement bottlenecks for synchrocyclotron manufacturers scaling production.
- NRC Licensing Friction:Radioactive materials licensing requirements for decommissioned beam lines extend facility modification timelines by 18-24 months, trapping capital in non-revenue-generating construction phases.
- Photon IMRT Substitution:Volumetric-modulated arc therapy advancement narrows the dosimetric advantage gap for prostate and lung indications, compressing proton therapy's addressable patient population in cost-sensitive markets.
Strategic Opportunities
- India Private Hospital Expansion:Apollo Hospitals and Tata Memorial Centre partnerships signal proton therapy entry into South Asia's medical tourism corridor, with BIS medical device registration pathways under active negotiation.
- Boron Neutron Capture Therapy Convergence:FDA breakthrough device designation pathways for combined proton-neutron platforms create white space for next-generation modality developers to leapfrog established cyclotron vendors.
- Mobile Proton Deployment:Gantry-on-rail architectures enable treatment delivery at community oncology networks, bypassing the $150M+ fixed-facility capital barrier that has constrained market penetration.
Industry Challenges
- Medical Physics Talent Scarcity:Commissioning and clinical operation of particle therapy systems requires board-certified proton therapy physicists, with training pipeline output lagging installed base expansion by approximately 40%.
- Monte Carlo Algorithm Validation:Treatment planning system upgrades demand extensive beam model commissioning, stretching clinical implementation timelines and delaying software license revenue recognition.
- Legacy Linen Integration:Existing photon vault shielding specifications often prove inadequate for proton beam energies, forcing costly civil reconfiguration or greenfield site selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Particle Therapy Systems Market |
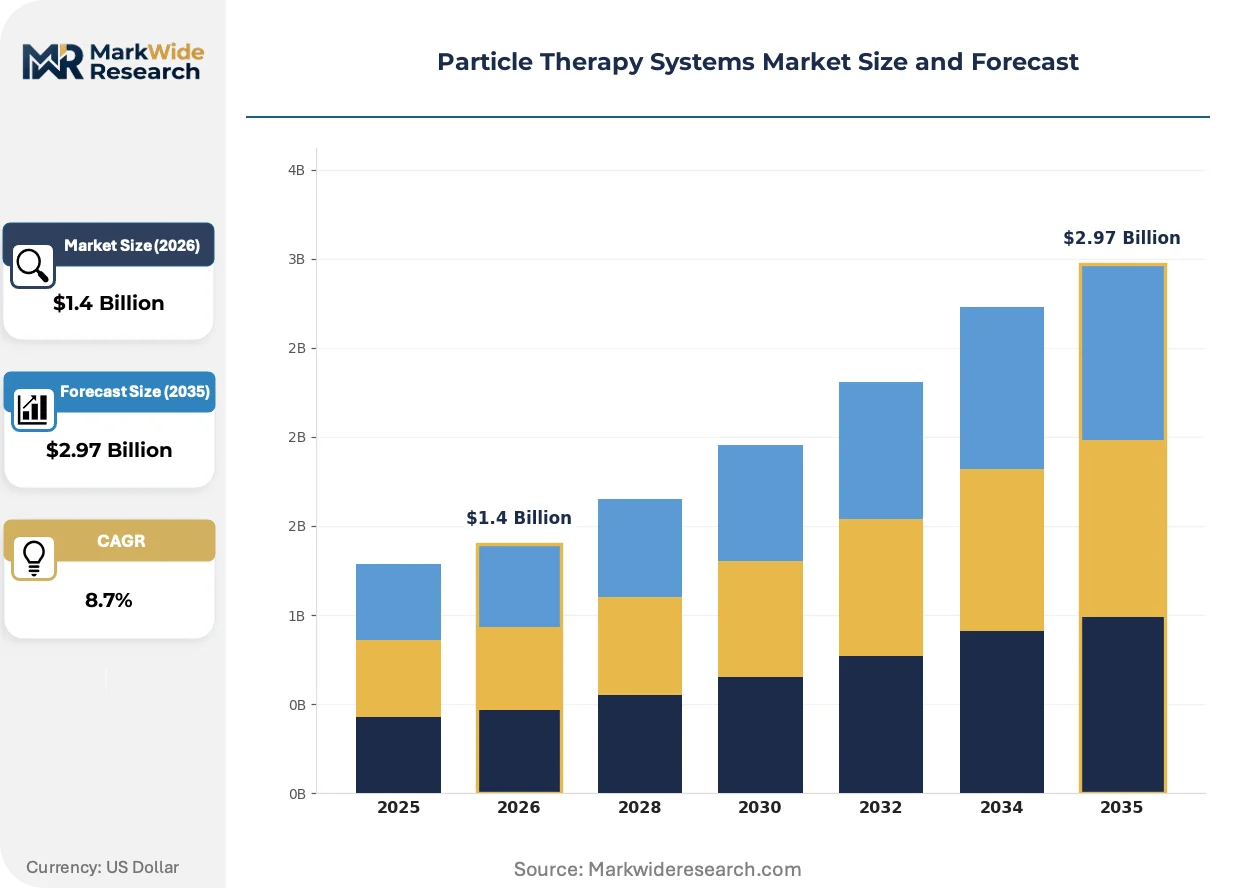
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Particle Accelerators, Treatment Planning Systems, Patient Positioning Systems, Quality Assurance Systems Treatment Technique: Proton Therapy, Heavy Ion Therapy, Boron Neutron Capture Therapy, Combined Modality Therapy End User: Hospitals, Cancer Treatment Centers, Research Institutions, Specialized Clinics Service Type: Installation Services, Maintenance Services, Training Services, Consulting Services |
| Companies Covered | Varian Medical Systems, IBA Worldwide, Hitachi, Mevion Medical Systems, Sumitomo Heavy Industries, Provision Healthcare, ProTom International, Optivus Proton Therapy, Advanced Oncotherapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Particle Therapy Systems Market Trends and Innovations
Particle therapy system architecture is fragmenting into divergent technical philosophies, with compact cyclotron vendors racing heavy-ion synchrotron developers to define the dominant facility-scale paradigm for the next decade.
Superconducting synchrocyclotron design is bifurcating the accelerator technology landscape. Direct-mounted gantry systems eliminate beam transport lines, cutting facility footprint by 60% and enabling single-room installations at community hospitals. Mevion and Varian are deploying these architectures aggressively in the United States. The technology is compressing the minimum viable proton center investment threshold from $200M toward $40M, democratizing access beyond academic medical centers.
EU MDR clinical evidence requirements are reshaping European market entry economics. CE marking under the 2017/745 regulation now demands prospective clinical data for software-as-medical-device treatment planning systems, extending regulatory timelines by 12-18 months. IBA Worldwide and Hitachi are front-loading clinical trial investment in Germany and France to preempt reimbursement negotiation disadvantages. The shift favors incumbents with established European installed bases over Asian challengers seeking initial market access.
Hospital procurement departments are unbundling service contracts from capital equipment purchases. Previously captive 10-year service agreements are being disaggregated into component-level maintenance, software support, and physics staffing tiers. United States health systems with multiple proton centers are centralizing physics workforce management, forcing vendors to compete on discrete service modules rather than bundled lifetime contracts. This restructuring is most visible in the Texas Medical Center and Boston hospital clusters.
Particle Therapy Systems Market Segmentation
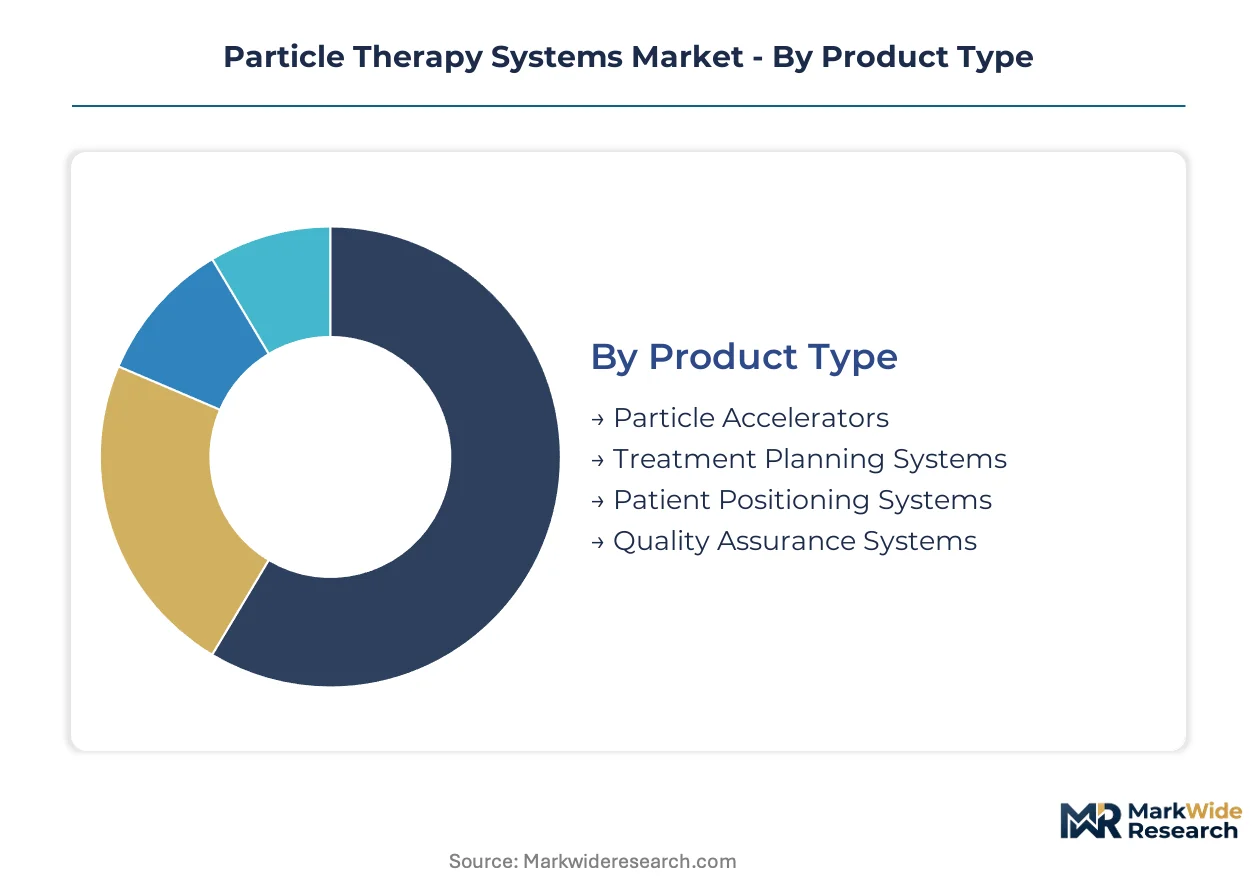
Particle therapy system procurement follows distinct budget allocation patterns across hardware, software, and service categories. Each segment carries different margin profiles and vendor competitive dynamics that reshape how institutions structure capital deployment and operational partnerships.
Product Type:
Margin pools concentrate in particle accelerators where superconducting magnet technology creates vendor differentiation and pricing power, while software components face compressed margins from open-source algorithm competition.
- Particle Accelerators:Cyclotron and synchrotron architectures generate proton or heavy ion beams through electromagnetic acceleration. Demand clusters at academic medical centers in the United States, Germany, and Japan where reimbursement stability justifies capital intensity. Superconducting synchrocyclotron miniaturization is collapsing facility cost barriers.
- Treatment Planning Systems:Monte Carlo-based dose calculation software enables millimeter-precision tumor targeting with Bragg peak optimization. Children's hospitals with dedicated proton suites drive upgrade cycles as pediatric protocols demand algorithmic refinement for CNS tumor applications.
- Patient Positioning Systems:Robotic couch assemblies with sub-millimeter reproducibility anchor immobilization workflows for cranial and spinal indications.
- Quality Assurance Systems:Beam monitoring and dosimetry validation equipment ensures regulatory compliance across NRC-licensed facilities.
Particle Accelerators holds installed capacity. Treatment Planning Systems is rotating up the share rankings.
Treatment Technique:
Volume distribution splits between established proton infrastructure and emerging heavy-ion modalities where premium reimbursement creates margin expansion opportunities.
- Proton Therapy:Bragg peak energy deposition spares adjacent healthy tissue compared to photon scatter. Community hospital networks in the United States are adopting compact single-room systems as capital thresholds fall toward $40M.
- Heavy Ion Therapy:Carbon-ion beams deliver higher linear energy transfer with enhanced biological effectiveness for radioresistant tumors. Japan's National Institute of Radiological Sciences and Germany's Heidelberg Ion-Beam Therapy Center anchor global capacity.
- Boron Neutron Capture Therapy:Binary radiation modality combines thermal neutron delivery with boron-10 tumor targeting for glioblastoma applications.
- Combined Modality Therapy:Integrated proton-neutron platforms under FDA breakthrough device designation pathway are attracting venture investment for next-generation facility architectures.
Proton Therapy holds installed capacity. Heavy Ion Therapy is rotating up the share rankings.
End User:
Customer-type segmentation reveals procurement sophistication divergence between integrated health systems and standalone research facilities.
- Hospitals:Academic medical centers with existing radiation oncology departments dominate capital deployment, leveraging CMS proton therapy coverage clarity to accelerate commitment cycles. Texas Medical Center and Boston hospital clusters are centralizing physics workforce management across multiple centers.
- Cancer Treatment Centers:Dedicated oncology networks prioritize throughput optimization and fractionation efficiency for prostate and lung indications.
- Research Institutions:National laboratories and university medical schools drive heavy-ion clinical trial infrastructure.
- Specialized Clinics:Ocular melanoma and skull-base tumor focused facilities exploit compact system footprints for niche indication capture.
Hospitals hold installed capacity. Cancer Treatment Centers is rotating up the share rankings.
Service Type:
Procurement disaggregation is fragmenting previously bundled contracts into discrete purchasing decisions with distinct vendor selection criteria.
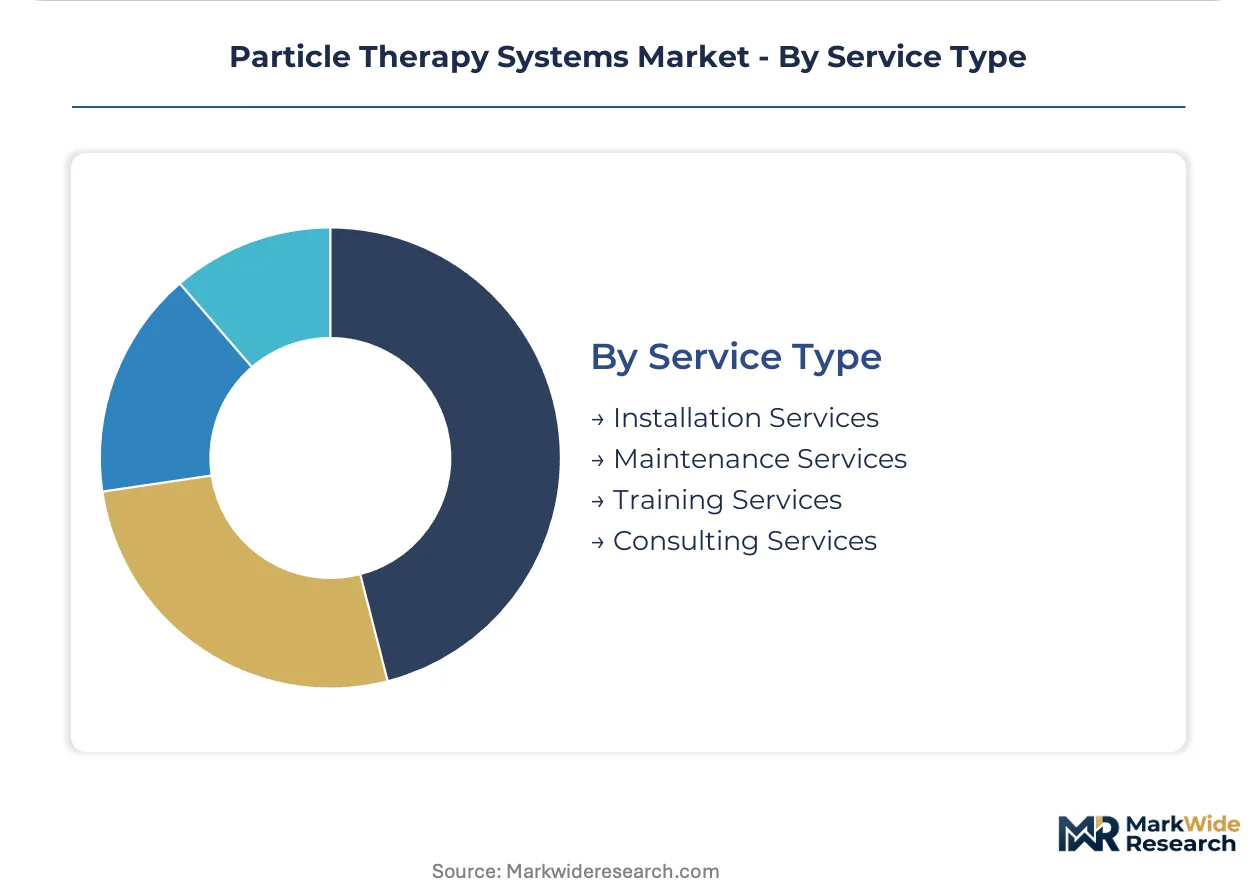
- Installation Services:Civil construction coordination and shielding validation for proton vault specifications. NRC radioactive materials licensing requirements extend facility modification timelines by 18-24 months.
- Maintenance Services:Superconducting magnet cryogenic system upkeep and beam line calibration. Niobium-titanium fabrication capacity concentration among three specialized foundries creates procurement bottlenecks.
- Training Services:Board-certified proton therapy physicist pipeline development lags installed base expansion by approximately 40%.
- Consulting Services:Operational workflow optimization and reimbursement navigation support for new market entrants.
Maintenance Services holds installed capacity. Training Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Academic medical centers in the United States absorb premium pricing for multi-gantry installations, while Indian private hospital groups negotiate aggressively on compact single-room system procurement.
United States
Texas Medical Center and Boston hospital clusters anchor installed capacity expansion. CMS proton therapy coverage determinations clarified billing codes in 2023, reducing institutional uncertainty. MD Anderson Cancer Center and Massachusetts General Hospital centralize physics workforce management across multiple proton centers.
Germany
Heidelberg Ion-Beam Therapy Center validates heavy-ion facility economics through carbon-ion clinical data accumulation. EU MDR clinical evidence requirements under 2017/745 regulation extend software registration timelines. Munich and Berlin academic networks drive dual-modality center investment.
Japan
National Institute of Radiological Sciences commands premium reimbursement rates for carbon-ion efficacy data. METI industrial policy supports domestic synchrotron manufacturing capacity. Chiba and Hyogo prefectures concentrate heavy-ion treatment infrastructure.
India
Apollo Hospitals and Tata Memorial Centre partnerships signal proton therapy entry into medical tourism corridors. BIS medical device registration pathways remain under active negotiation. Mumbai and Delhi-NCR private hospital groups target compact system deployment.
United Kingdom
NHS England proton commissioning frameworks restrict new facility approval to evidence-based indications. MHRA post-Brexit regulatory alignment with EU MDR creates transitional uncertainty. Manchester and London academic radiotherapy networks consolidate pediatric referral pathways.
Particle Therapy Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cyclotron manufacturers and synchrotron developers occupying distinct technical lanes. The structure concentrates around three strategic archetypes: superconducting compact system vendors, multi-gantry heavy-ion platform builders, and combined-modality platform developers. Competitive moves center on unbundling previously captive service contracts and accelerating FDA breakthrough device pathways for neutron-convergent architectures.
Within the integrated systems tier, Varian Medical Systems and IBA Worldwide exemplify divergent geographic anchoring strategies, with the former representing North American hospital network penetration and the latter occupying European proton expansion leadership. Mevion Medical Systems sits within the superconducting specialization vector, its company name signaling medical-technology focus. These three entities collectively illustrate how vendor positioning fragments across technical philosophy rather than converging on unified platform standards.
| Leading Market Players |
|---|
| Varian Medical Systems |
| IBA Worldwide |
| Hitachi |
| Mevion Medical Systems |
| Sumitomo Heavy Industries |
| Provision Healthcare |
| ProTom International |
| Optivus Proton Therapy |
| Advanced Oncotherapy |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts with embedded physics staffing tiers lock in both superconducting magnet supply access and predictable cost visibility across United States proton center networks. These multi-year agreements insulate cyclotron manufacturers from spot procurement volatility while anchoring hospital budgeting around fixed operational expenditure profiles.
Pricing Analysis
After-sales maintenance revenue tiers now dominate lifetime value capture for particle accelerator vendors. Three-tier pricing structure across premium multi-gantry installations, standard single-room systems, and economy compact configurations stratifies by beam energy capability and service bundling depth. Cost compression in the standard tier intensifies as photon IMRT advancement narrows proton's dosimetric advantage for prostate indications. Community hospital networks exhibit highest price sensitivity, while academic medical centers with dedicated pediatric protocols demonstrate lowest elasticity.
Supply Chain Analysis
United States, Germany, and Japan anchor superconducting synchrocyclotron fabrication capacity for proton therapy deployment. Niobium-titanium superconductor wire, precision cryogenic cooling systems, and radiation-hardened beam monitoring sensors draw from specialized foundries concentrated in these geographies. Single-source vulnerability concentrates in superconducting magnet supply, where three specialized foundries control global output. Distribution runs through direct vendor-hospital partnerships with embedded installation and commissioning protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Particle therapy systems face sustained substitution pressure from volumetric-modulated arc therapy advancement, forcing incumbents to articulate clear clinical differentiation beyond dosimetric margin gains.
For Market Incumbents: Fortify service contract unbundling defenses by centralizing physics workforce management across hospital clusters, stripping vendor pricing power from discrete maintenance modules. Accelerate FDA breakthrough device pathway submissions for combined proton-neutron platforms to preempt boron neutron capture therapy entrants from capturing next-generation modality positioning. For New Entrants and Emerging Players: Lead with mobile gantry-on-rail architectures targeting community oncology networks in cost-sensitive United States markets, bypassing fixed-facility capital barriers that constrain incumbent penetration. Pursue BIS medical device registration in India through Apollo Hospitals and Tata Memorial Centre partnerships, exploiting South Asia's medical tourism corridor as the most penetrable geography for compact single-room deployment. For Investors and Strategic Acquirers: Superconducting magnet technology specialists with captive cryogenic system capabilities represent priority acquisition targets, given supply concentration and procurement bottleneck exposure. Long-term viability hinges on dual-modality center economics maturation across German and Japanese reimbursement frameworks. Watch carbon-ion clinical data accumulation at Heidelberg Ion-Beam Therapy Center and National Institute of Radiological Sciences as inflection indicators for heavy-ion facility investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Hospital procurement departments now disaggregate 10-year agreements into discrete physics staffing, software support, and component maintenance tiers. |
| Superconducting Synchrocyclotron Miniaturization | Mevion and Varian deployments eliminate beam transport lines, collapsing facility footprints by 60% and cutting capital thresholds toward $40M. |
| FDA Breakthrough Device Pathway | Combined proton-neutron platforms attract venture investment by leapfrogging established cyclotron vendors in glioblastoma applications. |
| EU MDR Clinical Evidence Front-Loading | IBA Worldwide and Hitachi extend trial investment in Germany and France to preempt reimbursement negotiation disadvantages under 2017/745 regulation. |
| Mobile Proton Deployment | Gantry-on-rail architectures enable treatment delivery at community oncology networks, bypassing fixed-facility capital barriers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across proton therapy physicists, hospital procurement committee members, biomedical engineers at academic medical centers, and GPO contracts managers. Primary interview insights triangulated against FDA 510(k) clearance databases, NRC radioactive materials licensing records, CMS proton therapy coverage determinations, and EU MDR CE marking submissions under 2017/745 regulation. Bottom-up installed base enumeration across United States, German, and Japanese facilities cross-validated with top-down capital expenditure aggregation from hospital network disclosures.
Across the analysis window, the forecast framework models particle accelerator hardware, treatment planning software, and service revenue streams segmented by proton versus heavy-ion technique, compact single-room versus multi-gantry facility scale, and hospital versus cancer treatment center end-user archetype. CAGRs derive from reimbursement framework stability indices, cyclotron miniaturization cost curves, and pediatric oncology protocol expansion rates. Monte Carlo algorithm upgrade cycles and superconducting magnet replacement timelines feed industry-specific demand elasticity parameters.
The analysis sits within stated boundaries; outcomes outside sustained CMS proton therapy coverage clarity, stable niobium-titanium superconductor supply, or continued Bragg peak dosimetric advantage for CNS tumors would require recalibration. Forecasts reflect assumptions around physics workforce pipeline expansion lagging installed base growth and EU MDR software registration timeline extensions. Recalibration cycles align with material shifts in carbon-ion efficacy data maturation, boron neutron capture therapy FDA designation progress, and photon IMRT technological advancement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Glottic Cancer Treatment Market
Oncology
Internal Radiation Therapy Market
Oncology
Oncology Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Pharyngeal Neoplasm Market
Oncology
Immuno-Oncology Clinical Trials Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Pituitary Cancer Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Radiation Therapy Software Market
Oncology
Head and Neck Cancer Market
Oncology
Angiosarcomas Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
Ustekinumab Market