
 AI in Oncology Market | 2026-2036
AI in Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Oncology Market Intelligence
FDA 510(k) and De Novo clearance cycles for Software as a Medical Device are reorganizing competitive entry in AI oncology, raising the barrier for unvalidated algorithms. Siemens Healthineers leverages its installed base of imaging equipment to distribute integrated AI diagnostics directly through hospital radiology departments. NVIDIA Corporation anchors the market through GPU infrastructure and MONAI framework support that underpins most commercial imaging analytics pipelines. PathAI specializes in digital pathology AI, sustaining competitive position through exclusive laboratory partnerships and proprietary staining protocols.
AI in oncology encompasses machine learning algorithms, natural language processing systems, and imaging analytics platforms designed to detect malignancies, predict treatment response, and optimize therapeutic protocols from multimodal patient data. These systems process histopathological slides, radiological scans, genomic sequences, and electronic health records to augment clinician decision-making in screening, diagnosis, and personalized care planning. Diagnostic tools currently lead product type revenue, while treatment personalization applications within clinical decision support represent the fastest-expanding segment as providers seek to reduce trial-and-error in chemotherapy and immunotherapy selection. Pharmaceutical companies are emerging as high-growth end users, deploying predictive analytics to compress oncology drug discovery timelines and improve patient stratification for clinical trials.
The FDA Software as a Medical Device framework and HIPAA interoperability rules shape product development roadmaps and data governance requirements for US market access, while the EU AI Act and MDR impose additional conformity obligations for European deployment. EMA guidance on AI in medicinal product lifecycle management is creating parallel compliance tracks that favor vendors with transatlantic regulatory capabilities. Stakeholders must monitor evolving FDA guidance on adaptive algorithms and pre-determined change control plans, as these will determine which platforms can iterate clinically without repeated submissions.
Market Dynamics
FDA Software as a Medical Device clearance pathways are compressing competitive entry timelines while simultaneously elevating validation requirements for machine learning algorithms in radiology and pathology applications.
Growth Catalysts
- De Novo clearance framework:The FDA's streamlined pathway for novel AI diagnostics accelerates market entry for first-in-class algorithms, reducing premarket review cycles for imaging analytics platforms.
- Pharmaceutical predictive analytics:Oncology drug developers deploy AI to compress patient stratification timelines and optimize clinical trial enrollment protocols.
- Community hospital network expansion:Regional health systems across the United States are standardizing procurement of integrated imaging analytics to augment radiologist capacity.
Market Restraints
- GPU supply concentration:Specialized accelerator hardware for training and inference depends on a limited supplier base, creating procurement bottlenecks for imaging analytics vendors.
- Interoperability friction:HIPAA data governance requirements impose architectural constraints on multimodal patient data integration across electronic health record systems.
- Validation cost structure:Prospective clinical studies required for FDA clearance impose seven-figure expenditure minimums, excluding undercapitalized algorithm developers.
Strategic Opportunities
- EU AI Act compliance services:The European Union's risk-based classification system for medical AI creates advisory and technical implementation demand for transatlantic vendors.
- Digital pathology laboratory partnerships:Exclusive staining protocol development with academic medical centers locks in proprietary training data access for algorithm refinement.
- Natural language processing convergence:Integration of clinical note extraction with imaging analytics enables comprehensive patient risk scoring beyond radiological features alone.
Industry Challenges
- Adaptive algorithm governance:FDA guidance on predetermined change control plans remains unsettled, creating uncertainty for vendors seeking to iterate models without repeated submissions.
- Multimodal data engineering talent:Scarce expertise in harmonizing histopathological, genomic, and radiological data streams constrains product development velocity.
- Legacy PACS integration:Hospital picture archiving and communication systems require custom middleware development, extending deployment timelines and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Oncology Market |
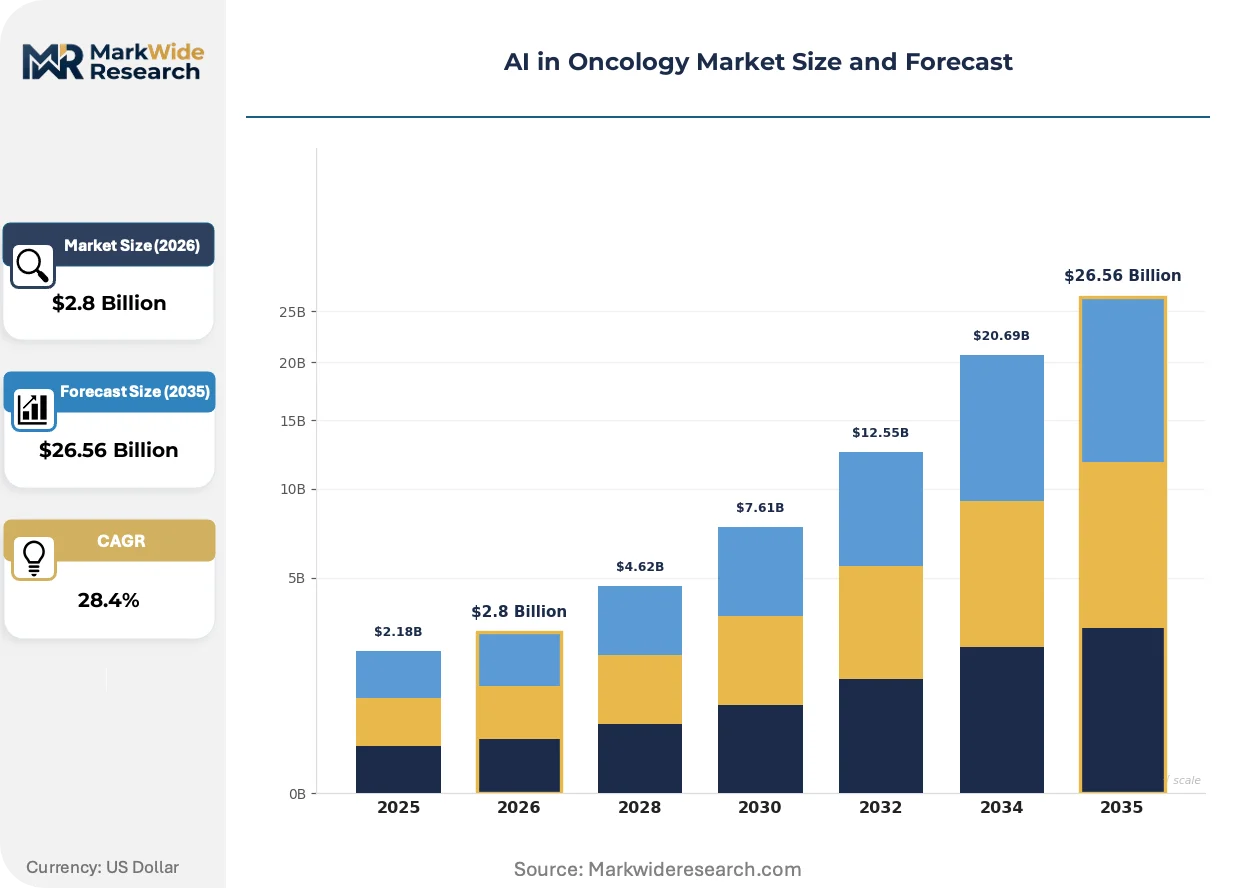
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Treatment Planning Software, Patient Monitoring Systems, Radiotherapy Solutions End User: Hospitals, Oncology Clinics, Research Institutions, Pharmaceutical Companies Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Imaging Analytics Application: Patient Stratification, Drug Discovery, Clinical Decision Support, Treatment Personalization |
| Companies Covered | Siemens Healthineers, GE Healthcare, NVIDIA Corporation, ConcertAI, IBM, PathAI, Azra AI, Medtronic, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Oncology Market Strategic Shifts & Innovations
Foundation models trained on multimodal oncology datasets are compressing algorithm development cycles and enabling zero-shot diagnostic capabilities previously requiring extensive supervised learning.
Generative adversarial networks for synthetic histopathological image generation are bifurcating the training data landscape. Academic medical centers with limited biopsy archives adopt synthetic augmentation to develop rare-cancer detection algorithms. This capability is compressing the competitive advantage of institutions with legacy tissue biobanks.
The EU AI Act's high-risk system classification is mandating conformity assessment procedures for oncology diagnostic algorithms deployed in European Union member states. Medical device manufacturers must implement post-market monitoring systems and algorithmic transparency documentation. Vendors with existing MDR technical file infrastructure are adapting quality management systems to accommodate the additional AI-specific obligations.
Hospital procurement committees are consolidating vendor relationships around integrated platform solutions rather than point algorithms. Community health systems favor single-source contracts covering radiology, pathology, and clinical decision support modules. This preference consolidation is most visible in United States metropolitan markets where integrated delivery networks command substantial purchasing leverage.
AI in Oncology Market Segmentation
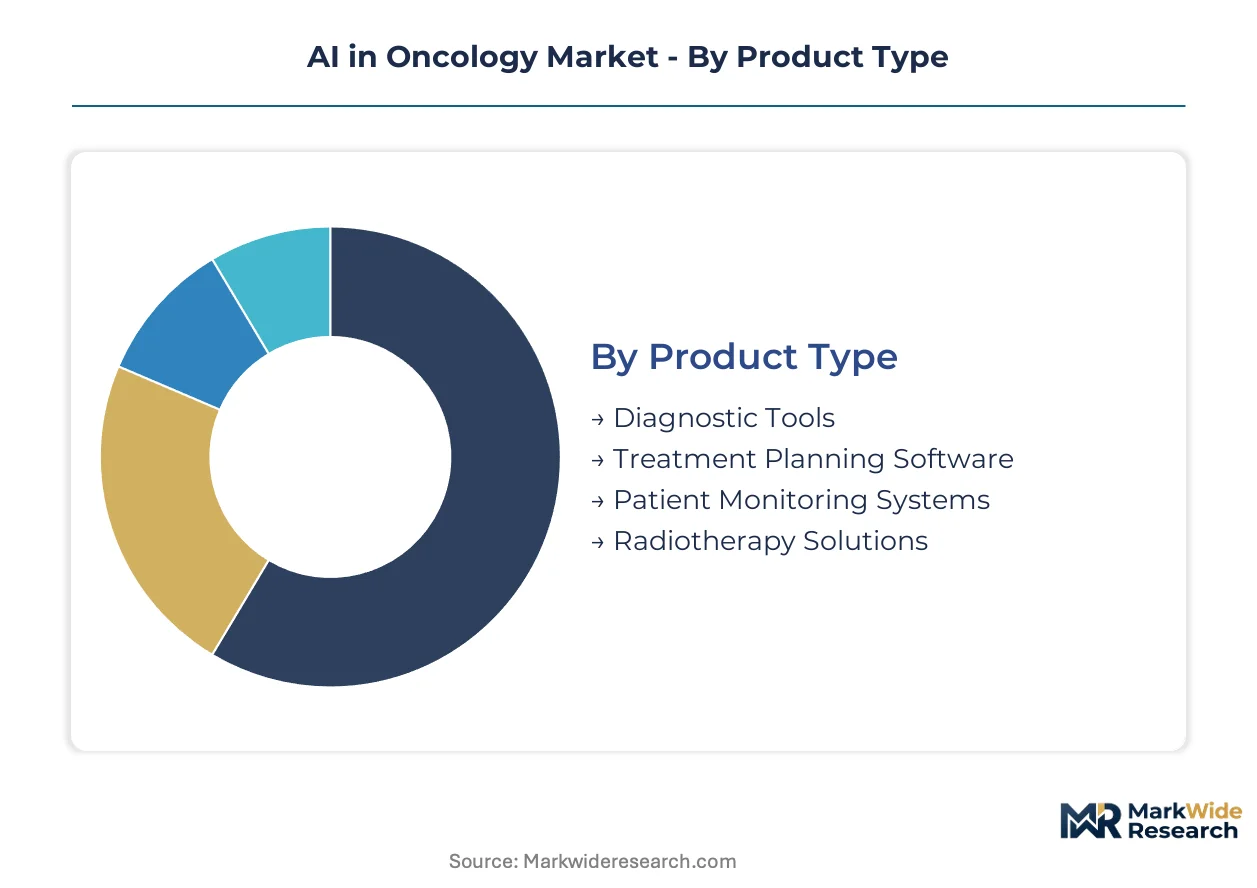
Segmentation in AI oncology reveals how value migrates across clinical workflows, from detection through therapeutic intervention. Distinct technology stacks and regulatory pathways govern each category's competitive dynamics and margin capture potential.
Product Type:
Margin pools concentrate in solutions that integrate directly into reimbursable clinical workflows rather than standalone research tools.
- Diagnostic Tools:Machine learning algorithms for radiology and pathology interpretation process CT, MRI, and histopathological slides to flag malignancies. United States academic medical centers deploy these at scale to augment radiologist throughput. FDA 510(k) clearance requirements elevate validation costs, compressing vendor margins for undercapitalized entrants.
- Treatment Planning Software:AI-driven dose optimization and organ-at-risk segmentation for radiation oncology. Community hospital networks in the United States favor these modules for their direct reimbursement tie-ins and workflow efficiency gains.
- Patient Monitoring Systems:Continuous biomarker tracking and adverse event prediction platforms.
- Radiotherapy Solutions:Adaptive planning algorithms that adjust treatment parameters based on anatomical changes during fractionated therapy.
Diagnostic Tools holds installed capacity. Treatment Planning Software is rotating up the share rankings.
End User:
Procurement authority and budget scale vary sharply across purchaser categories, shaping pricing power and contract structure.
- Hospitals:Integrated delivery networks and standalone facilities with radiology departments as primary deployment sites. United States metropolitan health systems command substantial purchasing leverage through consolidated vendor relationships.
- Pharmaceutical Companies:Predictive analytics for patient stratification and clinical trial optimization. These deployments compress oncology drug discovery timelines and improve enrollment protocol efficiency.
- Oncology Clinics:Specialized outpatient facilities focusing on infusion therapy and radiation treatment.
- Research Institutions:Academic medical centers developing proprietary algorithms and training datasets.
Hospitals anchor procurement volume. Pharmaceutical Companies are climbing the fastest as high-growth spenders.
Technology:
Technical architecture determines infrastructure dependencies and talent requirements for implementation.
- Machine Learning:Supervised and unsupervised learning models for pattern recognition across imaging and genomic datasets. NVIDIA GPU clusters underpin most commercial training pipelines, creating hardware concentration risk.
- Imaging Analytics:Computer vision systems for radiological and histopathological interpretation. United States FDA Software as a Medical Device framework governs clearance pathways for these platforms.
- Natural Language Processing:Clinical note extraction and unstructured data harmonization.
- Predictive Analytics:Prognostic modeling for treatment response and survival outcomes.
Machine Learning holds installed capacity. Imaging Analytics is rotating up the share rankings.
Application:
Clinical utility and reimbursement alignment separate commercially viable deployments from research-phase experiments.
- Treatment Personalization:AI-driven chemotherapy and immunotherapy selection protocols that reduce trial-and-error prescribing. United States community hospital networks deploy these to standardize care across geographically dispersed sites.
- Clinical Decision Support:Real-time recommendations integrated into electronic health record workflows.
- Patient Stratification:Biomarker-based cohort identification for targeted therapy eligibility.
- Drug Discovery:Target identification and compound screening acceleration for pharmaceutical pipelines.
Treatment Personalization is expanding most quickly. Clinical Decision Support holds installed capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States concentrate purchasing authority for AI diagnostic platforms. Academic medical centers in Germany and community networks in Japan drive comparable demand intensity. Regulatory divergence between FDA Software as a Medical Device pathways and EU AI Act conformity procedures shapes vendor prioritization.
United States
Integrated delivery networks in metropolitan markets standardize procurement of imaging analytics platforms across radiology departments. FDA 510(k) and De Novo clearance frameworks accelerate market entry for validated algorithms while elevating validation costs. The Greater Boston cluster anchors digital pathology development through exclusive laboratory partnerships with academic medical centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia deploy AI-driven radiation oncology planning systems to augment physicist capacity. EU AI Act high-risk system classification and MDR conformity assessment procedures govern product deployment. The Baden-Württemberg medical technology corridor concentrates imaging equipment manufacturing with integrated AI diagnostics distribution.
Japan
Community hospital networks in the Kanto region adopt machine learning algorithms for gastric and colorectal cancer screening programs. PMDA consultation pathways for Software as a Medical Device guide algorithm developers through premarket review. The Osaka-Kansai cluster specializes in endoscopic AI diagnostics development through partnerships between device manufacturers and university hospitals.
China
Provincial cancer centers in the Yangtze River Delta and Pearl River Delta regions deploy imaging analytics for lung and liver malignancy detection. NMPA innovation approval pathways for AI diagnostics compress regulatory timelines for domestic developers. The Beijing-Tianjin-Hebei corridor anchors national AI medical device standard-setting through Ministry of Industry and Information Technology working groups.
United Kingdom
NHS England integrated care systems pilot AI diagnostic platforms for breast and prostate cancer screening backlogs. MHRA Software as a Medical Device guidance aligns with FDA precedents while incorporating post-market surveillance requirements. The London-Oxford-Cambridge golden triangle concentrates digital health venture formation and clinical validation studies.
AI in Oncology Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with installed imaging equipment bases. Siemens Healthineers leverages radiology department relationships to distribute integrated AI diagnostics directly through hardware procurement cycles. NVIDIA Corporation anchors infrastructure supply through GPU clusters and MONAI framework support. Strategic moves concentrate on exclusive laboratory partnerships for proprietary training data access and regulatory clearance portfolio expansion through acquisition.
Within the infrastructure tier, NVIDIA Corporation exemplifies hardware-dependent competitive positioning through accelerator supply concentration. Siemens Healthineers and GE Healthcare occupy positions as integrated equipment-and-software vendors with direct hospital sales channel control. PathAI represents the specialized digital pathology archetype, sustaining market presence through exclusive staining protocol development with academic medical centers rather than broad platform distribution.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| NVIDIA Corporation |
| ConcertAI |
| IBM |
| PathAI |
| Azra AI |
| Medtronic |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
GPU-to-TPU substitution in training infrastructure is redistributing compute procurement from NVIDIA-dominated clusters toward Google Cloud and AWS custom silicon, compressing infrastructure costs for mid-tier imaging analytics vendors while fragmenting hardware supplier geography across Taiwan, South Korea, and the United States.
Pricing Analysis
Cost-plus contracts with GPU price indexation dominate infrastructure procurement for AI oncology vendors, with hyperscaler compute leases resetting quarterly against spot memory pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic algorithms from CE-marked equivalents and research-use-only tools. Cost compression in standard-tier SaaS subscriptions is intensifying because hospital procurement committees demand per-radiologist rather than per-study pricing. Community hospital networks exhibit highest price sensitivity, while pharmaceutical companies negotiating enterprise licenses for patient stratification platforms show least.
Supply Chain Analysis
Inventory lead times for NVIDIA H100 accelerators extend to 26-32 weeks, forcing imaging analytics vendors to pre-commit capital twelve months ahead of commercial deployment. Hardware supply concentrates in Taiwan, South Korea, and the United States, with advanced packaging for AI training chips drawing from TSMC facilities in Hsinchu. Single-source vulnerability pervades the GPU layer, where foundry capacity constraints create procurement bottlenecks irrespective of end-market demand. Distribution runs through direct hyperscaler partnerships and OEM-integrated equipment channels rather than independent software marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source foundation models trained on public oncology datasets threaten proprietary algorithm margins, compelling incumbents to defend through exclusive data partnerships and regulatory moats rather than architectural differentiation alone.
For Market Incumbents: Fortify market position by deepening exclusive laboratory partnerships with academic medical centers for proprietary staining protocol access, and accelerate FDA 510(k) portfolio expansion through acquisition of De Novo-cleared algorithm developers. The open-source foundation model threat demands locked-in training data access as the primary defensive lever. For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-track offers the most penetrable regulatory pathway for novel imaging analytics, particularly for rare-cancer detection algorithms where validation datasets remain scarce. Target community hospital networks in the United States Midwest and Southeast, where radiologist shortages create urgent demand for screening augmentation tools. Go-to-market execution should emphasize PACS integration middleware partnerships rather than direct hospital sales. For Investors and Strategic Acquirers: Capital is best deployed toward digital pathology specialists with locked-in academic medical center partnerships and existing MDR technical file infrastructure for EU AI Act compliance. Long-term viability across the analysis window hinges on transatlantic regulatory capabilities rather than algorithmic performance metrics alone. The signal to monitor is FDA guidance finalization on predetermined change control plans, which will determine which platforms can iterate without repeated submissions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Accelerates market entry for first-in-class algorithms through streamlined premarket review cycles. |
| Academic Medical Center Partnership | Locks in proprietary training data access and exclusive staining protocol development rights. |
| EU AI Act Compliance Investment | Enables European deployment through conformity assessment procedures for high-risk diagnostic systems. |
| PACS Integration Middleware Development | Reduces deployment friction with legacy hospital picture archiving and communication systems. |
| Pharmaceutical Predictive Analytics Licensing | Captures high-margin revenue from patient stratification and clinical trial optimization contracts. |
Research Approach
Desk research of FDA 510(k) and De Novo clearance databases, EMA guidance documents, and hospital procurement contract filings preceded structured interviews with radiology department chairs, pathology laboratory directors, biomedical informatics officers, and pharmaceutical clinical operations executives. Primary intelligence combined with secondary validation against CMS reimbursement data, GPO contract terms, and hyperscaler infrastructure capex disclosures. Bottom-up algorithm deployment counts and top-down healthcare IT spending estimates underwent cross-triangulation to reconcile volume projections.
Variance decomposition across technology segments, end-user categories, and geographic regulatory clusters shaped the analytical framework over the projection horizon. Segmentation modeling incorporated product type, application workflow, deployment scale, and regional clearance pathway complexity. CAGRs derived from fitted growth curves applied to validated base-year estimates, with pharmaceutical predictive analytics spend and community hospital network procurement velocity as industry-specific forecast inputs.
Underlying assumptions cover continued FDA Software as a Medical Device framework stability, sustained GPU supply concentration, and unaltered HIPAA interoperability enforcement, with deviation risk concentrated in adaptive algorithm governance guidance delays and EU AI Act implementation timeline shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Angiosarcomas Treatment Market
Oncology
Pituitary Cancer Market
Oncology
Internal Radiation Therapy Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Interventional Oncology Ablation Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Hadron Therapy Market
Oncology
France Radiation Oncology Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
North America Bone Metastasis Market
Oncology
Global Cancer Treatment Market