
 Asia-Pacific Cancer Biomarkers Market | 2026-2036
Asia-Pacific Cancer Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cancer Biomarkers Market Outlook
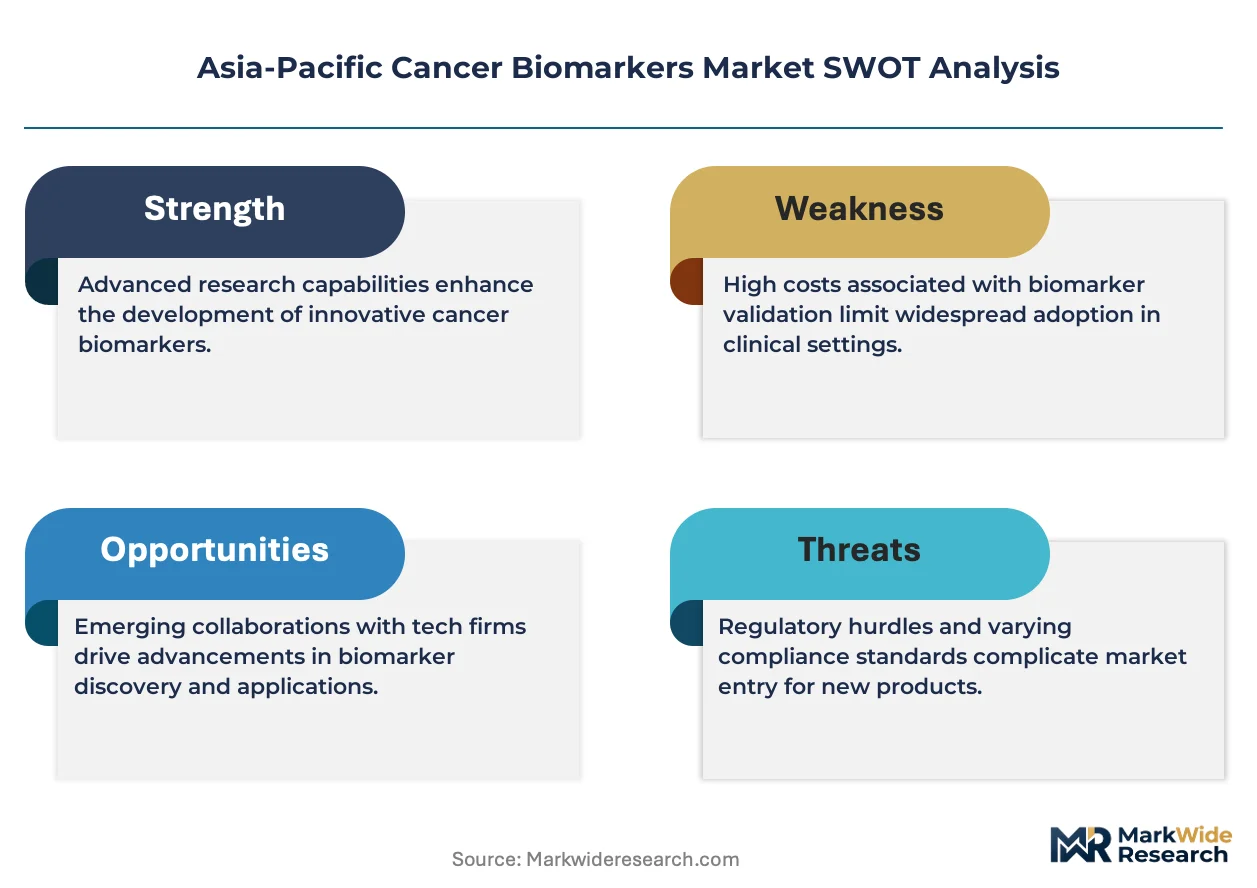
Oncology-focused pharmaceutical companies is redrawing procurement priorities across the Asia-Pacific Cancer Biomarkers landscape, shifting volume toward predictive and therapeutic monitoring applications. Thermo Fisher Scientific leverages its regional distribution infrastructure to supply mass spectrometry and PCR workflows to hospital laboratories in China and Japan. F. Hoffmann-La Roche Ltd anchors its position through integrated companion diagnostic platforms that span tissue-based and liquid biopsy testing. Illumina competes by extending next-generation sequencing instrument placements into research institutes and contract testing organizations across Southeast Asia.
Cancer biomarkers are measurable biological indicators—proteins, genetic mutations, metabolites, or imaging signatures—that detect malignancy, predict therapeutic response, or monitor disease progression; these molecules typically require extraction from blood, tissue, or biofluids followed by analytical validation against clinical endpoints to ensure sensitivity and specificity thresholds meet diagnostic standards. Genomics and proteomics segments dominate current revenue as NGS panels and multiplex protein assays become standard in non-small cell lung cancer and colorectal cancer screening protocols. Next-generation sequencing and mass spectrometry technologies are capturing the fastest expansion, driven by declining per-sample costs and expanding reimbursement for comprehensive genomic profiling in South Korea and Australia.
Japan's PMDA, China's NMPA, and India's CDSCO enforce divergent but increasingly stringent premarket validation requirements for companion diagnostics, forcing manufacturers to maintain multiple regulatory dossiers and clinical evidence packages. The EU AI Act and MDR frameworks, though extraterritorial, influence quality system expectations for Asia-Pacific exporters serving European trial sponsors and reference laboratories. Stakeholders must monitor harmonization efforts between national regulators while building localized manufacturing and clinical utility data to sustain market access across fragmented approval pathways.
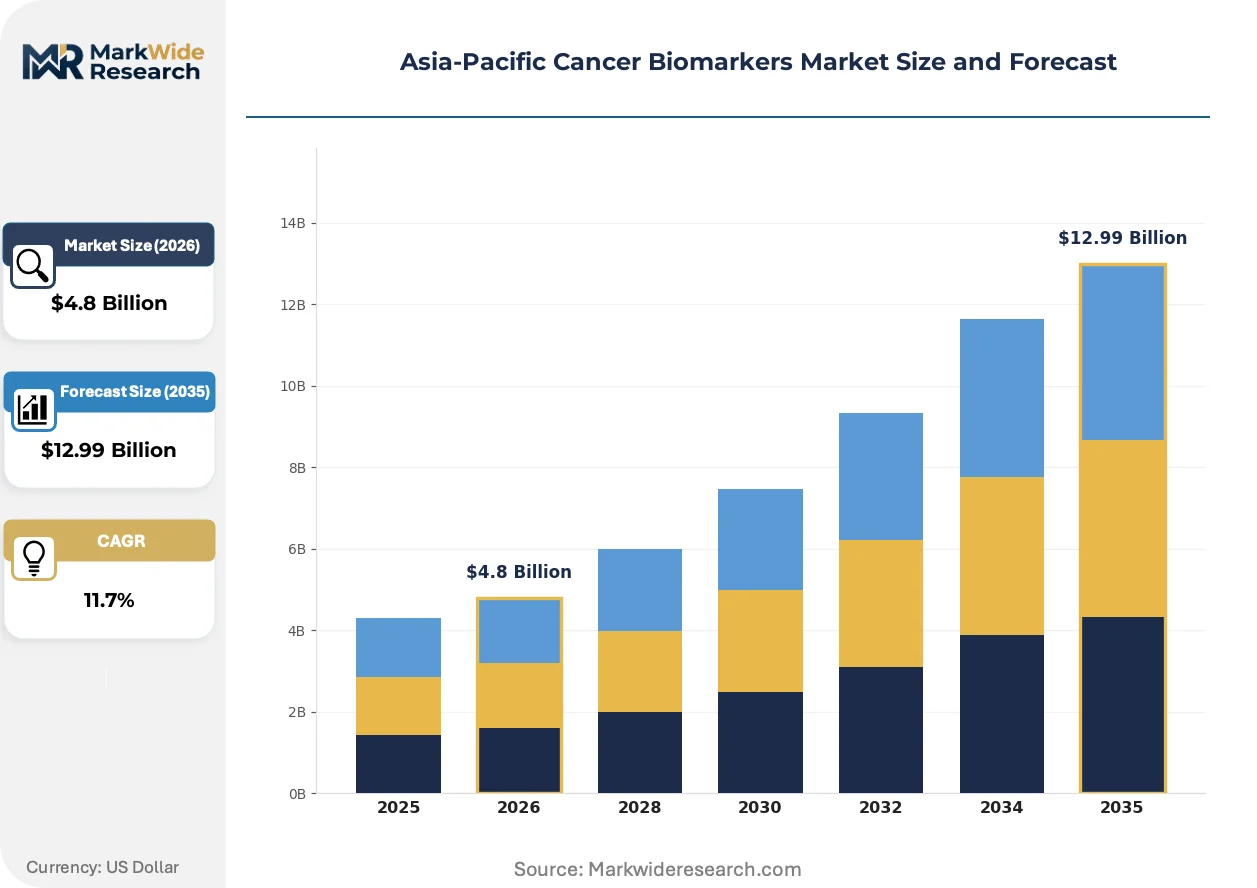
Market Dynamics
Companion diagnostic approval tightening by Japan's PMDA and India's CDSCO is forcing biomarker assay manufacturers to rebuild clinical evidence packages, fragmenting regulatory pathways and reshaping competitive positioning across the Asia-Pacific region.
Growth Catalysts
- Liquid biopsy platform proliferation:Hospital laboratory networks in China are scaling NGS-based testing capabilities for non-small cell lung cancer screening, compressing turnaround times from tissue acquisition to treatment decision.
- CDSCO companion diagnostic mandates:India's tightened premarket validation requirements for predictive biomarker assays are accelerating demand for analytically validated PCR and mass spectrometry workflows in oncology pipelines.
- Comprehensive genomic profiling reimbursement:South Korea and Australia have expanded coverage for multiplex NGS panels, pulling pharmaceutical companies toward integrated biomarker strategies in precision oncology trials.
Market Restraints
- Reagent supply concentration:Critical enzymes and fluorescent probes for NGS library preparation concentrate among a handful of North American and European suppliers, exposing Asia-Pacific laboratories to currency volatility and shipping disruptions.
- Interoperability gaps:Divergent data formats between Chinese domestic genomics platforms and international LIMS systems create technical friction in multi-site clinical trials spanning the region.
- Pathologist workforce scarcity:Specialized training in digital pathology and biomarker interpretation lags instrument deployment across Southeast Asian hospital networks.
Strategic Opportunities
- Rural hospital laboratory penetration:Tier-2 and Tier-3 cities in China remain underpenetrated for automated immunohistochemistry platforms, creating whitespace for decentralized biomarker testing infrastructure.
- AI-assisted image analysis convergence:Integration of machine learning algorithms with digital pathology scanners is enabling quantitative scoring of PD-L1 expression and tumor-infiltrating lymphocyte density.
- Plasma-based minimal residual disease monitoring:Emerging therapeutic monitoring applications in colorectal cancer and breast cancer are opening recurring revenue streams beyond initial diagnostic testing.
Industry Challenges
- Multi-jurisdictional dossier maintenance:Manufacturers must simultaneously satisfy China's NMPA clinical trial requirements, Japan's PMDA QMS inspections, and Australia's TGA conformity assessments for the same biomarker assay.
- Legacy instrument integration complexity:Hospital laboratories in Japan and South Korea face capital write-down pressures when retrofitting existing PCR and FISH workflows for next-generation sequencing compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cancer Biomarkers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteomics, Genomics, Imaging Biomarkers, Metabolomics Application: Diagnostic Testing, Predictive Testing, Prognostic Testing, Therapeutic Monitoring End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Technology: ELISA, PCR, Mass Spectrometry, Next-Generation Sequencing |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, QIAGEN, bioMérieux, Agilent Technologies, Illumina, Bio-Rad Laboratories, Hologic, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cancer Biomarkers Market Strategic Shifts
Multiplex protein quantification and artificial intelligence-enabled pathology are compressing traditional single-analyte testing paradigms, while regulatory divergence across national agencies forces adaptive quality system architectures.
Mass spectrometry-based proteomic profiling is displacing conventional ELISA workflows for cancer biomarker quantification in high-throughput hospital laboratories. Chinese and Japanese reference centers are adopting MALDI-TOF and LC-MS/MS platforms for simultaneous measurement of multiple protein signatures from minimal sample volumes. This displacement is compressing cost-per-test metrics while expanding the analytical dynamic range for low-abundance biomarker detection.
Japan's PMDA has implemented enhanced post-market surveillance requirements for companion diagnostics, mandating real-world evidence collection on analytical performance and clinical utility. Pharmaceutical sponsors must now integrate biomarker testing data into drug safety reporting systems, extending regulatory obligations beyond initial approval. Oncology trial sponsors operating across Asia-Pacific are responding by building localized clinical utility databases to satisfy divergent national pharmacovigilance expectations.
Hospital procurement committees in South Korea and Australia are unbundling instrument placements from reagent supply agreements, compressing vendor lock-in periods and accelerating competitive switching. This behavioral shift is fragmenting long-term service contracts that previously secured decade-long revenue streams for integrated diagnostic platform providers. The disintermediation is most visible in comprehensive genomic profiling contracts, where reference laboratories now source NGS consumables through competitive tender rather than sole-source arrangements.
Asia-Pacific Cancer Biomarkers Market Segmentation
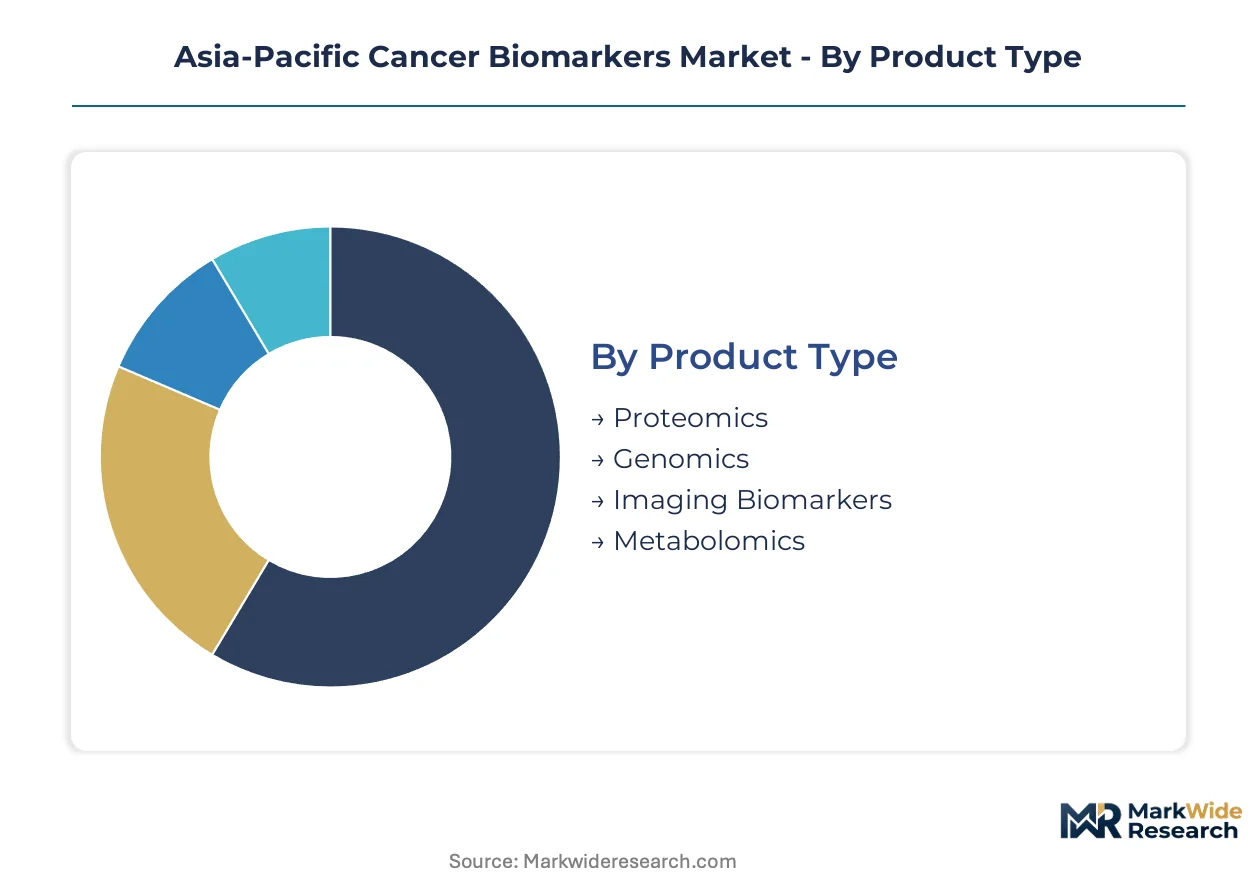
Segmentation in the Asia-Pacific Cancer Biomarkers Market reveals how diagnostic workflows, regulatory pathways, and procurement channels intersect to shape commercial opportunity. Understanding these divisions exposes where capital flows concentrate and where technology transitions create displacement risk.
Product Type:
Channel mix varies sharply across product categories, with genomics and proteomics dominating hospital laboratory procurement while metabolomics and imaging biomarkers flow through specialized reference centers and academic medical centers.
- Genomics:Next-generation sequencing panels and circulating tumor DNA assays constitute the technical backbone of precision oncology programs. China's NMPA has accelerated approvals for domestic NGS platforms, pulling volume toward Beijing and Shanghai hospital networks seeking comprehensive genomic profiling capabilities.
- Proteomics:Multiplex protein quantification via mass spectrometry displaces single-analyte immunoassays in high-throughput settings. Japanese reference laboratories in Osaka and Tokyo are adopting MALDI-TOF workflows for cancer antigen detection, compressing cost-per-test metrics while expanding analytical dynamic range.
- Imaging Biomarkers:Radiomic signatures extracted from CT and MRI scans enable non-invasive tumor characterization. South Korean academic centers deploy these for treatment response monitoring in hepatocellular carcinoma protocols.
- Metabolomics:Small-molecule profiling from plasma or urine samples captures metabolic reprogramming in malignancy. Australian research institutes lead regional adoption for biomarker discovery pipelines.
By volume, genomics leads. By growth pace, proteomics is ahead.
Application:
Cost tier stratification separates applications, with diagnostic and predictive testing commanding premium pricing due to regulatory validation burdens while prognostic and therapeutic monitoring segments compete on operational efficiency and recurring revenue economics.
- Diagnostic Testing:Initial malignancy detection via tissue biopsy or liquid biopsy screening. India's CDSCO mandates companion diagnostic linkage for targeted therapies, tightening premarket validation requirements and elevating analytical performance thresholds.
- Predictive Testing:Biomarker assays forecasting therapeutic response to specific agents. Pharmaceutical sponsors in Japan integrate PMDA-approved predictive assays into clinical trial protocols, creating captive demand for validated EGFR and ALK testing.
- Prognostic Testing:Risk stratification for disease recurrence or progression. Southeast Asian hospital networks deploy these for post-surgical surveillance in colorectal cancer, though reimbursement remains fragmented across national health systems.
- Therapeutic Monitoring:Serial biomarker measurement to assess treatment efficacy or resistance emergence. Plasma-based minimal residual disease testing is gaining traction in Australian oncology practices for breast and colorectal cancer follow-up.
Diagnostic testing captures the largest revenue pool. Therapeutic monitoring exhibits the steepest expansion trajectory as pharmaceutical pipelines emphasize longitudinal patient stratification.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies and research institutes driving technology adoption while hospitals and diagnostic laboratories prioritize workflow integration and total cost of ownership.
- Hospitals:Integrated health systems performing biomarker testing within pathology departments or centralized laboratories. China's tier-1 cities—Beijing, Shanghai, Guangzhou—anchor regional instrument placements as hospital networks consolidate testing under single vendor contracts.
- Diagnostic Laboratories:Independent reference centers processing samples from multiple healthcare providers. South Korea's MFDS-regulated laboratories are unbundling instrument placements from reagent supply agreements, fragmenting long-term vendor lock-in.
- Research Institutes:Academic and government facilities conducting biomarker discovery and analytical validation. Japan's National Cancer Center and comparable Australian institutions drive early adoption of emerging proteomic and metabolomic platforms.
- Pharmaceutical Companies:Drug developers requiring biomarker testing for clinical trial patient selection and pharmacodynamic assessment. CDSCO's tightened companion diagnostic mandates are forcing sponsors to rebuild clinical evidence packages for India-enrolling studies.
Hospitals dominate current procurement volume. Pharmaceutical companies are expanding their share fastest as precision oncology pipelines proliferate across the region.
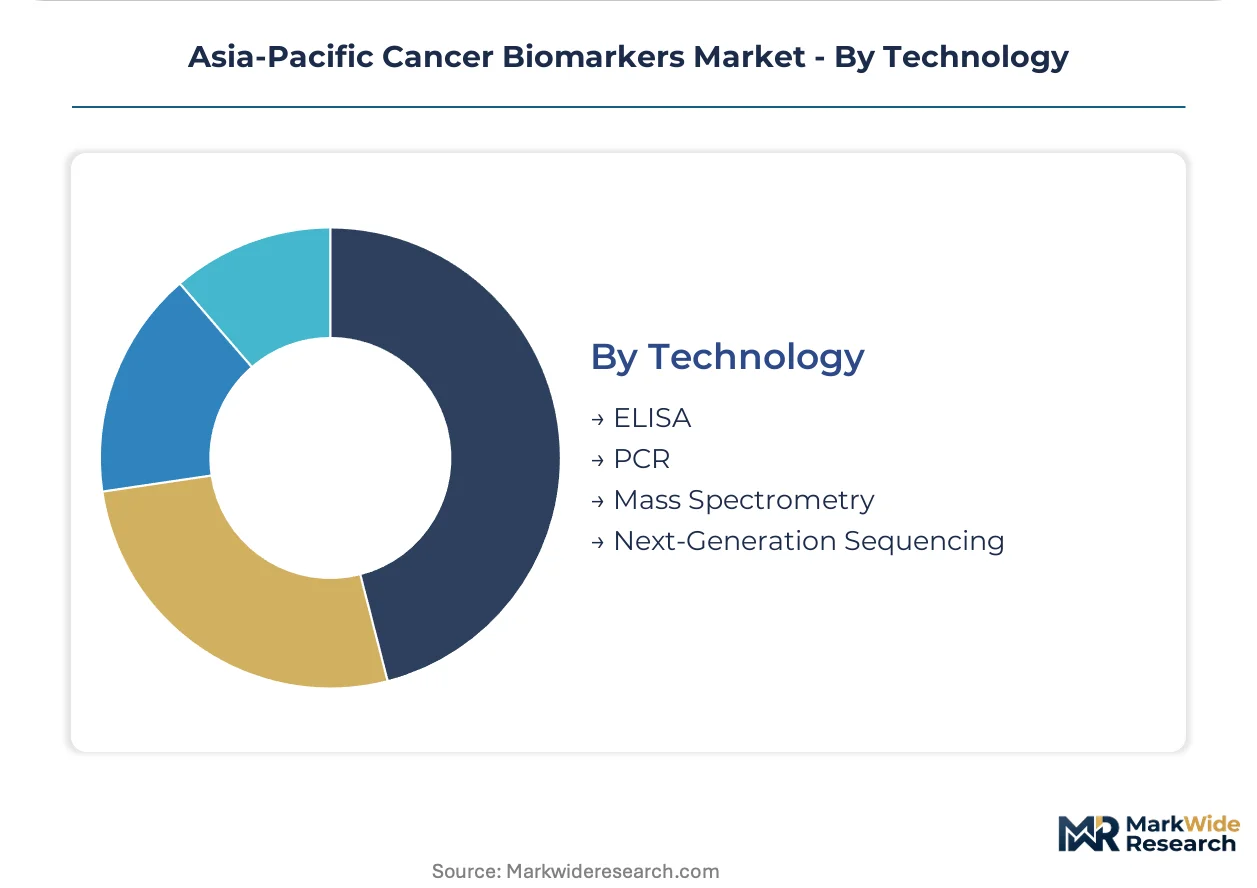
Technology:
Maturity curves separate technologies, with PCR and ELISA representing installed-base mainstays while mass spectrometry and next-generation sequencing capture displacement-driven growth through superior multiplexing and sensitivity.
- Next-Generation Sequencing:Parallel sequencing of millions of DNA fragments enabling comprehensive genomic profiling. China's domestic platform manufacturers—MGI and BGI—are scaling placements into hospital laboratory networks, challenging Illumina's regional dominance.
- Mass Spectrometry:Ion-based detection of biomolecules with exceptional specificity and quantitative precision. Japanese and Australian reference centers adopt LC-MS/MS for multiplex protein quantification, displacing conventional ELISA workflows.
- PCR:Amplification-based detection of specific genetic mutations with rapid turnaround. Remains the workhorse for EGFR and KRAS testing in non-small cell lung cancer, though laboratories face retrofit pressures for NGS compatibility.
- ELISA:Enzyme-linked immunosorbent assays for protein biomarker detection. Still prevalent in resource-constrained Southeast Asian settings, though margins compress as mass spectrometry platforms penetrate mid-tier laboratories.
PCR maintains the largest installed base. Next-generation sequencing is climbing the fastest as per-sample costs decline and reimbursement expands in South Korea and Australia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in Asia-Pacific cancer biomarker logistics, handling temperature-controlled reagent imports and domestic platform exports that feed hospital laboratory networks across the region.
China
Beijing and Shanghai hospital networks drive NGS instrument procurement for non-small cell lung cancer screening. NMPA has accelerated approvals for domestic genomics platforms, reducing import dependency. MGI and BGI scale manufacturing in Shenzhen and Wuhan, challenging foreign vendors for comprehensive genomic profiling contracts.
Japan
Osaka and Tokyo reference laboratories adopt mass spectrometry workflows for multiplex protein quantification. PMDA enforces enhanced post-market surveillance for companion diagnostics, mandating real-world evidence collection. The National Cancer Center anchors clinical utility database development for pharmaceutical sponsors.
India
Mumbai and Delhi diagnostic laboratories face CDSCO mandates for companion diagnostic validation in oncology pipelines. CDSCO's tightened premarket requirements force manufacturers to rebuild clinical evidence packages. Domestic PCR workflow demand concentrates in Karnataka and Telangana biotech clusters.
South Korea
Seoul Capital Area hospital procurement committees unbundle instrument placements from reagent supply agreements. MFDS-regulated laboratories now source NGS consumables through competitive tender rather than sole-source arrangements. Samsung Medical Center and Asan Medical Center drive comprehensive genomic profiling adoption.
Australia
Sydney and Melbourne oncology practices expand plasma-based minimal residual disease monitoring for breast and colorectal cancer follow-up. TGA conformity assessments align with EU MDR frameworks for exporters serving European trial sponsors. Peter MacCallum Cancer Centre anchors proteomic platform validation for therapeutic monitoring protocols.
Asia-Pacific Cancer Biomarkers Market Competitive Environment
Listed leaders compete with private specialists across platform integration and regulatory dossier capabilities, producing a tiered structure where scale-driven multinationals anchor premium segments while regional specialists capture mid-tier laboratory procurement. Three archetypes dominate: integrated diagnostic platform providers, reagent-focused assay manufacturers, and precision oncology service laboratories. Competitive moves concentrate on strategic partnerships for regulatory harmonization and geographic expansion through distributor network consolidation.
Among US-based platform providers, Thermo Fisher Scientific and Illumina occupy positions spanning mass spectrometry and next-generation sequencing infrastructure. Swiss-listed F. Hoffmann-La Roche Ltd anchors the integrated companion diagnostic tier, exemplifying how pharmaceutical-linked validation strategies capture predictive testing volume. These three represent the dominant competitive anchors across hospital laboratory and pharmaceutical sponsor procurement channels.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| bioMérieux |
| Agilent Technologies |
| Illumina |
| Bio-Rad Laboratories |
| Hologic |
| Others |
Value Chain & Pricing Dynamics
Long-term reagent supply agreements lock in both NGS library preparation kit access and predictable per-test cost visibility for hospital laboratories across China and Japan, insulating procurement committees from fluorescent probe spot-market volatility while cementing vendor lock-in periods that fragment competitive switching opportunities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates analytically validated companion diagnostic assays from research-use-only panels and unbundled reagent-only supply. Price differentiation rests on NMPA approval status and ISO 13485 certification tier, with CDSCO-mandated validation packages commanding 40-60% premiums over non-validated equivalents. Cost compression in economy-tier PCR workflows is intensifying because domestic Chinese manufacturers are scaling MGI platform consumables. Pharmaceutical sponsors exhibit least price sensitivity due to captive trial demand, while tier-3 hospital laboratories in Southeast Asia face acute budget constraints.
Supply Chain Analysis
Shanghai-Ningbo port congestion and trans-Pacific container availability constraints are elevating inbound logistics costs for temperature-controlled enzyme shipments from North American suppliers. Critical raw material concentration centers on California and Massachusetts for fluorescent probes, Bavaria for high-fidelity polymerases, and Shenzhen for domestic Chinese oligo synthesis. Single-source vulnerability pervades NGS library preparation enzymes, with three suppliers controlling 80% of regional hospital laboratory feedstock. Distribution runs through regional distributor networks anchored by Thermo Fisher and QIAGEN logistics hubs in Singapore and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-based minimal residual disease monitoring services are expanding faster than NGS instrument placements, creating a recurring-revenue layer that outpaces hardware depreciation cycles and reshapes vendor-customer relationships toward subscription economics.
For Market Incumbents: Consolidate control over reagent supply agreements before South Korean and Australian procurement committees complete their unbundling transitions. Deepen backward integration into critical enzyme manufacturing to offset North American supplier concentration risk. Lock in decade-long service contracts with Japan's National Cancer Center and comparable reference laboratories to anchor clinical utility database development against emerging proteomics specialists. For New Entrants and Emerging Players: AI-assisted pathology interpretation services represent a service-layer gap where Roche and Leica under-serve mid-tier Southeast Asian hospital networks lacking specialized training infrastructure. Target tier-2 Chinese cities for automated immunohistochemistry platform placements, where whitespace persists for decentralized biomarker testing infrastructure. Lead with outcome-based contracting models that tie pricing to PD-L1 scoring accuracy rather than instrument capital expenditure. For Investors and Strategic Acquirers: Regional proteomics assay developers with validated LC-MS/MS workflows and existing PMDA quality system certifications offer the most attractive acquisition profile. Long-term viability hinges on regulatory dossier depth across multiple Asia-Pacific jurisdictions rather than single-market dominance. Watch for CDSCO companion diagnostic mandate expansion into breast and colorectal cancer as the inflection indicator signaling accelerated evidence-package investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Harmonization | Reduces multi-jurisdictional dossier maintenance burden for manufacturers serving PMDA, NMPA, and CDSCO simultaneously. |
| Liquid Biopsy Platform Manufacturing Scale-Up | Domestic Chinese MGI and BGI facilities are compressing per-sample costs for circulating tumor DNA assays. |
| AI-Enabled Pathology Software Development | Quantitative PD-L1 scoring algorithms address pathologist workforce scarcity across Southeast Asian hospital networks. |
| Reagent Supply Agreement Restructuring | South Korean MFDS-regulated laboratories are fragmenting long-term vendor lock-in through competitive tender processes. |
| Clinical Utility Database Localization | Japan's PMDA post-market surveillance mandates require pharmaceutical sponsors to build region-specific real-world evidence repositories. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at companion diagnostic manufacturers, hospital laboratory directors, and pharmaceutical biomarker strategists; and secondary validation against NMPA and PMDA filing databases, CDSCO approval registries, and hospital procurement contract disclosures. Bottom-up instrument placement counts from Chinese tier-1 city health bureaus were triangulated against top-down revenue estimates derived from reagent consumption models.
Across the analysis window, the forecasting framework modeled volume and value trajectories by biomarker type, application, end-user archetype, and national regulatory cluster. CAGRs were derived from segmented growth rate differentials applied to base-year estimates, with specific inputs including NGS per-sample cost decline curves and companion diagnostic approval velocity by agency.
Forecasts assume regulatory continuity in China's NMPA accelerated approval pathways and Japan's PMDA enhanced post-market surveillance regimes; material policy shifts would require re-modeling. Analytical outcomes reflect assumptions of stable reagent supply chain configuration and continued reimbursement expansion for comprehensive genomic profiling in South Korea and Australia. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Pancreatic Cancer Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
North America Bone Metastasis Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
North America Veterinary Oncology Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Immuno-Oncology Market
Oncology
Osteosarcoma Market
Oncology
France Radiation Oncology Market
Oncology
Bone Metastasis Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
North America Tumor Ablation Market
Oncology
Radiation Oncology Market
Oncology
Ustekinumab Market