
 Angiosarcomas Treatment Market | 2026-2036
Angiosarcomas Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
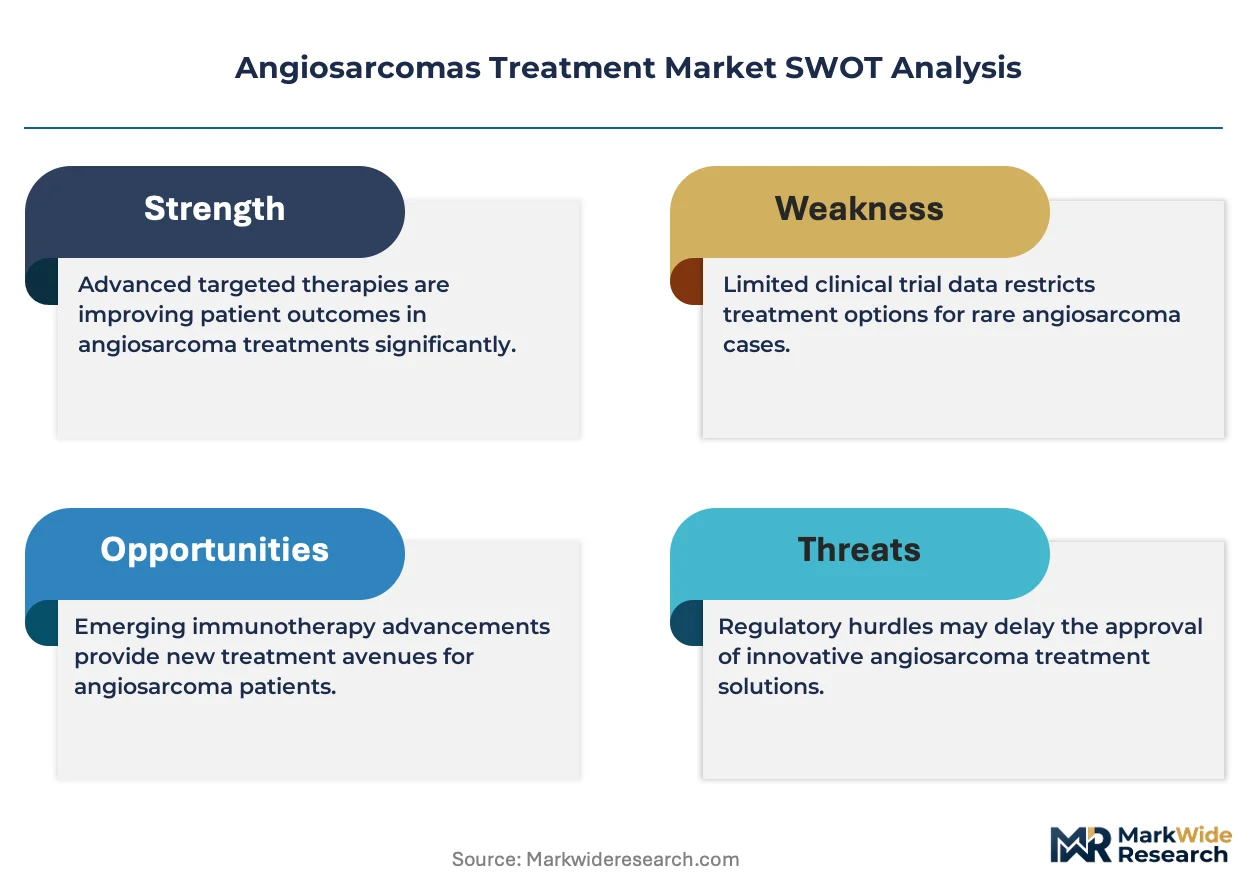
Angiosarcomas Treatment Market Analysis
A shortage of sarcoma-specialized oncologists is unwinding treatment capacity in community settings. F. Hoffmann La Roche Ltd leverages its diagnostic-treatment integration to anchor clinical trial recruitment. Novartis AG competes through targeted therapy portfolios in vascular malignancies. Bayer AG differentiates via radiopharmaceutical expertise that extends into rare cancer indications.
Angiosarcomas treatment encompasses multimodal interventions for malignant endothelial cell tumors, typically combining systemic agents with locoregional radiation due to the disease's aggressive vascular proliferation and high metastatic propensity. The primary purpose centers on prolonging survival in a patient population where surgical resection alone yields poor outcomes due to frequent multifocal presentation. Chemotherapy retains the largest patient volume share, while immunotherapy represents the fastest-expanding segment as checkpoint inhibitors demonstrate activity in vascular tumors. Injectable formulations dominate hospital administration, though oral targeted agents are capturing share in maintenance settings.
The FDA orphan drug program shapes development economics through tax credits and market exclusivity provisions, while the EMA's PRIME designation streamlines European access for innovative sarcoma therapies. Japan's PMDA offers Sakigake fast-track review for breakthrough oncology products, compressing approval timelines for angiosarcoma indications. Stakeholders must monitor biomarker-defined subpopulations where VEGF-directed and immune-mediated mechanisms show differential response, as these segments will determine pipeline prioritization and reimbursement positioning.
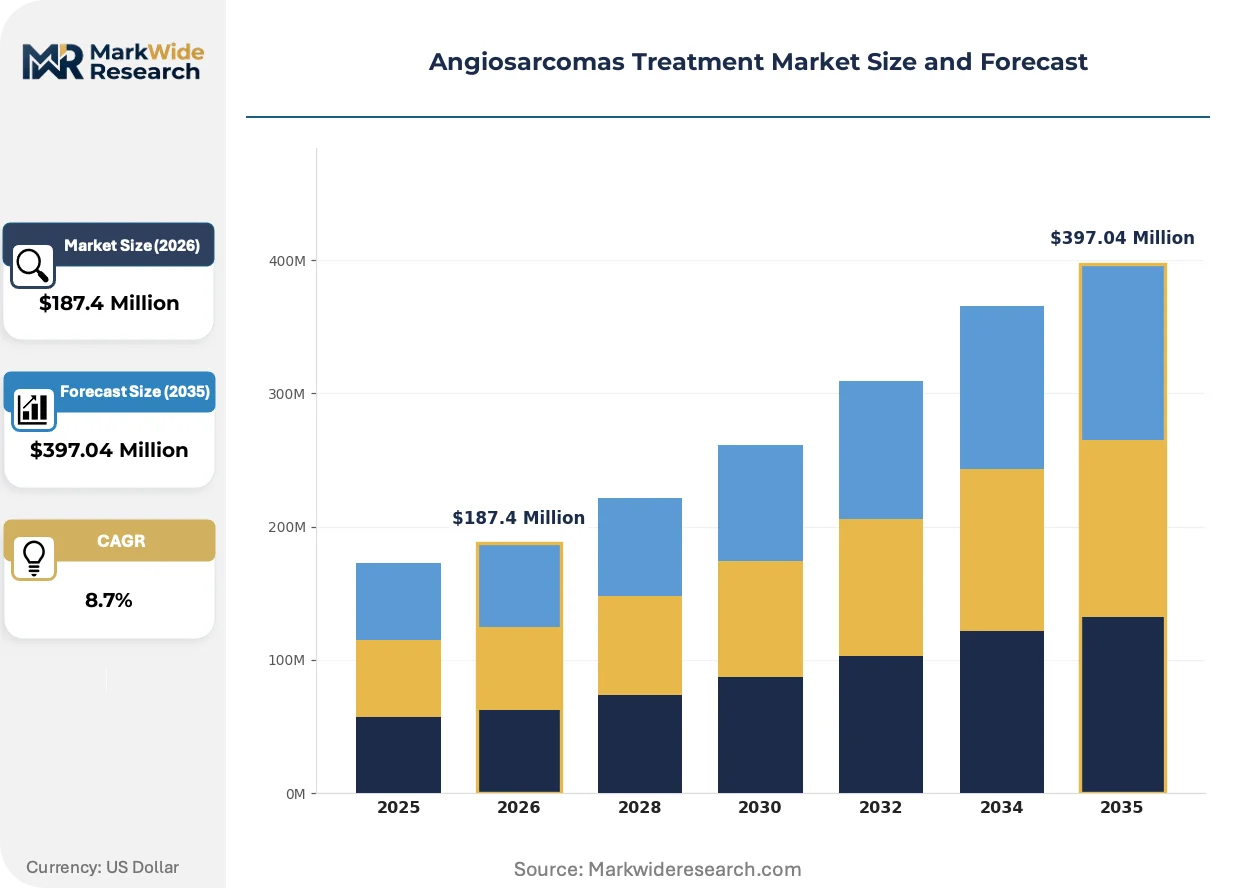
Market Dynamics
The FDA orphan drug designation pathway is concentrating development incentives around angiosarcoma indications, while sarcoma-specialized oncologist shortages in community settings are compressing treatment capacity and shifting patient flows toward academic medical centers.
Growth Catalysts
- Orphan Drug Tax Credits:The FDA's program provides developers with tax incentives and market exclusivity provisions that improve project economics for rare vascular malignancies.
- Checkpoint Inhibitor Activity:Immunotherapy mechanisms are demonstrating measurable response rates in vascular tumor subpopulations, expanding addressable patient pools beyond chemotherapy-refractory cases.
- Sarcoma Referral Network Density:Germany, Japan, and the United States maintain the most developed specialist infrastructure, concentrating clinical trial recruitment and early adoption of novel protocols.
Market Restraints
- Specialist Workforce Constraints:The shortage of sarcoma-specialized oncologists limits treatment capacity in community hospital settings and extends time-to-treatment intervals.
- Biomarker Definition Gaps:Incomplete molecular stratification of angiosarcoma subtypes restricts patient selection precision for VEGF-directed and immune-mediated therapies.
- Reimbursement Compression:Payer scrutiny of high-cost oncology agents creates prior authorization friction for novel immunotherapy combinations in rare indications.
Strategic Opportunities
- Diagnostic-Treatment Integration:Companion diagnostic development for VEGF pathway markers creates patient segmentation tools that support premium positioning and payer negotiation.
- Radiopharmaceutical Extension:Alpha-emitter and beta-emitter platforms validated in other vascular malignancies offer mechanistic rationale for angiosarcoma indication expansion.
- Maintenance Oral Formulations:Transition from injectable chemotherapy to oral targeted agents in post-response settings reduces hospital burden and extends therapy duration.
Industry Challenges
- Clinical Trial Recruitment Bottlenecks:Low disease incidence across dispersed geographies complicates enrollment timelines and increases per-patient trial costs.
- Multimodal Protocol Coordination:Integration of systemic agents with locoregional radiation requires specialized care teams that community oncology practices struggle to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angiosarcomas Treatment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Radiation Therapy, Immunotherapy End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Settings Formulation: Oral, Injectable, Intravenous, Topical Mode of Action: Angiogenesis Inhibitors, Cytotoxic Agents, Hormonal Agents, Monoclonal Antibodies |
| Companies Covered | F. Hoffmann La Roche Ltd, Novartis AG, Bayer AG, Sanofi, Amgen Inc., Merck & Co. Inc., AbbVie Inc., Eli Lilly and Company, Genentech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angiosarcomas Treatment Market Emerging Trajectories
Combination therapy protocols are displacing single-agent standards in angiosarcoma care, while biomarker-driven patient selection is compressing development timelines for mechanism-specific candidates.
Next-generation sequencing panels are fragmenting the historical histology-first diagnostic approach by identifying actionable alterations in VEGF signaling and DNA damage response pathways. Academic medical centers are adopting these platforms at accelerating pace, enabling molecular tumor board decisions that match patients to targeted trials. This molecular stratification is fragmenting the previously uniform angiosarcoma patient population into addressable subsegments with distinct therapeutic vulnerabilities.
The EMA's PRIME designation streamlines European access pathways for innovative sarcoma therapies by providing accelerated assessment and enhanced regulatory dialogue. Developers leveraging this framework gain compressed approval timelines and conditional reimbursement access in Germany and France. Small-cap biopharma firms with angiosarcoma assets are prioritizing PRIME eligibility to secure European market entry ahead of full clinical data maturity.
Hospital procurement departments are unbundling oncology drug purchasing from bundled service contracts, creating direct negotiation leverage with manufacturers. This shift is most visible in United States health systems where pharmacy benefit managers have lost exclusivity on oncology agent contracting. Academic medical centers with captive specialty pharmacies are capturing margin previously allocated to external distributors, restructuring channel economics for injectable formulations.
Angiosarcomas Treatment Market Segmentation
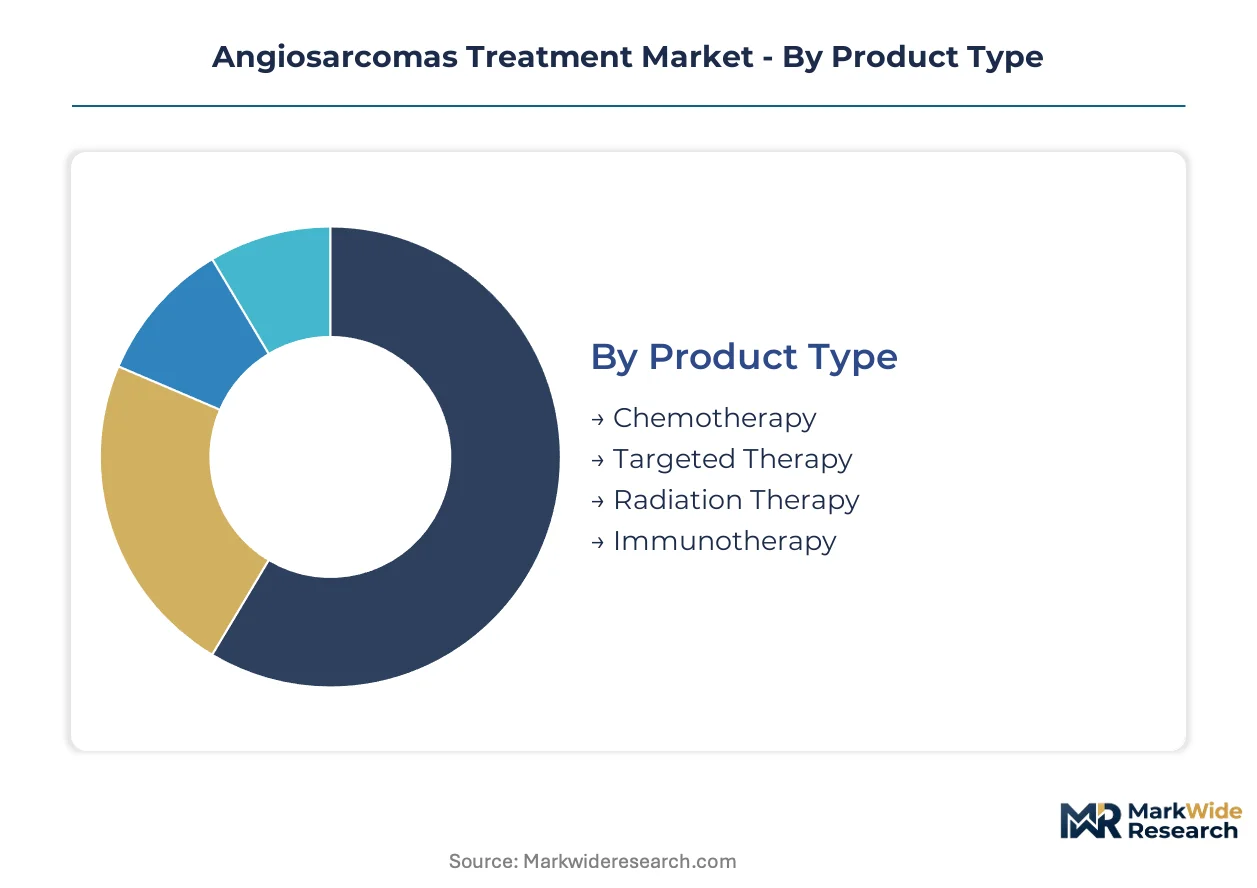
Angiosarcomas treatment channels fragment sharply across institutional versus ambulatory settings, with formulation choices and reimbursement pathways determining where specific modalities concentrate. Molecular stratification is splintering the previously uniform patient population into mechanism-addressable subsegments with distinct therapeutic vulnerabilities.
Product Type:
Hospital infusion centers capture chemotherapy and immunotherapy volumes, while oral targeted agents flow through specialty pharmacy channels toward maintenance settings.
- Chemotherapy:Anthracycline-based and taxane regimens remain the backbone of first-line systemic treatment, administered predominantly in hospital outpatient departments where prior authorization workflows are streamlined. United States academic medical centers concentrate the highest procedure volumes due to sarcoma referral network density.
- Immunotherapy:Checkpoint inhibitors demonstrate measurable response rates in vascular tumor subpopulations, with pembrolizumab and nivolumab protocols expanding into combination studies. Germany's EMA PRIME designation pathway accelerates European access for these mechanism-specific candidates.
- Targeted Therapy:VEGF pathway inhibitors address biomarker-defined angiosarcoma subtypes through oral and intravenous formulations.
- Radiation Therapy:External beam and brachytherapy approaches integrate with systemic agents in multimodal protocols at specialized sarcoma centers.
By volume, chemotherapy leads. By growth pace, immunotherapy is ahead.
End User:
Cost tier stratification separates high-complexity multimodal care from maintenance therapy, with reimbursement rates determining institutional versus home-based administration.
- Hospitals:Academic medical centers with embedded radiation oncology and surgical oncology capabilities anchor complex case management. Japan's PMDA Sakigake fast-track review compresses approval timelines for novel agents entering these high-volume centers.
- Oncology Clinics:Community-based practices with sarcoma-specialized oncologists handle stable patients and treatment monitoring, though workforce shortages constrain capacity expansion.
- Research Institutions:Clinical trial recruitment concentrates at NIH-designated cancer centers and European comprehensive cancer networks.
- Homecare Settings:Oral targeted agents and supportive care medications shift administration burden away from institutional sites.
By patient throughput, hospitals dominate. By margin structure, oncology clinics outperform.
Formulation:
Application requirements dictate whether administration occurs in supervised clinical settings or ambulatory environments, with patient compliance and bioavailability driving selection.
- Injectable:Cytotoxic chemotherapy and monoclonal antibodies require infusion center infrastructure with nursing supervision and adverse event monitoring capabilities.
- Intravenous:Continuous infusion protocols and combination regimens anchor hospital-based revenue streams through drug purchasing and administration fees.
- Oral:Tyrosine kinase inhibitors and hormonal agents enable treatment continuation outside institutional settings, reducing hospital burden.
- Topical:Cutaneous angiosarcoma presentations utilize localized therapeutic approaches in dermatology and surgical oncology clinics.
By administration frequency, intravenous formulations lead. By patient preference trajectory, oral options are expanding most quickly.
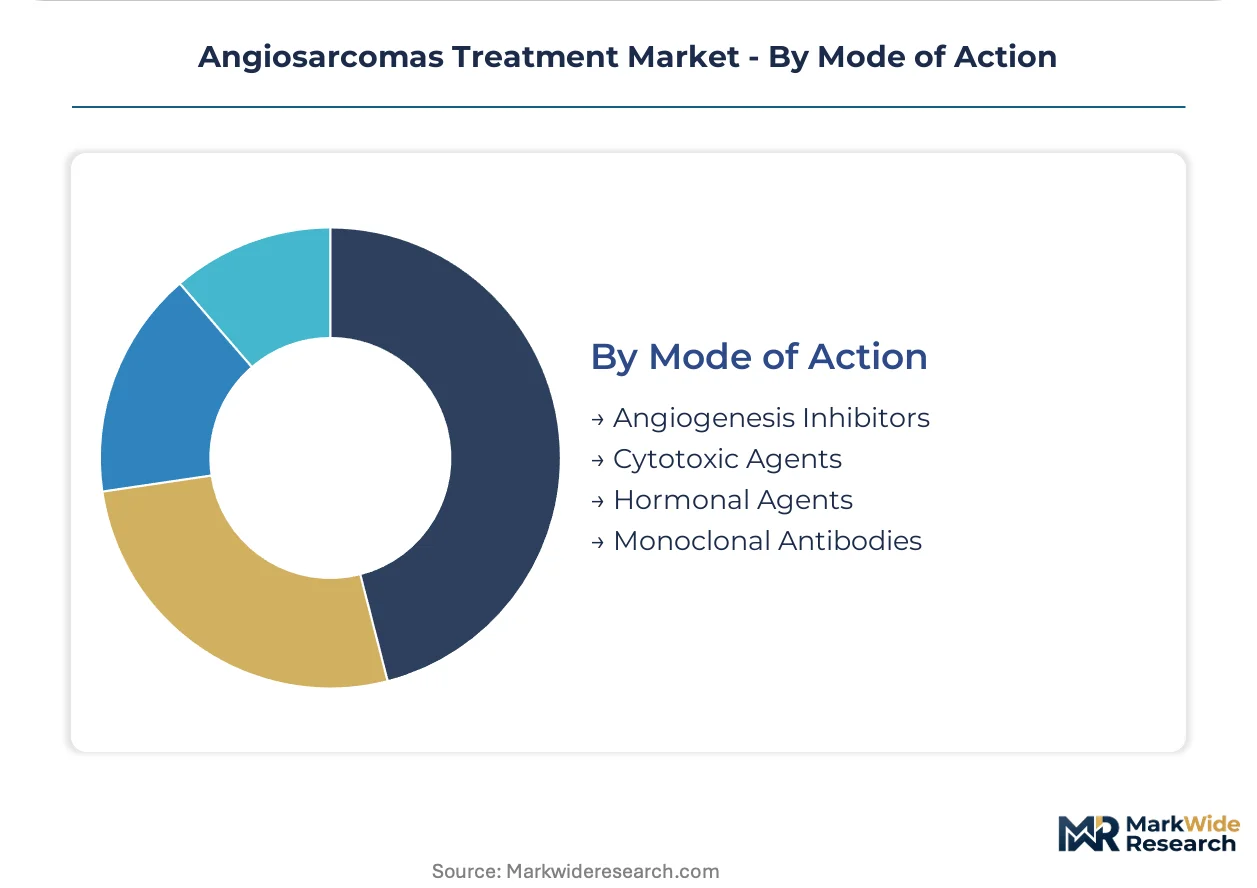
Mode of Action:
Customer type segmentation separates curative-intent first-line therapy from palliative and maintenance approaches, with biomarker availability determining precision targeting feasibility.
- Cytotoxic Agents:DNA-intercalating and microtubule-stabilizing compounds address rapidly proliferating vascular malignancies regardless of molecular subtype, preserving broad applicability.
- Angiogenesis Inhibitors:VEGF-directed therapies demonstrate differential response in biomarker-enriched subpopulations, with companion diagnostic development supporting premium positioning.
- Monoclonal Antibodies:Immune checkpoint blockade and vascular targeting constructs require specialized cold-chain distribution and handling protocols.
- Hormonal Agents:Limited applicability in hormone receptor-positive angiosarcoma subtypes restricts addressable patient pools to specific molecular profiles.
By current utilization, cytotoxic agents lead. By pipeline investment intensity, angiogenesis inhibitors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese tertiary centers where sarcoma referral networks justify premium reimbursement, while community oncology practices in the United States face compressed margins due to workforce shortages and prior authorization friction.
United States
Academic medical centers in Houston, New York, and Boston anchor complex case volumes through NIH-designated cancer center designations. The FDA's orphan drug tax credit program incentivizes developers targeting rare vascular malignancies. MD Anderson Cancer Center and Memorial Sloan Kettering concentrate the highest clinical trial recruitment rates for angiosarcoma combination protocols.
Germany
Comprehensive cancer networks in Heidelberg, Munich, and Essen leverage EMA PRIME designation pathways to accelerate access for mechanism-specific candidates. Germany's statutory health insurance system maintains distinct reimbursement tiers for hospital-based versus ambulatory oncology care. The German Cancer Research Center coordinates molecular tumor board decisions that match patients to targeted trials.
Japan
PMDA Sakigake fast-track review compresses approval timelines for breakthrough oncology products entering Tokyo and Osaka metropolitan centers. Japan's aging demographic concentrates cutaneous angiosarcoma incidence in sun-exposed elderly populations. National Cancer Center Hospital and Osaka International Cancer Institute anchor sarcoma specialist capacity.
United Kingdom
NHS England's specialized commissioning framework routes rare cancer cases to designated sarcoma centers in London, Manchester, and Birmingham. The MHRA's reliance on EMA centralized procedures streamlines regulatory access for innovative therapies. Royal Marsden Hospital and Christie NHS Foundation Trust maintain the deepest clinical trial portfolios for vascular malignancies.
Switzerland
Swissmedic's accelerated access pathway enables early reimbursement for orphan oncology indications at university hospitals in Zurich, Basel, and Geneva. Switzerland's mandatory health insurance system permits premium pricing for biomarker-directed therapies with companion diagnostics. University Hospital Zurich anchors translational research bridging diagnostic-treatment integration.
Angiosarcomas Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated pharmaceutical conglomerates commanding clinical trial infrastructure while mid-cap biotech firms pursue mechanism-specific development. The market structure fragments across three tiers: global oncology majors with diagnostic-treatment integration capabilities, targeted therapy specialists in vascular malignancies, and radiopharmaceutical developers extending platforms into rare indications. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic expansion through EMA PRIME and PMDA Sakigake pathway utilization.
Within the integrated pharmaceutical tier, F. Hoffmann La Roche Ltd and Novartis AG exemplify contrasting strategic positions. The Swiss conglomerate anchors clinical trial recruitment through diagnostic-treatment integration, while the Basel-based competitor competes through targeted therapy portfolios in vascular malignancies. Bayer AG occupies a distinct radiopharmaceutical specialization that extends into rare cancer indications, representing the platform-extension archetype.
| Leading Market Players |
|---|
| F. Hoffmann La Roche Ltd |
| Novartis AG |
| Bayer AG |
| Sanofi |
| Amgen Inc. |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Eli Lilly and Company |
| Genentech Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for checkpoint inhibitor cold-chain distribution anchor pricing power at academic medical centers with captive specialty pharmacy infrastructure, while community oncology practices absorb margin compression from inventory carrying costs and prior authorization delays. This lead-time band concentrates procurement leverage among United States health systems that have unbundled oncology drug purchasing from bundled service contracts.
Pricing Analysis
The customization-premium spread between biomarker-directed combination protocols and standard chemotherapy regimens spans three-tier pricing structure across premium, standard, and economy levels. FDA orphan drug designation creates exclusivity premiums for mechanism-specific candidates, while anthracycline-based generics face cost compression from pharmacy benefit manager formulary placement. Academic medical centers with molecular tumor board capabilities capture the least price-sensitive segment, whereas community oncology clinics with sarcoma workforce shortages exhibit highest sensitivity to prior authorization friction.
Supply Chain Analysis
The inventory/lead-time observation reveals that monoclonal antibody cold-chain requirements tether distribution to United States, Germany, and Japan where sarcoma referral network density justifies specialized logistics investment. Active pharmaceutical ingredients for VEGF inhibitors and checkpoint inhibitors draw from Swiss and Irish contract manufacturing organizations, creating single-source vulnerability for orphan indication scale-up. Distribution runs through hospital outpatient departments and captive specialty pharmacies at academic medical centers, bypassing traditional wholesale channels for high-value oncology agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The angiosarcoma treatment market sits at a platform-economics inflection where diagnostic-treatment integration creates winner-take-most dynamics, with next-generation sequencing panel adoption fragmenting patient segmentation and compressing development timelines for mechanism-matched candidates.
For Market Incumbents: Shield market position through backward integration into companion diagnostic development for VEGF pathway markers, creating patient segmentation tools that defend premium pricing against biosimilar pressure. Prioritize capacity expansion at NIH-designated cancer centers in Houston, Boston, and New York where clinical trial recruitment concentration creates switching costs for investigator relationships. For New Entrants and Emerging Players: FDA orphan drug fast-track designation offers the most penetrable regulatory pathway for mechanism-specific candidates, with EMA PRIME designation providing complementary European access acceleration. Target Germany's comprehensive cancer networks where statutory health insurance reimbursement tiers favor innovative sarcoma therapies, deploying diagnostic-treatment integration partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap biopharma parents with angiosarcoma assets in phase II development but lacking commercial infrastructure to exploit orphan drug exclusivity provisions. Long-term viability hinges on biomarker-defined subpopulation addressability rather than histology-first approaches, with checkpoint inhibitor response rate durability in vascular tumor subtypes serving as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | VEGF pathway marker validation enables precision patient segmentation for premium positioning. |
| EMA PRIME Designation Pursuit | Accelerated assessment compresses European approval timelines for mechanism-specific candidates. |
| Academic Medical Center Partnership | NIH-designated cancer center alliances anchor clinical trial recruitment and early protocol adoption. |
| Oral Formulation Transition | Tyrosine kinase inhibitor development shifts administration burden from hospital to homecare settings. |
| Radiopharmaceutical Platform Extension | Alpha-emitter validation in vascular malignancies creates mechanistic rationale for angiosarcoma indication expansion. |
Methodological Framework
The analysis maps chemotherapy, immunotherapy, targeted therapy, and radiation therapy segments, each validated through sarcoma-specialist oncologists, hospital pharmacy directors, regulatory affairs leads, and payer access specialists. Primary interviews combined with secondary validation from FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov protocol databases, and hospital procurement contracts enable bottom-up and top-down triangulation across market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models treatment line, formulation type, mode of action, and regional regulatory cluster dimensions, with CAGRs derived from procedure volume trajectories at academic medical centers and payer reimbursement rate assumptions. Pipeline progression probabilities and biomarker prevalence estimates inform patient-addressable market calculations.
Decision-makers should treat outputs as directional under stable orphan drug incentive structures and continued checkpoint inhibitor activity in vascular tumors; material deviation in regulatory pathway economics or immunotherapy response durability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
AI in Oncology Market
Oncology
Global Cancer Profiling Market
Oncology
Glioblastoma Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
America Cancer Immunotherapy Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Thymus Cancer Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Testicular Cancer Treatment Market
Oncology
Tumor Embolization Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Immuno-Oncology Market
Oncology
Australia Cancer Treatment Market
Oncology
Metastases Spinal Tumor Market
Oncology
Laser Cancer Therapy Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market