
 Europe Biomedical Sensors Market | 2026-2036
Europe Biomedical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biomedical Sensors Market Foresight
The gap between premium sensor platforms and commodity component supply is repositioning competitive dynamics across European healthcare procurement. Medtronic leverages its vertical integration in implantable sensor manufacturing to sustain pricing power in cardiac monitoring applications. Siemens Healthineers anchors its position through R&D intensity in optical sensing architectures for diagnostic imaging systems. Sensirion AG competes on MEMS miniaturization expertise, dominating flow sensor modules for respiratory devices.
Biomedical sensors are electromechanical or biochemical transducers that convert physiological signals into quantifiable electrical outputs, typically operating within precision ranges of microvolts to millivolts and requiring biocompatible encapsulation for tissue contact. These devices serve the primary commercial purpose of enabling real-time physiological monitoring, therapeutic feedback control, and diagnostic data acquisition across clinical and ambulatory environments. Wearable sensors are capturing margin pools as homecare reimbursement expands across EU member states, while implantable sensors face elongated approval cycles under MDR conformity assessment. Microelectromechanical Systems technology leads volume production due to semiconductor foundry scalability, though biochemical sensors represent the fastest-growing category driven by point-of-care molecular diagnostics demand.
The EU Medical Device Regulation and CE marking framework enforce clinical evidence thresholds that shape product development timelines and market access costs for sensor manufacturers. EMA guidance on combination products and ECHA REACH compliance for biocompatible materials further constrain material selection and supplier qualification processes. Stakeholders must monitor evolving notified body capacity bottlenecks and MDR transition deadline enforcement to calibrate European market entry strategies.
Market Dynamics
The EU Medical Device Regulation's clinical evidence requirements are compressing product development timelines while simultaneously elevating barriers for non-integrated sensor manufacturers. This regulatory compression favors vertically integrated producers with captive notified body relationships and in-house biocompatibility testing infrastructure.
Growth Catalysts
- Chronic disease management protocols:Germany's DMP frameworks for diabetes and cardiovascular conditions are mandating continuous physiological monitoring, expanding reimbursable indications for ambulatory glucose and pressure sensors.
- REACH compliance evolution:ECHA's expanding restricted substance lists are accelerating substitution toward platinum-group-metal-free electrode materials in electrochemical biosensors, opening procurement windows for compliant suppliers.
- MEMS foundry scaling:Semiconductor fabrication capacity in Grenoble and Dresden is enabling volume production of sub-millimeter pressure and flow transducers for minimally invasive surgical instruments.
Market Restraints
- Notified body capacity constraints:MDR transition bottlenecks at TÜV SÜD and BSI Group are extending CE marking timelines to 18-24 months for novel implantable sensor categories.
- Biocompatible material concentration:Medical-grade silicone and parylene C supply is concentrating among three German specialty chemical producers, creating input cost volatility for encapsulation-dependent devices.
- Optical sensing limitations:Tissue perfusion variability and melanin interference continue constraining photoplethysmography accuracy in ambulatory pulse oximetry applications.
Strategic Opportunities
- Eastern European hospital modernization:Poland and Romania's EU cohesion fund allocations for critical care infrastructure are creating first-mover advantages for patient monitoring system integrators with local service presence.
- AI-enabled diagnostic convergence:Edge computing integration with biochemical sensors is enabling real-time pattern recognition for sepsis biomarker panels in emergency department triage workflows.
- Green procurement mandates:The EU Green Deal's circular economy requirements for medical devices are favoring sensor architectures with modular battery replacement and recyclable polymer housings.
Industry Challenges
- Multidisciplinary talent scarcity:The intersection of electrochemistry, MEMS fabrication, and clinical regulatory affairs requires hybrid skill sets that European technical universities are not yet producing at sufficient scale.
- Legacy system integration friction:Hospital information systems in France and Italy operate on proprietary data protocols that demand costly middleware development for seamless sensor data ingestion.
- IP landscape complexity:Thicketed patent positions around enzymatic glucose sensing and optical coherence tomography are forcing licensing negotiations that delay product commercialization by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biomedical Sensors Market |
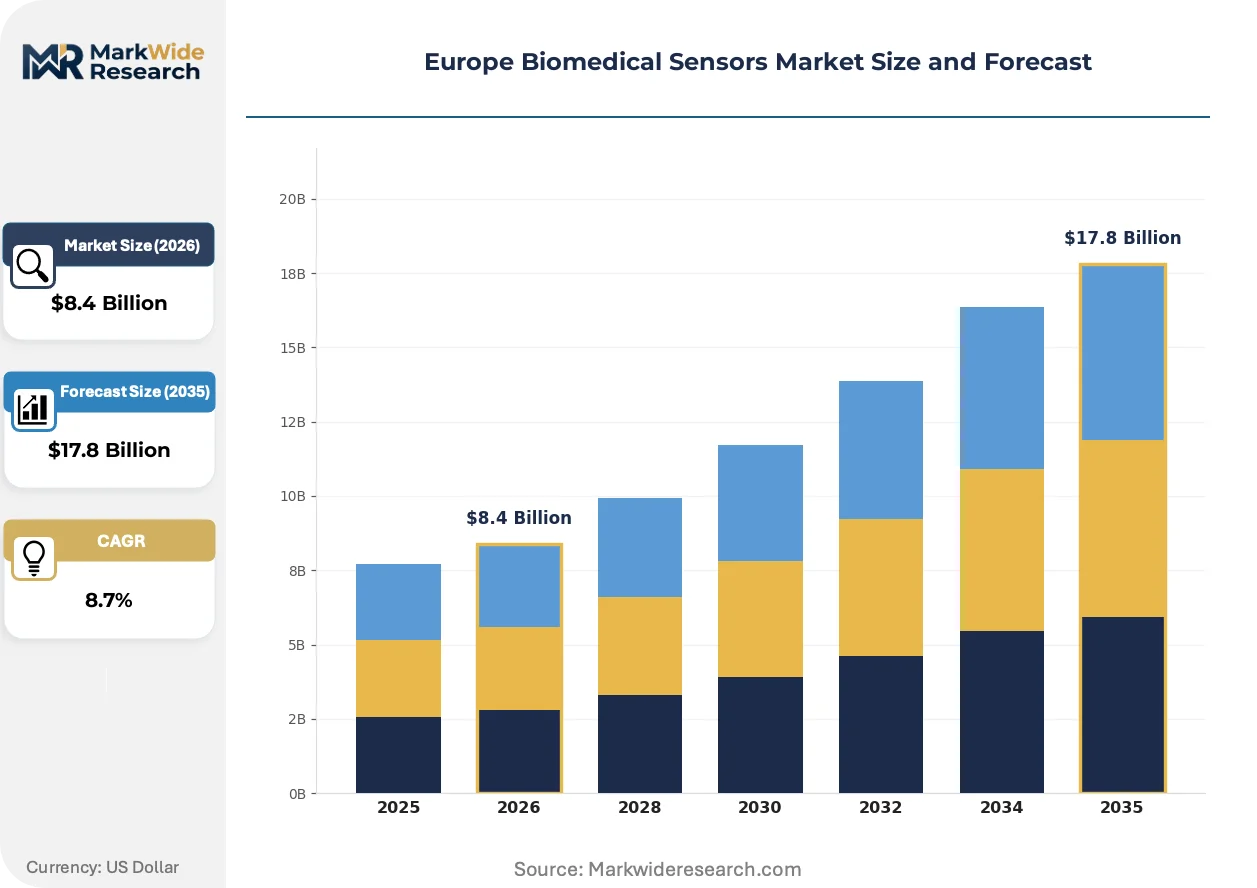
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Invasive Sensors, Non-Invasive Sensors End User: Hospitals, Research Laboratories, Homecare Settings, Diagnostic Centers Technology: Optical Sensors, Electrode Sensors, Microelectromechanical Systems, Biochemical Sensors Application: Patient Monitoring, Disease Diagnosis, Drug Development, Health Management |
| Companies Covered | Medtronic, GE Healthcare, Siemens Healthineers, Analog Devices Inc., Honeywell International Inc., TE Connectivity, LumaSense Technologies, Opsens, Sensirion AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biomedical Sensors Market Shifts & Advancements
Convergence between semiconductor miniaturization and molecular diagnostics is redefining performance benchmarks across wearable and implantable sensor categories. Three developments are commanding strategic attention from European device manufacturers and procurement networks.
Silicon photonics is consolidating optical biosensing into single-chip architectures that combine light sources, waveguides, and detectors for label-free biomolecular detection. Diagnostic imaging OEMs in the Netherlands and Switzerland are adopting these platforms for point-of-care coagulation testing, compressing the cost structure previously dominated by discrete optical subassemblies and external laser modules.
MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa and higher sensor devices. Manufacturers must now maintain electronic systems for traceability and periodic safety updates, with Swissmedic and national competent authorities conducting unannounced audits of technical documentation. Implantable neuromodulation sensors face the steepest compliance burden, with several notified bodies withdrawing from active implantable device certification due to liability exposure.
Hospital procurement consortia in France and Italy are consolidating sensor purchasing through regional group purchasing organizations that negotiate multi-year framework agreements. Device vendors must now demonstrate total cost-of-ownership metrics including calibration frequency, disposable consumption, and training requirements rather than competing on capital equipment price alone. This behavioral shift is most visible in Lombardy's centralized tendering for intensive care monitoring systems, where five-year service bundling has become a mandatory evaluation criterion.
Europe Biomedical Sensors Market Segmentation
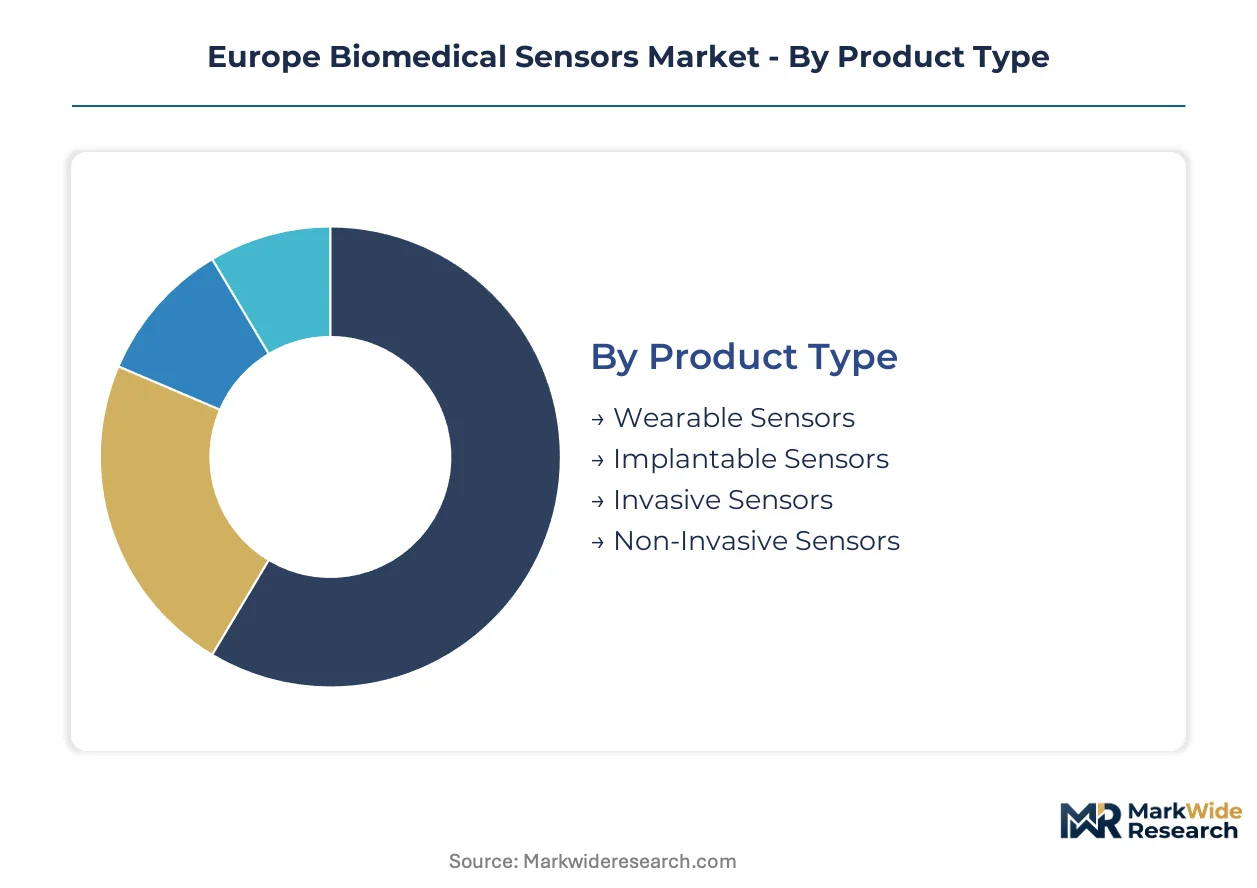
Biomedical sensor procurement across Europe fragments along technical performance thresholds and reimbursement eligibility tiers. Hospital procurement consortia in France and Germany evaluate segments through divergent clinical evidence requirements and total cost-of-ownership frameworks.
Product Type:
Supply concentration in MEMS foundries and biocompatible material producers reshapes competitive positioning across form factor categories.
- Wearable Sensors:Flexible substrate assemblies integrate photoplethysmography and accelerometry for ambulatory cardiac and metabolic monitoring. Germany's DMP reimbursement expansion for home glucose tracking concentrates demand in adhesive patch formats with 14-day wear durations.
- Implantable Sensors:Hermetically sealed titanium enclosures house pressure and glucose transducers requiring MDR Class III certification. Extended CE marking timelines at TÜV SÜD and BSI Group constrain new entrant capacity, favoring incumbents with captive notified body relationships.
- Invasive Sensors:Catheter-mounted temperature and pressure probes serve interventional cardiology and critical care applications. Swiss precision device clusters around Basel and Zurich anchor manufacturing for high-reliability arterial monitoring.
- Non-Invasive Sensors:Surface electrode and optical configurations dominate routine vital signs acquisition in emergency and general ward settings. Lombardy's regional tendering for intensive care infrastructure prioritizes five-year service bundling for these capital equipment categories.
Today's leader: Wearable Sensors. Tomorrow's challenger: Implantable Sensors.
End User:
Reimbursement pathway differentiation separates acute care procurement from emerging homecare channels.
- Hospitals:Centralized purchasing through France's regional GPOs and Italy's consorzi sanitari demands interoperability with proprietary HIS protocols. Procurement evaluation weights calibration frequency, disposable consumption, and training burden alongside capital cost.
- Homecare Settings:Remote patient monitoring reimbursement expansion across EU member states captures margin pools previously concentrated in institutional sales. Poland and Romania's EU cohesion fund allocations for critical care infrastructure create first-mover advantages for vendors with local service presence.
- Research Laboratories:Preclinical and clinical trial applications require customizable sensor configurations with open data architecture. EMA guidance on combination products shapes qualification timelines for investigational device exemptions.
- Diagnostic Centers:Point-of-care molecular diagnostics demand drives biochemical sensor volume in decentralized testing networks. Edge computing integration enables real-time pattern recognition for sepsis biomarker panels in emergency department triage workflows.
Acute care procurement dominates current revenue. Homecare reimbursement expansion delivers the steepest trajectory.
Technology:
Semiconductor fabrication scalability separates volume production leaders from specialty technology niches.
- Microelectromechanical Systems:Sub-millimeter pressure and flow transducers leverage foundry capacity in Grenoble and Dresden for minimally invasive surgical instruments. MEMS miniaturization expertise anchors Sensirion AG's dominance in respiratory device modules.
- Biochemical Sensors:Enzymatic and affinity-based transducers convert molecular recognition events into quantifiable electrical signals. Point-of-care molecular diagnostics demand climbs fastest for this category, though IP thickets around glucose oxidase formulations delay commercialization.
- Optical Sensors:Silicon photonics consolidation combines light sources, waveguides, and detectors for label-free biomolecular detection. Tissue perfusion variability and melanin interference constrain photoplethysmography accuracy in ambulatory pulse oximetry.
- Electrode Sensors:Electrochemical transduction architectures depend on platinum-group-metal-free materials to satisfy ECHA REACH compliance evolution. Three German specialty chemical producers concentrate medical-grade silicone and parylene C supply for encapsulation-dependent devices.
MEMS technology commands current volume leadership. Biochemical sensors gain share fastest on diagnostic decentralization.
Application:
Clinical workflow integration requirements determine sensor specification priorities and procurement evaluation criteria.
- Patient Monitoring:Continuous physiological parameter acquisition spans intensive care, general ward, and ambulatory environments. AI-enabled diagnostic convergence with edge computing reshapes performance benchmarks for real-time alarm generation.
- Disease Diagnosis:Point-of-care and laboratory-based detection platforms require distinct accuracy and throughput specifications. Optical coherence tomography patent thickets force licensing negotiations that extend product development timelines.
- Drug Development:Clinical trial endpoints depend on validated sensor biomarkers for therapeutic efficacy and safety monitoring. MDR Article 10 post-market surveillance mandates systematic follow-up data collection for Class IIa and higher devices.
- Health Management:Preventive and chronic disease protocols in Germany's DMP frameworks mandate continuous glucose and pressure tracking. EU Green Deal circular economy requirements favor modular battery replacement and recyclable polymer housing architectures.
Patient Monitoring anchors installed base. Disease Diagnosis expands most quickly on molecular diagnostic decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemistry and MEMS fabrication specialists concentrate in German university towns and Swiss precision manufacturing corridors, anchoring European sensor innovation capacity.
Germany
Chronic disease management protocols for diabetes and cardiovascular conditions mandate continuous physiological monitoring, expanding reimbursable indications for ambulatory glucose sensors. The country's DMP frameworks accelerate procurement of adhesive patch formats with extended wear durations. Dresden's semiconductor foundry ecosystem enables volume production of sub-millimeter pressure transducers for minimally invasive surgical instruments.
Switzerland
Precision device clusters around Basel and Zurich anchor manufacturing for high-reliability arterial monitoring and implantable pressure sensors. Swissmedic maintains stringent post-market surveillance requirements for active implantable devices, with several notified bodies withdrawing from certification due to liability exposure. The Basel precision device corridor specializes in hermetically sealed titanium enclosures for Class III sensor systems.
France
Regional group purchasing organizations consolidate sensor purchasing through multi-year framework agreements that demand total cost-of-ownership metrics. ANSM enforces clinical evidence thresholds for CE marking under the EU Medical Device Regulation. Lombardy-style centralized tendering in French hospital consortia now mandates five-year service bundling for intensive care monitoring capital equipment.
Netherlands
Silicon photonics adoption for point-of-care coagulation testing compresses cost structures previously dominated by discrete optical subassemblies. ECHA REACH compliance evolution accelerates substitution toward platinum-group-metal-free electrode materials in electrochemical biosensors. Eindhoven's photonics integration ecosystem consolidates light sources, waveguides, and detectors into single-chip architectures for label-free biomolecular detection.
Poland
EU cohesion fund allocations for critical care infrastructure create first-mover advantages for patient monitoring system integrators establishing local service presence. The country's national pharmaceutical regulator aligns with EMA guidance on combination products for investigational device qualifications. Warsaw and Krakow hospital modernization programs prioritize interoperability with proprietary French and Italian hospital information system protocols.
Europe Biomedical Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European biomedical sensor value chain. Vertically integrated medical technology conglomerates with captive foundry capacity and in-house biocompatibility testing infrastructure command premium positioning in implantable categories. The vendor base fragments across MEMS miniaturization specialists, optical sensing architects, and electrochemical assay developers. Dominant competitive moves include strategic partnerships with notified bodies to compress CE marking timelines and portfolio diversification into AI-enabled diagnostic convergence platforms.
Among diversified health technology conglomerates, Medtronic and GE Healthcare occupy positions anchored by vertical manufacturing control and diagnostic imaging system integration respectively. Sensirion AG exemplifies the MEMS miniaturization specialist archetype, with its Swiss GmbH structure reflecting precision device cluster proximity. Siemens Healthineers represents the R&D-intensive optical sensing architect segment. These three entities illustrate how geographic concentration in German and Swiss industrial corridors shapes competitive positioning across wearable, implantable, and diagnostic sensor categories.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Siemens Healthineers |
| Analog Devices Inc. |
| Honeywell International Inc. |
| TE Connectivity |
| LumaSense Technologies |
| Opsens |
| Sensirion AG |
| Others |
Supply & Pricing Matrix
MEMS fabrication specialists concentrated in Grenoble and Dresden generate labor-cost differentials that widen pricing-tier spreads between premium implantable platforms and standard wearable modules. The scarcity of electrochemistry-MEMS-regulatory hybrid talent pools in Swiss precision corridors further stratifies cost structures across CE marking tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates capital equipment vendors from disposable-focused suppliers across European hospital procurement networks. Three-tier pricing structure across premium, standard, and economy levels differentiates by MDR certification grade and after-sales service intensity. Cost compression in standard-tier wearable sensors intensifies because MEMS foundry scaling in Dresden enables volume production economics. Academic medical centers in Germany exhibit lowest price sensitivity due to research funding buffers, while Poland's EU cohesion fund hospitals demonstrate highest sensitivity to total cost-of-ownership metrics.
Supply Chain Analysis
MDR Article 10 qualification gating and REACH substance restrictions constrain supplier pools for biocompatible encapsulation materials. Medical-grade silicone and parylene C supply concentrates in Germany, with semiconductor fabrication capacity anchored in France and Switzerland. Raw material dependencies include platinum-group-metal-free electrode formulations, hermetic titanium enclosures, and photonics-grade silicon substrates. Single-source vulnerability pervades notified body relationships, as TÜV SÜD and BSI Group capacity constraints extend qualification timelines. Distribution runs through regional group purchasing organizations in France and Italy's consorzi sanitari.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European biomedical sensors hinges on MEMS foundry scaling economics displacing discrete component architectures, while premium-tier shifts toward AI-enabled diagnostic convergence capture higher service bundling yields.
For Market Incumbents: Acquire captive notified body relationships to compress CE marking timelines for novel implantable categories. Defensive consolidation demands backward integration into biocompatible material supply chains as ECHA REACH restrictions concentrate input sources among German specialty chemical producers. Capacity addition in Grenoble semiconductor corridors secures volume positioning for minimally invasive surgical instrument transducers. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms bypass incumbent GPO lock-in across France's regional purchasing networks. White-space targets center on Poland and Romania's EU cohesion fund critical care infrastructure, where local service presence creates first-mover advantages. Point-of-care molecular diagnostics for emergency department sepsis triage offers the most penetrable application wedge. For Investors and Strategic Acquirers: Diversified health technology conglomerates are the most active acquirer in this space, seeking MEMS miniaturization capabilities and optical sensing IP portfolios. Long-term viability frames around 5-10 year regulatory compliance automation and AI diagnostic integration trajectories. Acquisition target archetypes include Swiss precision device specialists with hermetic sealing expertise. The signal to watch is notified body withdrawal patterns from active implantable device certification.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | Compressed timelines at TÜV SÜD accelerate market access for Class III implantables. |
| Hospital System Partnership | Five-year service bundling with Lombardy consorzi sanitari locks in intensive care monitoring share. |
| Software Companion Development | Edge computing integration with biochemical sensors enables real-time sepsis biomarker pattern recognition. |
| Reimbursement Strategy | Germany's DMP framework expansion for home glucose tracking opens adhesive patch format demand. |
| Backward Integration | In-house biocompatibility testing infrastructure buffers against ECHA REACH material substitution volatility. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each regional cluster. The approach combines structured interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation against EMA guidance documents, MDR technical documentation databases, and hospital procurement tender records. Bottom-up sensor shipment modeling and top-down healthcare expenditure allocation triangulate market sizing across the analysis window.
Granularity-level framing applies country-specific reimbursement pathway differentiation, technology-type production economics, and end-user procurement behavior dimensions. Segmentation modeling captures product type, technology platform, application workflow, and end-user channel dynamics throughout the forecast period. CAGRs derive from installed base expansion rates and replacement cycle compression in acute care settings, cross-referenced against EU Green Deal circular economy mandate implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics consolidation would alter the outlook if discrete optical subassembly cost structures persist. Forecasts reflect assumptions around MDR transition deadline enforcement and notified body capacity normalization. A model refresh is warranted upon material change in ECHA REACH restricted substance list expansion or Swissmedic active implantable surveillance requirement escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market