
 Global Viral Clearance Services Market | 2026-2036
Global Viral Clearance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Viral Clearance Services Market Foresight
North American capacity expansion is fragmenting the competitive landscape for viral clearance outsourcing. Charles River Laboratories leverages its integrated testing portfolio to capture multi-phase biologics programs from early development through commercial release. Merck KGaA sustains technology leadership in chromatography-based clearance platforms, while WuXi AppTec anchors cost-competitive scale through its Chinese and U.S. dual-site network.
Viral clearance services encompass validated methodologies for detecting and eliminating adventitious agents from biological therapeutics, employing techniques such as nanofiltration at 20-50 nm pore ratings, UV-C irradiation at 254 nm wavelength, and low-pH chemical inactivation to achieve log reduction values exceeding 4-6 logs. These processes ensure compliance with ICH Q5A safety standards before human administration of biologics. Chromatography and filtration modalities dominate current service revenue due to their established validation packages and broad applicability across monoclonal antibody platforms. Gene therapy applications represent the fastest-expanding demand segment as AAV and lentiviral vector manufacturing scales strain existing in-house clearance capabilities.
FDA guidance documents, EMA viral safety guidelines, and ICH Q5A harmonized standards collectively mandate demonstrable viral clearance for all biological products, creating non-negotiable demand for validated service providers. The EU's updated GMP Annex 1 requirements for contamination control further tighten documentation expectations for contract testing labs serving European markets. Stakeholders must evaluate whether to build captive clearance capacity or lock in long-term partnerships before gene therapy manufacturing bottlenecks intensify competition for qualified service slots.
Market Dynamics
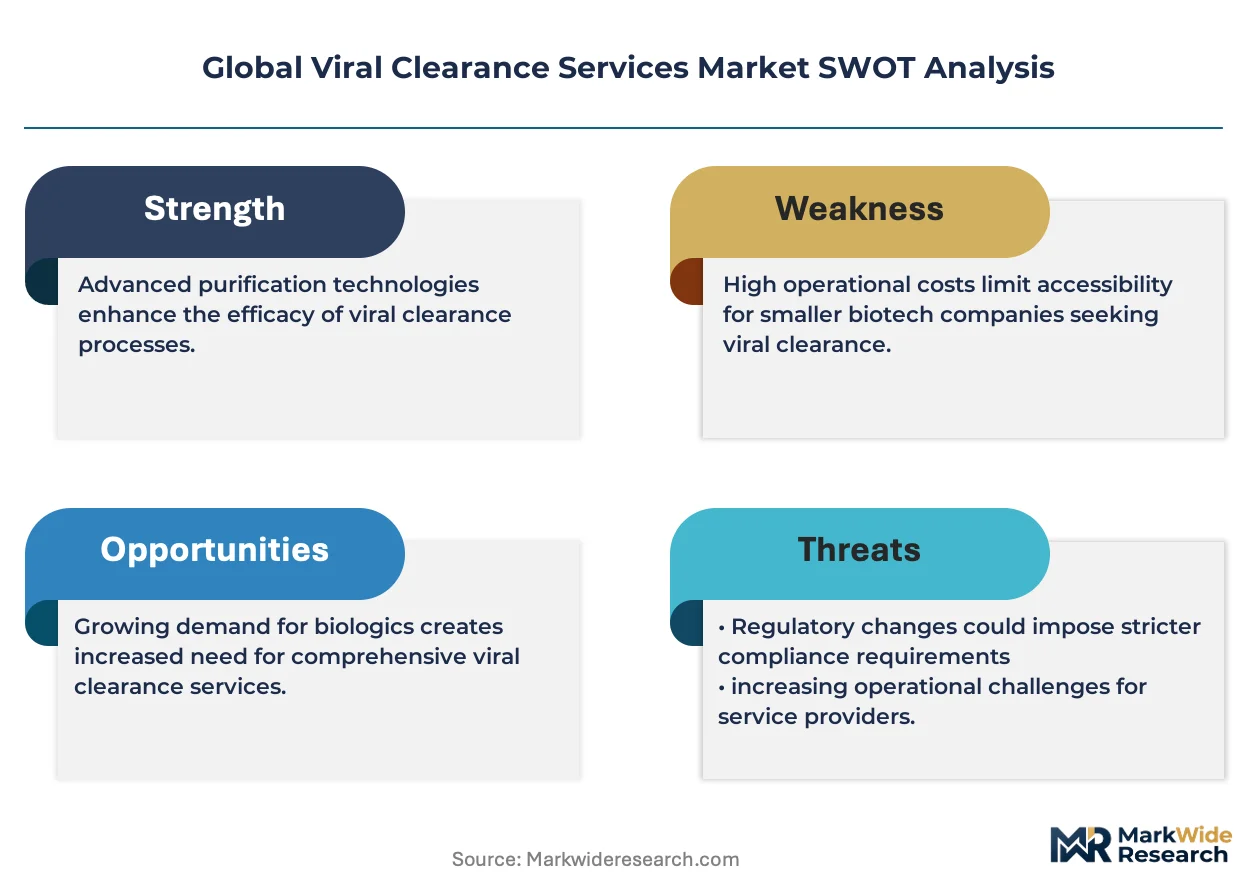
Gene therapy manufacturing scale-up is forcing viral clearance capacity into structural shortage, as AAV and lentiviral vector production lines outpace in-house validation capabilities at biopharma developers.
Growth Catalysts
- ICH Q5A Harmonization:The ICH Q5A guideline mandates demonstrable viral clearance for all biological products, creating non-negotiable demand for validated third-party service providers across FDA, EMA, and PMDA jurisdictions.
- Chromatography Platform Expansion:Protein A and ion-exchange chromatography systems achieve 4-6 log reduction values for enveloped viruses, making these modalities the default choice for monoclonal antibody clearance validation.
- Boston-Cambridge Cluster Density:Concentrated gene therapy manufacturing in Massachusetts and California requires localized clearance infrastructure, driving contract testing lab expansion within 50-mile radii of production facilities.
Market Restraints
- Specialized Equipment Concentration:Nanofiltration skids and UV-C irradiation systems rely on German and Swiss precision manufacturing, exposing service providers to extended lead times and currency volatility.
- Validation Timeline Rigidity:FDA's updated guidance on viral safety evaluation requires 12-18 month protocol development cycles, locking developers into fixed partnerships and limiting vendor switching.
- In-House Build-or-Buy Tension:Large biopharma sponsors face capital allocation decisions between captive clearance suites and outsourced contracts, with depreciation schedules favoring internalization at commercial scale.
Strategic Opportunities
- India CDMO Emergence:Indian contract development and manufacturing organizations are investing in BSL-3 containment facilities to capture viral clearance outsourcing from domestic biosimilar and vaccine producers.
- Continuous Processing Integration:Perfusion bioreactor adoption in upstream manufacturing creates demand for inline viral clearance technologies that operate without batch interruption.
- EU GMP Annex 1 Alignment:The European Union's updated contamination control requirements for sterile manufacturing are pushing European developers toward certified contract testing labs with pre-validated clearance packages.
Industry Challenges
- Bioanalytical Scientist Scarcity:Viral clearance validation requires expertise in qPCR, TCID50, and next-generation sequencing assays, with qualified personnel concentrated at fewer than 200 specialized facilities worldwide.
- Legacy Facility Retrofit Costs:Existing contract testing labs face seven-figure capital outlays to upgrade HVAC, waste handling, and containment systems to BSL-3 standards required for live virus spiking studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Viral Clearance Services Market |
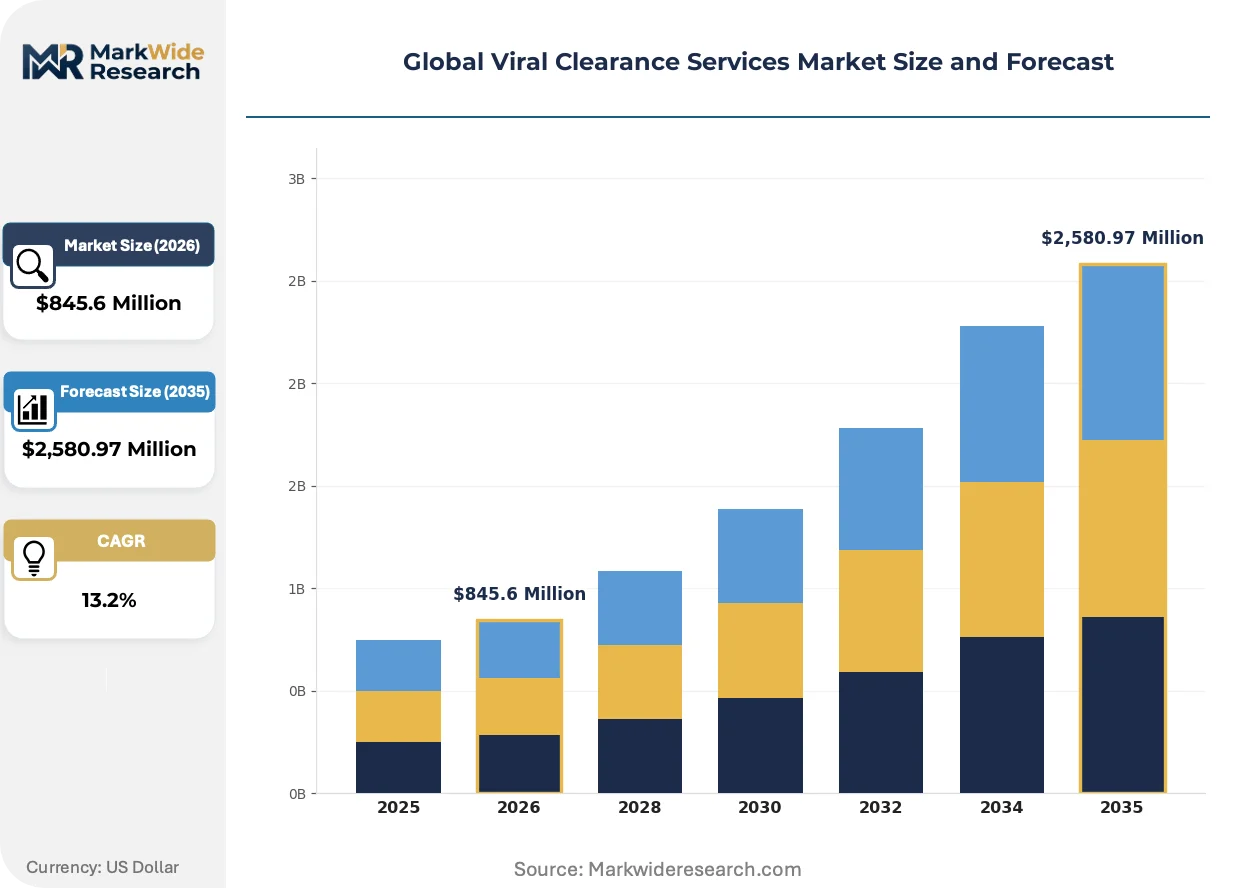
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $2,580.97 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Filtration, UV Treatment, Chromatography, Chemical Inactivation, Heat Treatment, Affinity Adsorption Application: Biopharmaceuticals, Vaccine Manufacturing, Gene Therapy Production, Plasma-Derived Products, Cell Therapy, Diagnostic Reagents End User: Contract Manufacturing Organizations, Biotechnology Firms, Research Institutions, Pharmaceutical Developers, Government Labs, Academic Facilities Deployment: In-House, Third-Party Testing Labs, Pilot Scale, Commercial Scale, Automated Systems, Manual Processes |
| Companies Covered | Charles River Laboratories, Merck KGaA, WuXi AppTec, Sartorius AG, Texcell, Syngene International, WuXi Biologics, Eurofins Scientific, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Viral Clearance Services Market Shifts & Advancements
Service providers are repositioning around platform standardization and modular facility design to compress validation timelines and capture gene therapy manufacturing contracts before capacity constraints harden into long-term bottlenecks.
Membrane adsorber technology is hybridizing anion exchange chromatography with nanofiltration into single-unit operations, reducing footprint and buffer consumption by half. Gene therapy CDMOs in Germany and the United States are piloting these systems for AAV vector clearance. This convergence is compressing the traditional three-step clearance train into two-unit processes, threatening standalone filtration service revenue.
EMA's revised viral safety guidelines now explicitly recognize next-generation sequencing for adventitious agent detection, displacing in vivo and in vitro indicator cell assays for certain product categories. European biotech developers are accelerating NGS qualification programs to align with this regulatory acceptance. The shift most affects plasma-derived and vaccine product lines, where traditional methods required six-month testing windows.
Biopharma procurement teams are consolidating viral clearance contracts under multi-phase master service agreements that span early development through commercial release, displacing transactional project-by-project sourcing. CDMOs with integrated testing portfolios in Massachusetts and North Carolina are capturing these consolidated contracts. This concentration is most visible among mid-cap gene therapy developers lacking internal analytical infrastructure.
Global Viral Clearance Services Market Segmentation
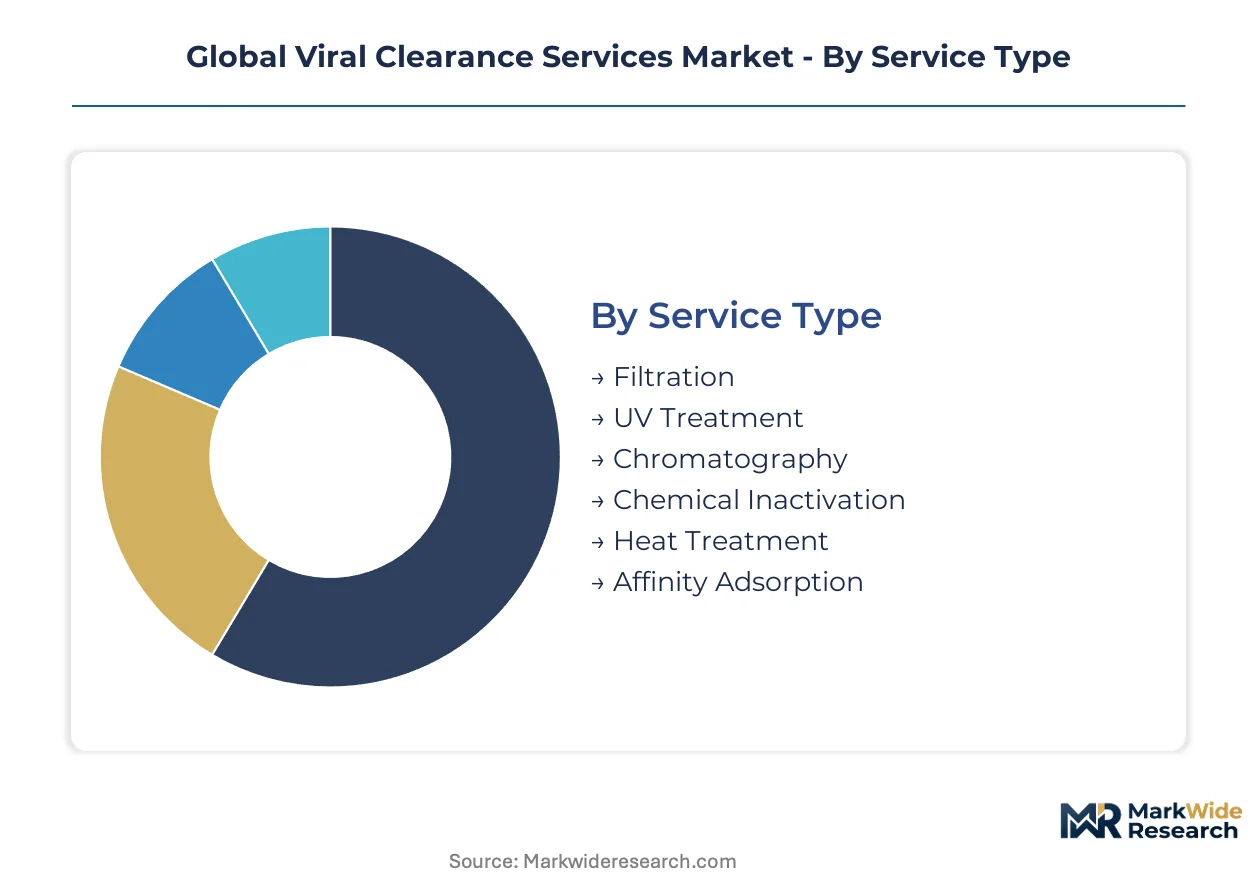
Viral clearance services fragment across multiple operational dimensions, each carrying distinct validation requirements and margin profiles. Understanding these divisions reveals where capacity constraints concentrate and which service configurations command pricing premiums.
Service Type:
Clearance methodologies span the full spectrum from physical separation to chemical destruction, with selection driven by product stability and regulatory precedent.
- Chromatography:Protein A and ion-exchange resins achieve 4-6 log reduction values for enveloped viruses through binding affinity differentiation. Demand concentrates in Massachusetts and California monoclonal antibody facilities where platform standardization accelerates validation cycles.
- Filtration:Nanofiltration at 20-50 nm pore ratings provides size-based exclusion for non-enveloped viruses with minimal product modification. German and Swiss equipment manufacturers supply the precision skids, creating lead time vulnerabilities for North American service providers scaling gene therapy capacity.
- UV Treatment:254 nm wavelength irradiation damages viral nucleic acids without thermal stress.
- Chemical Inactivation:Low-pH and solvent-detergent protocols target lipid-enveloped agents.
- Heat Treatment:Pasteurization methods apply primarily to plasma-derived product lines.
- Affinity Adsorption:Membrane adsorber technology hybridizes chromatography with filtration into single-unit operations.
The dominant share belongs to chromatography, while affinity adsorption is closing the gap fastest.
Application:
End-use sectors impose divergent contamination risk profiles and regulatory scrutiny levels, shaping service provider specialization.
- Biopharmaceuticals:Monoclonal antibody and recombinant protein manufacturing represents the established revenue base, with validated clearance trains specified in FDA and EMA license applications.
- Gene Therapy Production:AAV and lentiviral vector manufacturing strains existing in-house capabilities, forcing developers toward contract testing labs with BSL-3 containment for live virus spiking studies.
- Vaccine Manufacturing:Egg-based and cell culture platforms require clearance validation for adventitious agents.
- Plasma-Derived Products:Pooling of human source material mandates redundant clearance steps.
- Cell Therapy:Autologous and allogeneic products present patient-specific contamination risks.
- Diagnostic Reagents:Lower regulatory burden permits streamlined validation packages.
Biopharmaceuticals command the largest contract value, though gene therapy production is expanding most quickly.
End User:
Customer organizational types determine contract structure, with procurement sophistication varying from transactional project work to multi-phase master service agreements.
- Contract Manufacturing Organizations:CDMOs in North America and Europe are expanding captive viral clearance capacity to differentiate integrated service offerings and capture gene therapy manufacturing contracts before capacity bottlenecks intensify.
- Biotechnology Firms:Mid-cap gene therapy developers lack internal analytical infrastructure, consolidating clearance contracts under multi-phase agreements spanning early development through commercial release.
- Pharmaceutical Developers:Large sponsors face build-or-buy capital allocation decisions between captive clearance suites and outsourced contracts.
- Research Institutions:Academic facilities require flexible, small-batch validation support.
- Government Labs:Public health manufacturing operates under distinct procurement frameworks.
- Academic Facilities:Limited budgets constrain service tier selection.
Contract manufacturing organizations absorb the majority of third-party service volume, while biotechnology firms are driving contract consolidation fastest.
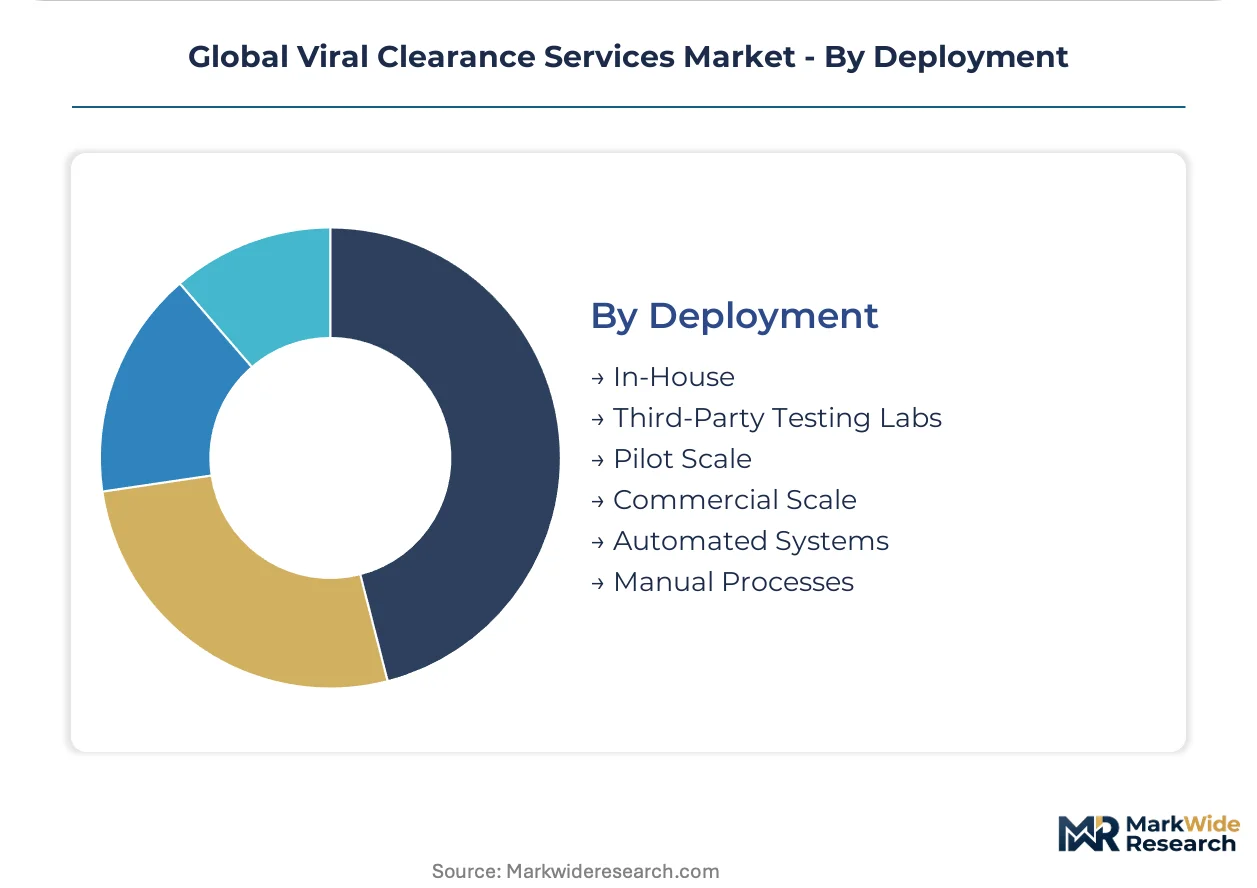
Deployment:
Operational scale and automation level determine facility capital intensity and personnel qualification requirements.
- Commercial Scale:Multi-thousand liter bioreactor trains demand continuous clearance validation with documented log reduction values for FDA and EMA regulatory submissions.
- Third-Party Testing Labs:Specialized facilities in Massachusetts, North Carolina, and Germany concentrate BSL-3 containment infrastructure and qualified bioanalytical scientists for live virus studies.
- In-House:Captive capacity requires seven-figure facility retrofit investments.
- Pilot Scale:Development-phase manufacturing tolerates manual processing.
- Automated Systems:Inline technologies enable continuous processing without batch interruption.
- Manual Processes:Labor-intensive methods persist at smaller scales.
Commercial scale deployments generate the highest absolute revenue, with third-party testing labs gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on viral safety evaluation anchors United States demand, while EMA's updated viral safety guidelines and ICH Q5A harmonization create synchronized compliance obligations across Germany, Switzerland, and the United Kingdom.
United States
Gene therapy manufacturing clusters in Massachusetts and California drive localized clearance infrastructure investment. FDA's updated guidance on viral safety evaluation for biotechnology products mandates 12-18 month protocol development cycles. The Boston-Cambridge corridor concentrates BSL-3 containment facilities within 50-mile radii of AAV and lentiviral vector production sites.
Germany
Precision manufacturing of nanofiltration skids and UV-C irradiation systems anchors equipment supply chains for North American service providers. EMA viral safety guidelines and EU GMP Annex 1 contamination control requirements tighten documentation expectations for contract testing labs. Bavarian and Baden-Württemberg industrial zones host chromatography platform specialists serving monoclonal antibody developers.
Switzerland
Swissmedic oversight of biological product licensing creates demand for validated third-party clearance protocols. The country's precision engineering base supplies German and North American service providers with specialized filtration equipment. Basel and Zurich regions concentrate viral clearance validation expertise for plasma-derived and vaccine product lines.
United Kingdom
Post-Brexit regulatory alignment with ICH Q5A standards maintains clearance validation requirements for biopharmaceutical exports. The MHRA's adoption of EMA-equivalent viral safety guidelines preserves market access for UK-based contract testing labs. London and Cambridge biotech clusters outsource live virus spiking studies to specialized facilities with BSL-3 containment.
India
Domestic biosimilar and vaccine production expansion drives investment in BSL-3 containment facilities by contract development organizations. CDSCO regulatory frameworks for biological product safety create demand for validated clearance methodologies. Hyderabad and Bengaluru biotech corridors anchor viral capacity investment for export-oriented manufacturing.
Global Viral Clearance Services Market Competitive Landscape
Integrated testing portfolios and specialized technology platforms split the market between full-service contract research organizations and equipment-anchored service providers. Consolidation pressure intensifies as gene therapy manufacturing bottlenecks harden competition for qualified BSL-3 facility slots. Three archetypes dominate: integrated CDMOs with captive analytical infrastructure, standalone contract testing labs with regulatory-specialized validation packages, and equipment manufacturers extending into service provision. Capacity expansion and multi-phase master service agreement capture represent the dominant competitive moves, with procurement teams consolidating clearance contracts under single-vendor relationships spanning early development through commercial release.
Within the integrated CDMO tier, Charles River Laboratories and WuXi AppTec exemplify archetypes combining geographic reach with platform standardization. Charles River Laboratories occupies a position representing North American-centric integrated testing portfolios, while WuXi AppTec anchors cost-competitive scale through dual-site network configuration. Merck KGaA sits within the equipment-anchored service provider archetype, representing European technology leadership in chromatography-based clearance platforms. These three entities collectively illustrate the strategic segmentation between integrated service breadth, geographic cost arbitrage, and technology-led positioning that defines current competitive structure.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Merck KGaA |
| WuXi AppTec |
| Sartorius AG |
| Texcell |
| Syngene International |
| WuXi Biologics |
| Eurofins Scientific |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Transatlantic air freight corridors linking German precision equipment manufacturers to Massachusetts gene therapy clusters impose cost premiums that cascade through validation service pricing, concentrating margin leverage with providers holding captive chromatography resin production or dual-site redundancy.
Pricing Analysis
Geographic price spreads between North American and European contract testing labs reflect equipment import duties and BSL-3 facility operating costs. Three-tier pricing structure across premium, standard, and economy levels segments by validation timeline urgency and regulatory submission support depth. Pricing pressure stems from Indian CDMOs investing in BSL-3 containment at lower cost bases. Mid-cap gene therapy developers exhibit highest price sensitivity due to constrained Series B runway funding.
Supply Chain Analysis
Charles River Laboratories, WuXi AppTec, and Lonza Group concentrate commercial-scale viral clearance capacity across the United States, Germany, and Switzerland. Chromatography resins, nanofiltration membranes, and UV-C irradiation lamps draw from German and Swiss precision manufacturing. Single-source vulnerability concentrates in 20-50 nm nanofiltration skid supply. Distribution runs through multi-phase master service agreements spanning development to commercial release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as gene therapy manufacturing scale-up outpaces in-house validation capabilities, creating specialized niches for BSL-3 containment providers and modular facility designers.
For Market Incumbents: Pre-empt capacity bottlenecks by accelerating BSL-3 facility expansion in Massachusetts and North Carolina corridors before Indian CDMOs capture mid-market share. Lock in multi-phase master service agreements with mid-cap gene therapy developers lacking internal analytical infrastructure. Vertical integration into chromatography resin production defends margin position against German equipment supplier price volatility.
For New Entrants and Emerging Players: Establish a beachhead in Indian biosimilar and vaccine producer segments where CDSCO regulatory frameworks create demand for validated clearance methodologies. Target Hyderabad and Bengaluru biotech corridors with cost-competitive BSL-3 containment offerings. Lead with next-generation sequencing qualification programs aligned to EMA viral safety guideline recognition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated CDMOs with captive analytical infrastructure over standalone equipment manufacturers. Five-to-ten year viability hinges on gene therapy pipeline maturation rather than monoclonal antibody platform commoditization. Watch for inflection in FDA guidance updates on viral safety evaluation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| BSL-3 Facility Expansion | Captures gene therapy manufacturing contracts before capacity constraints harden into structural shortage. |
| Chromatography Platform Standardization | Accelerates validation cycles for Massachusetts and California monoclonal antibody facilities. |
| Next-Generation Sequencing Qualification | Aligns with EMA viral safety guideline recognition for adventitious agent detection. |
| Multi-Phase Master Service Agreements | Consolidates procurement relationships spanning early development through commercial release. |
| Indian CDMO Market Entry | Exploits cost arbitrage for domestic biosimilar and export-oriented vaccine manufacturing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with viral clearance validation scientists, regulatory affairs leads at biotechnology firms, CDMO procurement directors, and bioanalytical laboratory managers. Secondary validation drew from FDA guidance documents, EMA viral safety guidelines, ICH Q5A harmonized standards, EU GMP Annex 1 contamination control requirements, and clinical trial database filings. Bottom-up service revenue estimates triangulated against top-down biopharmaceutical manufacturing capacity projections.
Calibration against historical capacity utilization rates and regulatory submission timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include service type, application, end user, and deployment scale. CAGRs derived from regression analysis of contract manufacturing organization expansion announcements and gene therapy pipeline progression. Industry-specific inputs incorporated BSL-3 facility construction lead times and chromatography platform validation cycle durations.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical venture funding levels and German-Swiss equipment export tariffs would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline rigidity and gene therapy manufacturing scale-up rates. Quarterly review of FDA guidance publication schedules and CDMO capacity expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Surgical Site Infection Control Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Alcohol Wipes Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Disinfection Equipment Market
Infection Control
Antimicrobial Catheters Market
Infection Control
North America Bloodstream Infection Testing Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Ear Infection Treatment Market
Infection Control
Hand Hygiene Market
Infection Control
Ultrasound Probe Disinfection Market