
 Breast Prosthesis Market | 2026-2036
Breast Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Prosthesis Market Analytics
Asset-light leasing models for surgical suites and outpatient reconstruction centers are narrowing the capital barrier for mid-tier clinics to stock premium prosthesis inventories. Establishment Labs leverages direct-to-provider financing partnerships to accelerate clinic adoption of its silicone portfolio. Mentor Worldwide LLC anchors its competitive stance through captive manufacturing of medical-grade elastomers. GC Aesthetics differentiates by specializing in custom-fit anatomical shapes for asymmetric reconstruction cases.
A breast prosthesis is a synthetic implant or external device designed to replicate breast form following mastectomy, lumpectomy, or congenital absence, typically constructed from medical-grade silicone elastomer, polyurethane foam, or gel-filled chambers with specific durometer and tear-strength specifications calibrated to match native tissue compliance. Silicone products command the dominant share of reconstructive procedures due to superior aesthetic longevity and reduced capsular contracture rates versus foam alternatives, while gel-based formulations represent the fastest-advancing segment as manufacturers refine cohesive polymer chemistry to mimic natural breast movement. Specialty stores and hospital outpatient departments capture the deepest margin pools by bundling fitting services with repeat-purchase accessories, whereas homecare channels remain underdeveloped for post-surgical recovery products.
FDA biocompatibility protocols and ISO 10993 standards govern material safety and cytotoxicity testing for all implantable silicone devices, while the EU Medical Device Regulation mandates enhanced clinical evidence requirements for Class III breast implants sold in European markets. These frameworks compress time-to-market for new entrants and elevate post-market surveillance obligations that favor manufacturers with established regulatory infrastructure. Stakeholders must monitor evolving reimbursement policies for contralateral prophylactic mastectomy and reconstruction to anticipate shifts in prosthesis procurement volume and product mix.
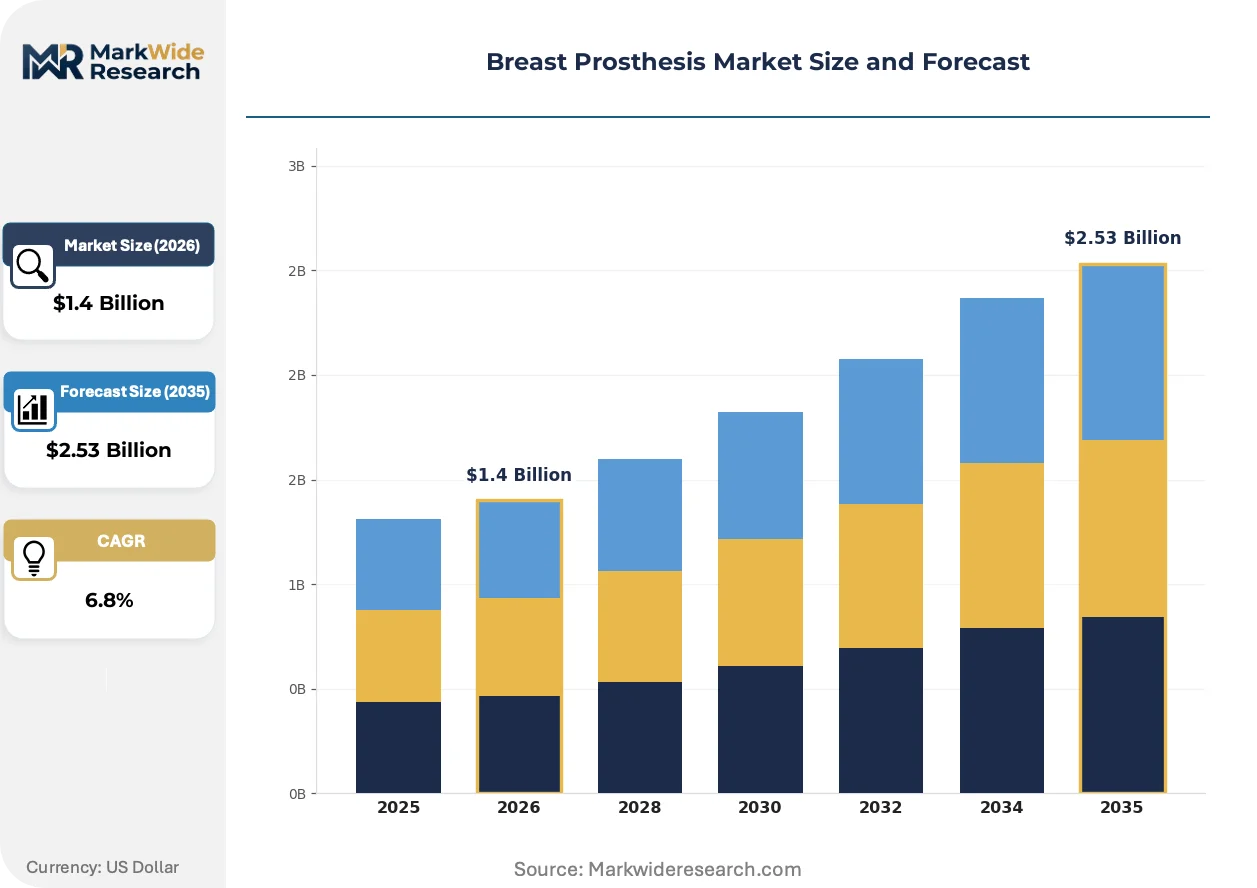
Market Dynamics
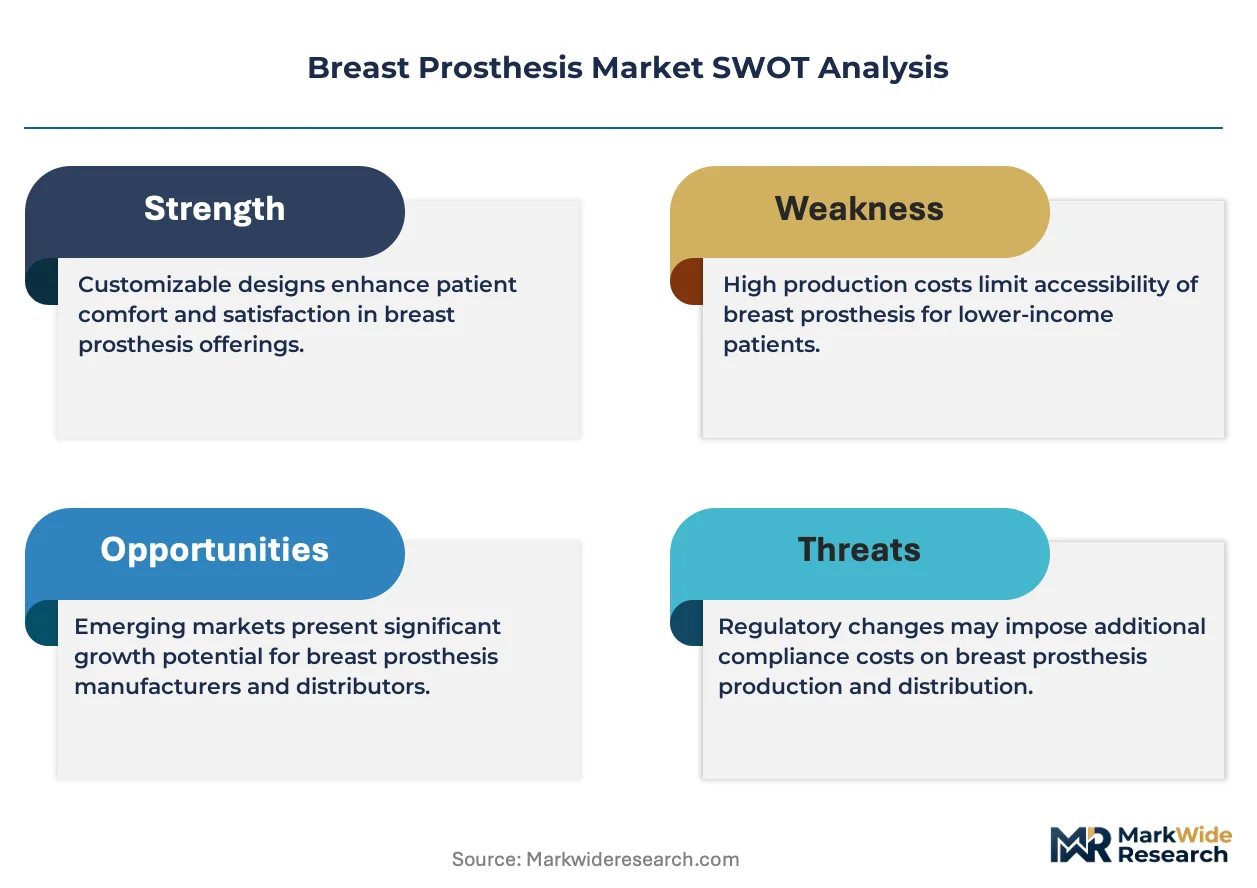
The breast prosthesis market is compressing around regulatory compliance costs as the FDA's updated biocompatibility guidance for long-term implantables forces manufacturers to rebuild testing protocols, while silicone supply concentration in specialized elastomer foundries creates procurement bottlenecks for mid-tier clinics.
Growth Catalysts
- Academic medical center expansion:Post-mastectomy reconstruction programs at university-affiliated hospitals are scaling silicone prosthesis procurement volumes through centralized purchasing consortia.
- ISO 10993 harmonization:Alignment of cytotoxicity testing standards across jurisdictions is reducing redundant certification burdens for multi-market manufacturers.
- Gel chemistry refinement:Cohesive polymer formulations are improving capsular contracture resistance, pulling demand away from foam-based alternatives in aesthetic reconstruction.
Market Restraints
- Medical-grade silicone feedstock volatility:Specialized elastomer precursors concentrate among three European chemical suppliers, exposing manufacturers to input cost spikes.
- EU MDR clinical evidence requirements:Enhanced post-market surveillance obligations for Class III implants are extending time-to-market for product line extensions.
- Biologic matrix substitutes:Autologous fat grafting techniques are capturing select reconstruction cases previously routed to permanent implants.
Strategic Opportunities
- Direct-to-provider financing:Leasing partnerships for surgical suites are enabling outpatient reconstruction centers to stock premium prosthesis inventories without capital outlay.
- Asymmetric reconstruction specialization:Custom-fit anatomical shapes for unilateral mastectomy cases remain underserved by standard symmetrical product lines.
- Homecare recovery products:Post-surgical accessories and external prosthesis channels are underdeveloped relative to implantable device penetration.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity assay bottlenecks are extending pre-submission timelines for novel silicone formulations.
- Reimbursement policy fragmentation:Contralateral prophylactic mastectomy coverage varies across US state Medicaid programs, complicating volume forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Prosthesis Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Foam, Gel, Custom-Made End User: Hospitals, Clinics, Homecare, Specialty Stores Size: Small, Medium, Large, Extra Large Material: Silicone Rubber, Polyurethane, Cotton, Nylon |
| Companies Covered | Establishment Labs, Amoena Medizin-Orthopädie-Technik GmbH, Allergan Inc., American Breast Care, Anita Dr. Helbig GmbH, Mentor Worldwide LLC, GC Aesthetics, POLYTECH Health & Aesthetics, Sientra Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Prosthesis Market Evolving Landscape
Silicone polymer engineering is converging with digital fitting workflows to reshape how reconstruction clinics match prosthesis specifications to patient anatomy, compressing the traditional trial-and-error fitting cycle.
Cohesive silicone gel technology is hybridizing with 3D surface scanning systems to enable patient-specific prosthesis selection. Academic reconstruction centers are adopting these combined platforms fastest, replacing standardized sizing protocols. This convergence is compressing revision surgery rates while elevating inventory complexity for distributors managing multi-SKU portfolios.
The EU Medical Device Regulation is tightening post-market clinical follow-up requirements for Class III breast implants sold in European markets. Manufacturers must now submit periodic safety update reports with real-world performance data. High-volume implant producers are responding by building dedicated European vigilance infrastructure, while smaller competitors are withdrawing from the region.
Patients are requesting bundled fitting services that combine initial prosthesis selection with multi-year accessory replacement programs. Hospital outpatient departments are capturing this shift by integrating certified fitters into surgical workflows, displacing independent specialty retailers. This pattern concentrates margin pools in the United States, where reconstruction rates following cancer surgery exceed most other national markets.
Breast Prosthesis Market Segmentation
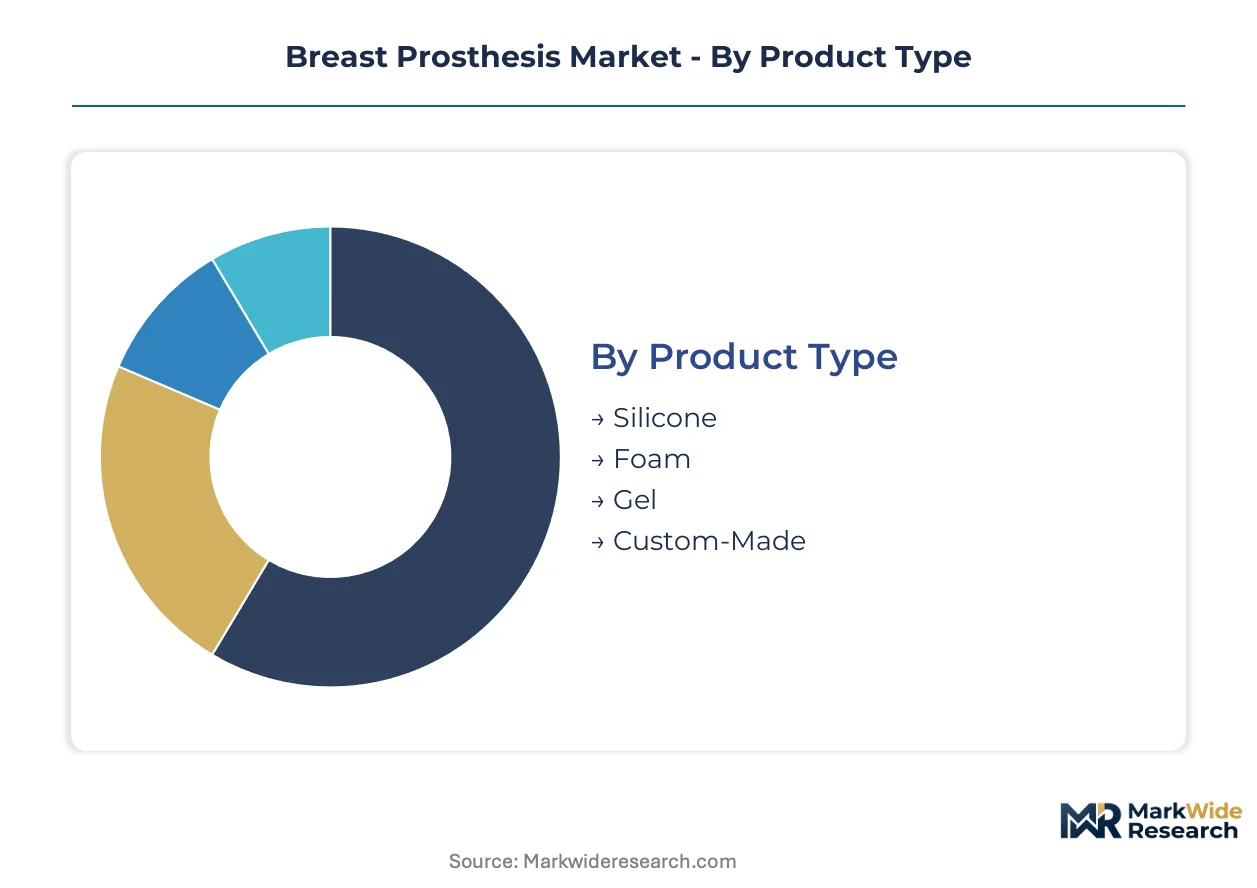
Product configuration in the breast prosthesis market determines reimbursement pathways, inventory carrying costs for distributors, and the technical skill required of certified fitters. Segmentation by material chemistry and end-use channel reveals where margin pools concentrate versus where volume flows.
Product Type:
Cost tier stratification across implantable versus external devices shapes procurement patterns and clinical workflow integration.
- Silicone:Medical-grade elastomer formulations with calibrated durometer and tear-strength specifications match native tissue compliance. Demand concentrates in academic medical centers with centralized purchasing consortia, driven by superior aesthetic longevity and reduced capsular contracture rates versus alternatives.
- Gel:Cohesive polymer chemistry refined to mimic natural breast movement and rotation. Reconstruction clinics in the United States are rotating procurement toward these formulations fastest, pulled by improving capsular contracture resistance and digital fitting workflow compatibility.
- Foam:Polyurethane foam construction offers lightweight external alternatives for post-surgical recovery periods.
- Custom-Made:Patient-specific anatomical shapes address asymmetric reconstruction cases underserved by standard symmetrical lines.
Silicone holds installed capacity. Gel is rotating up the share rankings.
End User:
Application setting determines bundling potential for fitting services and repeat-purchase accessory programs.
- Hospitals:Inpatient and outpatient surgical departments integrate prosthesis selection into mastectomy reconstruction workflows. United States hospital systems are capturing deepest margin pools by embedding certified fitters into surgical teams, displacing independent retailers through bundled service models.
- Specialty Stores:Dedicated fitting centers combine initial prosthesis selection with multi-year accessory replacement programs. These channels face compression as hospital outpatient departments expand reconstruction service lines and direct-to-provider financing models enable clinic inventory stocking.
- Clinics:Ambulatory reconstruction centers leverage asset-light leasing for surgical suites to stock premium inventories.
- Homecare:Post-surgical recovery products and external prosthesis channels remain underdeveloped relative to implantable penetration.
Hospitals anchor volume concentration. Specialty stores are defending margin position through service differentiation.
Size:
Volume distribution across dimensional specifications reflects reconstruction case mix and contralateral matching requirements.
- Medium:Standard dimensional specifications address the majority of unilateral reconstruction cases requiring symmetry with remaining native tissue.
- Large:Expanded specifications serve patients with greater native breast volume or those seeking augmentation-adjacent outcomes.
- Small:Reduced dimensions accommodate prophylactic mastectomy cases and patients with minimal native tissue.
- Extra Large:Specialized specifications address outlier anatomical requirements and revision reconstruction cases.
Medium holds baseline demand concentration. Large is expanding most quickly as reconstruction rates rise.
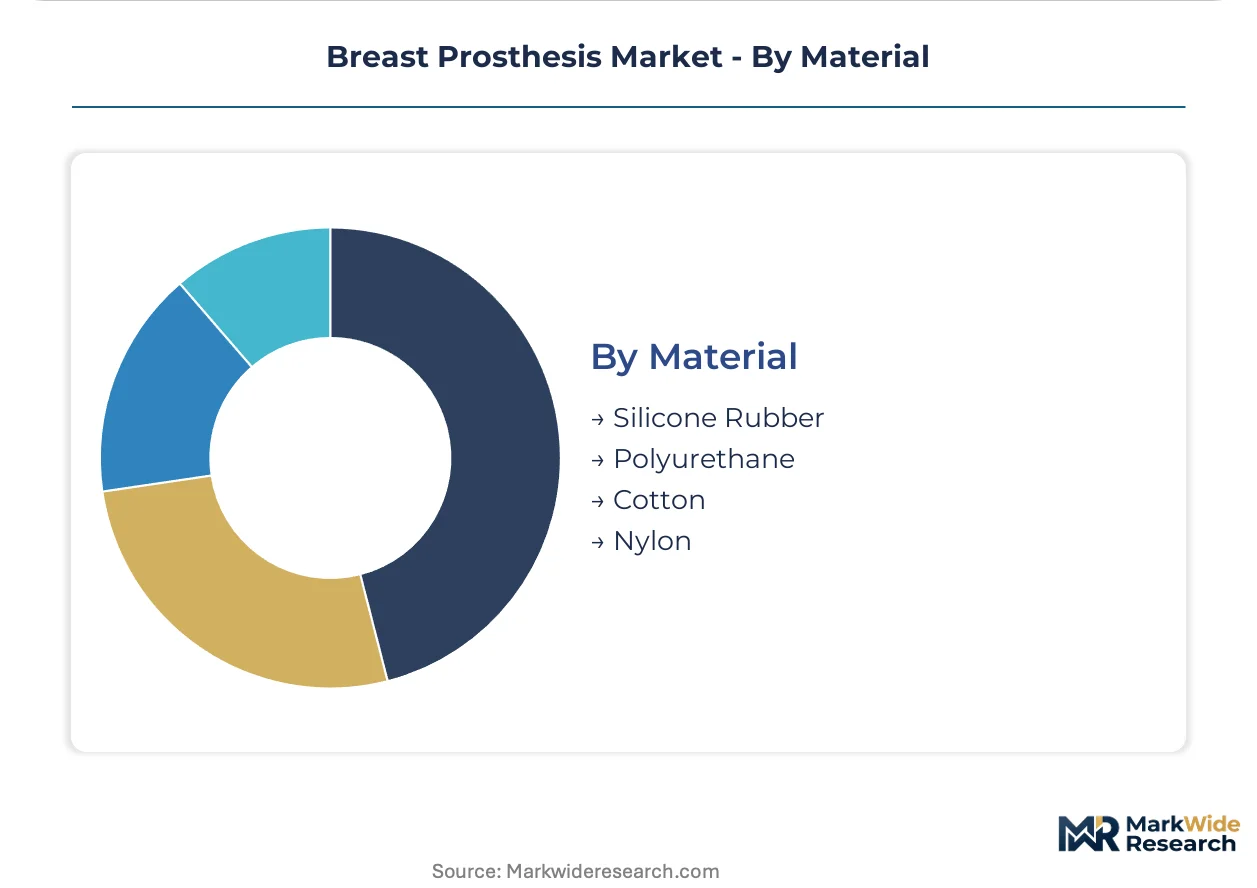
Material:
Supply concentration in specialized elastomer foundries creates procurement bottlenecks that differentiate competitive positioning.
- Silicone Rubber:Medical-grade elastomer precursors concentrate among three European chemical suppliers, exposing manufacturers to input cost volatility. FDA biocompatibility protocols and ISO 10993 cytotoxicity testing requirements govern all implantable formulations.
- Polyurethane:Foam-based external prostheses serve recovery-phase applications where implantable devices are contraindicated or patient preference favors non-surgical alternatives.
- Cotton:Natural fiber constructions provide lightweight external options for immediate post-surgical comfort.
- Nylon:Synthetic textile components feature in external prosthesis covers and accessory products.
Silicone rubber commands implantable segment priority. Polyurethane retains external application share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in breast prostheses tilt toward import-dependent markets with sophisticated reconstruction infrastructure, while manufacturing concentrates where medical-grade silicone chemistry and regulatory expertise overlap. The United States, Germany, Japan, and the United Kingdom anchor procurement volumes, with Brazil emerging as Latin America's reconstruction hub.
United States
Academic medical centers in Boston and Houston drive silicone prosthesis procurement through centralized purchasing consortia. FDA biocompatibility protocols for long-term implantables elevate compliance costs for new entrants. The reconstruction corridor spanning New York Metro to Philadelphia captures deepest margin pools by embedding certified fitters into surgical workflows.
Germany
EU MDR clinical evidence requirements for Class III implants compress time-to-market for manufacturers serving European markets. The country's national pharmaceutical regulator enforces enhanced post-market surveillance obligations that favor established players. Industrial clusters in Bavaria and Baden-Württemberg host specialized elastomer foundries supplying medical-grade silicone precursors.
Japan
PMDA oversight of implantable devices maintains stringent cytotoxicity testing standards aligned with ISO 10993 frameworks. The Tokyo-Osaka corridor concentrates reconstruction clinic density and digital fitting platform adoption. METI industrial policy supports domestic manufacturing of cohesive gel formulations for aesthetic reconstruction cases.
United Kingdom
NHS reimbursement pathways for post-mastectomy reconstruction sustain steady prosthesis procurement volumes through hospital outpatient departments. The country's national pharmaceutical regulator harmonizes with EU MDR vigilance requirements despite post-Brexit regulatory divergence. London and Manchester anchor specialty fitting service networks competing with integrated hospital models.
Brazil
ANVISA registration requirements for Class III medical devices create regulatory barriers that filter import competition. São Paulo and Rio de Janeiro concentrate private reconstruction clinic capacity serving regional demand. Rising contralateral prophylactic mastectomy rates are expanding addressable market size for silicone implant portfolios.
Breast Prosthesis Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with captive regulatory infrastructure and specialized elastomer chemistry capabilities. Three strategic archetypes dominate: vertically integrated silicone specialists, external prosthesis fabricators with fitting service networks, and contract manufacturers serving private-label distributors. Competitive moves center on direct-to-provider financing partnerships and geographic withdrawal from high-compliance jurisdictions like the EU.
Among the named participants, Establishment Labs and Mentor Worldwide LLC occupy positions in the integrated manufacturing tier, while GC Aesthetics exemplifies the specialization archetype focused on anatomical customization. Amoena Medizin-Orthopädie-Technik GmbH anchors the external prosthesis segment with established fitting infrastructure. These entities represent contrasting strategic postures rather than direct peer competitors across all product configurations.
| Leading Market Players |
|---|
| Establishment Labs |
| Amoena Medizin-Orthopädie-Technik GmbH |
| Allergan Inc. |
| American Breast Care |
| Anita Dr. Helbig GmbH |
| Mentor Worldwide LLC |
| GC Aesthetics |
| POLYTECH Health & Aesthetics |
| Sientra Inc. |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp corridor freight dynamics compress landed costs for medical-grade silicone elastomers while amplifying price differentiation between implantable and external prosthesis tiers. Supply concentration in Bavarian chemical foundries feeds procurement bottlenecks that force mid-tier clinics toward premium gel formulations or economy foam alternatives.
Pricing Analysis
Hospital outpatient departments anchor three-tier pricing structure across premium, standard, and economy levels in the breast prosthesis market. Price differentiation rests on ISO 10993 certification tier and volume scale through centralized purchasing consortia. Pricing pressure stems from EU MDR compliance costs extending time-to-market for product line extensions. Mid-tier ambulatory clinics exhibit highest price sensitivity, while academic medical centers with captive financing partnerships demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from specialized elastomer foundries in Germany, Switzerland, and the Netherlands stabilize working capital for manufacturers facing biocompatibility testing bottlenecks. Raw material dependencies center on medical-grade silicone precursors, cohesive polymer catalysts, and polyurethane foam substrates. Single-source vulnerability concentrates among three European chemical suppliers exposing producers to input cost volatility. Distribution runs through hospital procurement consortia and direct-to-provider financing partnerships displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breast prosthesis market sits in early-cycle expansion as digital fitting workflows accelerate clinic adoption of cohesive gel formulations and compress revision surgery rates. Academic medical center procurement growth and direct-to-provider financing penetration create structural tailwinds for premium product tiers.
For Market Incumbents: Harden regulatory infrastructure against EU MDR post-market surveillance obligations by building dedicated European vigilance capabilities. Fortify silicone supply security through backward integration into medical-grade elastomer chemistry or long-term offtake agreements with Bavarian foundries. Autologous fat grafting substitutes threaten permanent implant volumes in aesthetic reconstruction cases. For New Entrants and Emerging Players: Asymmetric reconstruction cases in outpatient clinics represent the most penetrable entry point, as standard symmetrical product lines underserve unilateral mastectomy patients requiring custom-fit anatomical shapes. Homecare recovery products and external prosthesis channels remain underdeveloped relative to implantable penetration. Partner with asset-light surgical suite leasing platforms to bypass capital barriers for inventory stocking. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents seeking to exit high-compliance implantable segments under EU MDR pressure. Long-term viability favors manufacturers with captive regulatory infrastructure and specialized elastomer chemistry capabilities. Monitor FDA biocompatibility guidance evolution for early signals of compliance cost escalation that would accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biocompatibility Compliance Investment | Rebuilds testing protocols for long-term implantables under updated guidance elevating barriers for smaller competitors. |
| Direct-to-Provider Financing Partnership | Enables outpatient reconstruction centers to stock premium silicone inventories without capital outlay through surgical suite leasing. |
| Digital Fitting Platform Integration | Compresses revision surgery rates by hybridizing cohesive gel technology with 3D surface scanning systems at academic centers. |
| European Vigilance Infrastructure Buildout | Satisfies EU MDR periodic safety update report requirements with real-world performance data from Class III implant portfolios. |
| Asymmetric Reconstruction Specialization | Captures underserved unilateral mastectomy cases through patient-specific anatomical shapes beyond standard symmetrical lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with reconstructive surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and certified prosthesis fitters. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, ISO 10993 testing records, and CMS Medicare reimbursement data. Bottom-up volume estimates from clinic-level adoption patterns were triangulated against top-down market sizing from manufacturer shipment disclosures.
Calibration against historical reconstruction procedure volumes and prosthesis replacement cycles anchored projections across the analysis window. Segmentation dimensions modeled include material chemistry tier, end-use channel configuration, product size specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating digital fitting platform penetration and contralateral prophylactic mastectomy rate trajectories. Forecast inputs incorporated silicone feedstock cost indices and academic medical center capital expenditure cycles.
Practitioners should monitor FDA biocompatibility protocol evolution, EU MDR enforcement intensity, and autologous reconstruction technique advancement for early signals of demand trajectory shift. Forecasts reflect assumptions regarding reimbursement stability for post-mastectomy reconstruction and centralized purchasing consortium expansion. Macroeconomic contraction affecting elective procedure volumes, regulatory deviation expanding compliance burdens, or technological substitution from biologic matrix alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Biopsy Devices Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Sphincterotomes Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Pericardial Patches Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Cardiac Implants Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Global Foot Orthotic Insoles Market