
 Global Swab and Viral Transport Medium Market | 2026-2036
Global Swab and Viral Transport Medium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Swab and Viral Transport Medium Market Foresight
Asset-light leasing models for automated swab production lines is reconfiguring capital barriers for mid-sized manufacturers entering the viral transport medium space. Thermo Fisher Scientific leverages its diagnostic reagent ecosystem to bundle transport media with downstream assay platforms. COPAN Diagnostics anchors its competitive position through proprietary flocked nylon fiber technology that improves pathogen elution rates. Puritan Medical Products sustains North American manufacturing scale while navigating FDA quality system requirements.
Swab and viral transport medium refers to sterile collection devices paired with buffered stabilizing solutions—typically containing Hank's balanced salt solution, fetal bovine serum, and antimicrobial agents—that preserve nucleic acid and viral integrity during specimen transit from collection site to laboratory. These systems enable reliable downstream polymerase chain reaction, antigen detection, and cell culture isolation across clinical and non-clinical settings. Flocked swabs command premium positioning due to superior sample release characteristics and patient comfort profiles compared with traditional fiber-wound designs. Molecular diagnostics applications represent the fastest-expanding segment as multiplex PCR panels and next-generation sequencing workflows proliferate in hospital laboratories. Diagnostic testing remains the volume anchor, sustained by seasonal respiratory surveillance and routine infectious disease screening protocols.
FDA quality system regulation and ISO 13485 medical device standards govern swab biocompatibility, sterilization validation, and transport medium shelf-life claims across the United States and European markets. EMA's in vitro diagnostic regulation is accelerating conformity assessment requirements for specimen collection devices distributed within the European Union. China's NMPA is tightening registration pathways for imported viral transport media used in domestic molecular diagnostics workflows. Stakeholders must monitor evolving harmonization between FDA and NMPA premarket review criteria to anticipate duplicative testing burdens or mutual recognition opportunities.
Market Dynamics
Automated production lines for flocked nylon swabs are compressing unit economics and forcing mid-tier manufacturers toward asset-light leasing arrangements rather than capital-intensive facility builds. This capital restructuring is redrawing competitive entry barriers across the specimen collection supply base.
Growth Catalysts
- Multiplex PCR panel expansion:Hospital laboratories in China are scaling molecular testing infrastructure, creating pull-through demand for viral transport media with extended nucleic acid stabilization windows.
- FDA's updated in vitro diagnostic guidance:Tighter quality benchmarks for transport systems are accelerating replacement cycles among diagnostic laboratories seeking premarket notification alignment.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting contract manufacturers to establish viral transport medium filling capacity near pharmaceutical clusters.
Market Restraints
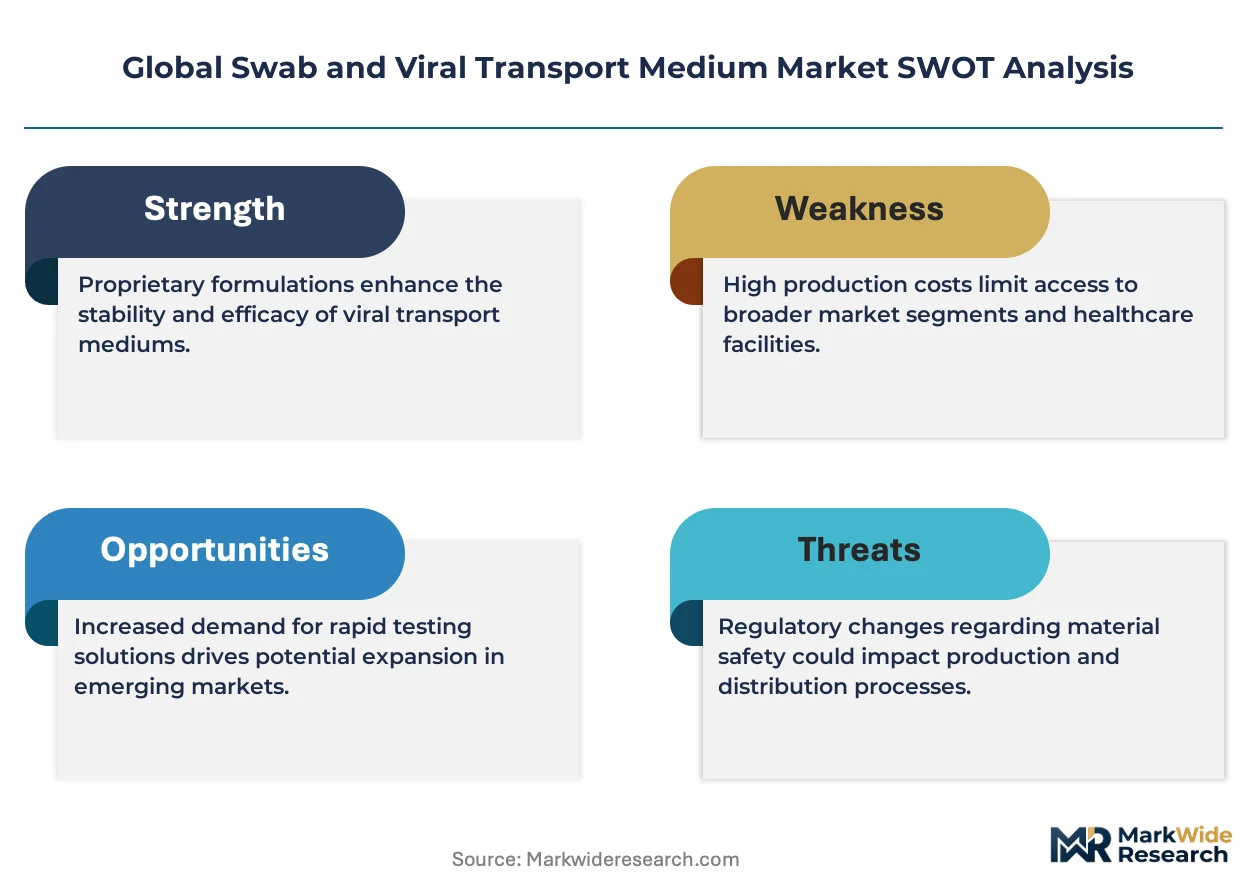
- Fetal bovine serum supply volatility:Transport medium formulations depend on this biological input, whose price swings and ethical sourcing constraints compress margin predictability.
- Single-source flocked fiber concentration:Proprietary nylon fiber technology remains concentrated among limited specialized suppliers, creating bottleneck risk for swab manufacturers.
- EMA's MDR transition timeline:Extended conformity assessment periods for specimen collection devices are delaying European market access for new transport medium entrants.
Strategic Opportunities
- Brazil's ANVISA streamlined registration:Recent pathway simplifications for imported diagnostic consumables create first-mover advantage for viral transport medium suppliers establishing local distribution.
- Point-of-care molecular testing convergence:Integration of isothermal amplification with smartphone-connected readers is creating demand for room-temperature-stable transport media in decentralized settings.
- Saudi Arabia's SFDA localization mandates:Healthcare sector nationalization policies are incentivizing joint ventures for domestic swab and transport medium production.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification backlogs for quality management systems are extending time-to-market for new transport medium manufacturers.
- Legacy LIS integration complexity:Automated specimen tracking systems require middleware development to interface with hospital laboratory information systems.
- Antimicrobial agent validation protocols:Demonstrating transport medium shelf-life stability demands extended real-time aging studies that tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Swab and Viral Transport Medium Market |
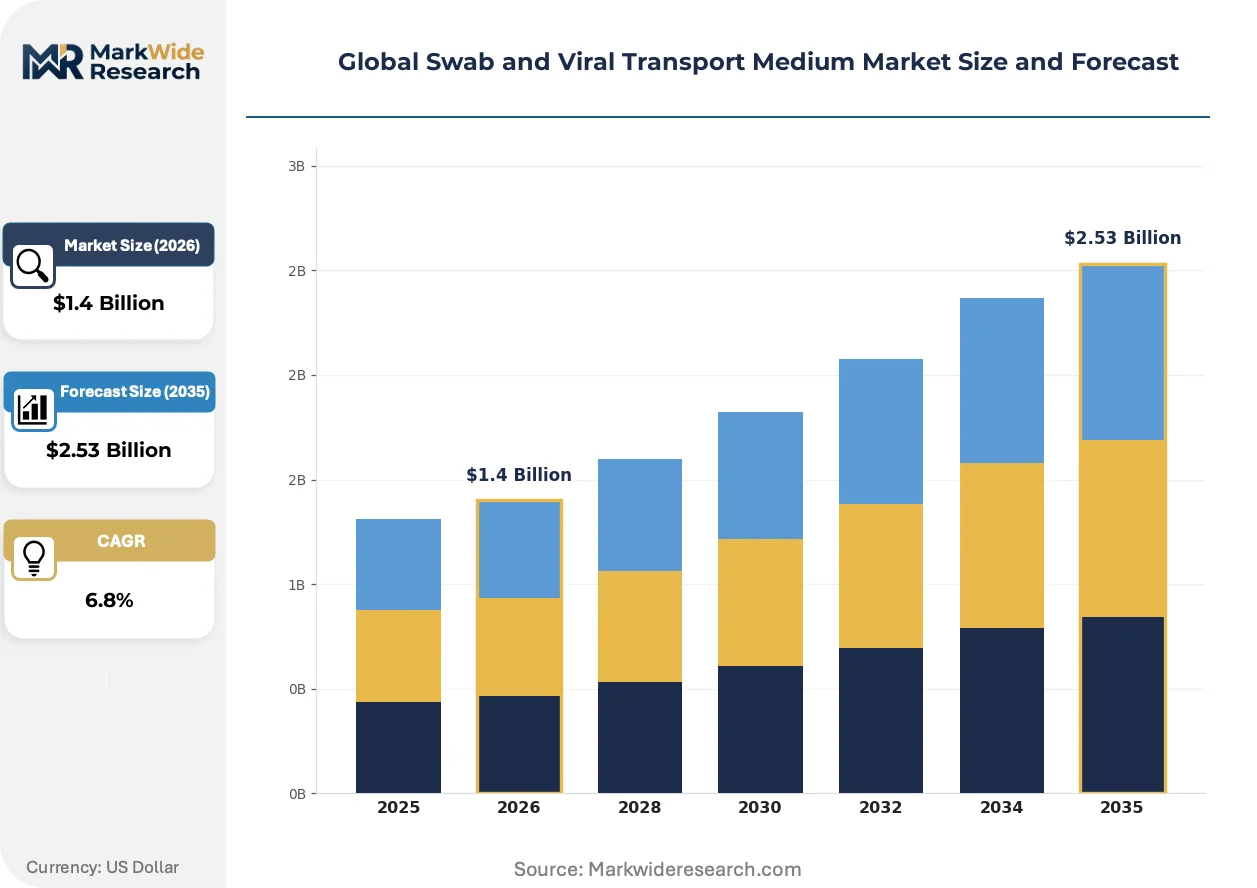
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocked Swabs, Foam Swabs, Polyester Swabs, Cotton Swabs, Viral Transport Medium Application: Diagnostic Testing, Molecular Diagnostics, Microbiological Analysis, Environmental Monitoring, Food Safety Analysis End User: Clinical Labs, Diagnostic Centers, Research Institutes, Pharmaceutical Companies, Blood Banks Distribution Channel: Direct Sales, Online Stores, Wholesale Distributors, Medical Supply Stores, Government Tenders |
| Companies Covered | Puritan Medical Products, McKesson Laboratories, Thermo Fisher Scientific, Titan Biotech Limited, Quidel Corporation, Becton, Dickinson and Company, Cardinal Health, Medical Wire & Equipment (MWE), COPAN Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Swab and Viral Transport Medium Market Shifts & Advancements
Specimen collection systems are undergoing material and process transformation as laboratories demand higher nucleic acid yields from smaller sample volumes. These shifts are compressing traditional fiber-wound swab architectures while elevating synthetic fiber and stabilization chemistry innovation.
Flocked nylon fiber technology is migrating from premium molecular diagnostics applications into standard infectious disease screening workflows. Reference laboratories in Germany and the United States are adopting these swabs for routine respiratory panels. The technology transfer is compressing price premiums and forcing traditional fiber-wound manufacturers to defend position through volume contracts.
China's NMPA is tightening registration pathways for imported viral transport media used in domestic molecular diagnostics workflows. This regulatory friction is accelerating local production partnerships and technology transfer agreements. Multinational suppliers are responding by qualifying domestic filling operations within China's free trade zones.
Diagnostic laboratories are consolidating procurement authority into centralized supply chain functions with outcome-based performance metrics. Group purchasing organizations are displacing direct manufacturer relationships for routine swab and transport medium categories. This behavioral shift is most visible in United States hospital networks where standardization committees now mandate flocked swab specifications across affiliated laboratories.
Global Swab and Viral Transport Medium Market Segmentation
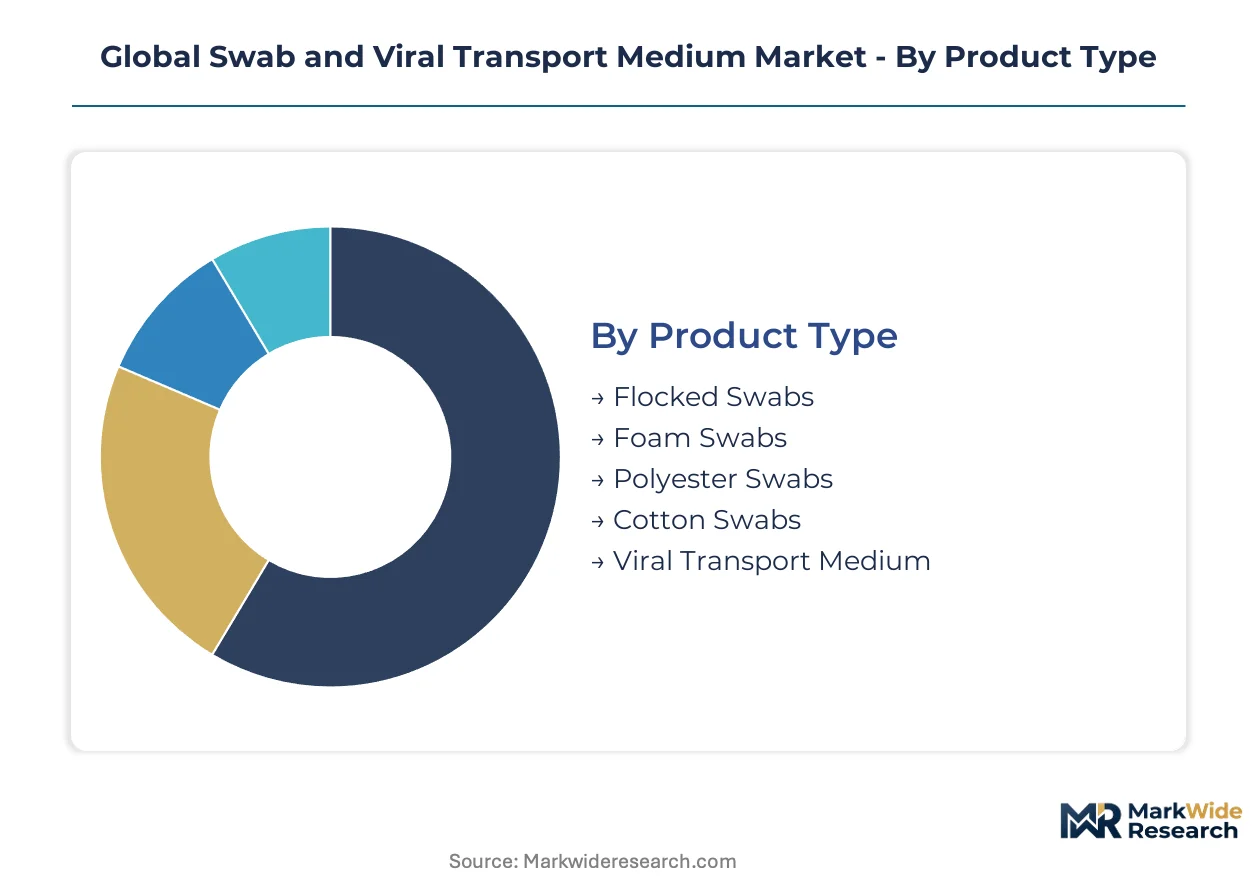
Product architecture in swab and viral transport medium markets determines stabilization chemistry compatibility, nucleic acid yield thresholds, and sterilization validation requirements. Application workflows separate high-throughput molecular diagnostics from routine screening protocols with distinct specimen handling demands.
Product Type:
Cost tier separates premium synthetic fiber platforms from commodity wound-fiber alternatives with divergent margin structures and capital intensity.
- Flocked Swabs:Perpendicular nylon fiber arrays maximize pathogen elution rates for PCR workflows. Demand concentrates in German and United States reference laboratories scaling multiplex respiratory panels, constrained by single-source fiber supply concentration.
- Viral Transport Medium:Buffered stabilizing solutions containing Hank's balanced salt solution and antimicrobial agents preserve nucleic acid integrity during transit. China's tier-one hospital networks are pulling extended stabilization window formulations as molecular testing capacity expands.
- Foam Swabs:Open-cell polyurethane structures suit surface sampling protocols in environmental monitoring applications.
- Polyester Swabs:Woven synthetic fiber constructions serve routine diagnostic screening with lower unit economics.
- Cotton Swabs:Traditional fiber-wound designs retain position in resource-limited settings and legacy procurement contracts.
Flocked swabs hold installed capacity in molecular diagnostics. Viral transport medium is rotating up the share rankings as stabilization chemistry becomes the value capture point.
Application:
Volume concentration in diagnostic testing creates procurement scale effects that reshape supplier negotiation leverage across hospital networks.
- Diagnostic Testing:Seasonal respiratory surveillance and routine infectious disease screening sustain baseline demand through high-frequency collection protocols. United States diagnostic laboratories are consolidating procurement authority into group purchasing organizations with outcome-based performance metrics.
- Molecular Diagnostics:Multiplex PCR panels and next-generation sequencing workflows demand superior nucleic acid yields from minimal sample volumes. China's hospital laboratories are scaling infrastructure fastest, creating pull-through for premium flocked swab and extended-stability transport medium combinations.
- Microbiological Analysis:Cell culture isolation protocols require sterile collection systems with validated bioburden specifications.
- Environmental Monitoring:Surface sampling applications in pharmaceutical manufacturing facilities drive specialized foam swab demand.
- Food Safety Analysis:Pathogen detection workflows in processing facilities use standardized collection devices for regulatory compliance sampling.
Diagnostic testing anchors procurement volume. Molecular diagnostics is climbing the fastest as workflow automation expands in hospital laboratories.
End User:
Customer type determines specification complexity, with clinical laboratories demanding ISO 13485-certified supply chains and research institutes tolerating broader validation tolerances.
- Clinical Labs:High-throughput processing centers require automated specimen tracking integration and lot-to-lot consistency for regulatory compliance. FDA quality system requirements and ISO 13485 standards govern procurement specifications in United States facilities.
- Diagnostic Centers:Decentralized collection sites prioritize room-temperature stability and simplified logistics over laboratory-grade performance.
- Research Institutes:Academic and government laboratories drive demand for specialized collection devices in epidemiological surveillance studies.
- Pharmaceutical Companies:Clinical trial specimen collection mandates chain-of-custody documentation and temperature excursion monitoring.
- Blood Banks:Donor screening protocols require sterile swabs with validated viral inactivation claims.
Clinical labs hold installed capacity. Diagnostic centers are gaining share fastest as point-of-care molecular testing decentralizes collection infrastructure.
Distribution Channel:
Supply concentration in wholesale distributors creates working capital requirements that favor manufacturers with balance sheet capacity for inventory financing.
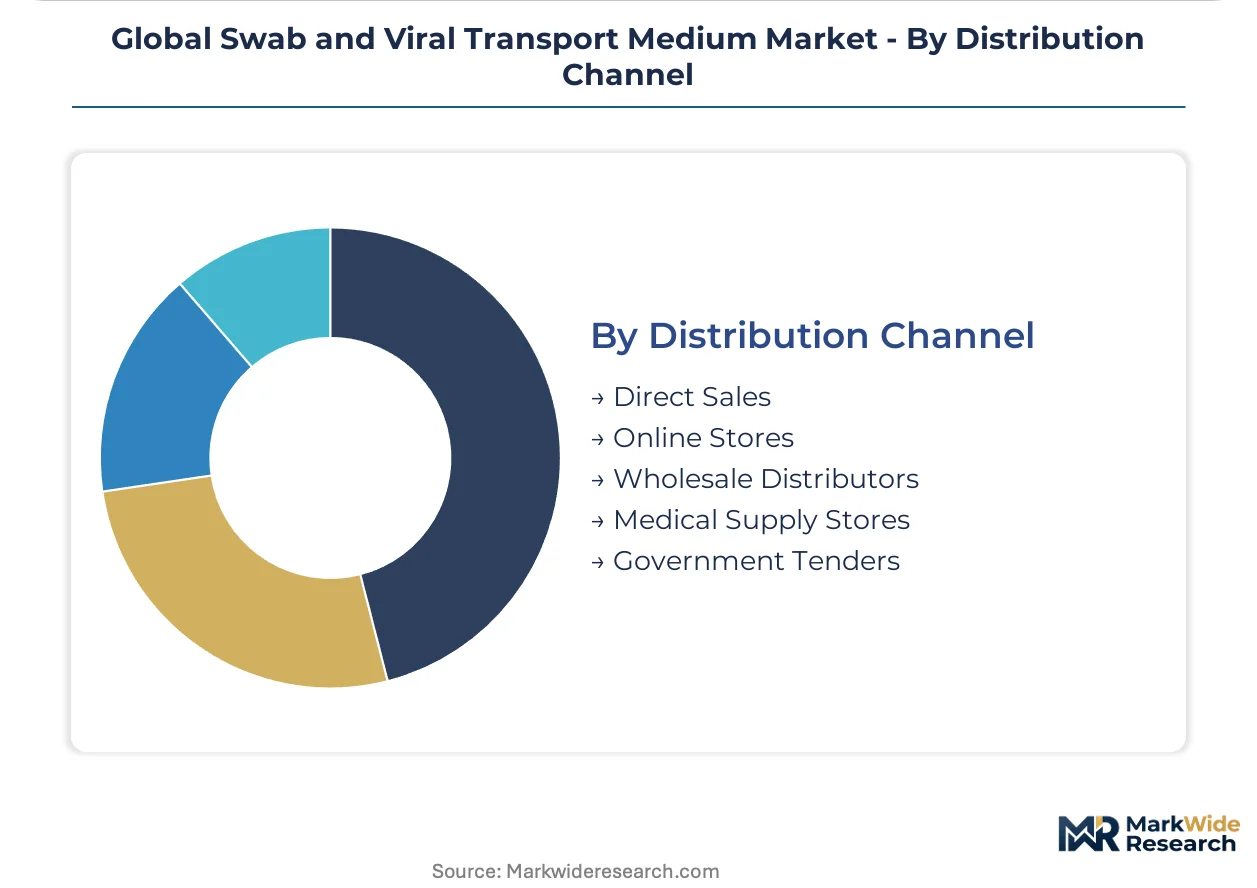
- Direct Sales:Manufacturer relationships with large hospital networks enable specification customization and volume pricing agreements. Group purchasing organizations in United States healthcare systems are displacing direct relationships for routine categories.
- Wholesale Distributors:Regional medical supply networks aggregate demand from mid-sized laboratories and diagnostic centers, requiring inventory depth and logistics capabilities.
- Government Tenders:National stockpile procurement and public health emergency preparedness programs create lumpy demand with extended payment terms.
- Online Stores:E-commerce platforms serve small research laboratories and point-of-care settings with standardized product configurations.
- Medical Supply Stores:Local distributors retain position in urgent procurement and replacement order scenarios.
Direct sales hold installed capacity. Government tenders are rotating up the share rankings as pandemic preparedness programs institutionalize strategic stockpiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and United States reference laboratories commanding premium flocked swab specifications, while Chinese manufacturers compete on stabilization chemistry scale. This asymmetry shapes procurement negotiation leverage across regional supply bases.
United States
Diagnostic laboratories in Massachusetts and California are consolidating procurement authority into group purchasing organizations with outcome-based performance metrics. FDA's updated in vitro diagnostic guidance tightens quality benchmarks for transport systems, accelerating replacement cycles. The Boston-Cambridge biotech corridor anchors molecular diagnostics infrastructure expansion.
Germany
Reference laboratories in Munich and Heidelberg are adopting flocked nylon swabs for routine respiratory panels, compressing traditional fiber-wound market share. EMA's MDR transition extends conformity assessment periods for specimen collection devices. The Rhine-Main pharmaceutical cluster drives demand for clinical trial-grade collection systems with chain-of-custody documentation.
China
Tier-one hospital networks in Beijing and Shanghai are scaling molecular testing capacity, pulling extended-stabilization transport medium formulations. NMPA registration pathway tightening for imported viral transport media accelerates local production partnerships. The Yangtze River Delta free trade zones host qualified domestic filling operations for multinational suppliers.
India
Contract manufacturers near Hyderabad and Ahmedabad are establishing viral transport medium filling capacity to serve pharmaceutical export clusters. The PLI scheme for medical devices attracts domestic manufacturing investment with production-linked incentives. The Gujarat pharmaceutical belt concentrates new specimen collection device assembly lines.
Brazil
Diagnostic distributors in São Paulo and Rio de Janeiro are streamlining import registration for viral transport media under ANVISA pathway simplifications. Recent regulatory reforms for diagnostic consumables create first-mover positioning for suppliers establishing local distribution. The São Paulo state healthcare procurement system consolidates demand from affiliated public hospital networks.
Global Swab and Viral Transport Medium Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and stabilization chemistry. The market structure organizes around three tiers: multinational diagnostics conglomerates bundling transport media with assay platforms, mid-sized manufacturers leasing automated production capacity, and regional contract fillers serving localized regulatory requirements. Two strategic archetypes dominate—vertically integrated reagent-to-device suppliers and asset-light specialists outsourcing fiber production. Competitive moves concentrate on strategic partnerships for NMPA registration support and capacity expansion through leased production lines rather than greenfield facility investment.
Among North American-based manufacturers, Puritan Medical Products and COPAN Diagnostics exemplify the component-specialist archetype with differentiated fiber technology positioning. Thermo Fisher Scientific represents the platform-integrator model, leveraging diagnostic reagent ecosystems to bundle specimen collection with downstream workflows. These three companies anchor the competitive structure without exhausting its variation—European and Asian specialists occupy parallel positions in regional supply bases.
| Leading Market Players |
|---|
| Puritan Medical Products |
| McKesson Laboratories |
| Thermo Fisher Scientific |
| Titan Biotech Limited |
| Quidel Corporation |
| Becton, Dickinson and Company |
| Cardinal Health |
| Medical Wire & Equipment (MWE) |
| COPAN Diagnostics |
| Others |
Supply & Pricing Matrix
Fetal bovine serum supply volatility compresses margin predictability across transport medium formulations while simultaneously forcing manufacturers toward synthetic stabilizer alternatives and extended supplier payment terms that reshape working capital structures throughout the specimen collection ecosystem.
Pricing Analysis
Clinical laboratory buyers anchor a three-tier pricing structure across premium flocked swabs, standard fiber-wound alternatives, and economy cotton designs. Price differentiation hinges on ISO 13485 certification tier and nucleic acid yield performance in downstream PCR workflows. Cost compression in the standard tier is intensifying as Chinese manufacturers scale Hank's balanced salt solution production. Reference laboratories in Germany and the United States show least price sensitivity due to outcome-based procurement mandates, while diagnostic centers in emerging markets prioritize unit economics over stabilization window extension.
Supply Chain Analysis
Extended payment terms from wholesale distributors concentrate working capital demands on manufacturers with balance sheet depth for inventory financing. Nylon fiber production concentrates in Italy and the United States, while viral transport medium filling capacity clusters in China, India, and Germany. Raw material flows draw from fetal bovine serum processors in Australia and New Zealand, antimicrobial chemical suppliers in Switzerland, and specialty buffer manufacturers in Japan. Single-source vulnerability in flocked fiber technology creates bottleneck exposure. Distribution runs through regional medical supply networks that aggregate mid-sized laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care molecular testing convergence signals early-cycle expansion as isothermal amplification workflows penetrate decentralized settings previously served by centralized laboratory infrastructure.
For Market Incumbents: Pre-empt synthetic fiber substitution by securing captive supply of perpendicular nylon arrays through backward integration into fiber extrusion or exclusive tolling arrangements with Italian specialty manufacturers. Accelerate FDA quality system alignment ahead of guidance enforcement windows to compress competitor replacement cycle participation. Defensive patent positioning around room-temperature stabilization chemistry limits entrant formulation freedom. For New Entrants and Emerging Players: Pursue white-space positioning in Brazil's ANVISA-simplified registration environment before established suppliers consolidate distribution partnerships in São Paulo and Rio de Janeiro diagnostic networks. Target India's PLI scheme beneficiaries for contract filling partnerships that circumvent capital-intensive greenfield facility requirements. Emphasize smartphone-connected reader compatibility as the go-to-market angle for point-of-care molecular testing workflows. For Investors and Strategic Acquirers: EMA's MDR transition timeline reshapes the acquisition landscape by extending conformity assessment periods and stranding new transport medium entrants without notified body relationships. Long-term viability favors asset-light specialists with leased automated production capacity and established ISO 13485 certification rather than capital-intensive integrated manufacturers. Monitor NMPA registration pathway harmonization with FDA premarket review criteria as the signal for duplicative testing burden reduction or mutual recognition opportunity emergence.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Partnership | Domestic filling qualification within Yangtze River Delta free trade zones accelerates China market access for multinational suppliers. |
| Leased Automated Production Line | Asset-light capacity expansion compresses capital barriers for mid-tier manufacturers entering viral transport medium filling. |
| Flocked Fiber Technology License | Proprietary nylon array access differentiates specimen collection performance in multiplex PCR panel workflows. |
| Group Purchasing Organization Contract | Centralized procurement authority in United States hospital networks mandates standardized flocked swab specifications across affiliates. |
| Extended Stabilization Formulation | Room-temperature nucleic acid preservation chemistry enables point-of-care molecular testing in decentralized diagnostic settings. |
Research Methodology
Operator-level perspectives from diagnostic laboratory directors, GPO contracts managers, biomedical engineers, and viral transport medium manufacturing plant managers anchored the qualitative base. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EMA notified body certificates, NMPA registration databases, and hospital procurement contract records. Bottom-up demand modeling across end-user segments triangulated with top-down supply capacity assessments from identified manufacturing clusters.
Scenario-bracketing framed the analytical approach across the projection horizon, with baseline, upside, and downside pathways reflecting regulatory timeline uncertainty and raw material supply disruption probability. Segmentation dimensions modeled include product architecture, application workflow, end-user type, and distribution channel structure. CAGRs derived from installed base replacement cycles, molecular testing infrastructure expansion rates, and procurement consolidation patterns. Fetal bovine serum price trajectory and flocked fiber capacity expansion served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, trade tariff regimes, or pandemic preparedness funding allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and supplier concentration stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Glass Pasteur Pipettes Market