
 US Smart Thermostat Market | 2026-2036
US Smart Thermostat Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Thermostat Market Analysis
Silicon carbide power semiconductors are decoupling thermostat hardware costs from traditional silicon price curves, enabling manufacturers to pack more sensing and processing capability into mid-tier price bands without margin erosion. Ecobee leverages its Canadian-origin cold-climate engineering heritage to dominate northern US utility partnership channels, while Honeywell Home anchors its position through backward integration into legacy HVAC control infrastructure and contractor training networks. Johnson Controls sustains commercial-grade credibility by extending its building automation software stack into smaller-format thermostats that compete on protocol interoperability rather than consumer aesthetics.
A smart thermostat constitutes a networked environmental control device incorporating temperature, humidity, and occupancy sensors with predictive algorithms that modulate HVAC equipment cycling through low-voltage relay interfaces or proprietary digital communications buses. Wi-Fi thermostats occupy the volume tier due to minimal installation friction and broad router compatibility, while learning thermostats capture disproportionate attention from utility demand-response programs that value automated setback precision. The professional installation segment retains structural importance because HVAC contractor relationships determine replacement-cycle access in the aging US housing stock, where compatibility verification with existing furnace control boards prevents widespread DIY adoption.
FERC Order 2222 enables aggregated thermostat fleets to participate in wholesale electricity markets, reshaping how manufacturers architect cloud backends for grid-interactive functionality. EPA ENERGY STAR certification thresholds and DOE appliance efficiency standards constrain hardware design choices while creating compliance moats against unbranded imports. California Title 24 building codes mandate smart thermostat compatibility in new construction, establishing a regulatory template that stakeholders must monitor as other states draft electrification roadmaps.
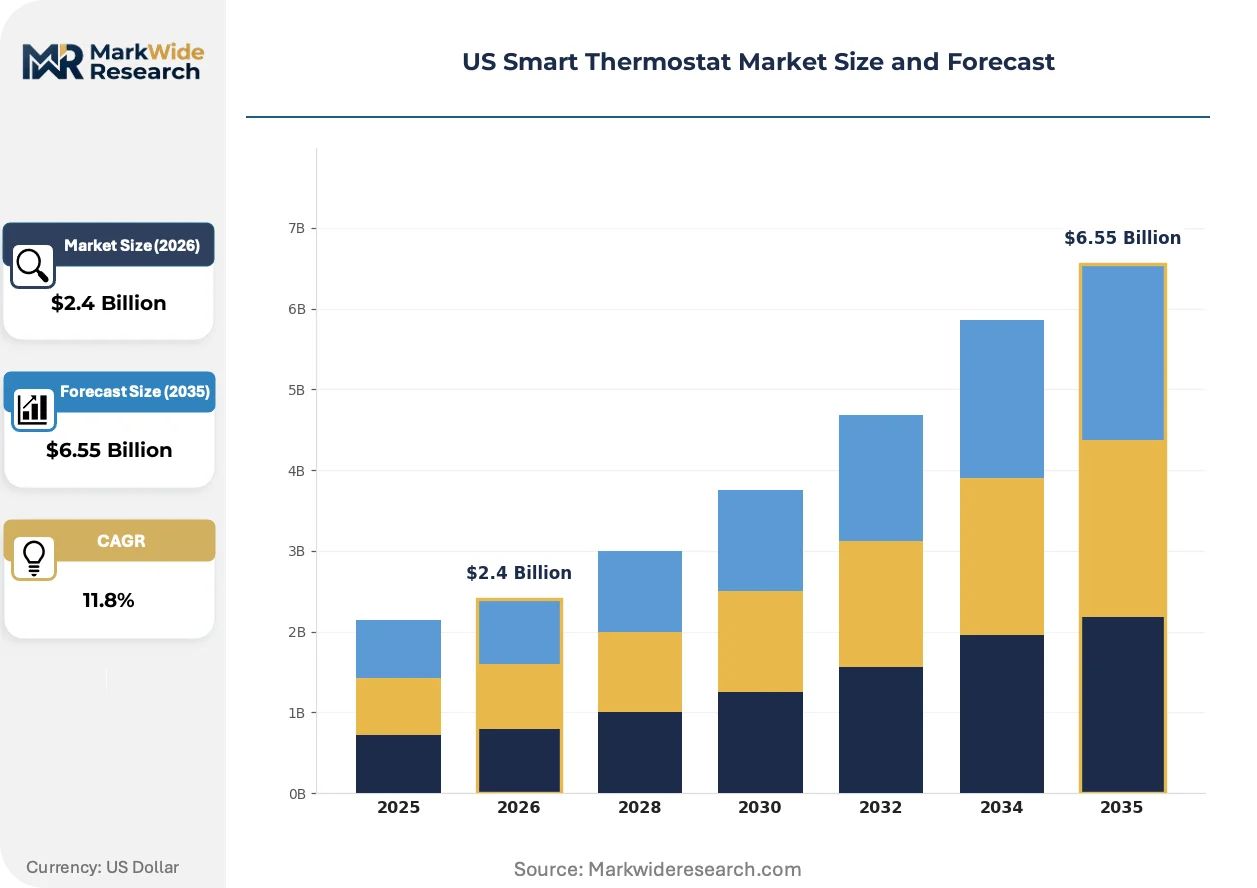
Market Dynamics
Silicon carbide power semiconductors are compressing hardware cost curves while FERC Order 2222 reclassifies thermostat fleets as grid assets, forcing manufacturers to rebuild cloud architectures for wholesale electricity market participation rather than simple demand-response signaling.
Growth Catalysts
- California Title 24 mandates:New construction must install smart thermostat-compatible systems, creating guaranteed replacement-cycle access in the nation's largest housing market.
- Utility rebate programs:State-level public utility commissions in Texas and California structure time-of-use tariffs that reshape homeowner economics toward automated setback adoption.
- Silicon carbide semiconductors:This material decouples thermostat hardware costs from traditional silicon price curves, enabling sensor and processing density upgrades in mid-tier price bands.
Market Restraints
- Legacy furnace control board incompatibility:Aging US housing stock requires professional compatibility verification, preventing widespread DIY adoption and inflating total cost of ownership.
- EPA ENERGY STAR certification thresholds:These constrain hardware design flexibility while creating compliance moats that slow unbranded import penetration.
- Contractor channel concentration:HVAC installer relationships control replacement-cycle access, locking out direct-to-consumer distribution models in the retrofit segment.
Strategic Opportunities
- FERC Order 2222 aggregation:Wholesale electricity market participation rights enable thermostat fleets to monetize grid services beyond traditional demand-response programs.
- Northern climate utility partnerships:Cold-climate engineering capabilities unlock utility channel dominance in states with aggressive electrification mandates and extreme weather exposure.
- Building automation software convergence:Commercial-grade protocol interoperability competes on technical credibility rather than consumer aesthetics in multi-family and light commercial installations.
Industry Challenges
- DOE appliance efficiency standard compliance:Certification timelines and testing protocols delay product launches and compress development cycles for hardware iterations.
- Cloud backend re-architecture:Grid-interactive functionality requires real-time wholesale market integration, forcing capital-intensive platform rebuilds for established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Thermostat Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Thermostats, Smart Programmable Thermostats, Learning Thermostats, Multizone Thermostats Feature: Energy Monitoring, Remote Control, Voice Control, Home Automation Integration Installation: DIY Installation, Professional Installation, Retrofit Installation, New Construction End User: Residential Users, Commercial Establishments, HVAC Professionals, Building Managers |
| Companies Covered | Emerson Sensi, Vivint, Nest, Johnson Controls, Bosch, Ecobee, Lennox iComfort, Mysa, Honeywell Home, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Thermostat Market Emerging Trajectories
Three forces are actively restructuring competitive positioning: semiconductor material transitions, regulatory reclassification of distributed energy resources, and contractor channel entrenchment in residential HVAC replacement cycles.
Silicon carbide power electronics are consolidating thermostat hardware value propositions by enabling simultaneous reductions in thermal management mass and increases in sensor channel density. Residential buyers in California and Texas receive utility-subsidized units that pack commercial-grade processing capability into mid-tier price bands. This material transition is consolidating competitive differentiation around sensing precision rather than connectivity features.
FERC Order 2222 redefines networked thermostats as wholesale market participants rather than passive demand-response endpoints. The regulation forces manufacturers to architect bidirectional cloud backends capable of real-time price signal ingestion and automated load modulation. Grid-interactive functionality requirements are concentrating R&D investment among firms with existing building automation software stacks.
Contractor-installed replacement cycles dominate demand formation as aging furnace control boards resist DIY compatibility verification. Homeowners in the Northeast and Midwest rely on HVAC technician assessments before purchase, preserving professional installation as the primary channel. This channel structure privileges manufacturers with backward integration into legacy control infrastructure and technician training networks over direct-to-consumer entrants.
US Smart Thermostat Market Segmentation
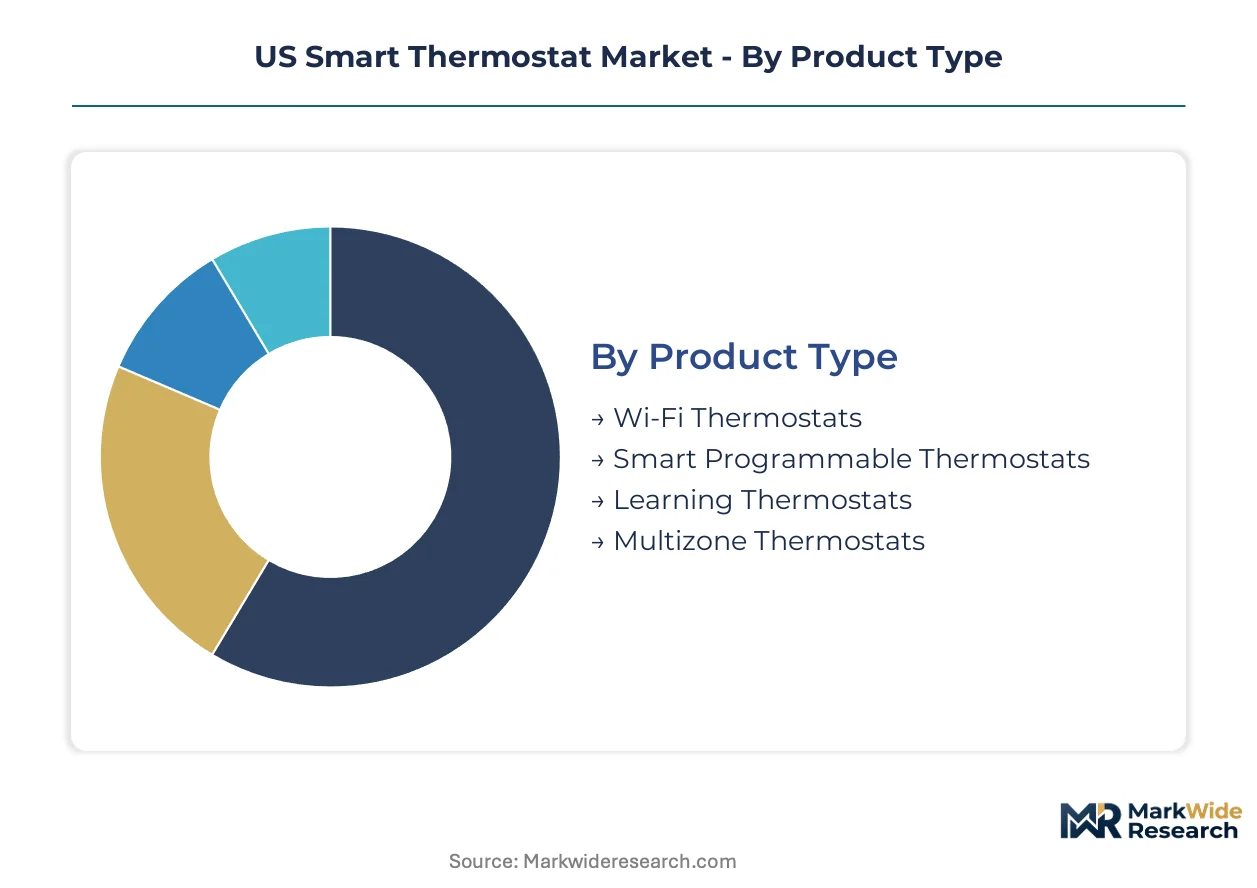
Segmentation reveals how hardware capabilities, installation economics, and user sophistication intersect to determine channel strategy and pricing power. Product architecture choices cascade through feature bundling, installation complexity, and end-user procurement patterns.
Product Type:
Integration depth varies sharply: standalone wall-mounted units dominate residential retrofits while embedded systems with multi-protocol backplanes penetrate commercial building automation stacks.
- Wi-Fi Thermostats:Cloud-connected units using standard 802.11 protocols for smartphone control without proprietary hubs. Demand concentrates in Texas and California single-family housing where utility rebate programs subsidize mass-market deployment.
- Learning Thermostats:Algorithm-driven devices with occupancy prediction and automated setback scheduling. California Title 24 mandates and FERC Order 2222 aggregation requirements drive adoption among grid-interactive utility programs.
- Smart Programmable Thermostats:Schedule-based units with app connectivity but without machine learning inference.
- Multizone Thermostats:Central controllers managing multiple HVAC zones through damper or valve actuation.
Wi-Fi Thermostats lead volumes today; Learning Thermostats are gaining share fastest.
Feature:
Feature bundling stratifies across cost tiers, with premium configurations commanding contractor channel premiums and economy bundles targeting retail self-installation.
- Home Automation Integration:Multi-protocol connectivity spanning Zigbee, Z-Wave, and Matter standards for whole-home orchestration. Northeast and Midwest residential markets show concentration where aging furnace infrastructure demands professional compatibility verification.
- Remote Control:Smartphone and web-based interfaces enabling off-premise temperature adjustment. Texas and California dominate adoption due to time-of-use tariff structures from state public utility commissions.
- Energy Monitoring:Real-time consumption tracking with utility bill integration.
- Voice Control:Native or bridge-connected speech interfaces for hands-free operation.
Remote Control leads volumes today; Home Automation Integration is expanding most quickly.
Installation:
Installation modality determines margin structure and customer acquisition cost, with professional channels capturing replacement-cycle economics and DIY routes fighting for new construction access.
- Professional Installation:HVAC contractor deployment with compatibility verification and warranty registration. Demand concentrates across the aging US housing stock where legacy furnace control boards resist amateur wiring.
- Retrofit Installation:Replacement of existing thermostats without HVAC equipment modification. California and Texas show geographic concentration as extreme weather accelerates replacement cycles.
- DIY Installation:Consumer self-deployment with manufacturer-provided wiring guides.
- New Construction:Builder-grade specification during initial HVAC system commissioning.
Professional Installation leads volumes today; Retrofit Installation is climbing the fastest.
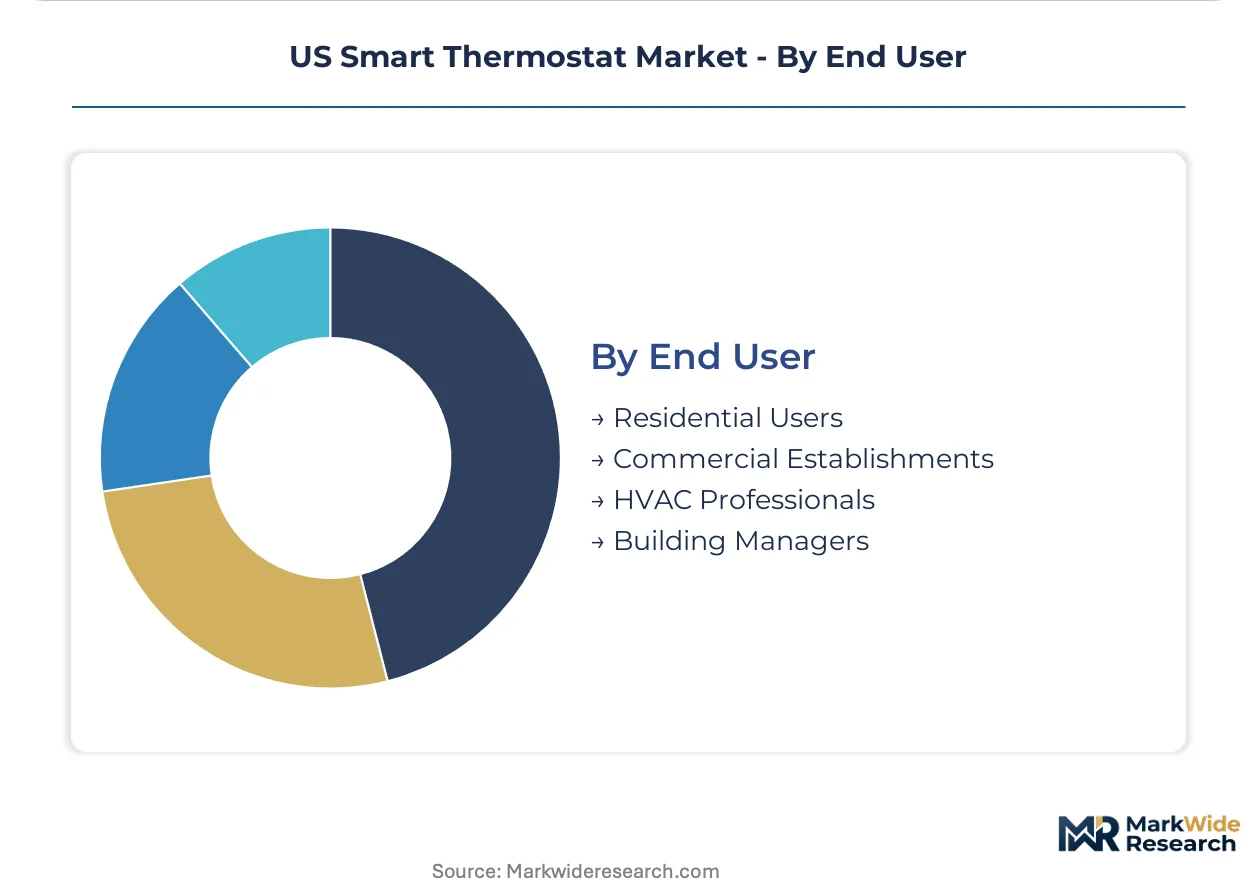
End User:
End-user segmentation maps procurement authority to technical sophistication, with facility managers demanding protocol interoperability and homeowners prioritizing installation simplicity.
- Residential Users:Single-family and multi-family occupants purchasing through retail or utility channels. California and Texas represent the fastest-expanding buyer segment as state energy offices advance building electrification mandates.
- HVAC Professionals:Contractor-specified procurement controlling replacement-cycle access across the aging US housing stock.
- Commercial Establishments:Small and mid-size businesses with standalone HVAC systems.
- Building Managers:Multi-tenant facility operators with centralized control requirements.
Residential Users lead volumes today; Building Managers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Silicon Valley and Los Angeles basin anchor national demand formation for grid-interactive climate control hardware. State energy offices across the Sun Belt are accelerating replacement cycles through electrification mandates and time-of-use tariff restructuring.
California
Extreme heat events and Title 24 building codes drive replacement velocity in single-family housing stock. The California Energy Commission mandates smart thermostat compatibility in all new construction permits issued after 2025. Los Angeles and San Diego metropolitan areas concentrate utility rebate program enrollment and contractor certification networks.
Texas
ERCOT grid instability and summer peak demand spikes reshape homeowner economics toward automated load modulation. The Public Utility Commission of Texas structures time-of-use tariffs that subsidize learning thermostat deployment through retail electric provider partnerships. Houston and Dallas-Fort Worth metroplexes host the densest HVAC contractor networks controlling retrofit channel access.
Florida
Hurricane-driven grid resilience investments and humidity control requirements concentrate demand in coastal counties. The Florida Public Service Commission oversees utility demand-response pilots that enroll networked thermostats in emergency load curtailment programs. Miami-Dade and Tampa Bay regions exhibit the highest penetration of multizone systems in multi-family housing stock.
New York
Aggressive building electrification mandates from the Climate Leadership and Community Protection Act reshape replacement economics in aging housing infrastructure. The New York State Energy Research and Development Authority channels rebate funding toward cold-climate heat pump compatibility verification. New York City and Long Island sub-markets prioritize professional installation due to legacy steam and hydronic system complexity.
Illinois
ComEd grid modernization investments and winter peak demand management programs accelerate smart meter-thermostat integration. The Illinois Commerce Commission approves rider structures that compensate aggregated thermostat fleets for frequency regulation services. Chicago metropolitan area contractors dominate the Midwest replacement cycle through legacy furnace control board compatibility expertise.
US Smart Thermostat Market Vendor Landscape
Backward integration into legacy control infrastructure dominates the current landscape as manufacturers defend replacement-cycle access. The vendor base concentrates around three strategic archetypes: heritage HVAC conglomerates with contractor training networks, utility-channel specialists with cold-climate engineering credentials, and building automation software providers extending into residential formats. M&A activity targets cloud backend capabilities for FERC Order 2222 compliance, while strategic partnerships with state public utility commissions lock in rebate program eligibility.
Within the heritage HVAC tier, Honeywell Home and Johnson Controls exemplify manufacturers leveraging backward integration into legacy furnace control infrastructure and technician certification networks. Ecobee occupies a distinct position as a utility-channel specialist with Canadian-origin cold-climate engineering heritage. Nest represents the platform-native archetype with consumer electronics distribution DNA.
| Leading Market Players |
|---|
| Emerson Sensi |
| Vivint |
| Nest |
| Johnson Controls |
| Bosch |
| Ecobee |
| Lennox iComfort |
| Mysa |
| Honeywell Home |
| Others |
Supply Flow & Price Mechanics
California Title 24 mandates for smart thermostat compatibility in new construction are compressing price bands as manufacturers race to deliver certified units at utility-subsidized price points. This demand-side specification tightening forces supply chain reconfiguration around EPA ENERGY STAR certification tiers, with silicon carbide semiconductor transitions enabling mid-tier feature density without margin erosion.
Pricing Analysis
Silicon carbide power semiconductor cost curves determine input-cost pass-through into thermostat hardware tiers. Three-tier pricing structure across premium, standard, and economy levels separates learning algorithms with FERC Order 2222 grid-interactive backends from basic Wi-Fi connectivity units. Cost compression in standard tiers intensifies because silicon carbide decouples processing capability from legacy silicon price trajectories. Residential utility rebate recipients show lowest price sensitivity; DIY retail buyers exhibit highest.
Supply Chain Analysis
EPA ENERGY STAR certification and DOE appliance efficiency standards gate supplier qualification, concentrating component sourcing among Taiwan, South Korea, and USA semiconductor fabricators. Raw material dependencies center on silicon carbide substrates, copper relay assemblies, and humidity sensor membranes. Single-source vulnerability runs through Taiwan-based power semiconductor foundries. Distribution runs through HVAC contractor networks controlling replacement-cycle access rather than direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Smart Thermostat Market represents a late-cycle quality story where FERC Order 2222 grid-interactive specifications are displacing basic connectivity as the baseline procurement requirement. Premium algorithmic setback precision and wholesale market participation capability now define minimum viable product positioning.
For Market Incumbents: Deploy backward integration into legacy furnace control board compatibility databases to lock contractor channel access against direct-to-consumer entrants. Acquire cloud backend engineering teams capable of real-time wholesale price signal ingestion to satisfy FERC Order 2222 aggregation requirements. Channel control through HVAC technician training networks remains the priority defensive lever as DIY installation faces structural barriers from aging housing stock wiring complexity. For New Entrants and Emerging Players: Enter via cold-climate utility partnership channels in northern states where Ecobee's Canadian-origin engineering heritage has created specification templates for extreme weather performance. Target multi-family building manager segments with protocol interoperability demands that heritage HVAC conglomerates underserve. White-space concentration sits in commercial-grade software stacks extended to smaller-format residential controllers. For Investors and Strategic Acquirers: Asymmetric upside sits with building automation software providers possessing existing protocol interoperability stacks that can absorb FERC Order 2222 cloud re-architecture costs. Long-term viability favors firms with captive utility commission relationships securing rebate program eligibility. The signal to watch is state-level public utility commission adoption of California Title 24 template codes across Sun Belt jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Backend Re-architecture | FERC Order 2222 compliance requires real-time wholesale market bidirectional integration capabilities. |
| Silicon Carbide Semiconductor Transition | Power electronics material shift enables sensor density upgrades without thermal management mass penalties. |
| Utility Partnership Lock-in | State PUC rebate program eligibility creates procurement channel moats against unbranded import competition. |
| Contractor Training Network Expansion | HVAC installer certification programs control replacement-cycle access in aging single-family housing stock. |
| Cold-Climate Engineering Certification | Extreme weather performance validation unlocks northern state electrification mandate compliance premiums. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC contractor network managers, utility demand-response program administrators, state energy office electrification leads, and smart thermostat product engineers with secondary validation against FERC Order 2222 docket filings, EPA ENERGY STAR certification databases, and state public utility commission tariff rulings. Bottom-up unit shipment modeling and top-down market value reconciliation anchored triangulation across the analysis window.
Comparable historical periods spanning pre- and post-FERC Order 2222 implementation anchored forecast calibration across the projection horizon. Segmentation dimensions modeled include product architecture tier, installation modality, end-user procurement authority, and regional regulatory framework cluster. CAGRs derived from algorithmic setback adoption curves and utility rebate program enrollment trajectories. Forecast inputs incorporated silicon carbide semiconductor price elasticity and contractor channel capacity constraints.
Inputs from EPA certification databases and state PUC docket filings were available through the study window; gaps in real-time wholesale market participation revenue data introduce uncertainty bands around grid-interactive functionality monetization assumptions. Forecasts reflect documented scenario assumptions regarding Title 24 code adoption velocity across additional states. A model refresh is warranted upon material change in FERC distributed energy resource aggregation rulemakings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
Aviation IoT Solutions Market