
 Global IoT Devices Market | 2026-2036
Global IoT Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Devices Market Outlook
Semiconductor fabrication capacity in Taiwan is realigning global IoT module availability. Cisco Systems leverages its edge networking portfolio to anchor enterprise IoT deployments across manufacturing floors. Huawei Technologies competes through integrated chipset-to-cloud architectures that sustain its position in smart city infrastructure.
IoT devices are physical objects embedded with sensors, processors, and network connectivity enabling data exchange without human intervention, typically operating on sub-1 GHz to 5 GHz frequency bands with power consumption thresholds measured in milliwatts for battery-constrained deployments. Their primary purpose spans real-time monitoring, predictive maintenance, and autonomous control across industrial and consumer environments. Industrial Equipment dominates manufacturing value capture due to high unit costs and long replacement cycles, while Smart Home Devices represent the fastest-expanding volume pool as Wi-Fi and Zigbee module costs decline. Cellular connectivity commands premium positioning in asset tracking applications where wide-area coverage overrides power constraints.
FCC spectrum allocations in the United States, CE marking requirements under the EU Radio Equipment Directive, and China's GB standards enforced by MIIT collectively shape device certification timelines and market access pathways. The EU AI Act introduces additional conformity layers for autonomous decision-making in connected health and industrial systems. Stakeholders must monitor harmonization gaps between regional cybersecurity mandates before committing to platform architectures.
Market Dynamics
Semiconductor fabrication concentration in Taiwan is compressing module availability timelines while healthcare providers accelerate remote patient monitoring deployments under tightening algorithmic transparency mandates.
Growth Catalysts
- EU AI Act compliance layers:Connected medical device manufacturers face expanded conformity requirements for autonomous decision-making systems, creating certified product premiums in diagnostic and therapeutic applications.
- Germany's industrial automation corridor:Munich and Stuttgart manufacturing clusters concentrate demand for predictive maintenance sensors and edge analytics hardware across automotive and precision engineering supply chains.
- Sub-1 GHz spectrum allocation:FCC and CE marking harmonization around unlicensed low-power wide-area protocols reduces module certification friction for battery-constrained agricultural and utility metering deployments.
Market Restraints
- Advanced node foundry concentration:Taiwan-based semiconductor fabrication accounts for disproportionate share of IoT-optimized process technologies, exposing module supply to geographic concentration risk.
- Cellular certification cost structure:PTCRB and GCF testing requirements for LTE-M and NB-IoT modules impose fixed compliance burdens that disproportionately constrain low-volume specialty device entrants.
- Power-performance tradeoff ceiling:Milliwatt-scale consumption thresholds for battery-operated endpoints limit computational capability, forcing cloud dependency for complex inference workloads.
Strategic Opportunities
- India's smart metering mandate:Ministry of Power directives for advanced metering infrastructure create volume pull for RF modules and edge gateways across state distribution utilities.
- Digital twin convergence:Integration of physics-based simulation with real-time sensor streams enables asset-centric service models in rotating equipment and process manufacturing verticals.
- Healthcare procurement decentralization:Hospital system direct sourcing of connected diagnostic devices bypasses traditional distributor markups, rewarding manufacturers with captive certification and logistics capabilities.
Industry Challenges
- Embedded systems security engineering:Shortage of firmware developers with hardware-level cryptography and secure boot implementation expertise extends product development cycles.
- Multi-jurisdiction certification sequencing:FCC, CE marking, and MIIT GB standards require staggered testing protocols that compress launch windows for simultaneous multi-market releases.
- Legacy SCADA integration friction:Brownfield industrial sites operate proprietary protocol stacks that demand protocol translation gateways, adding hardware cost and failure point complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Devices Market |
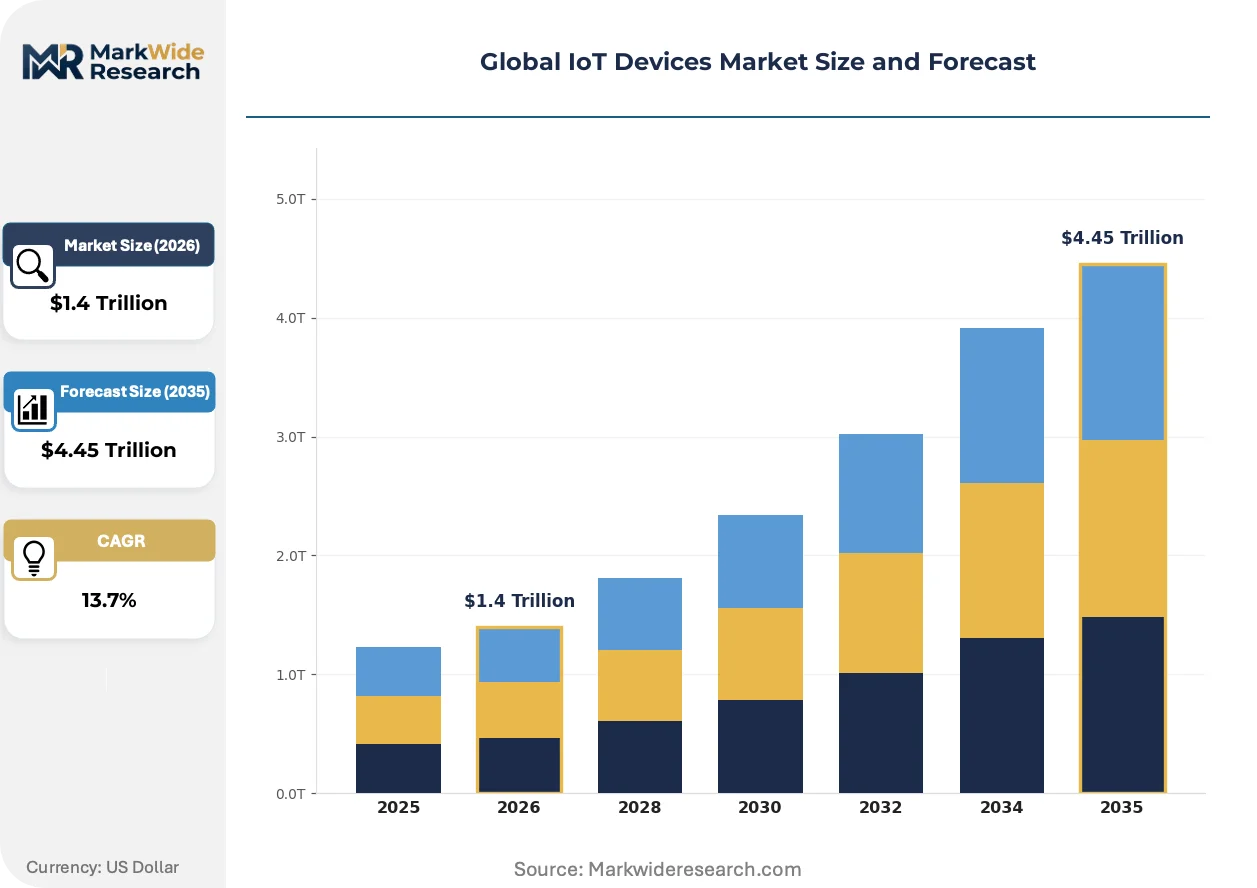
| Market Size in 2026 | $1.4 Trillion |
| Market Size in 2035 | $4.45 Trillion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Smart Appliances, Industrial Equipment, Smart Home Devices Technology: Bluetooth, Wi-Fi, Zigbee, Cellular End User: Healthcare Providers, Retailers, Manufacturers, Smart Cities Application: Asset Tracking, Home Automation, Health Monitoring, Industrial Automation |
| Companies Covered | Cisco Systems, Inc., Microsoft Corporation, Amazon Web Services, Inc., IBM Corporation, Huawei Technologies Co., Ltd., Intel Corporation, Qualcomm Technologies, Inc., Siemens AG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Devices Market Strategic Shifts
Edge-native processing architectures are compressing cloud dependency while regulatory fragmentation around algorithmic accountability reshapes product development roadmaps across health and industrial verticals.
Ultra-low-power microcontrollers with integrated neural accelerators are consolidating inference capability at the endpoint. Agricultural monitoring networks and wearable diagnostics manufacturers adopt these system-on-chip designs to reduce transmission frequency and extend battery service intervals. This silicon integration is consolidating module supplier tiers as discrete component vendors lose socket share to integrated platform providers.
EU AI Act risk classification tiers impose documentation and human oversight obligations on connected health devices with autonomous diagnostic functions. Manufacturers must maintain algorithmic change logs and performance monitoring systems that extend quality management systems beyond traditional hardware lifecycle controls. Germany and France healthcare procurement authorities now embed these conformity requirements into tender specifications, filtering supplier pools before technical evaluation.
Asset-as-a-service contracting is displacing capital equipment purchases in precision agriculture and commercial HVAC verticals. OEMs retain device ownership and bundle connectivity, maintenance, and performance guarantees into per-acre or per-square-meter subscriptions. This model concentrates in North American and Western European markets where balance sheet treatment of operational expenditures favors procurement officers managing capital allocation constraints.
Global IoT Devices Market Segmentation
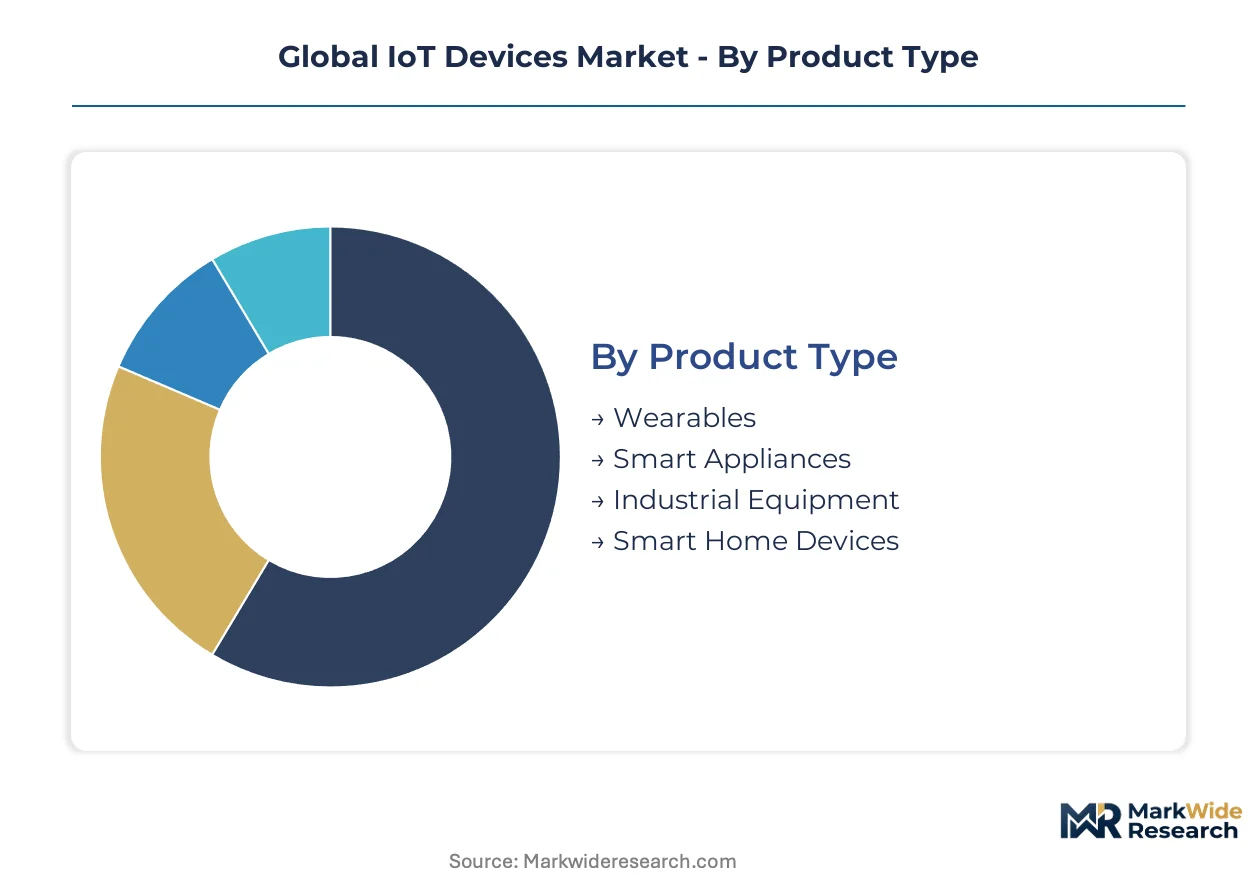
Segmentation in the Global IoT Devices Market reveals how connectivity specifications, power budgets, and regulatory environments create distinct competitive arenas. Technology choices determine certification pathways and margin structures, while end-user procurement patterns concentrate volume in vertically integrated supply chains.
Product Type:
Power consumption thresholds and replacement cycles differentiate hardware economics across device categories.
- Industrial Equipment:Ruggedized sensors and actuators operate on 10-15 year lifecycles with IP67+ ingress protection. German automotive suppliers in Munich and Stuttgart drive demand for vibration monitoring and predictive maintenance endpoints that integrate with Siemens and Bosch control systems. Long procurement cycles favor established vendors with captive certification expertise.
- Smart Home Devices:Wi-Fi and Zigbee modules at sub-dollar price points enable mass-market penetration of thermostats, lighting controls, and security cameras. US and European consumers upgrade these devices every 3-5 years, creating recurring revenue pools for platform ecosystems.
- Wearables:Fitness bands and medical-grade patches demand milliwatt-scale power budgets with BLE 5.0+ connectivity. FDA and EU MDR compliance requirements separate consumer wellness from regulated diagnostic applications.
- Smart Appliances:Refrigerators, washing machines, and HVAC systems integrate edge processors for local inference. Korean and Japanese manufacturers lead in appliance-to-grid communication protocols.
Mature deployment sits with Industrial Equipment. Newer deployment is concentrated in Smart Home Devices.
Technology:
Spectrum allocation and certification cost structures shape module selection across geographic markets.
- Cellular:LTE-M and NB-IoT modules provide wide-area coverage for asset tracking and agricultural monitoring. PTCRB and GCF testing impose fixed costs that disadvantage low-volume entrants, concentrating supply among Qualcomm and MediaTek platform licensees.
- Wi-Fi:802.11ax/6E standards enable high-throughput video streaming and cloud-dependent inference. Smart home and enterprise access point vendors drive silicon integration toward single-chip solutions.
- Bluetooth:BLE 5.3 with direction-finding supports indoor positioning and proximity-based access control. Nordic Semiconductor and Silicon Labs dominate the low-power controller segment.
- Zigbee:Mesh networking protocols sustain smart lighting and building automation deployments. Matter standard convergence is compressing Zigbee-only module demand in consumer applications.
Volume leadership belongs to Wi-Fi. Steepest expansion trajectory is occurring in Cellular as NB-IoT coverage extends across India and Southeast Asia.
End User:
Procurement centralization and technical specification authority determine vendor access and pricing power.
- Healthcare Providers:Hospital systems and integrated delivery networks source connected diagnostic devices directly, bypassing distributor markups. EU AI Act documentation requirements filter supplier pools before technical evaluation.
- Manufacturers:Automotive and precision engineering clusters in Germany concentrate demand for predictive maintenance sensors. Edge analytics hardware procurement favors vendors with local application engineering support.
- Smart Cities:Municipal infrastructure departments deploy environmental monitors, traffic sensors, and public safety endpoints. Chinese GB standards and EU cybersecurity mandates create divergent certification requirements.
- Retailers:Supply chain visibility and cold-chain monitoring drive RFID and cellular tracker adoption. US and European grocery chains lead in automated inventory management deployments.
Procurement sophistication peaks with Healthcare Providers. Fastest volume gains are occurring in Smart Cities as Indian and Middle Eastern municipalities accelerate infrastructure digitization.
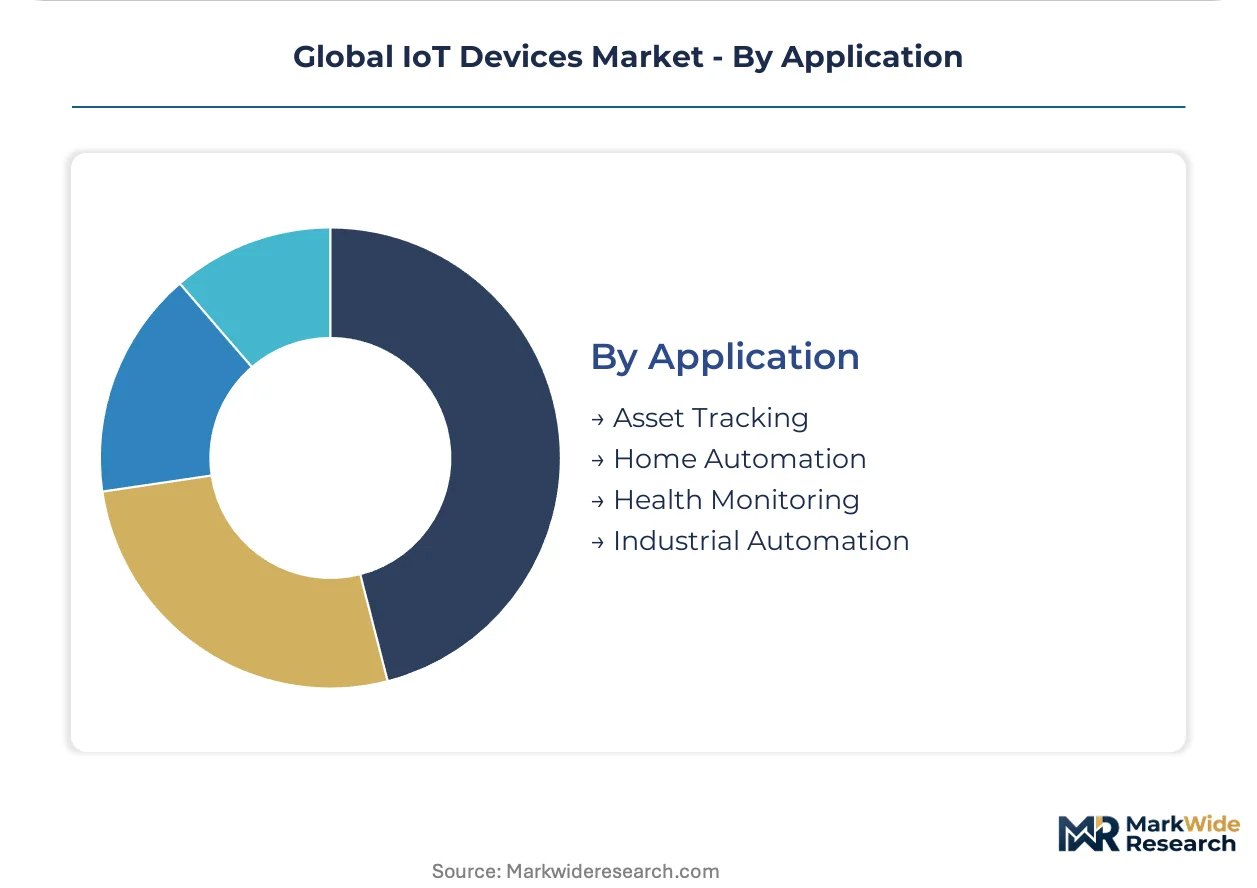
Application:
Use-case complexity and data sovereignty requirements determine edge versus cloud processing architectures.
- Industrial Automation:Real-time control loops demand sub-10 millisecond latency, favoring edge-native processing over cloud dependency. Brownfield SCADA integration creates protocol translation gateway demand.
- Health Monitoring:Remote patient monitoring deployments expand under Medicare reimbursement expansion in the US and NHS long-term plan targets in the UK. Algorithmic transparency mandates reshape product development roadmaps.
- Asset Tracking:Fleet management and logistics visibility solutions leverage cellular and satellite hybrid connectivity. Battery life optimization drives silicon selection toward ultra-low-power microcontrollers.
- Home Automation:Voice control and occupancy-based climate management concentrate consumer expenditure in North America and Western Europe. Platform interoperability wars between Amazon, Google, and Apple reshape module specifications.
Deployment maturity clusters in Industrial Automation. Gaining share fastest is Health Monitoring as reimbursement codes align with connected diagnostic value propositions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese semiconductor foundries supply the silicon substrate powering IoT module proliferation worldwide. Geographic concentration of advanced node fabrication creates supply vulnerability that shapes procurement strategies across end markets.
United States
Medicare reimbursement expansion for remote patient monitoring drives healthcare IoT procurement. FDA algorithmic transparency guidance aligns with emerging EU AI Act documentation standards. Silicon Valley and Austin technology clusters concentrate edge AI chip design activity.
Germany
Automotive and precision engineering suppliers demand predictive maintenance sensors with 10-15 year lifecycles. CE marking under EU Radio Equipment Directive governs module certification timelines. Munich and Stuttgart industrial automation corridors anchor European demand for ruggedized industrial endpoints.
China
Smart city infrastructure deployments accelerate environmental monitoring and public safety endpoint installation. MIIT enforces GB standards for radio equipment and cybersecurity compliance. Yangtze River Delta manufacturing bases produce cost-optimized modules for domestic and export markets.
India
Ministry of Power smart metering mandates create volume demand for RF modules and edge gateways. BIS certification requirements shape product qualification pathways. State distribution utilities in Maharashtra and Gujarat lead advanced metering infrastructure procurement.
Japan
Appliance-to-grid communication protocols drive smart home device integration with energy management systems. METI standards govern IoT security and interoperability frameworks. Kanto region electronics manufacturers consolidate edge processor design for HVAC and appliance applications.
Global IoT Devices Market Competitive Environment
Global majors compete with regional champions across cloud-to-edge integration capabilities. Market structure tilts toward consolidated platform providers with captive certification expertise, though specialized module vendors retain pockets of differentiation. Three archetypes dominate: cloud-native platform operators, silicon-to-systems integrators, and industrial automation incumbents. Competitive moves center on strategic partnerships for protocol interoperability and backward integration into semiconductor supply.
Within the cloud-native tier, Amazon Web Services and Microsoft Corporation exemplify platform-centric positioning that bundles connectivity management with analytics infrastructure. Cisco Systems and Huawei Technologies occupy positions spanning networking hardware through edge software stacks. Siemens AG anchors the industrial automation archetype with captive certification capabilities and localized application engineering support across European manufacturing clusters.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Huawei Technologies Co., Ltd. |
| Intel Corporation |
| Qualcomm Technologies, Inc. |
| Siemens AG |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between CE-marked industrial endpoints and unlicensed consumer modules manifests in both unit economics and sourcing configurations. Premium-tier hardware commands three-to-five-year service bundles that embed firmware update commitments, while commodity Wi-Fi sensors ship bare-metal with minimal after-sales attachment.
Pricing Analysis
Warranty and firmware-update bundling separates industrial-grade pricing from consumer-tier transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FCC Part 15 Class B and CE marking compliance adding fixed testing overhead that low-volume entrants cannot amortize. Cost compression in cellular modules is intensifying because Qualcomm and MediaTek platform consolidation reduces merchant silicon alternatives. Healthcare procurement committees exhibit lowest price sensitivity due to reimbursement code alignment, while agricultural monitoring deployments in India prioritize unit cost above protocol sophistication.
Supply Chain Analysis
Advanced-node wafer supply rests on Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation foundry capacity, with South Korea's Samsung Foundry providing secondary sourcing for legacy nodes. RF front-end components draw from Murata and Skyworks fabrication, while substrate materials hinge on Japanese specialty laminate producers. Single-source vulnerability concentrates in 12-inch wafer supply for neural-accelerator integration. Distribution runs through Arrow Electronics and Avnet for enterprise volumes, with direct OEM relationships dominating automotive and healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwanese foundry capacity constraints prop module pricing across all tiers, creating supply-constrained conditions that favor incumbents with allocated wafer starts.
For Market Incumbents: Extend certification-captive positioning by embedding EU AI Act documentation capabilities into quality management systems before tender specifications harden. Acquire edge-AI chip design teams in Austin or Silicon Valley to reduce merchant silicon dependency. Threat substitution from integrated system-on-chip platforms demands upstream control over neural accelerator IP. For New Entrants and Emerging Players: Capture India's state-level smart metering procurement through BIS pre-certification and localized RF module assembly partnerships. White-space concentration sits with agricultural LPWAN endpoints where unlicensed spectrum protocols reduce PTCRB testing burdens. Go-to-market leverage runs through state distribution utility engineering departments rather than national tender portals. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays where cloud-native operators seek edge hardware capabilities. Five-to-ten-year viability favors vendors with captive certification expertise and multi-jurisdiction compliance track records. Acquisition target archetype: industrial automation specialists with Siemens or Bosch integration credentials. Signal to watch: harmonization between FCC spectrum allocations and EU Radio Equipment Directive timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Integration | Documentation capabilities filter supplier pools before German hospital tender evaluation. |
| Edge-Native Neural Accelerator Development | Silicon integration reduces cloud dependency for wearable diagnostic inference workloads. |
| India Smart Metering Partnership | Maharashtra and Gujarat utility mandates create volume pull for RF module suppliers. |
| Matter Protocol Certification | Interoperability standard compresses Zigbee-only module demand in North American smart home deployments. |
| Taiwan Foundry Capacity Reservation | Allocated wafer starts secure supply continuity for LTE-M and NB-IoT module production. |
Study Parameters
SEC 10-K filings, EU Medical Device Regulation submission databases, and hyperscaler IoT platform capex disclosures formed the secondary backbone for volume and value estimation. Primary interviews with hospital biomedical engineers, automotive Tier 1 procurement managers, and state utility smart metering directors validated deployment timelines and specification priorities. Bottom-up module shipment data triangulated against top-down connectivity subscription revenues across the analysis window.
Bottom-up modeling aggregated unit economics across product type, technology protocol, and end-user vertical, while top-down validation referenced semiconductor foundry capacity allocations and cellular carrier IoT connection disclosures. Segmentation dimensions spanned connectivity specification, power budget tier, and regional regulatory cluster. CAGRs derived from slope-log regression of annualized shipment values, with India smart metering mandates and Medicare reimbursement code expansions serving as demand-side inflection inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry capacity reallocation and EU AI Act enforcement harmonization across member states. Assumptions reflect current spectrum allocation timelines and certification protocol stability. Taiwan seismic risk, FCC unlicensed band reallocation, and India BIS testing backlog warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market