
 Connected IoT Devices Market | 2026-2036
Connected IoT Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Connected IoT Devices Market Analysis
Healthcare is consolidating as the fastest-growing end-use vertical for connected IoT devices, displacing pure consumer electronics in vendor priority. Siemens AG anchors European industrial IoT through its MindSphere platform and manufacturing automation depth. Qualcomm Technologies differentiates through cellular modem leadership in low-power wide-area chipsets for medical and agricultural endpoints. Huawei Technologies competes aggressively on 5G-enabled industrial sensor bundles despite Western market access restrictions.
Connected IoT devices encompass networked physical objects embedded with sensors, actuators, and communication modules that transmit data over internet protocol stacks, typically operating on power budgets below one watt for battery-constrained deployments. Their primary purpose spans real-time telemetry, automated control loops, and predictive analytics across commercial and industrial operations. Industrial Sensors command the deepest margin pools due to ruggedization requirements and long replacement cycles in manufacturing environments. Edge Computing deployment is expanding fastest as latency-sensitive healthcare and automotive applications reject cloud-only architectures. Smart Home Devices represent the most mature revenue segment, with Wi-Fi and Zigbee connectivity now standardized across premium and mass-market tiers.
The FCC governs radio spectrum allocation and device certification for IoT hardware in the United States, while the EU AI Act imposes conformity assessments on connected devices employing machine learning for autonomous decision-making. China's MIIT enforces GB standards for domestic IoT cybersecurity, creating divergent compliance burdens for multinational vendors. Stakeholders must monitor regulatory fragmentation across spectrum policy, data localization mandates, and algorithmic accountability frameworks to preserve cross-border product architectures.
Market Dynamics
The EU AI Act is forcing algorithmic transparency mandates onto connected medical devices, while healthcare providers accelerate remote patient monitoring deployments. This regulatory-demand convergence is restructuring vendor R&D priorities and compliance architectures across the value chain.
Growth Catalysts
- Remote Patient Monitoring:Healthcare providers are deploying continuous telemetry systems for chronic disease management, creating sustained hardware demand for low-power sensors.
- EU AI Act Conformity Pathways:The regulation's risk-classification framework for machine-learning-enabled devices is accelerating certified product development cycles in European markets.
- Munich-Stuttgart Industrial Corridor:Germany's manufacturing automation density is generating concentrated demand for ruggedized industrial sensors and edge computing nodes.
Market Restraints
- Semiconductor Supply Concentration:Advanced node fabrication for low-power wide-area chipsets depends on a concentrated East Asian supplier base, creating vulnerability to trade policy disruptions.
- Battery Chemistry Cost Volatility:Lithium-ion cell prices for battery-constrained IoT endpoints fluctuate with raw material extraction constraints and refining capacity bottlenecks.
- Legacy Protocol Fragmentation:Persistent coexistence of Zigbee, Z-Wave, Thread, and proprietary mesh standards forces multi-radio hardware designs that inflate BOM costs.
Strategic Opportunities
- Agricultural Sensor Networks:Precision farming applications in water-stressed regions present underpenetrated demand for soil moisture and microclimate monitoring endpoints.
- Cellular LPWA Convergence:NB-IoT and LTE-M module integration is enabling single-SKU designs that serve both carrier-managed and private network deployments.
- India's PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and testing are attracting module manufacturers to establish domestic manufacturing footprints.
Industry Challenges
- Embedded Security Engineering Talent:Shortage of firmware developers with cryptographic implementation expertise delays secure boot and over-the-air update deployment timelines.
- Multi-Jurisdiction Certification Parallelism:Simultaneous FCC, CE marking, and MIIT GB standard compliance requires redundant testing protocols that extend product launch schedules.
- Interoperability Testing Burden:Fragmented smart home ecosystem certification programs force vendors to maintain multiple hardware variants for platform-specific compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected IoT Devices Market |
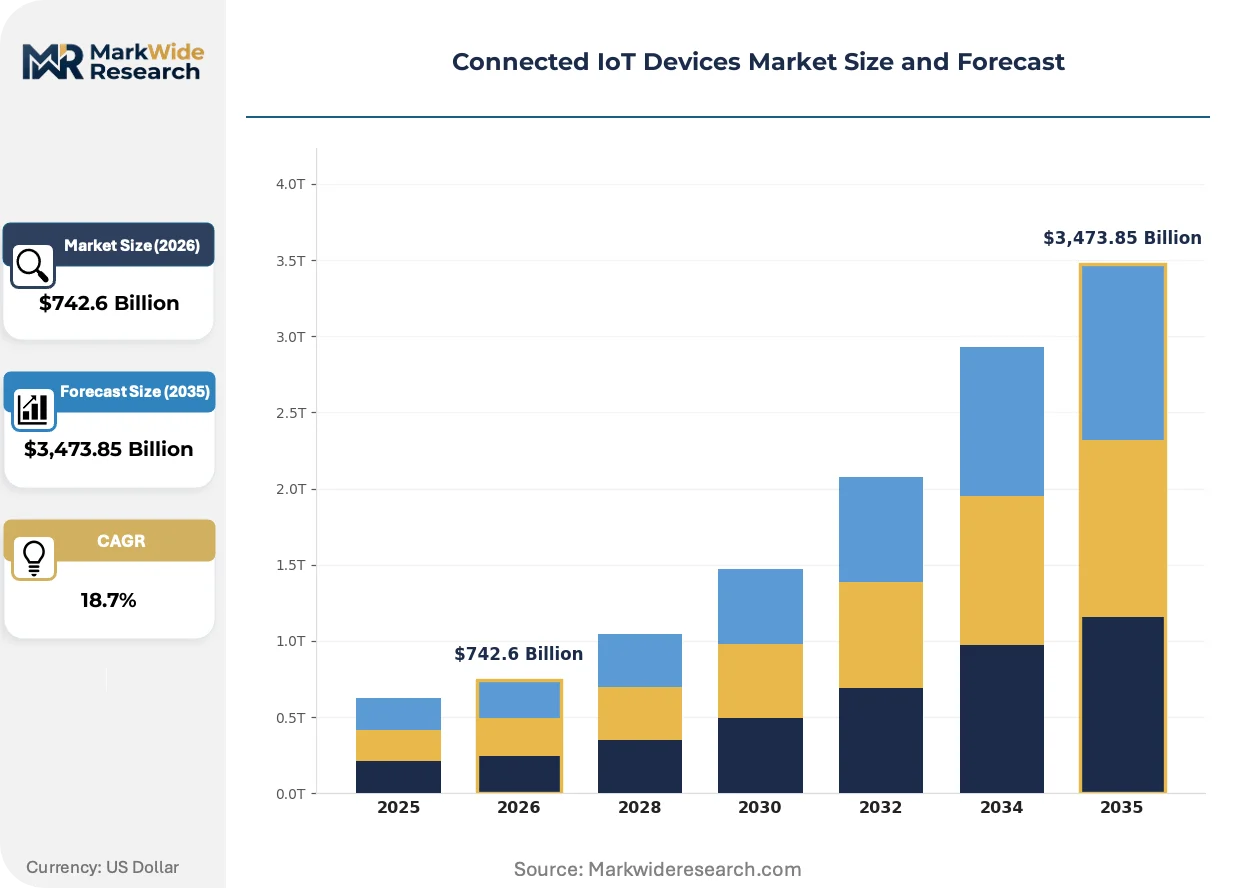
| Market Size in 2026 | $742.6 Billion |
| Market Size in 2035 | $3,473.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Smart Home Devices, Industrial Sensors, Smart Meters Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Connectivity Type: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Consumer, Healthcare, Manufacturing, Agriculture |
| Companies Covered | Amazon Web Services, Microsoft, Cisco Systems, IBM, Intel Corporation, Siemens AG, Huawei Technologies, Qualcomm Technologies, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected IoT Devices Market Emerging Trajectories
Edge-native processing architectures are overtaking cloud-dependent telemetry models as latency-sensitive applications reject round-trip data paths. This architectural pivot is compressing hardware specifications and reshaping vendor software stack investments.
On-device machine learning inference is overtaking cloud-only analytics for predictive maintenance and anomaly detection workloads. Manufacturing operators in Germany's industrial corridor are deploying tensor-optimized microcontrollers to eliminate network dependency for critical control loops. The shift is compressing acceptable latency thresholds below ten milliseconds and disqualifying legacy gateway-dependent architectures.
The EU AI Act's conformity assessment requirements for high-risk connected devices are mandating algorithmic documentation and human oversight interfaces. Medical device manufacturers must now maintain technical files demonstrating bias mitigation and decision traceability for autonomous diagnostic functions. European notified bodies are expanding audit capacity, while vendors accelerate hiring of regulatory affairs specialists with machine learning governance expertise.
Healthcare procurement is consolidating around integrated platform contracts that bundle hardware, connectivity, and analytics subscriptions. Hospital systems in the United States are displacing point-solution vendors with multi-year enterprise agreements covering remote patient monitoring infrastructure. This purchasing pattern concentrates vendor selection authority within supply chain and clinical informatics departments rather than individual department budgets.
Connected IoT Devices Market Segmentation
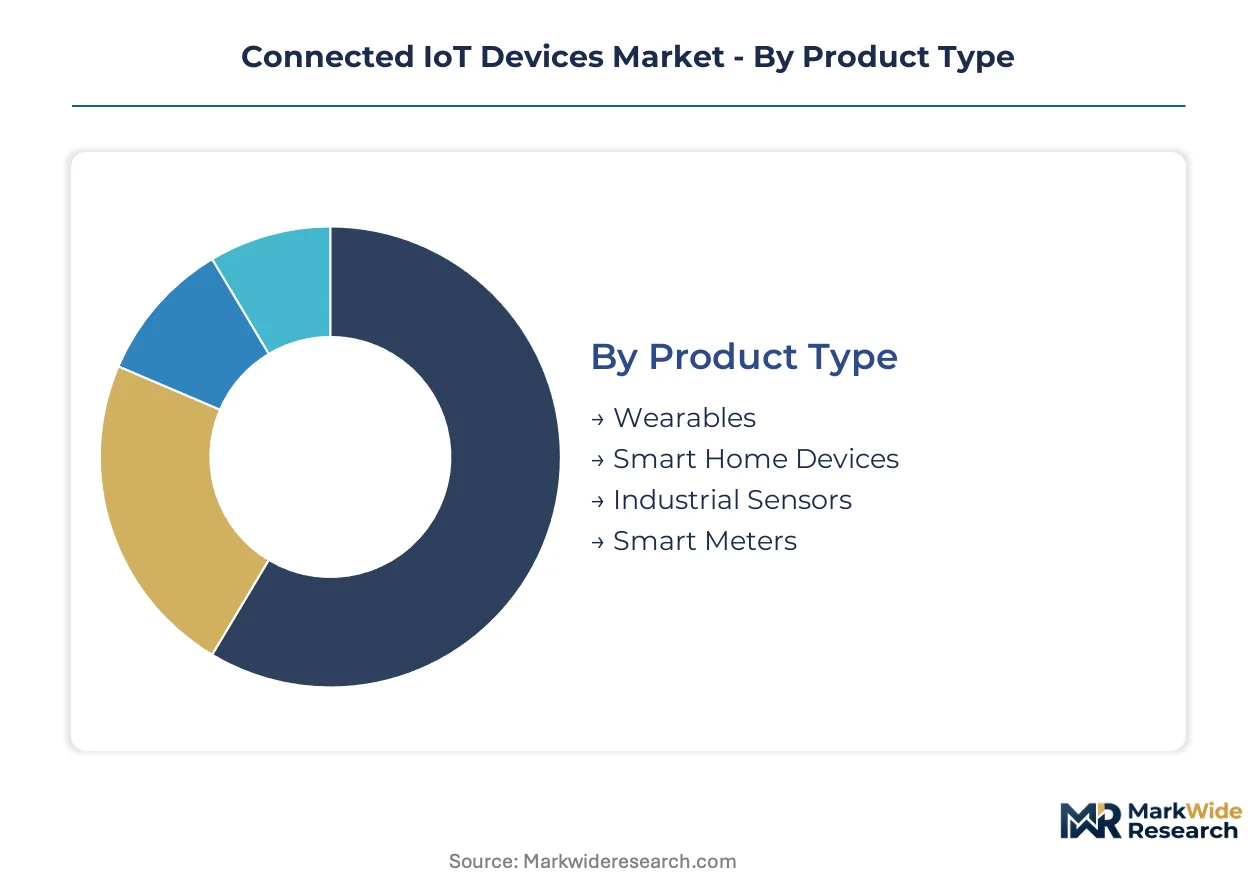
Segmentation in connected IoT devices reveals how hardware specifications, connectivity protocols, and deployment architectures align with distinct operational requirements across end-use environments. Each dimension carries upgrade-cycle implications that reshape vendor R&D roadmaps and procurement patterns.
Product Type:
Replacement cycles vary dramatically across product categories, with industrial assets demanding decade-long ruggedization against consumer electronics' compressed obsolescence windows.
- Industrial Sensors:Hardened enclosures with IP67+ ingress protection and extended temperature tolerances serve predictive maintenance workloads in manufacturing floors. Demand concentrates in Germany's Munich-Stuttgart corridor, where automotive and precision engineering operators require vibration-resistant telemetry for critical asset monitoring.
- Smart Home Devices:Wi-Fi and Zigbee-enabled thermostats, lighting controllers, and security cameras operate on 3-5 year replacement cycles driven by protocol evolution and feature expansion. North American and European households are consolidating around voice-integrated platforms, displacing standalone hardware with ecosystem-bound alternatives.
- Wearables:Continuous glucose monitors and cardiac telemetry patches for remote patient monitoring.
- Smart Meters:Utility-deployed electricity and gas measurement endpoints with decade-long certification requirements.
Industrial Sensors sit at the top of the volume ranking, with Smart Home Devices climbing the fastest.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from operational-expense cloud subscriptions, with hybrid architectures capturing mid-market procurement.
- Edge Computing:Tensor-optimized microcontrollers and gateway nodes process inference workloads locally, eliminating cloud round-trip latency for sub-10 millisecond control loops. Germany's manufacturing operators are deploying these architectures for autonomous anomaly detection, rejecting gateway-dependent topologies.
- Cloud-Based:Centralized data lakes and analytics platforms aggregate telemetry from distributed endpoints, with healthcare providers in the United States favoring subscription models that bundle storage, computation, and regulatory compliance.
- On-Premises:Air-gapped server infrastructure for defense and critical infrastructure operators with data sovereignty mandates.
- Hybrid:Split architectures that retain sensitive processing locally while pushing non-critical analytics to cloud tiers.
Cloud-Based deployment retains the largest installed base, though Edge Computing is gaining share fastest as latency requirements tighten.
Connectivity Type:
Application-specific bandwidth and power constraints dictate protocol selection, with cellular modules commanding premium positioning for wide-area deployments.
- Cellular:NB-IoT and LTE-M modules enable single-SKU designs spanning carrier-managed and private network deployments. Agricultural sensor networks in water-stressed regions are adopting these chipsets for soil moisture monitoring across expansive geographies.
- Wi-Fi:High-throughput connectivity for smart home and enterprise indoor environments with reliable power availability.
- Bluetooth:Low-energy personal area networking for wearables and proximity-based asset tracking.
- Zigbee:Mesh networking for home automation with sub-gigahertz penetration through building materials.
Wi-Fi maintains the broadest endpoint penetration, while Cellular is expanding most quickly in industrial and agricultural wide-area applications.
End User:
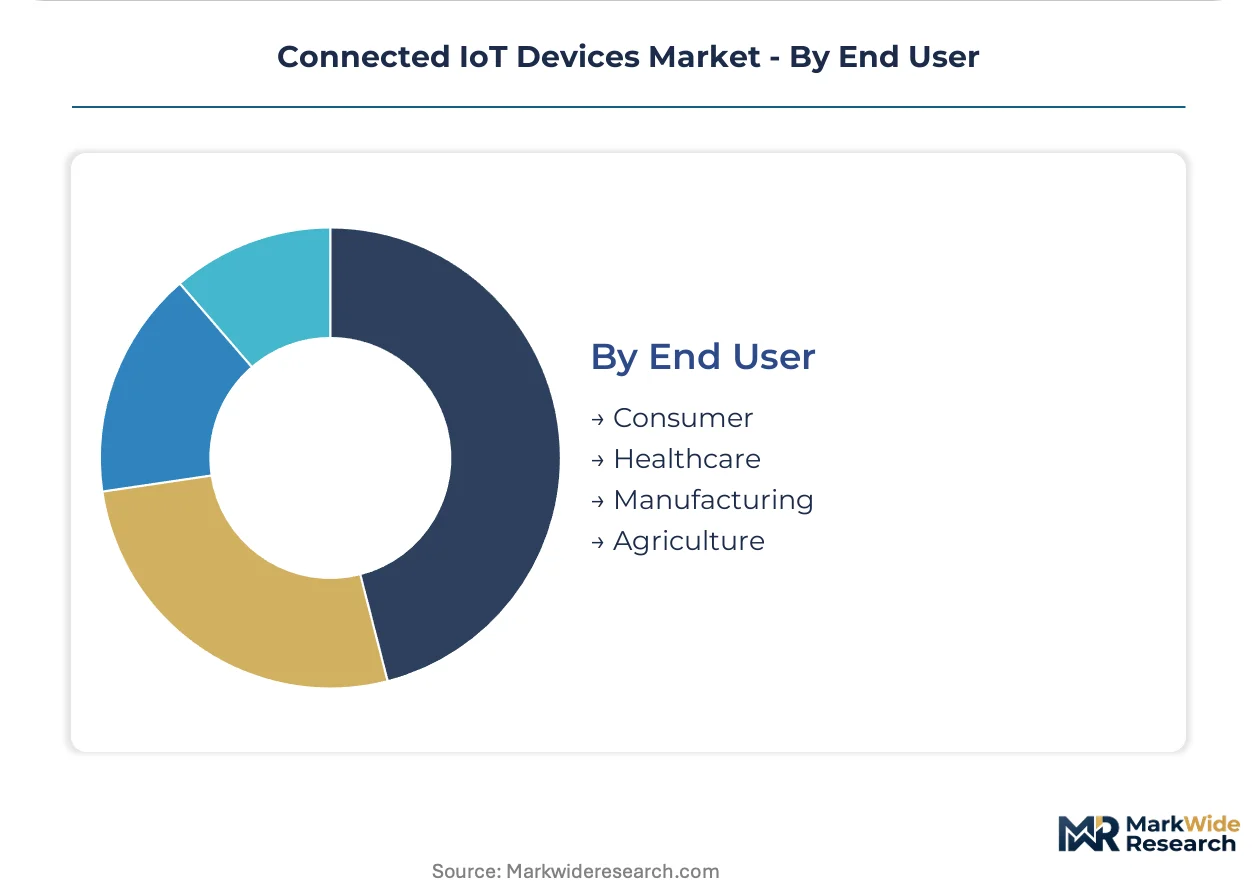
Customer type determines procurement authority structures, with healthcare consolidating around enterprise platform contracts and manufacturing favoring departmental point solutions.
- Healthcare:Hospital systems and home health agencies deploy remote patient monitoring infrastructure under multi-year enterprise agreements. United States procurement is concentrating authority within supply chain and clinical informatics departments, displacing fragmented departmental purchasing.
- Manufacturing:Discrete and process industries deploy predictive maintenance and quality control telemetry, with Germany's industrial automation density generating concentrated sensor demand.
- Consumer:Individual households acquiring smart home and wearable devices through retail channels.
- Agriculture:Precision farming operators deploying soil moisture and microclimate monitoring in water-stressed cultivation regions.
Manufacturing leads in hardware unit volume, with Healthcare demonstrating the steepest expansion trajectory as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting manufacturing investment toward jurisdictions with streamlined conformity pathways, compressing time-to-market for vendors navigating multi-jurisdiction certification requirements.
United States
Hospital systems are consolidating procurement around enterprise remote patient monitoring platforms. The FCC governs radio spectrum allocation and device certification for IoT hardware. Healthcare demand concentrates in the Boston-Cambridge corridor, where academic medical centers are deploying continuous telemetry infrastructure.
Germany
Automotive and precision engineering operators require vibration-resistant telemetry for critical asset monitoring. The EU AI Act imposes conformity assessments on connected devices employing machine learning for autonomous decision-making. Manufacturing automation density generates concentrated sensor demand across the Munich-Stuttgart industrial corridor.
China
Domestic module manufacturers are scaling production for agricultural and industrial sensor networks. MIIT enforces GB standards for domestic IoT cybersecurity, creating divergent compliance burdens. Shenzhen and Shanghai anchor design and assembly capacity for cellular LPWA chipsets serving regional export markets.
India
Production-linked incentives for semiconductor assembly and testing are attracting module manufacturers. The country's national electronics regulator enforces localization mandates for government procurement. Karnataka and Telangana are emerging as assembly hubs for connectivity modules targeting domestic precision farming applications.
Japan
Automotive OEMs are integrating edge-native processing for autonomous vehicle telemetry. METI oversees industrial standards coordination for smart manufacturing deployments. The Nagoya-Toyota industrial zone is deploying tensor-optimized microcontrollers for sub-10 millisecond control loops in production environments.
Connected IoT Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-integrated vendors capturing healthcare procurement consolidation while component suppliers serve fragmented industrial point solutions. The vendor base organizes into three tiers: cloud hyperscalers bundling infrastructure, semiconductor firms supplying connectivity silicon, and industrial automation houses delivering vertical-specific systems. Dominant competitive moves include strategic partnerships between sensor manufacturers and cloud platforms, plus geographic expansion through localized certification partnerships.
Within the industrial automation tier, Siemens AG anchors European market presence through its MindSphere platform architecture. Qualcomm Technologies occupies a position in cellular modem supply for low-power wide-area deployments. Huawei Technologies exemplifies the vertically integrated challenger archetype despite Western market access constraints.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Cisco Systems |
| IBM |
| Intel Corporation |
| Siemens AG |
| Huawei Technologies |
| Qualcomm Technologies |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Cellular LPWA module standardization around NB-IoT and LTE-M is compressing hardware BOM differentials while concentrating procurement leverage with East Asian semiconductor foundries. This technology transition simultaneously flattens tiered pricing structures and tightens supply-side bargaining power for European and North American device OEMs.
Pricing Analysis
Distributor margins on cellular connectivity modules compress as Qualcomm Technologies and Huawei Technologies sell direct to large-volume OEMs. Pricing stratifies across premium, standard, and economy tiers based on certification grade (FCC/CE/MIIT GB) and volume scale. Cost compression in mid-tier industrial sensors is intensifying because Chinese module manufacturers are absorbing margin to capture European automotive contracts. Healthcare providers in the United States demonstrate lowest price sensitivity due to bundled platform procurement, while agricultural cooperatives in water-stressed regions exhibit highest sensitivity.
Supply Chain Analysis
Firmware engineering talent shortages in Shenzhen and Shanghai are forcing module manufacturers to automate test protocols and relocate final assembly to Vietnam and India. Advanced node fabrication for low-power wide-area chipsets draws from Taiwan, South Korea, and mainland China. Lithium-ion cell supply hinges on raw material extraction constraints in Australia and Chile. Single-source vulnerability concentrates in 5G baseband silicon. Distribution runs through authorized distributors serving industrial automation OEMs in Germany and contract manufacturers in Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Connected IoT Devices Market functions as a geographic-arbitrage play where India's PLI scheme for electronics manufacturing offers cost advantages against EU AI Act compliance burdens in Germany. Vendors can capture margin by locating assembly in South Asia while maintaining algorithmic transparency engineering in Europe.
For Market Incumbents: Anticipate margin compression from Chinese module manufacturers selling below cost to secure European automotive platform wins. Defend position by deepening backward integration into cellular modem IP and accelerating CE marking pathways under EU AI Act conformity assessment frameworks. Prioritize hiring regulatory affairs specialists with machine learning governance expertise in Munich and Stuttgart. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for algorithmic documentation and human oversight interface specialists serving medical device manufacturers. Target agricultural sensor networks in water-stressed regions of India where precision farming adoption lags manufacturing automation density. Pursue go-to-market partnerships with domestic module assemblers in Karnataka and Telangana leveraging PLI scheme incentives. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with captive cellular LPWA testing capacity and MIIT GB certification capabilities. Long-term viability centers on vendors controlling both edge-native processing silicon and cloud analytics subscription revenue. Watch for inflection when hospital systems in the United States consolidate remote patient monitoring procurement around single-platform enterprise agreements.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Medical device manufacturers in Germany accelerate hiring of regulatory affairs specialists with machine learning governance expertise. |
| Cellular LPWA Module Standardization | Qualcomm Technologies and Huawei Technologies enable single-SKU designs serving carrier-managed and private network deployments. |
| Edge-Native Processing Architecture | Manufacturing operators in Japan's Nagoya-Toyota zone deploy tensor-optimized microcontrollers for sub-10 millisecond control loops. |
| India PLI Scheme Manufacturing Footprint | Module manufacturers establish assembly capacity in Karnataka and Telangana targeting domestic precision farming applications. |
| Healthcare Platform Consolidation | Hospital systems in the United States displace point-solution vendors with multi-year enterprise agreements bundling hardware and analytics. |
Methodological Framework
Bottom-up healthcare and manufacturing modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committees, plant engineers at automotive OEMs, and regulatory affairs specialists were validated against secondary sources including FCC device certification databases, EMA conformity assessment filings, MIIT GB standard publications, and customs records for cellular module trade flows. This triangulation approach ensures demand-side procurement patterns align with supply-side capacity constraints.
Historical trendline analysis of remote patient monitoring deployments and industrial sensor replacement cycles established baseline growth trajectories across the projection horizon. The analytical framework models segmentation dimensions including product type (industrial sensors, smart home devices, wearables, smart meters), deployment model (edge computing, cloud-based, on-premises, hybrid), connectivity type (cellular, Wi-Fi, Bluetooth, Zigbee), and end user (healthcare, manufacturing, consumer, agriculture). CAGRs were derived from regression analysis of hardware shipment volumes and connectivity subscription growth. Industry-specific forecast inputs include EU AI Act implementation timelines and India's PLI scheme capacity buildout schedules.
Revisions become necessary when regulatory enforcement intensity diverges from baseline assumptions or when semiconductor fabrication capacity expansion in East Asia accelerates beyond projected timelines. Forecasts reflect documented assumptions regarding hospital procurement consolidation patterns and agricultural sensor network adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Europe Cellular IoT Market