
 LPWAN in the Consumer IoT Market | 2026-2036
LPWAN in the Consumer IoT Market Size, Share, and Industry Trends Forecast 2026-2036
LPWAN in the Consumer IoT Market Insights
Multi-source chipset procurement is broadening as OEMs diversify beyond single-vendor LoRa dependencies. Semtech Corporation anchors the LoRaWAN ecosystem through its proprietary radio IP licensing model across module makers. Qualcomm Technologies, Inc. competes in the cellular LPWAN space with integrated NB-IoT and LTE-M baseband solutions for consumer device OEMs. Huawei Technologies Co., Ltd. extends its reach through vertically integrated silicon-to-network stacks, particularly in markets where it controls local infrastructure partnerships.
LPWAN in the Consumer IoT comprises low-power, wide-area network technologies operating in sub-GHz unlicensed or licensed spectrum bands with data rates from 0.3 kbps to 50 kbps and battery life extending 10 years, designed to connect distributed sensors and actuators where Wi-Fi range falls short and cellular power budgets exceed device constraints. LoRaWAN leads in smart home appliance deployments due to mature gateway ecosystems and minimal subscription overhead, while NB-IoT captures health monitoring applications where licensed spectrum reliability and regulatory-grade security certifications matter. Asset trackers represent the fastest-growing product type as logistics providers and consumer brands adopt disposable or low-cost tracking tags for high-value goods.
FCC Part 15 rules govern unlicensed LPWAN device emissions in the United States, while CE marking under the EU Radio Equipment Directive mandates harmonized spectrum access and interoperability testing for European market entry. China's MIIT issues network access licenses for NB-IoT modules operating on domestic carrier bands, creating compliance friction for imported silicon. Stakeholders must monitor evolving national spectrum reallocations and certification reciprocity agreements that could abruptly alter hardware qualification timelines and regional supplier viability.
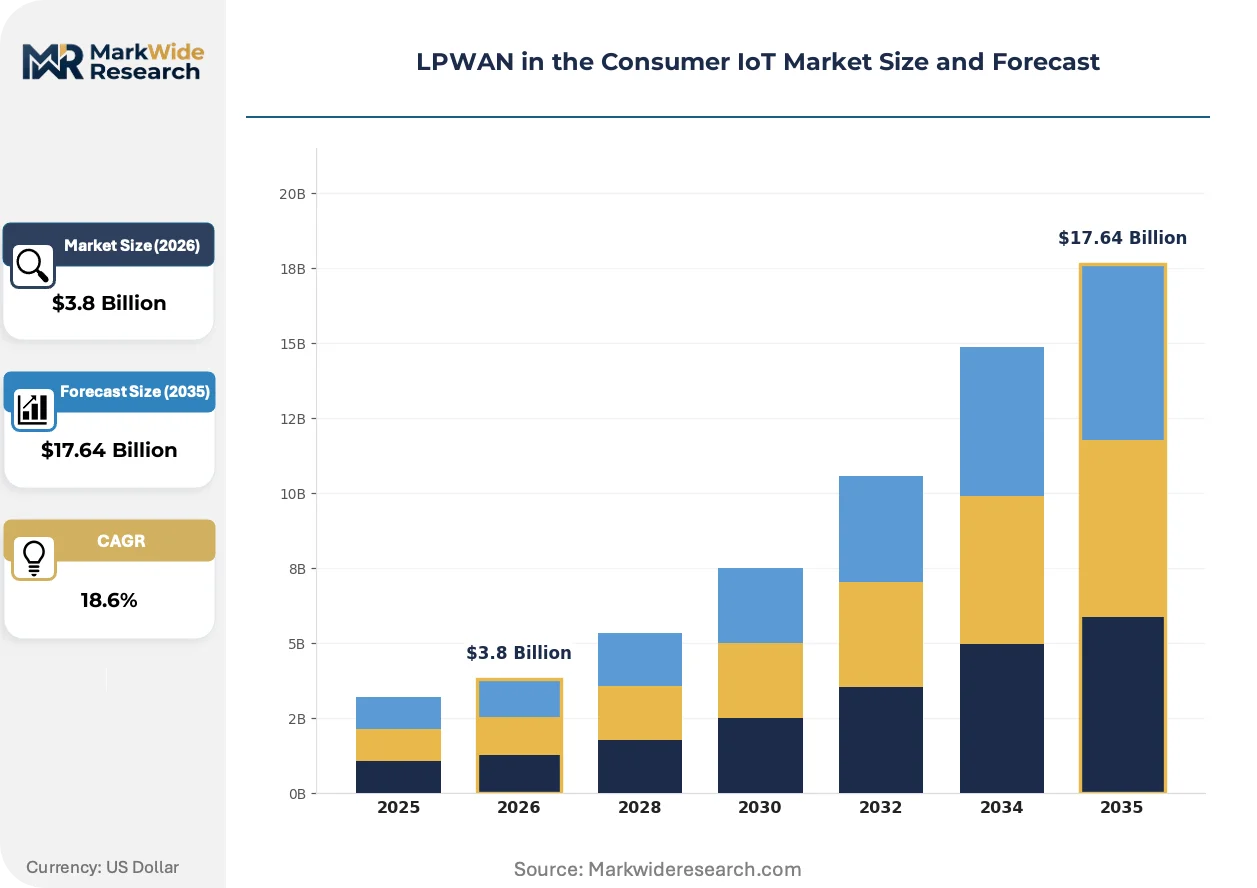
Market Dynamics
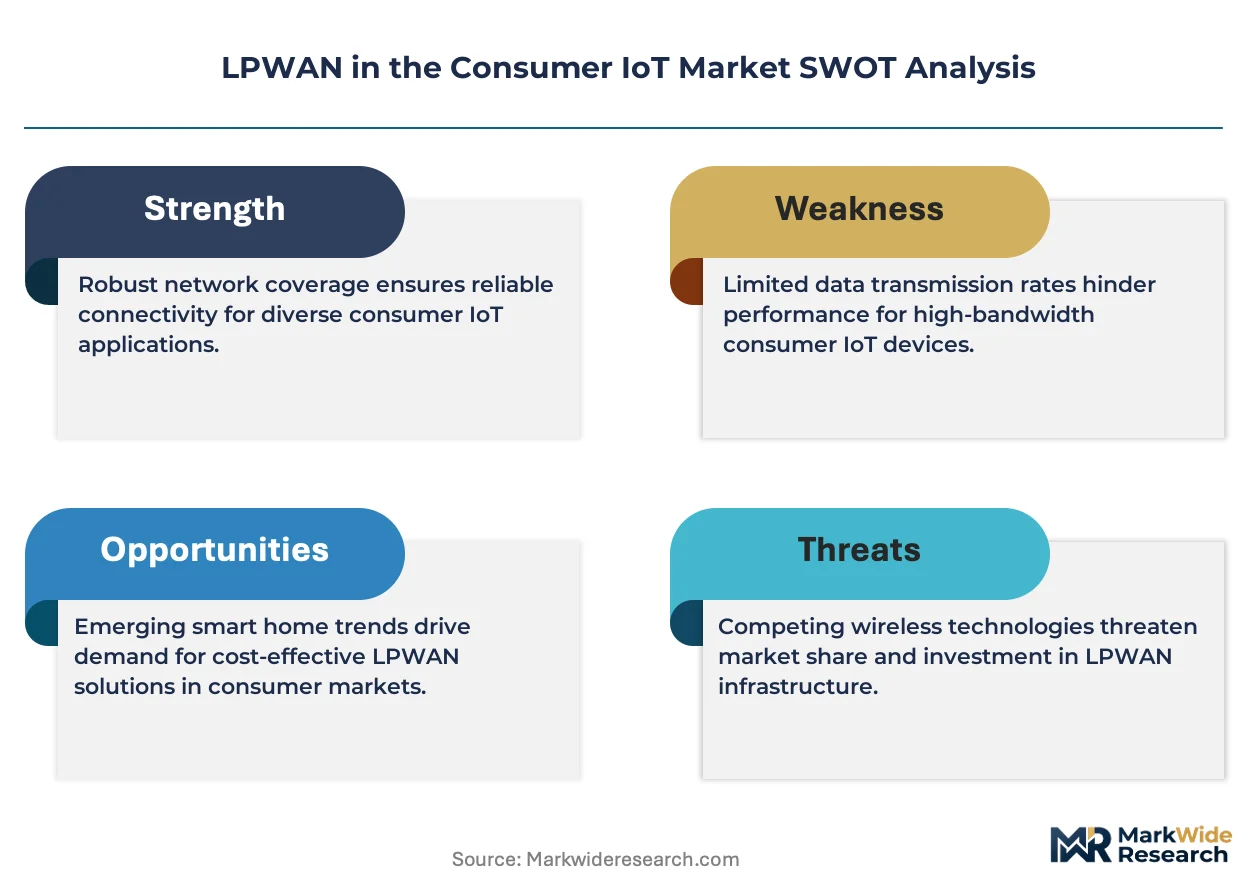
Smart home appliance manufacturers are expanding LPWAN integration into connected devices as the EU AI Act and GDPR compliance requirements push device makers toward certified low-power architectures. Multi-source chipset procurement is broadening as OEMs diversify beyond single-vendor dependencies.
Growth Catalysts
- EU AI Act compliance mandates:Device manufacturers in Germany and France are retrofitting connected appliances with certified low-power architectures to meet algorithmic transparency and data governance requirements.
- Smart home gateway ecosystem maturity:Residential automation installers across the Netherlands and Belgium are specifying LoRaWAN modules for whole-home sensor networks.
- Industrial IoT cluster proximity:Bavarian consumer electronics R&D hubs leverage adjacent automotive and manufacturing LPWAN deployments for shared infrastructure and talent pools.
Market Restraints
- Silicon supply concentration:LoRa radio IP licensing remains concentrated with Semtech Corporation, creating single-point-of-failure risk for module makers dependent on proprietary stack access.
- Licensed spectrum subscription costs:NB-IoT deployments incur recurring carrier fees that erode margin on sub-$20 consumer devices.
- Unlicensed band congestion:Sub-GHz ISM spectrum in dense European urban centers experiences interference from legacy industrial telemetry systems.
Strategic Opportunities
- Eastern European smart city integration:Polish and Romanian municipalities are bundling residential LPWAN connectivity with municipal lighting and waste management infrastructure tenders.
- Health monitoring regulatory tailwind:Germany's DiGA fast-track pathway for digital health applications is accelerating NB-IoT adoption in prescription-grade remote patient monitoring devices.
- Asset tracker channel innovation:Direct-to-consumer subscription models for disposable luggage and pet trackers are bypassing traditional retail electronics distribution.
Industry Challenges
- RF certification timeline compression:CE marking under the EU Radio Equipment Directive requires harmonized spectrum access testing that delays hardware launches by 4-6 months.
- Multi-protocol firmware complexity:OEMs supporting both LoRaWAN and NB-IoT variants face doubled qualification overhead for carrier certification and interoperability validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LPWAN in the Consumer IoT Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LoraWAN, Sigfox, NB-IoT, LTE-M Product Type: Smart Meters, Wearable Devices, Smart Home Appliances, Asset Trackers Application: Smart Agriculture, Home Automation, Health Monitoring, Smart Cities Connectivity: Cellular, Satellite, LPWAN, Bluetooth |
| Companies Covered | Semtech Corporation, Sigfox, AT&T, Actility, Ingenu Inc., Qualcomm Technologies, Inc., Huawei Technologies Co., Ltd., China Telecom, China Unicom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LPWAN in the Consumer IoT Market Trends and Innovations
LPWAN architectures are bifurcating between unlicensed LoRaWAN ecosystems and licensed cellular variants as compliance requirements harden. This divergence is reshaping how module vendors structure their product portfolios and geographic go-to-market strategies.
LoRaWAN is expanding into premium smart home security systems as German and Austrian insurers begin mandating certified connectivity for policy discounts. Residential integrators in Stuttgart and Vienna are specifying gateway-plus-sensor bundles that leverage mature open-source stack implementations. This technology is expanding into adjacent building automation segments previously served by proprietary Z-Wave or Zigbee implementations.
REACH substance restrictions and the EU Green Deal circular economy mandates are forcing module makers to eliminate conflict minerals and redesign for disassembly. The F-Gas Regulation's phase-down of fluorinated greenhouse gases affects cooling systems in edge gateway enclosures. Consumer appliance OEMs in Italy and Spain are responding by qualifying halogen-free PCB substrates and low-emission conformal coatings.
Buyer procurement patterns are consolidating around pre-certified module platforms rather than discrete chipset sourcing. Large white-goods manufacturers in Germany are shifting from component-level RF design to integrated LoRaWAN or NB-IoT modules with pre-loaded carrier profiles. This consolidation is most visible in France where domestic appliance brands are standardizing on three qualified module suppliers for pan-European SKU rationalization.
LPWAN in the Consumer IoT Market Segmentation
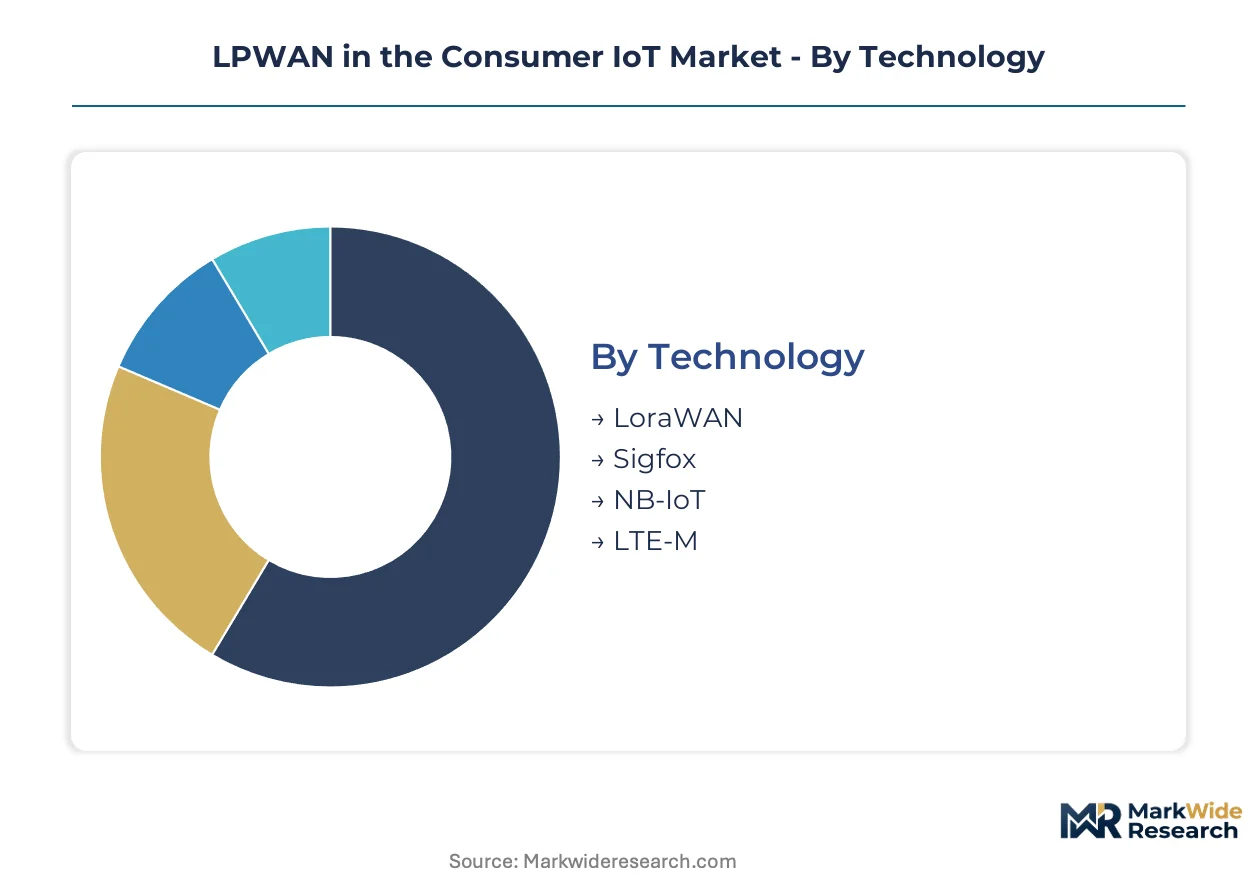
LPWAN deployment patterns diverge sharply across technology standards and use cases, with procurement decisions driven by spectrum licensing costs, battery life requirements, and gateway infrastructure availability. Manufacturers must align module selection with specific application constraints rather than defaulting to lowest-cost options.
Technology:
Procurement teams weigh total cost of ownership against deployment scale when selecting radio standards.
- LoRaWAN:Open-source MAC layer operating in sub-GHz ISM bands enables private network deployment without recurring carrier fees. German smart home integrators in Stuttgart and Munich favor this standard for whole-building sensor meshes where subscription economics would erode margins on sub-$50 devices.
- NB-IoT:Licensed 3GPP standard delivering deep indoor penetration through 200 kHz narrowband carriers. France's DiGA fast-track pathway for digital health devices is accelerating module adoption in prescription-grade remote patient monitors where CE marking under MDR mandates carrier-grade reliability.
- Sigfox:Ultra-narrowband proprietary network with national roaming agreements. Deployment concentrates in French utility metering where national coverage obviates private gateway infrastructure.
- LTE-M:1.4 MHz bandwidth cellular variant supporting voice and mobility. Austrian automotive suppliers specify this for connected vehicle accessories requiring handover capability.
Volume sits with LoRaWAN; growth tilts toward NB-IoT as health monitoring regulatory frameworks mature.
Product Type:
End-use durability and replacement cycles reshape module BOM decisions across device categories.
- Asset Trackers:Disposable or rechargeable tags with 2-5 year battery targets. Polish logistics providers and direct-to-consumer luggage brands in the Netherlands are driving specification for ultra-low-power modes and compact ceramic antenna integration.
- Smart Home Appliances:White-goods integration requiring 10-year operational life. Italian manufacturers are qualifying halogen-free PCB substrates under EU Green Deal circular economy mandates for washing machine and refrigerator connectivity modules.
- Smart Meters:Utility-grade enclosures with tamper-evident sealing. Spanish electricity distributors specify this category for residential AMI rollouts.
- Wearable Devices:Skin-contact form factors with SAR compliance requirements. Belgian health tech startups target prescription wellness applications.
Appliance volumes dominate current procurement; tracker applications are expanding most quickly through subscription-based direct channels.
Application:
Regulatory tailwinds and infrastructure subsidies determine geographic prioritization for solution vendors.
- Home Automation:Residential gateway ecosystems with multi-protocol backhaul. Dutch installers specify LoRaWAN for retrofit sensor networks in heritage buildings where Wi-Fi penetration fails.
- Health Monitoring:Clinical-grade data transmission with GDPR Article 9 sensitivity classification. German wearable OEMs pursue DiGA reimbursement eligibility through certified NB-IoT architectures.
- Smart Agriculture:Soil and livestock sensors in remote pastureland. Romanian farming cooperatives leverage municipal LPWAN infrastructure bundled with waste management tenders.
- Smart Cities:Streetlight and parking sensor networks with 15-year asset lifecycles. Polish municipalities integrate residential connectivity into unified procurement frameworks.
Home automation captures present volume concentration; health monitoring shows steepest expansion trajectory as reimbursement pathways standardize.
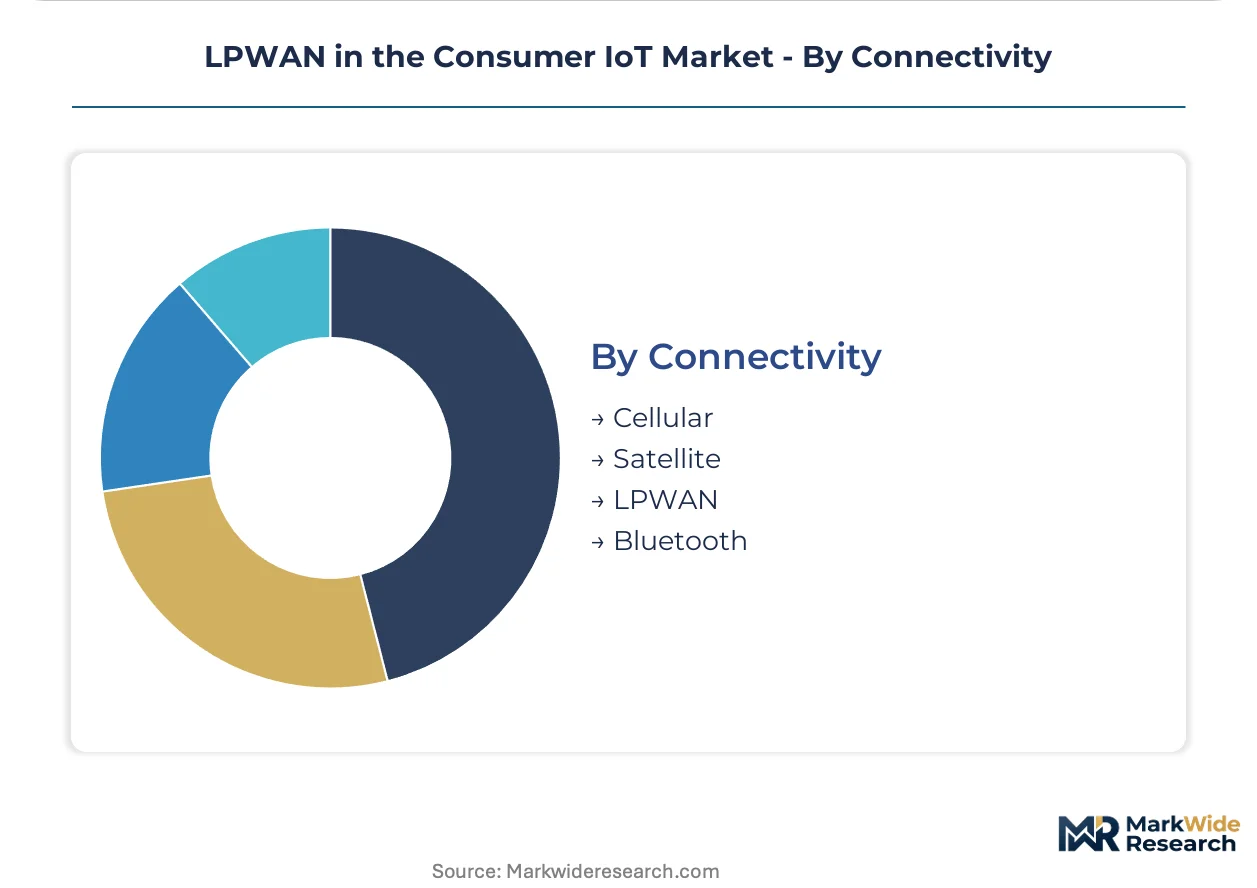
Connectivity:
Hybrid architectures are displacing single-mode designs as OEMs future-proof against spectrum reallocation risks.
- LPWAN:Purpose-built low-power wide-area protocols excluding legacy cellular. Bavarian industrial IoT clusters share LoRaWAN infrastructure between consumer and manufacturing applications.
- Cellular:Licensed spectrum with carrier-managed QoS. French insurers mandate certified connectivity for smart home security policy discounts.
- Satellite:Non-terrestrial backhaul for remote asset tracking. Alpine logistics operators in Austria test hybrid LoRaWAN-satellite handoff for mountain corridor visibility.
- Bluetooth:Short-range complement for provisioning and edge aggregation. Spanish appliance OEMs embed dual-mode modules for smartphone-based device onboarding.
LPWAN and cellular combinations command current design wins; satellite integration is gaining share fastest in outdoor mobility segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sub-GHz spectrum allocations in unlicensed ISM bands anchor LPWAN deployment geography, with regulatory harmonization across the EU Radio Equipment Directive creating contiguous market access from the Atlantic to the Black Sea.
Germany
Industrial IoT clusters in Bavaria and Baden-Württemberg generate dual-use infrastructure demand as automotive suppliers share LoRaWAN gateways with adjacent consumer electronics R&D facilities. The EU AI Act compliance mandates from Berlin's Federal Network Agency push device makers toward certified low-power architectures with algorithmic transparency documentation. Stuttgart integrators specify gateway-plus-sensor bundles for whole-home security networks qualifying for insurer policy discounts.
France
Paris-based health technology startups exploit the DiGA fast-track reimbursement pathway for prescription-grade remote patient monitors requiring NB-IoT carrier-grade reliability. ANSM and CNIL jointly enforce GDPR Article 9 sensitivity classifications on wearable data transmission architectures. Utility metering deployments concentrate in Lyon and Marseille where national Sigfox coverage eliminates private gateway infrastructure investment for water and electricity distributors.
Netherlands
Amsterdam residential automation installers specify LoRaWAN modules for retrofit sensor networks in UNESCO heritage buildings where Wi-Fi penetration fails through meter-thick masonry. The Dutch Authority for Digital Infrastructure enforces CE marking harmonization that accelerates cross-border hardware qualification into Belgium and Luxembourg. Eindhoven's high-tech campus exports RF engineering talent to domestic white-goods manufacturers integrating pre-certified connectivity modules.
Poland
Warsaw and Krakow municipalities bundle residential LPWAN connectivity with smart streetlight and waste management infrastructure tenders under unified procurement frameworks. The Office of Electronic Communications manages spectrum reallocation timelines that affect sub-GHz device certification windows. Logistics providers in Silesia drive specification for disposable asset tracker tags with ultra-low-power ceramic antenna integration for cross-border freight visibility.
Spain
Barcelona appliance OEMs qualify halogen-free PCB substrates under EU Green Deal circular economy mandates for washing machine and refrigerator connectivity modules with ten-year operational life targets. The Ministry for the Ecological Transition enforces F-Gas Regulation phase-down requirements affecting edge gateway enclosure cooling systems. Madrid electricity distributors specify tamper-evident smart meter enclosures for residential AMI rollouts with utility-grade security certifications.
LPWAN in the Consumer IoT Market Competitive Landscape
Technology licensing dominates the current landscape as radio IP holders monetize proprietary stack access through tiered royalty structures. The vendor base concentrates around three strategic archetypes: semiconductor designers controlling physical layer specifications, module integrators aggregating pre-certified hardware platforms, and carrier-dependent cellular specialists managing subscription economics. Competitive positioning hardens through M&A activity targeting RF engineering talent pools and strategic partnerships bridging unlicensed and licensed spectrum ecosystems.
Within the semiconductor archetype, Semtech Corporation and Qualcomm Technologies, Inc. occupy positions reflecting divergent spectrum strategies, while Huawei Technologies Co., Ltd. anchors a vertically integrated silicon-to-network stack approach. These three entities exemplify how proprietary IP control, integrated baseband solutions, and infrastructure partnerships respectively shape go-to-market architectures across European and Asia-Pacific deployment zones.
| Leading Market Players |
|---|
| Semtech Corporation |
| Sigfox |
| AT&T |
| Actility |
| Ingenu Inc. |
| Qualcomm Technologies, Inc. |
| Huawei Technologies Co., Ltd. |
| China Telecom |
| China Unicom |
| Others |
Pricing and Supply Chain Analysis
EU AI Act compliance mandates from Germany's Federal Network Agency are forcing smart home appliance OEMs toward certified low-power architectures with algorithmic transparency documentation, compelling module vendors to absorb certification overhead into base pricing while buyers consolidate procurement around pre-qualified suppliers. This demand-side specification tightening concentrates pricing power with semiconductor designers controlling proprietary radio IP and pre-certified module platforms.
Pricing Analysis
Warranty and carrier subscription bundling separate premium module tiers from unbundled economy alternatives, with LoRaWAN's open-source stack enabling lower total cost of ownership against NB-IoT's recurring carrier fees. Price differentiation hinges on CE marking grade and gateway ecosystem maturity, with certified German integrators commanding premiums for insurer-mandated security bundles. Pricing pressure intensifies as Polish and Romanian municipalities bundle residential connectivity into unified infrastructure tenders, compressing margins on sub-$20 device categories. White-goods manufacturers exhibit highest price sensitivity due to ten-year operational life targets, while prescription-grade health monitoring OEMs absorb premium pricing for DiGA reimbursement eligibility.
Supply Chain Analysis
Dual-sourcing requirements from German and French appliance OEMs mandate multi-supplier qualification for LoRa radio IP and NB-IoT baseband silicon, reducing single-point-of-failure exposure to Semtech's proprietary licensing concentration. Manufacturing concentrates in Taiwan for RF frontend components, Germany for automotive-adjacent module integration, and China for cost-optimized ceramic antenna substrates. Raw material dependencies include sub-GHz RF transceivers, halogen-free PCB laminates under REACH restrictions, and low-emission conformal coatings compliant with F-Gas Regulation phase-downs. Single-source vulnerability in proprietary stack access creates supply chain risk. Distribution runs through pre-certified module platforms rather than discrete chipset sourcing, with large OEMs shifting from component-level RF design to integrated carrier-profile modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over proprietary radio IP licensing and gateway infrastructure partnerships determines sustainable margin capture. Players are pursuing backward integration into RF frontend component sourcing to reduce licensing royalty burdens.
For Market Incumbents: Hedge against Sigfox network coverage gaps and emerging LTE-M mobility applications by diversifying module portfolios across unlicensed and licensed spectrum variants. Secure exclusive gateway infrastructure partnerships in Bavarian industrial IoT clusters to lock in shared infrastructure economics. Invest in CE marking pre-certification capabilities to compress hardware launch timelines against regulatory friction.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels for disposable asset trackers offer the most penetrable entry vector, bypassing traditional retail electronics distribution controlled by established module vendors. Target Polish logistics providers and Dutch luggage brands with ultra-low-power ceramic antenna integration specifications. Pursue white-label partnerships with municipal smart city integrators bundling residential LPWAN into unified procurement frameworks.
For Investors and Strategic Acquirers: The window for entry favors RF engineering talent pools in Eindhoven and Stuttgart with dual LoRaWAN-NB-IoT firmware capabilities. Long-term viability over the next decade rests on positioning for spectrum reallocation uncertainty and regulatory harmonization shifts. Watch for CE marking reciprocity agreement announcements as the primary inflection indicator for regional supplier viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Radio IP Licensing Expansion | Semtech's proprietary stack monetization anchors LoRaWAN ecosystem control across European module makers. |
| Pre-Certified Module Platform Consolidation | German white-goods manufacturers shift procurement from discrete chipsets to integrated carrier-profile modules. |
| Gateway Infrastructure Partnership | Bavarian industrial IoT clusters share LoRaWAN infrastructure between automotive and consumer electronics R&D facilities. |
| DiGA Reimbursement Pathway Pursuit | French and German health tech startups accelerate NB-IoT adoption for prescription-grade remote patient monitors. |
| Halogen-Free PCB Substrate Qualification | Italian and Spanish appliance OEMs respond to EU Green Deal circular economy mandates for ten-year operational life targets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with RF engineering directors at module integrators, procurement leads at German white-goods OEMs, carrier certification managers, and smart home system integrators in the Netherlands and Belgium. Secondary sources included FCC Part 15 equipment authorization databases, EU Radio Equipment Directive harmonized standards publications, MIIT network access license registries, and CE marking conformity assessment body reports. Bottom-up module shipment aggregation and top-down connectivity service revenue reconciliation provided cross-validation.
Data-stream reconciliation across technology standard adoption curves, application-specific deployment scales, and regional regulatory cluster maturity informed the analytical framework over the projection horizon. Segmentation dimensions modeled include radio protocol, product type durability requirements, application regulatory tailwinds, and connectivity architecture hybridization. CAGRs were derived from installed base growth rates and replacement cycle compression. Industry-specific forecast inputs incorporated DiGA reimbursement pathway expansion timelines and municipal smart city tender bundling patterns.
Inputs from carrier certification managers and module vendor shipment disclosures were available through the study window; gaps in proprietary royalty rate structures and private gateway deployment counts introduce uncertainty bands around market share estimates. Deviation in EU AI Act enforcement intensity or sub-GHz spectrum reallocation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
IoT Application Enablement Market