
 IoT Device Management Market | 2026-2036
IoT Device Management Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Device Management Market Analysis
Shortages in embedded systems engineering talent are redrawing competitive boundaries across the IoT device management landscape. Microsoft Corporation leverages its Azure IoT ecosystem to anchor enterprise deployments with deep cloud-native integration. Amazon Web Services sustains momentum through edge-to-cloud orchestration capabilities that dominate industrial IoT workloads. PTC Inc. specializes in digital thread connectivity, differentiating its ThingWorx platform for manufacturing customers requiring real-time equipment telemetry.
IoT device management encompasses the remote provisioning, monitoring, firmware updating, and security administration of connected endpoints through centralized software platforms, typically operating over protocols such as MQTT or CoAP with TLS encryption for command integrity. The primary commercial purpose is to maintain operational continuity across distributed sensor networks while minimizing manual field intervention. Cloud-based deployment models capture the largest margin pools as enterprises prioritize elastic scalability and reduced infrastructure capital, while hybrid architectures are gaining traction among healthcare and transportation operators balancing latency sensitivity with centralized analytics. LPWAN technology leads in agricultural and utility metering applications where ultra-low power budgets and extended range outweigh bandwidth requirements.
The EU AI Act, GDPR, and ISO/IEC 27001 standards collectively shape product certification requirements and cross-border data handling obligations for device management vendors serving European enterprises. FDA cybersecurity guidance and HIPAA technical safeguards impose analogous constraints on healthcare IoT deployments in the United States. Stakeholders must monitor evolving national encryption export controls and sector-specific incident reporting mandates that will determine platform architecture decisions and geographic market access priorities.
Market Dynamics
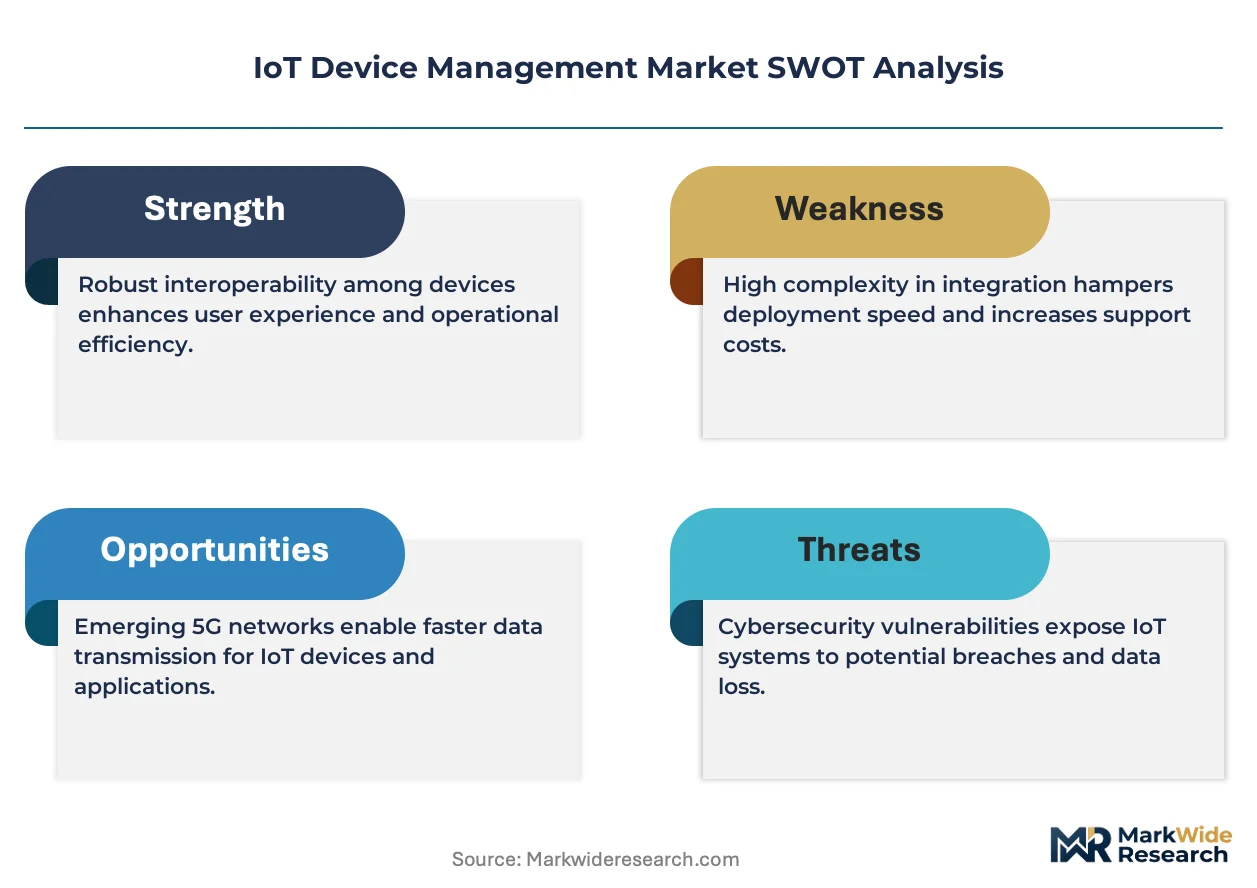
The IoT Device Management Market is experiencing structural compression as edge computing architectures fragment traditional cloud-centric control planes, forcing platform vendors to rearchitect for distributed intelligence while maintaining centralized governance capabilities.
Growth Catalysts
- Industrie 4.0 mandates:German automotive OEMs and machinery producers are procuring certified device management stacks to satisfy factory digitization KPIs tied to federal innovation funding programs.
- EU AI Act compliance deadlines:Enterprises across France, Italy, and the Netherlands are accelerating platform migrations to avoid penalties for non-conforming AI-enabled IoT deployments.
- LPWAN spectrum allocation:Agricultural operators in Brazil and Australia are expanding sensor networks using newly licensed sub-GHz bands for irrigation and livestock monitoring.
Market Restraints
- Silicon supply concentration:Taiwan-based foundry capacity constraints continue limiting secure element availability for device authentication modules.
- GDPR data localization:Cross-border telemetry routing requires expensive in-region cloud infrastructure buildouts that erode platform margins.
- MQTT protocol limitations:Lightweight messaging constraints prevent native support for complex over-the-air firmware delta compression, increasing bandwidth costs.
Strategic Opportunities
- Healthcare IoT in Japan:METI's Society 5.0 initiative is creating procurement windows for compliant remote patient monitoring platforms in rural prefectures.
- Digital twin convergence:Real-time device telemetry fused with physics-based simulation is opening premium pricing tiers for predictive maintenance contracts.
- India smart city mandates:Ministry of Housing and Urban Affairs requirements for municipal sensor networks are generating large-scale RFPs for integrated device management.
Industry Challenges
- Embedded security engineering scarcity:Firms report 8-14 month hiring cycles for firmware developers with TLS 1.3 and hardware security module expertise.
- ISO/IEC 27001 certification timelines:European vendors face 12-18 month audit backlogs that delay enterprise sales cycles.
- Legacy SCADA integration:Brownfield manufacturing sites require costly protocol gateway development to bridge Modbus and OPC-UA environments with modern MQTT platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Device Management Market |
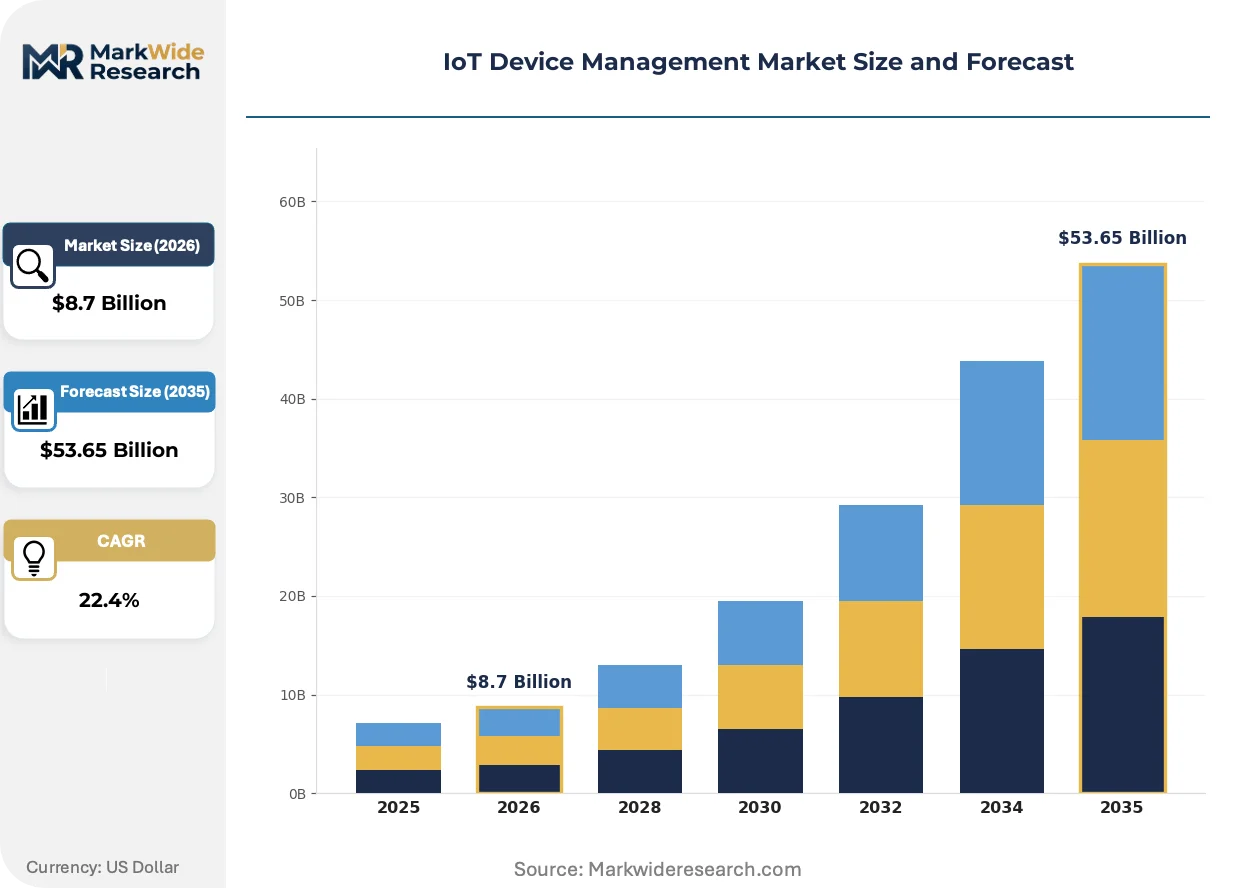
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Gateways, Controllers, Actuators Deployment Model: Cloud-Based, On-Premises, Hybrid, Multi-Cloud End User: Manufacturing, Healthcare, Transportation, Smart Homes Technology: LPWAN, Bluetooth, Zigbee, Wi-Fi |
| Companies Covered | Microsoft Corporation, Amazon Web Services, PTC Inc., IBM Corporation, Oracle Corporation, Google LLC, Advantech Co. Ltd., Telit Communications PLC, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Device Management Market Emerging Trajectories
Platform architectures are fragmenting as computational gravity shifts toward endpoints, creating new competitive axes around edge-native orchestration and sovereign data handling capabilities.
Containerized micro-agent runtimes are decomposing monolithic device management stacks into modular functions deployable on resource-constrained sensors. Automotive Tier-1 suppliers are embedding these lightweight agents directly into ECUs for over-the-air diagnostics. This decomposition is compressing vendor differentiation around proprietary cloud consoles while elevating interoperability standards.
CSRD disclosure mandates are forcing European industrial operators to instrument Scope 1 and Scope 2 emissions through certified IoT telemetry chains. The regulation requires auditable data provenance from sensor to sustainability report. Energy-intensive sectors including steel and chemicals are prioritizing platforms with built-in carbon accounting modules and EU-verified measurement protocols.
Subscription-based platform procurement is displacing perpetual licensing among mid-market manufacturing customers. Channel partners in Germany and Switzerland are bundling device management with predictive maintenance services to capture recurring revenue. This shift is most visible among automotive supplier networks where OEMs are mandating vendor-managed connectivity as a condition of supplier qualification.
IoT Device Management Market Segmentation
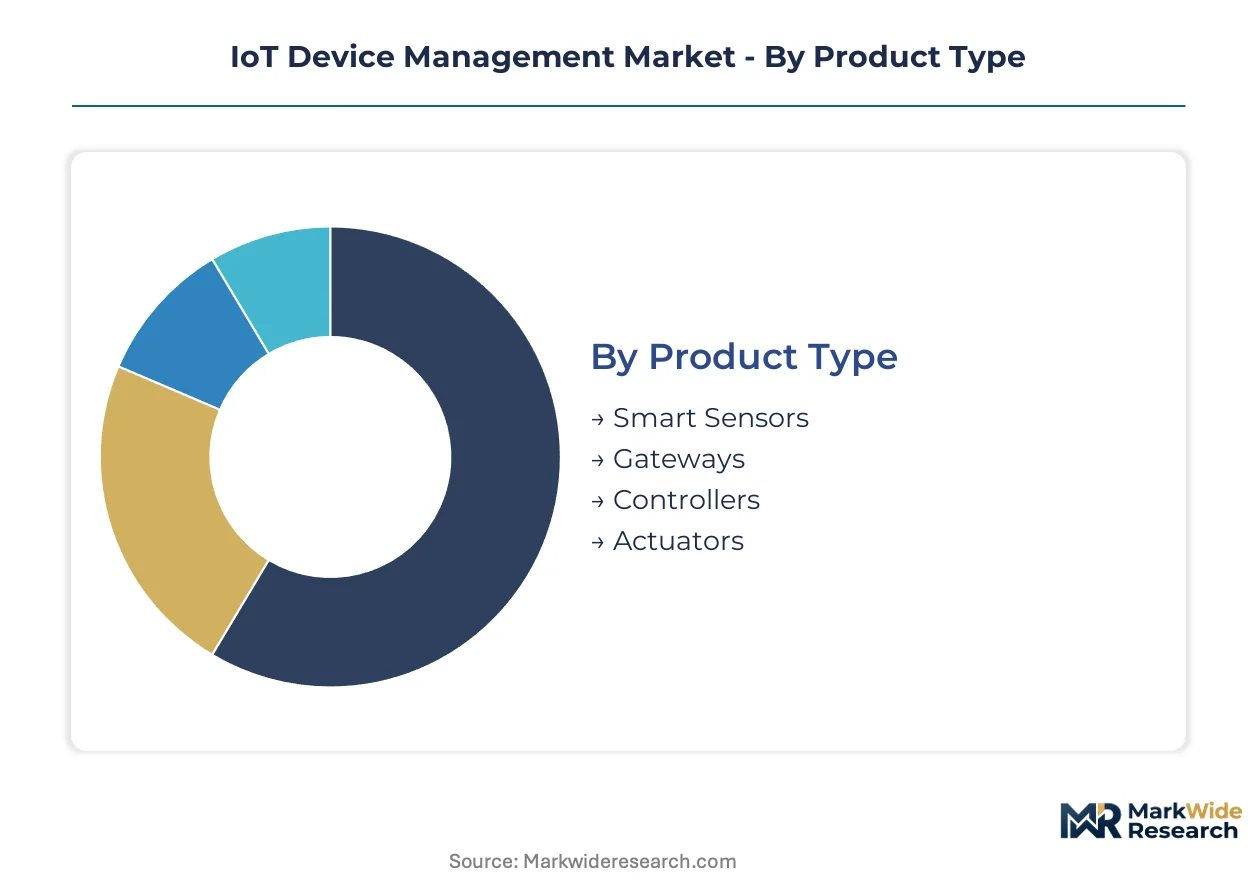
Segmentation reveals how IoT device management platforms fragment across hardware form factors, infrastructure architectures, industry verticals, and connectivity protocols. Each dimension carries distinct margin profiles, compliance burdens, and substitution vulnerabilities that reshape vendor positioning.
Product Type:
Smart sensors face the most acute substitution pressure as commoditized hardware from Asian contract manufacturers erodes proprietary differentiation across all four hardware categories.
- Smart Sensors:Microelectromechanical systems capturing temperature, vibration, pressure, and environmental parameters with embedded edge preprocessing. German automotive OEMs and machinery producers dominate procurement volumes as Industrie 4.0 mandates harden telemetry requirements for predictive maintenance workflows.
- Gateways:Protocol translation hubs bridging LPWAN, Zigbee, and legacy Modbus networks to IP backbones with local buffering and offline resilience. Demand clusters in brownfield manufacturing sites across France and Italy where EU AI Act compliance deadlines are forcing rapid infrastructure upgrades.
- Controllers:Programmable logic devices executing closed-loop automation at the edge with deterministic latency guarantees.
- Actuators:Electromechanical output devices converting digital commands into physical state changes for valve, motor, and robotic control.
Smart sensors retain volume leadership; gateways hold the steepest expansion curve as hybrid architectures displace pure cloud deployments.
Deployment Model:
Cost tier stratification separates enterprise-grade multi-cloud orchestration from constrained-budget on-premises installations in regulated healthcare and government verticals.
- Cloud-Based:Fully managed SaaS platforms with elastic compute scaling and centralized firmware orchestration delivered over TLS-encrypted MQTT backplanes. Manufacturing customers in Germany and the Netherlands prioritize this model to minimize infrastructure capital and accelerate EU AI Act certification timelines.
- On-Premises:Air-gapped or private data center deployments satisfying GDPR data localization mandates and FDA cybersecurity guidance for healthcare IoT. French and Italian enterprises accept higher total cost of ownership to avoid cross-border telemetry routing penalties.
- Hybrid:Split architectures processing time-critical workloads at the edge while streaming aggregated analytics to centralized cloud consoles.
- Multi-Cloud:Vendor-agnostic orchestration layers abstracting AWS, Azure, and Google Cloud infrastructure to prevent single-provider lock-in.
Cloud-based deployments capture the widest customer base; hybrid configurations are climbing the fastest as latency-sensitive applications proliferate.
End User:
Application-specific compliance requirements fragment platform procurement, with healthcare and transportation operators facing the most stringent certification barriers.
- Manufacturing:Discrete and process industry deployments spanning automotive assembly, steel production, and chemical processing with SCADA integration demands. German machinery producers and automotive suppliers drive platform selection, bundling device management with predictive maintenance service contracts.
- Healthcare:Remote patient monitoring, clinical asset tracking, and connected medical devices governed by FDA cybersecurity guidance and HIPAA technical safeguards in the United States, with analogous EMA and national health authority requirements across Europe.
- Transportation:Fleet telematics, connected vehicle diagnostics, and logistics cold chain monitoring with NHTSA and EU vehicle type-approval constraints.
- Smart Homes:Consumer-grade automation hubs and connected appliance management with lower security thresholds and price sensitivity.
Manufacturing retains volume leadership; healthcare is gaining share fastest as aging demographics and rural care gaps expand remote monitoring mandates.
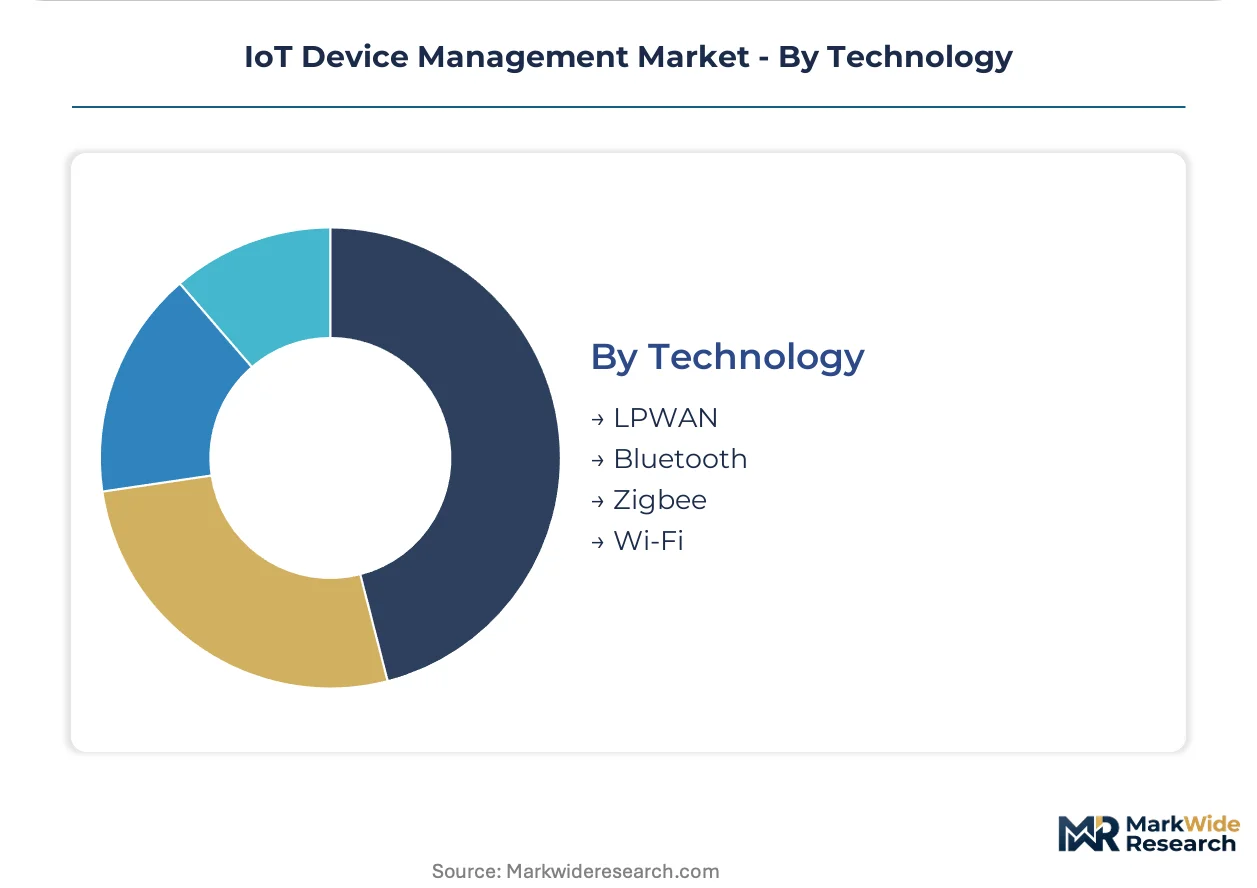
Technology:
Supply concentration in licensed spectrum and semiconductor IP shapes competitive dynamics across wireless protocol choices.
- LPWAN:Sub-GHz narrowband technologies including LoRaWAN and NB-IoT optimized for ultra-low power budgets and kilometer-range coverage. Agricultural operators in Brazil and Australia expand sensor networks using newly licensed spectrum for irrigation and livestock monitoring, while European utility metering relies on NB-IoT carrier infrastructure.
- Bluetooth:Short-range 2.4 GHz protocols including BLE 5.0 and mesh variants for indoor positioning and wearable health devices. Japanese healthcare providers under METI's Society 5.0 initiative deploy Bluetooth-enabled remote patient monitoring in rural prefectures.
- Zigbee:Mesh networking stack for smart home and building automation with self-healing topology and low-latency control.
- Wi-Fi:High-bandwidth 802.11 variants supporting video streaming and dense sensor clusters in industrial and commercial environments.
LPWAN retains volume leadership in utility and agricultural telemetry; Bluetooth holds the steepest expansion curve as healthcare wearables proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German manufacturers prioritize certified predictive maintenance stacks, while Brazilian agribusinesses favor ultra-low-power LPWAN telemetry. Japanese healthcare operators under METI mandates demand edge-native remote monitoring, and Indian municipalities procure at scale for smart city sensor grids.
Germany
Automotive OEMs and machinery producers anchor procurement volumes as Industrie 4.0 KPIs harden telemetry requirements. The EU AI Act and GDPR compliance deadlines compress platform migration timelines. Stuttgart and Munich industrial clusters drive demand for certified device management stacks bundled with predictive maintenance service contracts.
United States
Healthcare IoT deployments expand under FDA cybersecurity guidance and HIPAA technical safeguards for remote patient monitoring. NHTSA vehicle type-approval constraints shape connected fleet telematics procurement. Greater Boston and Silicon Valley health-tech clusters prioritize edge-to-cloud orchestration for clinical asset tracking.
Brazil
Agricultural operators scale LPWAN sensor networks using newly licensed sub-GHz spectrum for irrigation and livestock monitoring. ANVISA regulations govern connected medical device imports. São Paulo state agribusiness clusters lead procurement of ultra-low-power telemetry for precision farming operations.
Japan
METI's Society 5.0 initiative creates procurement windows for compliant remote patient monitoring platforms in rural prefectures. Bluetooth-enabled wearables proliferate under national health authority requirements. Kansai and Kyushu regional healthcare systems deploy edge-native device management for aging demographic care gaps.
India
Ministry of Housing and Urban Affairs mandates generate large-scale RFPs for integrated municipal sensor networks. BIS certification requirements shape platform selection for smart city deployments. Maharashtra and Karnataka state capitals lead procurement of cloud-based device management for traffic and utility monitoring grids.
IoT Device Management Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the IoT device management market. Cloud hyperscalers and industrial software incumbents dominate enterprise-grade deployments, while connectivity specialists and hardware-integrated vendors occupy mid-market niches. Two strategic archetypes define competitive positioning: cloud-native orchestration platforms with deep TLS-encrypted MQTT backplanes, and edge-embedded micro-agent providers serving latency-constrained industrial workloads. M&A activity concentrates on firmware security capabilities, while strategic partnerships target brownfield SCADA integration.
Among cloud-native orchestration providers, Microsoft Corporation and Amazon Web Services exemplify the integrated leader archetype with deep enterprise ecosystem anchoring. PTC Inc. occupies a position within the industrial specialist tier, representing digital thread connectivity for manufacturing telemetry requirements. These three entities collectively illustrate how vendor positioning fragments across cloud infrastructure depth, edge-native capabilities, and vertical-specific compliance bundling.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| PTC Inc. |
| IBM Corporation |
| Oracle Corporation |
| Google LLC |
| Advantech Co. Ltd. |
| Telit Communications PLC |
| Cisco Systems |
| Others |
Supply Flow & Price Mechanics
Foundry-scale economies in Taiwan and South Korea anchor secure element production for device authentication modules, compressing cost floors for gateway hardware while concentrating pricing power among semiconductor suppliers serving European compliance-driven procurement.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with SaaS-tiered structures separating premium EU AI Act-certified stacks from standard cloud-native offerings. Price differentiation hinges on ISO/IEC 27001 certification grade and after-sales predictive maintenance bundling. Cost compression in mid-market gateways is intensifying because Asian contract manufacturers are commoditizing protocol translation hardware. Mid-market manufacturing customers exhibit highest price sensitivity; German automotive OEMs show lowest sensitivity due to federal innovation funding absorption.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose concentrated foundry capacity for hardware security modules and LPWAN chipsets. Supply draws from Taiwan, South Korea, and China for semiconductor fabrication; Germany and the United States for industrial automation components. Single-source dependency on TSMC advanced nodes for secure elements creates structural fragility. Distribution runs through channel partners bundling device management with predictive maintenance services in Germany and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure cycles in automotive and industrial automation are lifting platform procurement volumes from cyclical troughs, positioning the market for sustained expansion through federal digitization mandates.
For Market Incumbents: Consolidate firmware security engineering capabilities through targeted capability acquisition, addressing 8-14 month hiring cycle gaps that constrain platform certification velocity. Deepen backward integration into edge-native micro-agent runtimes to defend against containerized orchestration challengers eroding proprietary cloud console differentiation.
For New Entrants and Emerging Players: Brownfield SCADA integration service gaps expose underserved manufacturing sites in France and Italy facing EU AI Act compliance deadlines. Target protocol gateway development for Modbus-OPC-UA-MQTT bridging as the most penetrable entry vector. Pursue channel partnerships with German automotive supplier networks where OEM-managed connectivity mandates create captive demand.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among edge-embedded micro-agent providers serving latency-constrained healthcare workloads under METI and FDA frameworks. Long-term viability favors platforms with sovereign data handling certifications spanning GDPR, HIPAA, and emerging national encryption controls. Monitor ISO/IEC 27001 audit backlog resolution as inflection indicator for European enterprise sales cycle normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies TLS-encrypted MQTT backplanes with edge-native orchestration for German automotive OEM deployments. |
| Acquisition of Specialist Firm | Addresses embedded security engineering scarcity through captive firmware talent pools with hardware security module expertise. |
| Strategic Partnership | Enables brownfield SCADA bridging for EU AI Act compliance in French and Italian manufacturing sites. |
| Geographic Expansion | Captures METI Society 5.0 procurement windows for Bluetooth-enabled remote patient monitoring in rural Japanese prefectures. |
| Product Launch | Introduces carbon accounting modules satisfying CSRD disclosure mandates for European steel and chemicals operators. |
Methodological Framework
Initial hypotheses were tested against primary input from IoT platform engineering directors, enterprise IT procurement officers, channel partner account managers, and regulatory compliance leads at industrial operators, then refined through secondary validation against SEC filings of cloud hyperscalers, ETSI protocol specifications, EU AI Act implementation guidance, and customs data for secure element imports. Bottom-up sensor deployment estimates and top-down enterprise software spending analysis were triangulated to anchor market sizing.
Variance decomposition across deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated LPWAN spectrum allocation timelines, Industrie 4.0 funding program trajectories, and ISO/IEC 27001 certification pipeline velocities.
Forecasts assume regulatory continuity in EU AI Act implementation, FDA cybersecurity guidance, and METI Society 5.0 procurement frameworks; material policy shifts would require re-modeling. Revision becomes warranted when secure element foundry utilization crosses capacity constraint thresholds or GDPR data localization enforcement intensifies beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
IoT in Chemical Industry Market