
 Smart Remote Market | 2026-2036
Smart Remote Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Remote Market Intelligence
The convergence of AI-powered voice assistants with low-power wireless protocols like Zigbee is reshaping product development. Universal Electronics Inc. leverages its extensive patent portfolio in universal control technologies to maintain a strong market position. Logitech International S.A. differentiates through its focus on high-end, multi-device remotes for home theater enthusiasts. Crestron Electronics, Inc. specializes in integrated solutions for high-value commercial and residential automation projects, anchoring its brand in the professional installation channel.
A smart remote is a programmable control device that consolidates command functions for multiple electronic components within a connected ecosystem. These devices utilize connectivity like Wi-Fi and Bluetooth, bypassing the line-of-sight limitations of traditional infrared remotes. While Wi-Fi enabled devices are gaining share for their integration with cloud services, Bluetooth remains a staple for its low power consumption in battery-operated units. The households segment constitutes the largest end-user base, though the commercial spaces category presents a high-margin growth opportunity.
Radio frequency emissions and device interoperability are governed by regulations like the FCC Part 15 rules in the United States and CE marking requirements in Europe. China’s Ministry of Industry and Information Technology (MIIT) also sets standards for wireless device certification, impacting market access for manufacturers. Decisions on which connectivity protocols and voice control platforms to support will determine a product's compatibility and addressable market across different ecosystems.
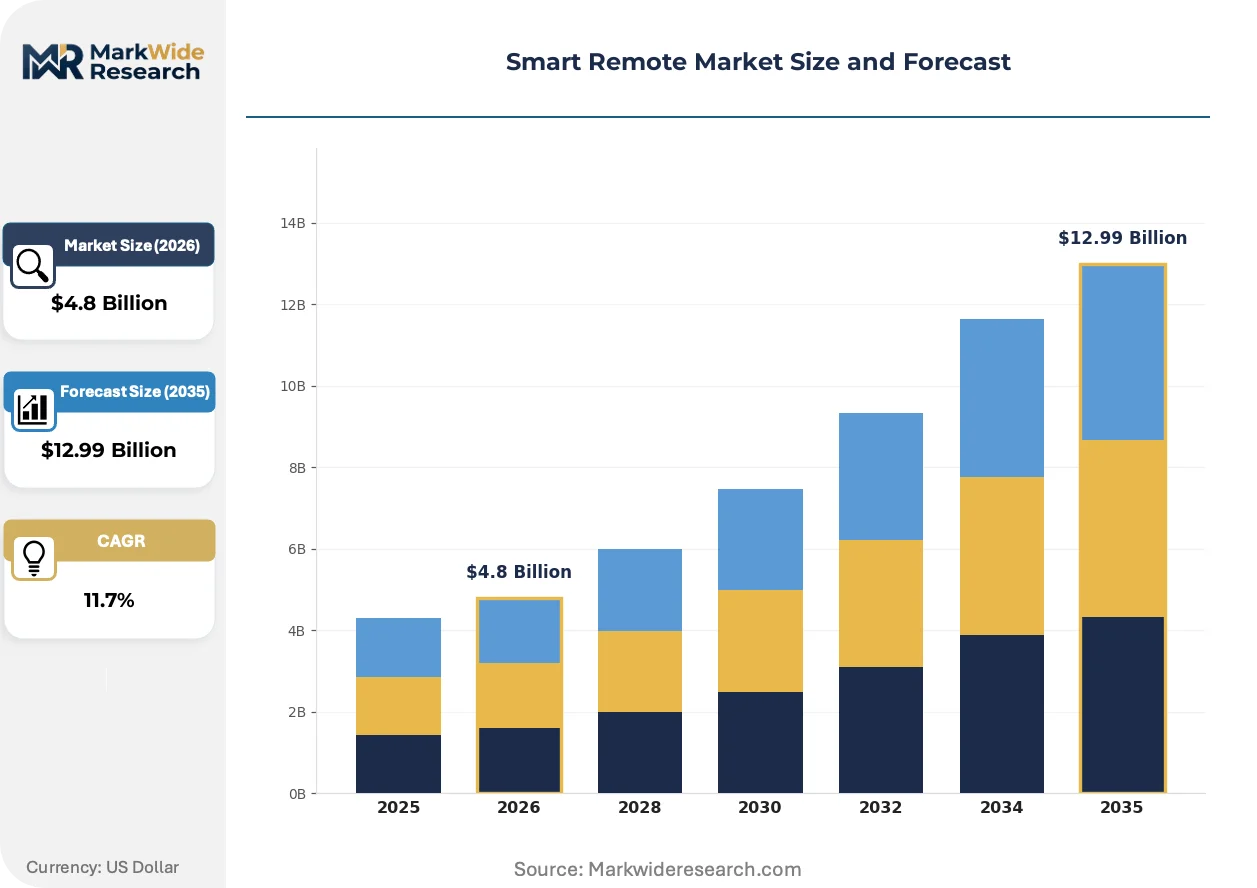
Market Dynamics
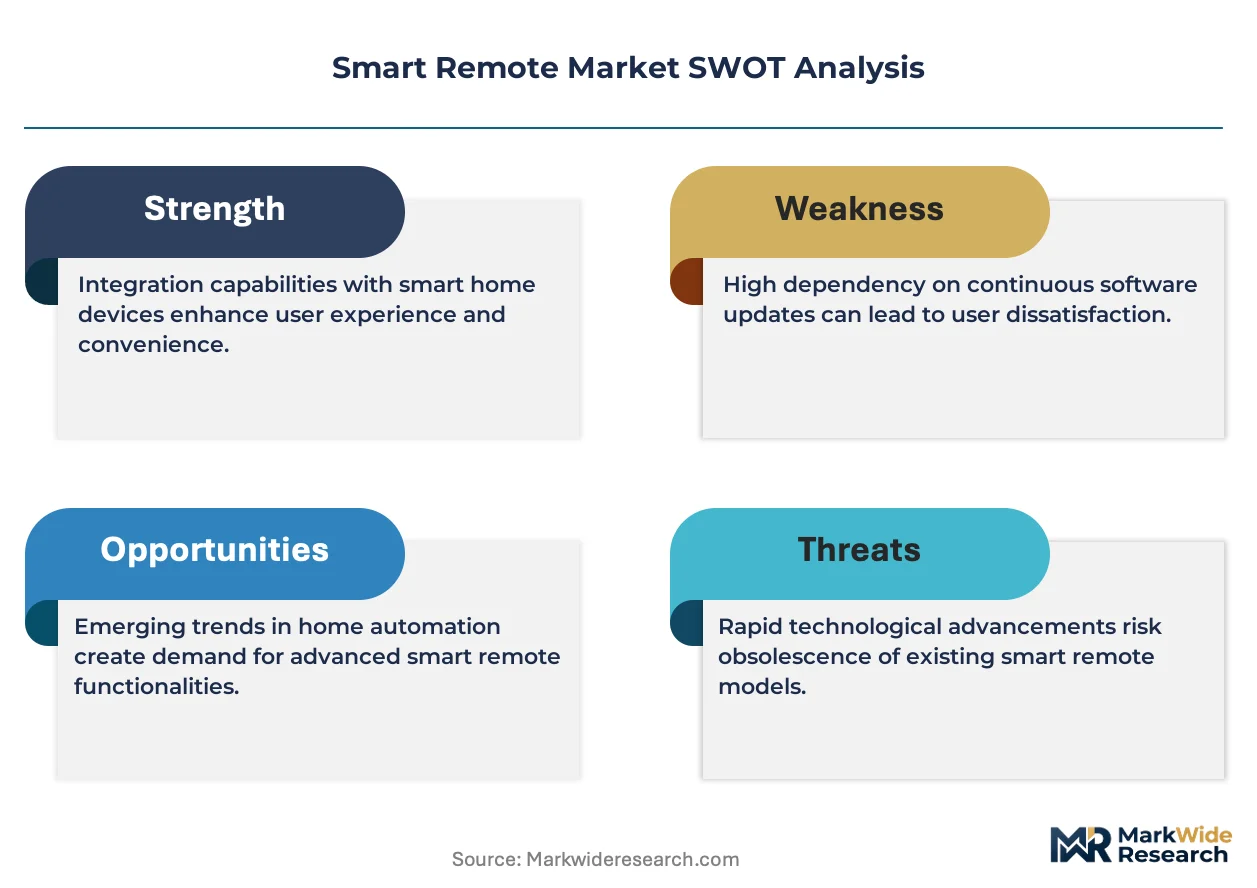
The imperative to deliver seamless interoperability across fragmented smart home and commercial ecosystems is the central force shaping the smart remote market. This dynamic pressures manufacturers to navigate complex alliances, competing wireless protocols, and divergent voice assistant platforms to create a unified user experience.
Growth Catalysts
- Hospitality Sector Integration:Demand from hotels and resorts for streamlined guest experiences, allowing a single device to control room lighting, climate, entertainment, and services, is a significant catalyst for commercial adoption.
- AI-Enabled Voice Control:The integration of sophisticated artificial intelligence for natural language processing enhances user interaction, making voice commands more intuitive and capable of executing complex multi-device routines.
- Smart Home Penetration:Rising adoption of connected devices in households, particularly in major metropolitan areas within the United States and China, expands the underlying addressable market for consolidated control solutions.
Market Restraints
- Interoperability Fragmentation:A lack of a single, universally adopted connectivity standard across device ecosystems like Zigbee, Z-Wave, Wi-Fi, and Bluetooth creates development complexity and consumer confusion.
- Substitution from Smartphone Apps:The availability of dedicated manufacturer apps for individual smart devices on smartphones presents a free and accessible alternative, potentially reducing the perceived need for a separate universal remote.
- Regulatory Compliance Hurdles:Adherence to radio frequency regulations, such as FCC Part 15 in the US and CE marking in Europe, adds cost and time-to-market for new products, acting as a barrier to entry.
Strategic Opportunities
- High-Value Commercial Projects:Targeting integrated automation in corporate boardrooms, educational institutions, and luxury residential projects offers high-margin opportunities for specialized, professionally installed systems.
- Telehealth and Assisted Living:Developing simplified remotes for the elderly or individuals with mobility challenges to control medical devices, communication tools, and home environments represents an underserved market segment.
- Energy Management Features:Incorporating features that allow users to easily monitor and control the energy consumption of connected devices provides a compelling value proposition tied to cost savings and sustainability.
Industry Challenges
- Software Lifecycle Management:Maintaining device compatibility through continuous firmware and software updates across a vast and ever-changing landscape of third-party products presents a significant ongoing operational challenge.
- Data Privacy and Security:As remotes become more connected and integrate voice assistants, ensuring the security of the device and the privacy of user data against potential cyber threats is a critical and complex responsibility.
- Intellectual Property Licensing:Navigating the dense patent landscape for universal control technologies requires significant legal and financial resources, particularly when dealing with established portfolios like that of Universal Electronics Inc.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Remote Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Remotes, Smart Home Remotes, Gaming Remotes, TV Remotes Connectivity: Bluetooth, Wi-Fi, Infrared, Zigbee End User: Households, Commercial Spaces, Hospitality, Education Features: Voice Control, Touchscreen Interface, Mobile App Integration, Macro Functions |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics, Inc., Sony Corporation, Universal Electronics Inc., Crestron Electronics, Inc., Logitech International S.A., Bose Corporation, Koninklijke Philips N.V., Haier Smart Home Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Remote Market Strategic Shifts & Innovations
The evolution of the smart remote is marked by its transition from a simple command device to an intelligent hub for the connected environment. This shift is driven by advancements in low-power processing, sensor integration, and the application of machine learning to personalize user interactions.
Ultra-wideband (UWB) technology is emerging as a key enabler for spatial awareness in premium remotes. This radio technology allows a device to determine its precise location relative to other devices. High-end home theater and smart home segments are beginning to see products with this capability. UWB technology is digitizing the physical context of user commands, enabling "point-and-control" functionality without prior device selection.
China’s Ministry of Industry and Information Technology (MIIT) is enforcing stricter standards for wireless device certification and data security. These regulations impact all manufacturers wishing to access the vast Chinese market, influencing design choices related to connectivity protocols and data handling. Consequently, global brands are adapting their product roadmaps to ensure compliance, sometimes creating region-specific hardware or firmware versions.
A notable behavioral change is the consumer's growing preference for minimalist design and tactile feedback. This pushes manufacturers beyond purely functional considerations, disrupting the dominance of button-heavy layouts. The high-end segment is responding with remotes featuring machined metal bodies, haptic engines for feedback, and configurable e-ink or OLED screens, a trend most visible in the custom integration channel for luxury homes.
Smart Remote Market Segmentation
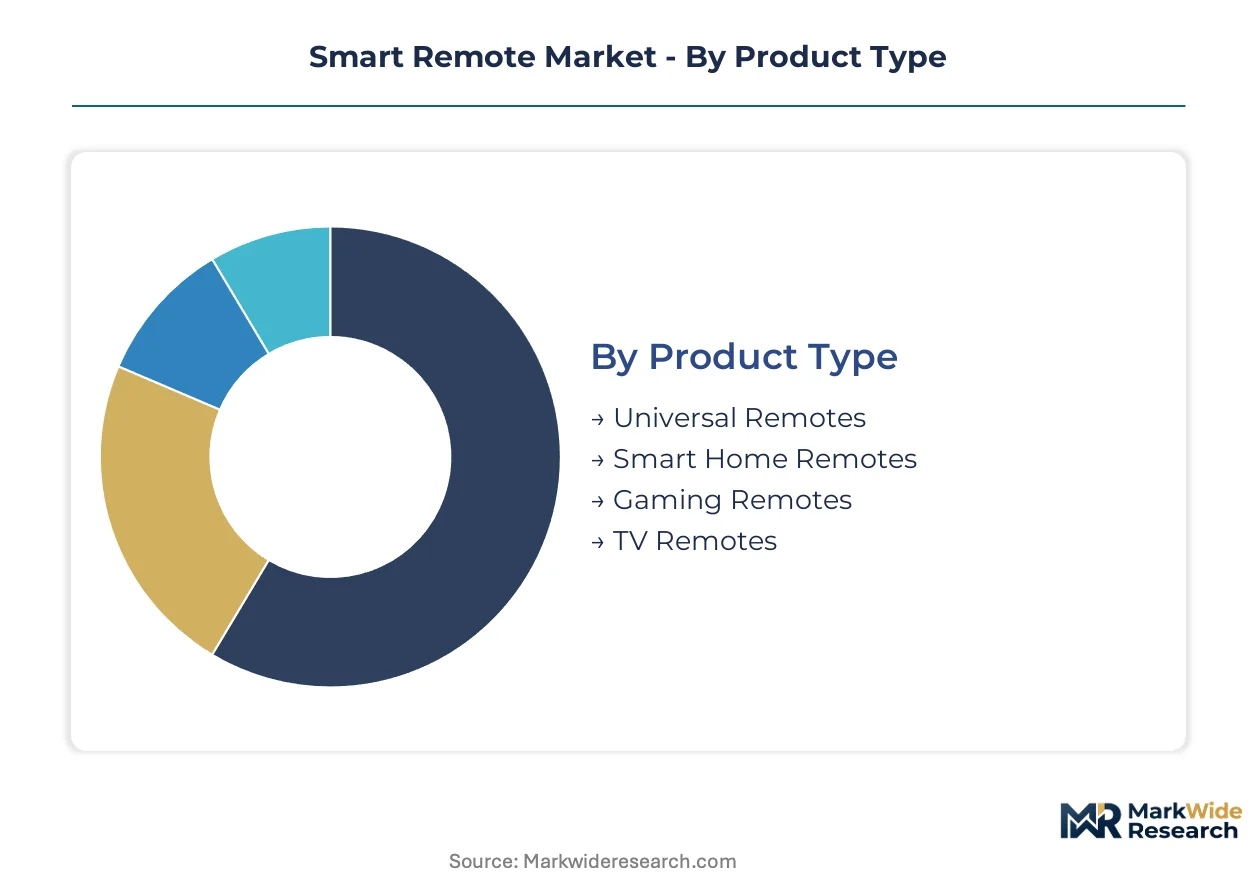
Market segmentation for smart remotes delineates the diverse applications and technological underpinnings that characterize this evolving control device category. Understanding these distinct segments helps manufacturers tailor product development and market strategies to specific user needs and technical requirements.
Product Type:
The intensity of after-sales service requirements often varies significantly across different product types, influencing design complexity and manufacturer support models.
- Universal Remotes:These programmable devices consolidate control for multiple electronic components from various brands, often relying on extensive code libraries and user-friendly setup processes. Demand for these remotes concentrates in households seeking to simplify their entertainment system management in major metropolitan areas like New York and Beijing.
- Smart Home Remotes:Designed specifically to manage connected home ecosystems, these remotes integrate with smart hubs and protocols like Zigbee or Wi-Fi to control lighting, climate, security, and entertainment. Their commercial significance is rising due to increased smart home penetration in regions such as the United States and China.
- Gaming Remotes:Optimized for gaming consoles and PC gaming setups, these remotes feature ergonomic designs, specialized buttons, and often incorporate motion sensing or haptic feedback for immersive experiences.
- TV Remotes:Primarily focused on television control, these devices have evolved from basic infrared models to include voice control, streaming app integration, and smart TV navigation features.
By volume, Universal Remotes lead. By growth pace, Smart Home Remotes are ahead.
Connectivity:
The cost tier of smart remotes often correlates directly with the sophistication and range of their embedded connectivity options.
- Wi-Fi:Enabling direct integration with cloud services and smart home ecosystems, Wi-Fi connectivity facilitates advanced features like remote access and over-the-air firmware updates. Wi-Fi enabled remotes are prevalent in smart home installations across the United States for their robust data capabilities.
- Bluetooth:Valued for its low power consumption and direct device pairing, Bluetooth remains a staple for battery-operated smart remotes, particularly for direct control of media players and set-top boxes. Its adoption is strong in portable devices and for direct pairing with consumer electronics in Europe.
- Infrared:This traditional line-of-sight technology provides backward compatibility with legacy entertainment systems, serving as a foundational element in many hybrid smart remote designs.
- Zigbee:A low-power, mesh networking protocol specifically designed for smart home devices, Zigbee offers reliable communication across a network of connected accessories.
The prevalence of Wi-Fi reflects its integration ease, while Zigbee gains traction for specialized smart home use cases.
End User:
Diverse applications across different end-user segments drive distinct requirements for smart remote functionality and integration.
- Households:This segment represents the largest consumer base, utilizing smart remotes to consolidate control over entertainment systems, smart home devices, and connected appliances. The expansion of smart home ecosystems in countries like the United States and China directly fuels demand from this segment.
- Commercial Spaces:Smart remotes in commercial environments manage integrated AV systems, lighting, and climate control in conference rooms, hotels, and educational facilities. This segment offers high-margin opportunities for customized, professionally installed solutions in corporate settings.
- Hospitality:Hotels and resorts deploy smart remotes to enhance guest experience, allowing control of room amenities from a single device, streamlining operations for staff.
- Education:Educational institutions use smart remotes to manage classroom technology, including projectors, interactive whiteboards, and audio systems, simplifying presentations.
The largest installed base resides in Households, but Commercial Spaces present a significant opportunity for future expansion.
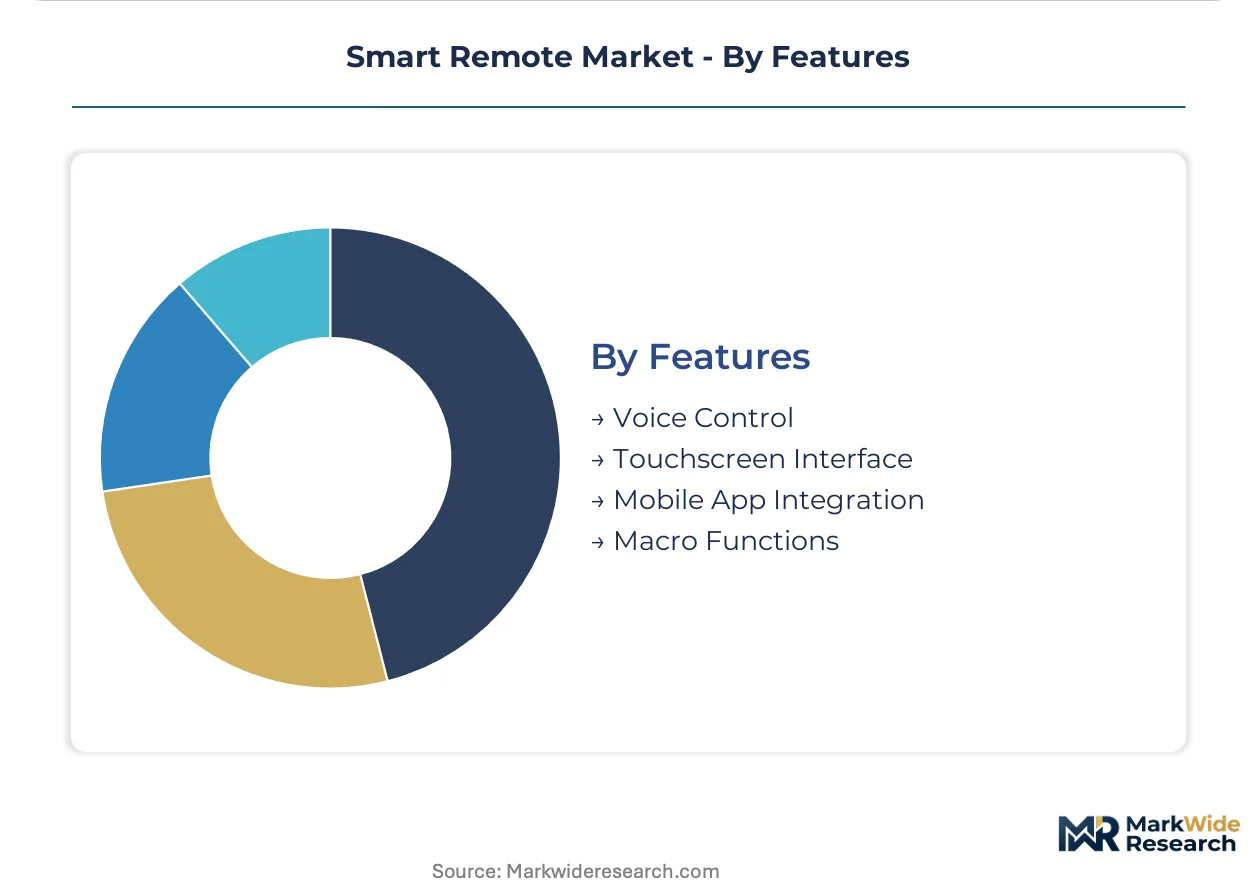
Features:
Different customer types prioritize specific features, influencing the design and marketing of smart remotes.
- Voice Control:Powered by AI and natural language processing, voice control allows users to issue commands verbally, enhancing accessibility and simplifying complex multi-device routines. This feature is becoming a standard expectation for smart remotes in tech-forward markets like the US and China.
- Touchscreen Interface:Providing a dynamic and customizable visual interface, touchscreens allow for intuitive navigation, personalized layouts, and context-aware controls. Premium smart remotes for home theater enthusiasts frequently incorporate advanced touchscreen displays.
- Mobile App Integration:This feature allows smartphones or tablets to function as smart remotes, providing an alternative control interface and often enabling advanced configuration options.
- Macro Functions:Users can program macro functions to execute a sequence of commands with a single button press, automating complex tasks across multiple devices.
User experience is profoundly impacted by Voice Control capabilities, with Mobile App Integration enhancing overall system control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households and commercial spaces represent concentrated buyer archetypes, driving distinct regional demand patterns for smart remotes. Smart home penetration rates and hospitality sector growth significantly influence market expansion in specific metropolitan areas. Regulatory frameworks for wireless devices also shape product development and market access across different geographic regions.
United States
Demand for smart remotes in the United States stems from high smart home penetration and the hospitality sector's need for streamlined guest experiences. FCC Part 15 rules govern radio frequency emissions for all wireless devices, impacting market entry. Major tech hubs like Silicon Valley and metropolitan areas such as New York City drive innovation and early adoption of advanced smart remote technologies.
China
China's vast consumer base and rapid smart home adoption fuel substantial demand for smart remotes, particularly those with AI-enabled voice control. The Ministry of Industry and Information Technology (MIIT) sets stringent standards for wireless device certification and data security. The Yangtze River Delta region, including cities like Shanghai and Hangzhou, acts as a key manufacturing and innovation cluster for smart home devices.
Germany
High-value commercial projects and a strong focus on energy management features define the smart remote market in Germany. CE marking requirements ensure products meet European health, safety, and environmental protection standards. Industrial centers such as Munich and Stuttgart lead in implementing integrated automation solutions for corporate and luxury residential sectors.
Japan
The Japanese market prioritizes minimalist design, tactile feedback, and applications in telehealth and assisted living for smart remotes. JIS standards (Japanese Industrial Standards) guide product quality and interoperability. Tokyo and Osaka serve as central hubs for consumer electronics innovation and the integration of smart remote technology into advanced home entertainment systems.
Smart Remote Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for smart remotes. The landscape includes established electronics manufacturers and specialized smart home solution providers. Strategic archetypes range from universal control experts to integrated automation specialists. Competitive moves frequently involve technology licensing and strategic partnerships to ensure interoperability across diverse ecosystems.
Universal Electronics Inc. represents players with extensive patent portfolios in universal control technologies, maintaining a strong market position through intellectual property. Logitech International S.A., a Swiss-based S.A., exemplifies companies focusing on high-end, multi-device remotes tailored for home theater enthusiasts. Crestron Electronics, Inc., a US-based Inc., anchors the segment specializing in integrated solutions for high-value commercial and residential automation projects, leveraging professional installation channels.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics, Inc. |
| Sony Corporation |
| Universal Electronics Inc. |
| Crestron Electronics, Inc. |
| Logitech International S.A. |
| Bose Corporation |
| Koninklijke Philips N.V. |
| Haier Smart Home Co., Ltd. |
| Others |
Cost & Logistics Intelligence
China’s MIIT certification requirements, a significant regulatory chokepoint, directly influence both smart remote pricing tiers and global supply chain configurations. Compliance costs and localized design efforts shape market access and product availability.
Pricing Analysis
Cost-plus contract patterns, often with component cost indexation, define pricing for integrated smart remote solutions. Advanced features like Ultra-wideband technology and customizable OLED screens drive premium pricing. Brand recognition from companies like Logitech and Crestron also commands higher price points. Pricing pressure stems from the free substitution offered by smartphone apps. Households exhibit high price sensitivity, while commercial and hospitality sectors prioritize functionality and integration, showing lower sensitivity.
Supply Chain Analysis
Contract manufacturing concentration in key Asian EMS providers, particularly those operating in China, underpins smart remote production. China and Vietnam serve as primary manufacturing hubs for electronic components. The supply chain relies on a stable flow of microcontrollers, advanced sensors, and specialized display panels. Geopolitical tensions and logistics chokepoints present a structural risk to component availability. Distribution runs through both direct-to-consumer retail channels and specialized professional installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart remote market is experiencing a cyclical recovery, driven by renewed consumer investment in smart home ecosystems. This resurgence creates strategic imperatives for market participants across all tiers.
For Market Incumbents: Entrench core market share by continuously expanding patent portfolios in universal control technologies. Deepen integration with leading AI-enabled voice control platforms to mitigate substitution from smartphone apps. Invest in R&D for advanced spatial awareness technologies like Ultra-wideband. Leverage existing professional installation channels, particularly in high-value commercial projects, to maintain brand loyalty against new entrants.
For New Entrants and Emerging Players: Establish a beachhead in underserved market segments, such as telehealth and assisted living. Develop simplified smart remotes tailored for the elderly or individuals with mobility challenges. Integrate energy management features to appeal to sustainability-conscious consumers. Partner with healthcare providers and assisted living facilities for direct channel access and specialized product validation.
For Investors and Strategic Acquirers: Niche software developers specializing in smart home interoperability and voice control integration represent attractive acquisition targets. The market offers long-term viability as smart homes become more prevalent, requiring sophisticated control interfaces. Companies with strong intellectual property in low-power wireless protocols or advanced user interface design are also valuable. A signal to watch is the increasing adoption of a unified connectivity standard across major smart home platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand AI-enabled Voice Control Integration | Enhances user interaction and enables complex multi-device routines, appealing to tech-forward households. |
| Develop Ultra-wideband (UWB) Spatial Awareness | Enables "point-and-control" functionality in premium remotes, digitizing physical context for advanced home theater users. |
| Target Telehealth and Assisted Living Segments | Addresses an underserved market by providing simplified control for medical devices and home environments. |
| Secure MIIT Wireless Certification | Ensures market access to China's vast consumer base, influencing product design and connectivity protocol choices. |
| Form Cross-Platform Interoperability Alliances | Mitigates market fragmentation and reduces consumer confusion across diverse smart home ecosystems like Zigbee and Wi-Fi. |
Research Approach
Cross-validation between in-depth primary interviews and extensive secondary research anchors the qualitative findings. Interviews included smart home device manufacturers, hospitality technology managers, professional AV integrators, and consumer electronics retailers. Secondary data sources comprised regulatory filings (FCC, MIIT), industry association reports, and financial disclosures of public companies. A combination of bottom-up market sizing and top-down validation ensured robust data integrity.
Forecasts were calibrated using a multi-factor analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, connectivity, end user, features, and geography. Compound annual growth rates were derived through regression analysis, reflecting anticipated market share shifts and technology adoption curves. Key industry-specific forecast inputs included smart home penetration rates and hospitality sector technology investment.
Sensitivities concentrate around unforeseen regulatory changes and rapid technological shifts in connectivity standards. Forecasts reflect documented assumptions regarding smart home adoption and consumer electronics trends. Quarterly review of connectivity standard evolution and smart home penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market