
 Global IOT Connectivity Management Platform (CMP) Market | 2026-2036
Global IOT Connectivity Management Platform (CMP) Market Size, Share, and Industry Trends Forecast 2026-2036
Global IOT Connectivity Management Platform (CMP) Market Foresight
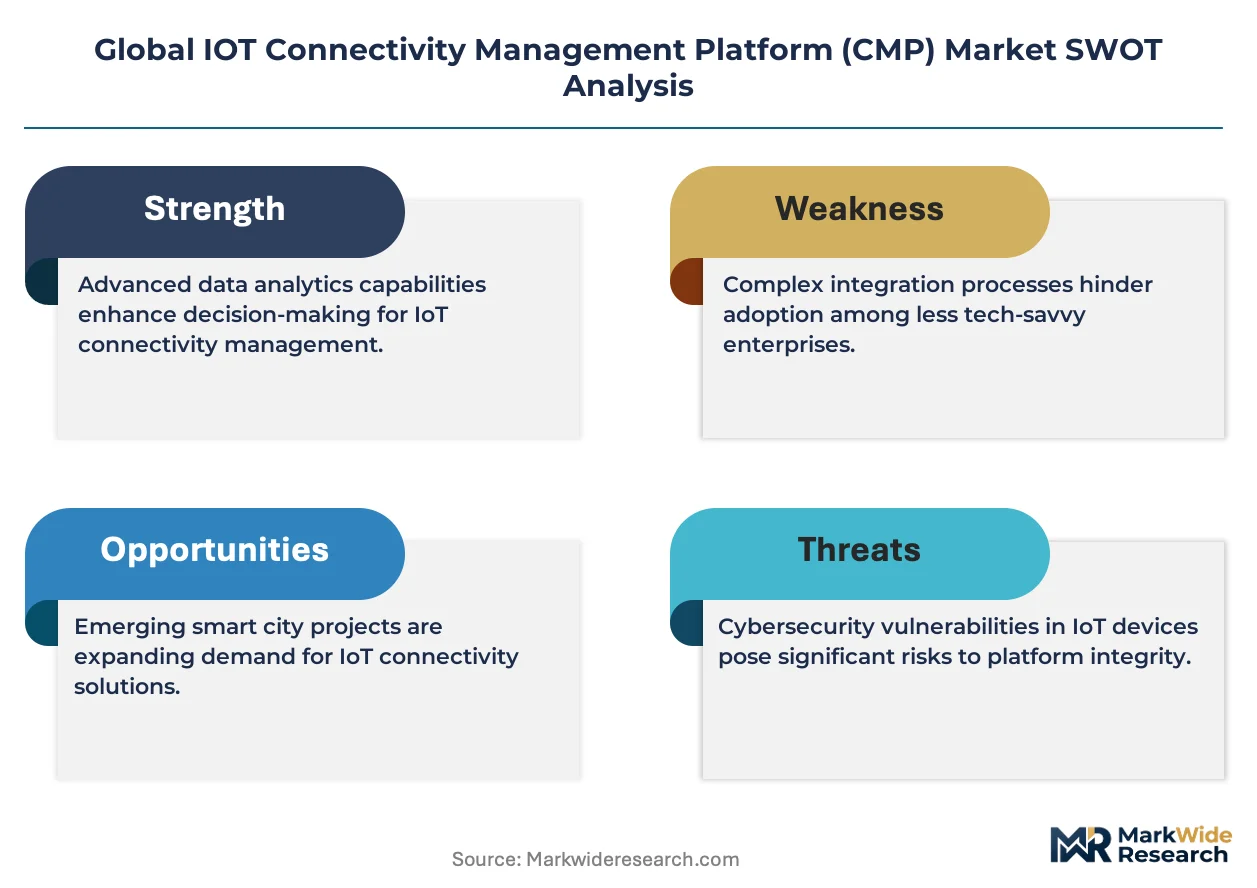
Subscription-based platform licensing and managed connectivity services are reconfiguring capital requirements for new entrants, lowering the barrier to serve mid-market industrial accounts. Microsoft Corporation leverages its Azure cloud footprint to anchor large enterprise deployments across manufacturing and energy verticals. Cisco Systems Inc. specializes in network orchestration layers that integrate with existing enterprise infrastructure. Huawei Technologies Co Ltd. dominates in telecommunications operator partnerships across Asia, the Middle East, and Africa.
An IoT Connectivity Management Platform is a software layer that provisions, monitors, and optimizes cellular or satellite connections across distributed device estates, typically supporting protocols including MQTT, CoAP, and LwM2M with real-time diagnostics down to the SIM or eSIM profile level. Its primary commercial purpose is to reduce operational complexity and connectivity spend for organizations operating thousands to millions of connected endpoints. Cloud-based deployment leads in new contract volume due to faster onboarding and elastic scaling, though hybrid cloud configurations are capturing margin-rich deals from financial services and defense-adjacent industrials requiring data sovereignty. Network orchestration and security management represent the fastest-expanding solution offerings as edge computing architectures multiply attack surfaces and connectivity paths.
The U.S. Federal Communications Commission shapes spectrum allocation and device certification timelines that directly influence CMP feature roadmaps for North American deployments. The European Union's Cyber Resilience Act and existing GDPR frameworks mandate breach notification automation and data residency controls that platform vendors must architect around. China's Ministry of Industry and Information Technology enforces domestic cloud localization and encryption standards that constrain how foreign CMP providers operate within its borders. Stakeholders should monitor evolving eSIM remote provisioning standards and national data-localization statutes as these will determine which platform architectures can scale across jurisdictions without costly re-engineering.
Market Dynamics
The eSIM remote provisioning standard is compressing hardware refresh cycles and forcing platform vendors to re-architect subscriber identity management for zero-touch onboarding at scale.
Growth Catalysts
- EU AI Act:Automated governance tooling embedded in CMP stacks creates compliance differentiation for vendors serving European automotive and industrial conglomerates.
- Fleet telematics:Logistics operators in Germany and the United States are consolidating multi-national device estates onto unified dashboards as cellular LPWAN coverage widens.
- Edge computing architectures:Distributed compute nodes multiply connectivity paths and attack surfaces, expanding attach rates for network orchestration modules.
Market Restraints
- Input cost volatility:Semiconductor shortages in Taiwan and South Korea constrain eSIM and secure element supply for high-volume deployments.
- Regulatory friction:China's MIIT enforces domestic cloud localization and encryption standards that fragment platform architectures for foreign providers.
- Technical limitation:Interoperability gaps between proprietary carrier APIs delay multi-network failover implementations.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA medical device tracking mandates create first-mover openings for CMP vendors with healthcare compliance modules.
- Technology convergence:Satellite-to-cellular handoff protocols are hybridizing with terrestrial LPWAN to serve maritime and remote agriculture use cases.
- Regulatory tailwind:India's PLI scheme for electronics manufacturing incentivizes domestic CMP hosting infrastructure for industrial IoT.
Industry Challenges
- Skill scarcity:Embedded systems security expertise lags demand for firmware-level diagnostics across heterogeneous device estates.
- Certification timelines:FCC and CE marking cycles for new radio modules extend 14-18 months, delaying platform feature rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IOT Connectivity Management Platform (CMP) Market |
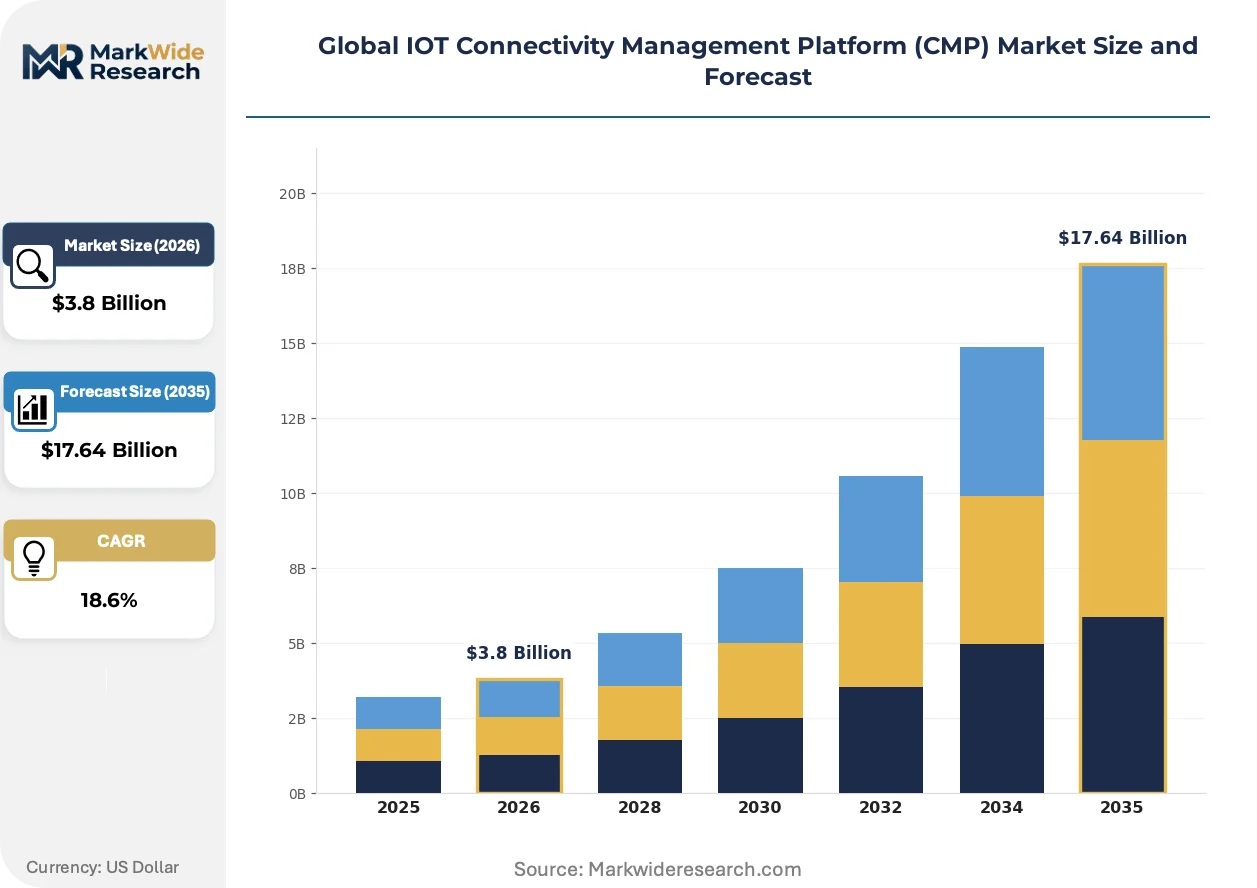
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid Cloud, Edge Deployment Solution Offering: Device Management, Network Orchestration, Security Management, Data Analytics, Billing & Monetization Use Case: Smart Cities, Connected Vehicles, Industrial Automation, Smart Metering, Asset Tracking End User Industry: Telecommunications, Manufacturing, Energy & Utilities, Transportation, Agriculture |
| Companies Covered | Google LLC, Microsoft Corporation, Amazon Web Services Inc., Cisco Systems Inc., Huawei Technologies Co Ltd., Telefonaktiebolaget LM Ericsson, Aeris Communications Inc., Verizon, Telefonica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IOT Connectivity Management Platform (CMP) Market Shifts & Advancements
Platform architectures are fragmenting across sovereignty requirements while automation layers compress operational headcount for connectivity operations.
Zero-touch eSIM orchestration is hybridizing subscriber lifecycle management with identity federation protocols. Automotive OEMs in Germany and fleet operators in the United States are adopting these stacks for million-unit estates within 18-month procurement windows. The technology is hybridizing hardware margins into recurring software revenue streams.
GDPR breach notification automation is reshaping data residency controls in European deployments. Platform vendors must architect real-time audit trails and cross-border transfer mechanisms. Financial services and defense-adjacent industrials in Switzerland and France are driving demand for hybrid cloud configurations.
Consumption-based pricing for connectivity is displacing fixed-rate contracts in mid-market industrial accounts. System integrators and managed service providers are capturing margin by unbundling platform licenses from carrier connectivity. This pattern is most visible in German manufacturing conglomerates consolidating multi-site IoT estates.
Global IOT Connectivity Management Platform (CMP) Market Segmentation
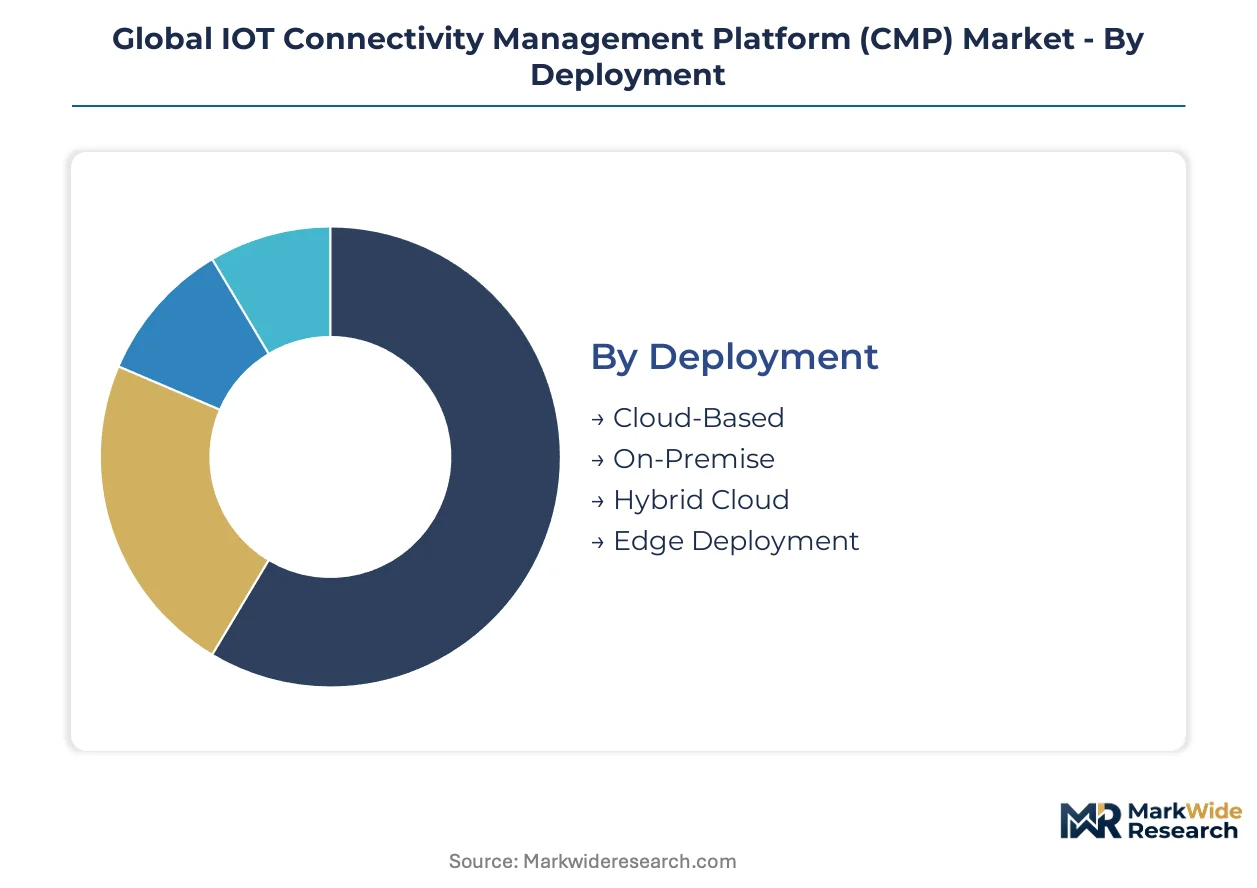
IoT Connectivity Management Platform architectures diverge sharply across deployment topologies and solution stacks, with each configuration demanding distinct integration intensity and recurring service commitments. Platform vendors calibrate their professional services and support models to the operational complexity inherent in each segment, creating tiered margin structures that reward deep technical engagement.
Deployment:
After-sales service intensity varies dramatically across deployment modes, with cloud-native implementations requiring continuous platform updates and security patching while on-premise estates demand dedicated field engineering support.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic scaling through hyperscaler infrastructure, with Microsoft Azure and AWS hosting the majority of new enterprise contracts. German automotive OEMs and U.S. energy utilities are migrating million-device estates to these stacks to compress onboarding timelines and eliminate data center capital expenditure.
- Hybrid Cloud:Split architectures partition sensitive workloads on-premise while routing telemetry through public cloud analytics layers. Swiss financial services and French defense-adjacent industrials mandate these configurations to satisfy GDPR data residency and national security requirements.
- On-Premise:Air-gapped installations serve critical infrastructure operators in China's energy sector under MIIT localization mandates, requiring captive support teams and custom firmware maintenance.
- Edge Deployment:Distributed compute nodes at cell towers and factory floors enable sub-50ms latency for autonomous vehicle telemetry and robotic control systems.
By volume, Cloud-Based leads. By growth pace, Hybrid Cloud is expanding most quickly as sovereignty requirements harden across European and Asian jurisdictions.
Solution Offering:
Cost tier stratification separates commodity device management modules from premium security and orchestration capabilities that command per-device pricing multiples.
- Network Orchestration:Dynamic carrier switching and multi-IMSI failover engines automate connectivity path optimization across heterogeneous radio access networks. Fleet operators in Germany and logistics providers in the United States attach these modules to eliminate roaming dead zones across transcontinental routes.
- Security Management:Firmware attestation, certificate lifecycle automation, and zero-trust microsegmentation protect edge attack surfaces multiplied by distributed compute architectures. Critical infrastructure operators in Saudi Arabia and UAE mandate these capabilities under national cybersecurity frameworks.
- Device Management:Remote diagnostics, over-the-air updates, and eSIM profile provisioning form the baseline platform layer.
- Data Analytics:Consumption metering and predictive connectivity quality scoring enable outcome-based pricing models.
- Billing & Monetization:Multi-tenant rating engines allow carriers and MVNOs to resell connectivity with custom tariff structures.
By revenue concentration, Network Orchestration dominates new contract value. By attach rate acceleration, Security Management is gaining share fastest as edge computing architectures proliferate.
Use Case:
Application maturity determines whether platforms deliver standardized tooling or require heavy customization for protocol translation and regulatory compliance.
- Connected Vehicles:Automotive-grade platforms must satisfy UN ECE R155 cybersecurity regulations and support million-unit eSIM provisioning at assembly line speed. German OEMs and U.S. electric vehicle manufacturers are consolidating telematics stacks onto unified dashboards as cellular LPWAN coverage widens.
- Industrial Automation:Time-sensitive networking integration and OPC-UA protocol bridging connect legacy programmable logic controllers to cloud analytics. Manufacturing conglomerates in Germany and Japan demand these capabilities for predictive maintenance across multi-site estates.
- Smart Cities:Street lighting and waste management deployments aggregate thousands of low-bandwidth sensors under municipal procurement frameworks.
- Smart Metering:Regulatory mandates from India's CEA and EU member state directives drive AMI platform standardization.
- Asset Tracking:Satellite-to-cellular handoff protocols serve maritime containers and remote agriculture equipment.
By deployment scale, Smart Metering leads in endpoint count. By platform spend per device, Connected Vehicles commands the steepest expansion trajectory.
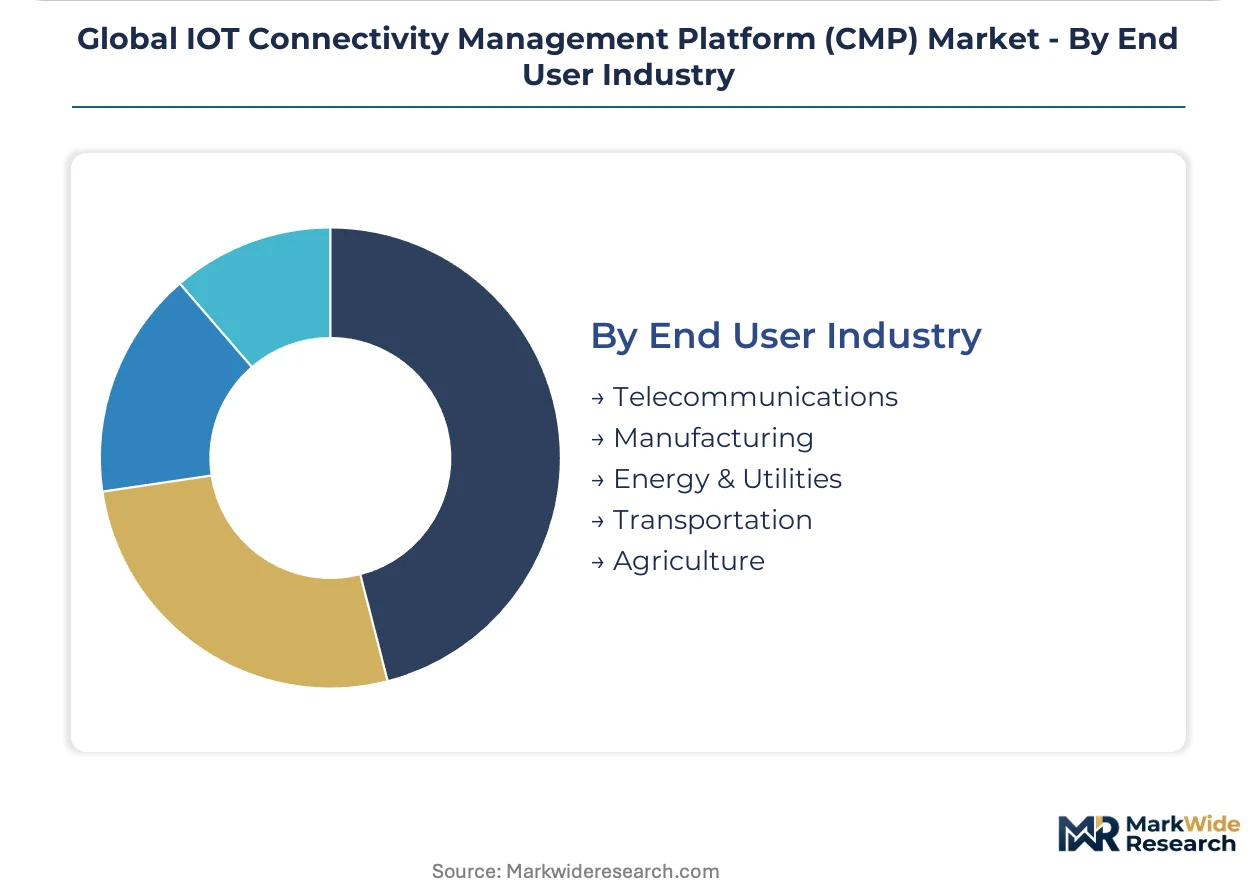
End User Industry:
Customer type differentiation separates carrier-grade platforms with wholesale billing capabilities from industrial stacks optimized for OT-IT convergence.
- Telecommunications:Mobile network operators require multi-tenant architectures with white-label portals for enterprise sub-branding. Huawei Technologies dominates these partnerships across Asia, the Middle East, and Africa.
- Manufacturing:Discrete and process industries demand protocol adapters for brownfield equipment and digital twin integration. German industrial conglomerates are consolidating multi-national IoT estates onto unified CMP dashboards.
- Energy & Utilities:Grid operators and oilfield services companies mandate IEC 61850 and DNP3 protocol support with disaster recovery guarantees.
- Transportation:Fleet operators and rail infrastructure managers prioritize real-time route optimization and regulatory compliance logging.
- Agriculture:Precision farming deployments in Brazil and Australia combine satellite connectivity with soil sensor networks for irrigation automation.
By contract volume, Telecommunications leads. By platform customization depth, Manufacturing is climbing the fastest as Industry 4.0 investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's PLI scheme for electronics manufacturing and the EU AI Act's compliance mandates are redirecting platform procurement toward vendors with embedded governance tooling. National data-localization statutes in China and India's CEA directives for smart metering are fragmenting deployment architectures across jurisdictions.
United States
Fleet operators across logistics and transportation are consolidating multi-national device estates onto unified dashboards as cellular LPWAN coverage widens. The FCC shapes spectrum allocation and device certification timelines that directly influence CMP feature roadmaps. California-based automotive OEMs and Texas energy utilities are migrating million-device estates to cloud-native stacks to compress onboarding timelines.
Germany
Automotive OEMs and industrial conglomerates are consolidating multi-national IoT estates onto unified CMP dashboards. The EU AI Act and emerging device certification requirements are prompting platform vendors to embed governance tooling directly into their stacks. Baden-Württemberg's manufacturing clusters and Bavaria's automotive corridors command the steepest platform spend per device in Europe.
China
MIIT enforces domestic cloud localization and encryption standards that constrain how foreign CMP providers operate within its borders. The ministry's dual carbon goals accelerate smart metering and industrial automation deployments. Yangtze River Delta electronics manufacturers and Pearl River Delta telecom equipment hubs anchor captive platform development for domestic supply chains.
India
The PLI scheme for electronics manufacturing incentivizes domestic CMP hosting infrastructure for industrial IoT. CEA mandates for smart metering drive AMI platform standardization across state distribution companies. Karnataka's Bengaluru tech corridor and Gujarat's industrial zones are capturing first-mover investments in sovereign cloud deployments.
Brazil
ANVISA medical device tracking mandates create first-mover openings for CMP vendors with healthcare compliance modules. Precision farming deployments in São Paulo and Minas Gerais combine satellite connectivity with soil sensor networks for irrigation automation. The country's national pharmaceutical regulator is expanding traceability requirements beyond medical devices into agricultural supply chains.
Global IOT Connectivity Management Platform (CMP) Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability layers: hyperscaler cloud infrastructure, telecommunications operator partnerships, and specialized network orchestration software. Cloud-native vendors anchor enterprise deployments through elastic scaling and rapid onboarding, while telecom-aligned providers capture wholesale connectivity relationships. The dominant competitive moves involve strategic partnerships between platform vendors and mobile network operators, plus portfolio diversification into edge security modules.
Within the hyperscaler tier, Microsoft Corporation and Amazon Web Services Inc. exemplify cloud-native platform anchoring for manufacturing and energy verticals. Huawei Technologies Co Ltd. occupies a position within telecommunications operator partnerships across Asia, the Middle East, and Africa. Cisco Systems Inc. represents the network orchestration specialist archetype, integrating with existing enterprise infrastructure.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Amazon Web Services Inc. |
| Cisco Systems Inc. |
| Huawei Technologies Co Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Aeris Communications Inc. |
| Verizon |
| Telefonica |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwan and South Korea semiconductor foundries is compressing margins for secure element and eSIM component suppliers, forcing platform vendors to absorb input cost volatility while maintaining subscription pricing discipline for enterprise accounts.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with GDPR-compliant and UN ECE R155-certified stacks commanding per-device premiums over baseline device management modules. Subscription-based SaaS licensing dominates new contracts, though consumption-based metering is gaining traction among mid-market industrial buyers. Price differentiation stems from security module depth and geographic data residency guarantees. German automotive OEMs exhibit lowest price sensitivity due to compliance mandates, while Brazilian agricultural operators drive hardest bargain negotiations.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing and Samsung Foundry for secure element silicon, plus Foxconn and Jabil for gateway hardware assembly. Component sourcing draws from South Korea for memory, Japan for precision analog chips, and China for PCB substrates. Single-source vulnerability around advanced node secure elements creates exposure to geopolitical export controls. Distribution runs through hyperscaler marketplaces and direct carrier partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and U.S. energy utilities consolidating million-device estates, compressing vendor margins and privileging platforms with embedded governance tooling.
For Market Incumbents: Entrench through backward integration into eSIM secure element supply and captive development of zero-touch orchestration stacks. Deepen certification investment for EU AI Act and UN ECE R155 compliance to defend against emerging cloud-native entrants. Prioritize hybrid cloud configurations for Swiss financial services and French defense-adjacent industrials where data sovereignty commands pricing premiums. For New Entrants and Emerging Players: Pursue whitespace in Brazil's ANVISA medical device tracking mandates and India's PLI-scheme industrial IoT hosting infrastructure. Brazil's healthcare compliance module gap offers lowest competitive density among major economies. Lead with satellite-to-cellular handoff protocols for maritime and remote agriculture use cases where incumbent platforms lack specialized protocol support. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment segments as hyperscaler infrastructure commoditizes compute layers. Long-term viability favors vendors with telecommunications operator partnership density and embedded security module attach rates. Target acquisition archetype: network orchestration specialists with carrier API integration depth. Monitor eSIM remote provisioning standard adoption velocity as inflection indicator for platform architecture obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Touch eSIM Orchestration | Automates million-unit provisioning for German automotive OEMs at assembly line speed. |
| Hybrid Cloud Sovereignty Configuration | Captures GDPR-mandated deals from Swiss financial services and French defense industrials. |
| Telecommunications Operator Partnership | Locks in wholesale connectivity relationships across Asia, Middle East, and Africa markets. |
| Edge Security Module Development | Addresses attack surface multiplication from distributed compute architectures in industrial automation. |
| Satellite-to-Cellular Protocol Integration | Enables maritime and remote agriculture use cases beyond terrestrial LPWAN coverage limits. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, carrier partnership announcements, and regulatory dockets from FCC, EU AI Act implementation bodies, and China's MIIT. Primary interviews engaged platform engineering directors, telecommunications procurement leads, automotive telematics executives, and industrial IoT operations managers. Secondary validation drew from GSMA eSIM specification documents, ISO/IEC 27001 certification registries, and customs trade data for secure element imports. Bottom-up device deployment estimates triangulate against top-down connectivity spend reported by major enterprise accounts.
Forecast inputs incorporate deployment topology adoption curves, solution module attach rate trajectories, and use case penetration patterns across connected vehicles, industrial automation, and smart metering segments. Modeled dimensions span cloud-native versus hybrid cloud versus on-premise configurations, network orchestration and security management solution tiers, and end user industry verticals. CAGRs derive from elasticity-adjusted pricing models and replacement cycle compression from eSIM adoption. Industry-specific inputs include FCC spectrum allocation timelines and EU Cyber Resilience Act implementation phases.
Sensitivities concentrate around semiconductor supply disruption from Taiwan Strait geopolitics, eSIM standard interoperability delays, and national data-localization statute proliferation fragmenting platform architectures. Forecasts embed assumptions regarding cellular LPWAN coverage expansion rates and regulatory compliance automation requirements. Quarterly review of MIIT localization enforcement intensity, ANVISA mandate expansion scope, and PLI scheme disbursement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market