
 Consumer IoT Market | 2026-2036
Consumer IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer IoT Market Intelligence
Home automation energy management is restructuring the Consumer IoT demand profile as residential buyers prioritize utility cost reduction and grid-responsive appliances. Amazon leverages its Alexa ecosystem to control smart speaker penetration and subscription attach rates. Samsung Electronics anchors global volume through vertical manufacturing of home automation systems and Thread-compatible appliances. Xiaomi competes on manufacturing scale, flooding entry-level wearable devices and smart appliances across price-sensitive Asian and European markets.
Consumer IoT comprises networked sensors, actuators, and edge computing modules embedded in residential and personal-use products, typically operating on sub-gigahertz or 2.4 GHz wireless protocols with power budgets under one watt and cloud-backed analytics for real-time user feedback. Smart speakers and home automation systems occupy the mature margin pool, where brand loyalty and platform lock-in protect pricing. Wearable devices represent the fastest-expanding segment, driven by health monitoring applications and clinical-grade sensor miniaturization. Wi-Fi and Thread dominate connectivity architecture, while Zigbee faces displacement as Matter protocol adoption simplifies cross-brand interoperability.
The EU AI Act and GDPR impose algorithmic transparency and data-localization mandates on voice assistants and health-monitoring wearables sold in Europe, forcing architecture redesigns. The FCC in the United States regulates spectrum allocation for Wi-Fi and Bluetooth IoT radios, while China's MIIT enforces GB standards on wireless transmission power and cybersecurity for domestic and exported devices. Stakeholders must monitor regulatory divergence between Brussels, Washington, and Beijing, as compliance fragmentation threatens platform economics and cross-border data flows.
Market Dynamics
Protocol unification around Matter is compressing hardware differentiation and forcing ecosystem consolidation as cross-brand interoperability becomes the baseline purchase criterion for smart home buyers.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for voice assistants and health wearables sold in Europe are accelerating architecture investments that improve consumer trust and reduce churn.
- Smart grid-responsive appliances:Residential buyers in Germany and California prioritize utility-integrated energy management systems that automate load shifting during peak pricing windows.
- Clinical-grade sensor miniaturization:Advances in photoplethysmography and bioimpedance analysis are expanding wearable applications from fitness tracking into preventive health monitoring.
Market Restraints
- Silicon supply concentration:Advanced node chip fabrication for edge AI processors remains concentrated in Taiwan, exposing device makers to geopolitical disruption risk.
- GDPR data-localization costs:EU-mandated regional cloud infrastructure for health data processing adds fixed operational overhead that compresses margins on sub-$100 devices.
- Sub-gigahertz spectrum fragmentation:Incompatible regional frequency allocations for Z-Wave and proprietary protocols force hardware variants that dilute manufacturing scale economies.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for semiconductor assembly and testing are attracting module manufacturers seeking alternative supply origins to China.
- Ambient computing convergence:Integration of radar-based presence sensing with voice interfaces enables proactive device activation without explicit user commands.
- Energy-as-a-service models:Utility partnerships for financed home battery and solar inverter installations create recurring revenue streams beyond hardware margins.
Industry Challenges
- Matter certification timelines:Multi-vendor interoperability testing extends product launch cycles by four to six months, compressing revenue recognition windows.
- Embedded systems security talent scarcity:Shortage of firmware engineers with cryptographic implementation expertise delays secure boot and over-the-air update deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer IoT Market |
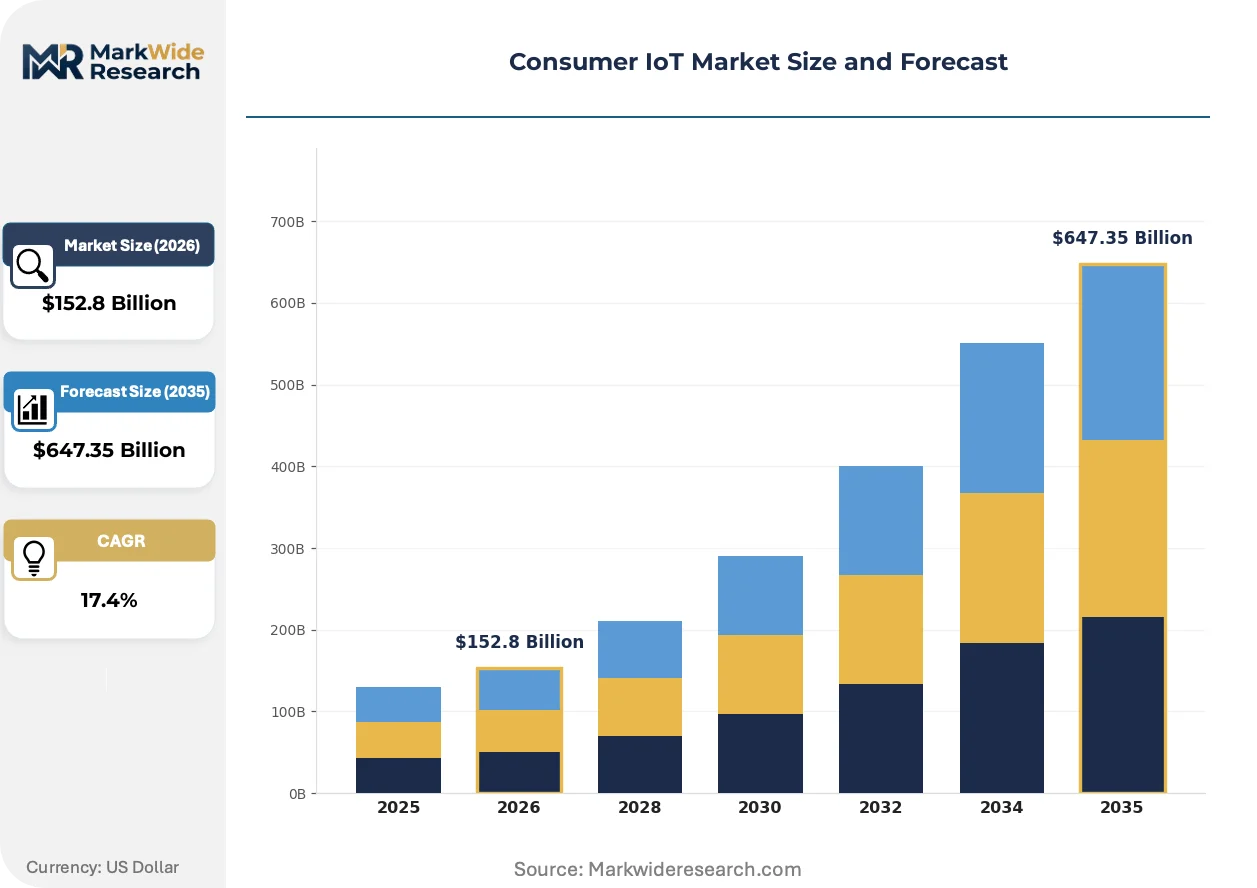
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $647.35 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Wearable Devices, Home Automation Systems, Smart Appliances Technology: Wi-Fi, Bluetooth, Zigbee, Thread End User: Residential, Retailers, Hospitality, Healthcare Application: Energy Management, Security & Surveillance, Health Monitoring, Personal Assistance |
| Companies Covered | Amazon, Google, Apple, Samsung Electronics, Huawei, Philips, Xiaomi, Intel, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer IoT Market Strategic Shifts & Innovations
Connectivity architecture is consolidating around unified protocols while regulatory pressure on algorithmic systems intensifies, and procurement patterns shift toward platform-locked subscription bundles.
Thread is overtaking Zigbee as the dominant mesh networking layer for battery-powered sensors and smart locks. Nordic Semiconductor and Silicon Labs are shipping Thread-native radio modules at volume, enabling OEMs to reduce SKU complexity. This protocol consolidation is overtaking the historical fragmentation that forced consumers into single-brand ecosystems.
Brussels is tightening enforcement of GDPR's automated decision-making provisions against health-monitoring wearables that infer medical conditions without human review. Device makers must now embed explainability interfaces and consent workflows that increase firmware footprint. European consumers are responding by favoring brands with explicit data portability commitments.
Residential buyers are consolidating purchases around voice-assistant platforms that bundle hardware discounts with subscription services. Amazon and Google are capturing lifetime value through energy management and security monitoring add-ons. This behavior is most pronounced in US metropolitan markets where utility rebate programs require platform-specific interoperability certifications.
Consumer IoT Market Segmentation
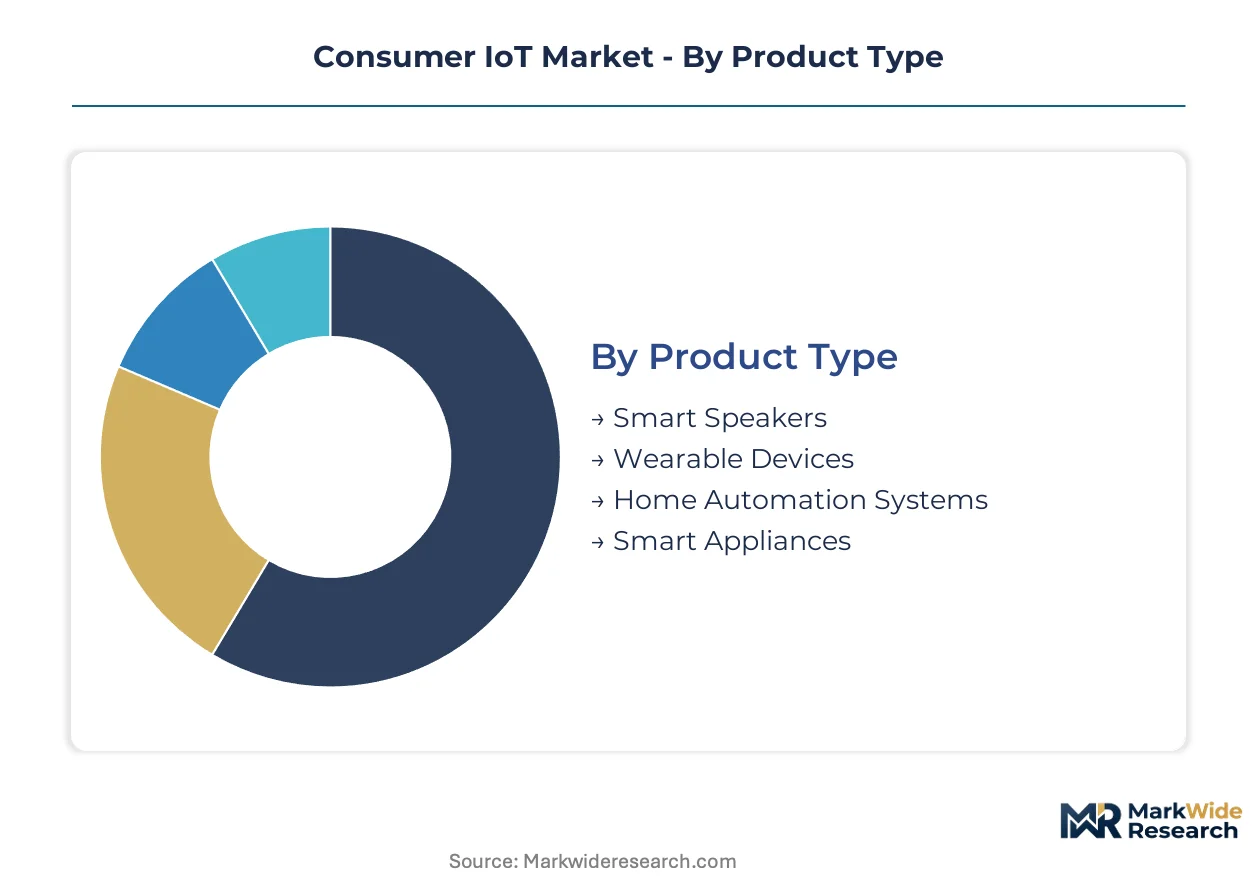
Consumer IoT segmentation reveals distinct margin profiles across hardware categories, with platform economics and connectivity standards determining which configurations capture sustainable returns versus commodity pricing pressure.
Product Type:
Volume concentrates in mass-market hardware while premium tiers attach subscription services and ecosystem lock-in.
- Smart Speakers:Far-field microphone arrays and natural language processors embedded in stationary form factors. Demand clusters in US metropolitan markets where utility rebate programs require Alexa and Google Home interoperability certifications, with Amazon capturing recurring revenue through energy management add-ons.
- Wearable Devices:Wrist-worn or body-worn sensors with photoplethysmography and bioimpedance analysis for health metrics. Germany and California buyers drive concentration as clinical-grade miniaturization expands applications from fitness tracking into preventive monitoring, though GDPR data-localization costs compress margins on sub-$100 units.
- Home Automation Systems:Centralized controllers and sensor networks for lighting, climate, and access control. Thread protocol adoption is displacing legacy Zigbee installations as Matter-certified cross-brand interoperability becomes baseline purchase criteria.
- Smart Appliances:Grid-responsive refrigerators, washers, and HVAC units with embedded edge computing. Residential buyers in China prioritize domestic ecosystem integration through Xiaomi and Huawei manufacturing clusters.
Today's leader: Smart Speakers. Tomorrow's challenger: Wearable Devices.
Technology:
Protocol consolidation around unified standards is compressing hardware differentiation while legacy radio technologies face displacement.
- Wi-Fi:2.4 GHz and 5 GHz radios for high-bandwidth streaming and cloud-backed analytics. FCC spectrum allocation rules shape device certification timelines for US-bound products, with Matter-over-Wi-Fi gaining traction for powered appliances.
- Bluetooth:Low-energy 2.4 GHz stacks for proximity pairing and audio streaming. Nordic Semiconductor modules dominate wearable and personal assistant device integration where power budgets stay under one watt.
- Zigbee:Mesh networking at 2.4 GHz with historical smart home penetration. Regional frequency fragmentation and Matter protocol migration are eroding installed base value as Thread-native modules from Silicon Labs capture new designs.
- Thread:IPv6-native mesh protocol operating at 2.4 GHz with border router architecture. Battery-powered sensors and smart locks in European markets favor Thread for simplified cross-brand interoperability without ecosystem lock-in.
Protocol leadership has shifted: Wi-Fi holds installed base dominance while Thread captures design wins in new construction and retrofit installations.
End User:
Procurement patterns diverge between direct consumer purchases and institutional buyers with compliance-driven specification requirements.
- Residential:Individual households purchasing through retail and direct-to-consumer channels. EU AI Act algorithmic transparency mandates force architecture redesigns for voice assistants and health wearables sold to European consumers.
- Retailers:Commercial deployments for inventory tracking, customer analytics, and smart shelving. Bluetooth beacon density and Wi-Fi presence sensing enable foot traffic optimization in physical store formats.
- Hospitality:Hotels and serviced apartments deploying in-room automation and guest-facing interfaces. Energy-as-a-service partnerships for financed installations create recurring revenue streams beyond hardware margins.
- Healthcare:Clinical and remote patient monitoring applications with regulatory-grade data handling. FDA and EMA oversight of diagnostic-adjacent wearables imposes validation requirements absent in consumer fitness segments.
Residential volume dominates unit shipments; healthcare commands the steepest expansion trajectory as clinical-grade sensor miniaturization enables new reimbursement codes.
Application:
Use case prioritization reflects regional energy pricing structures and demographic health trends rather than uniform global demand patterns.
- Energy Management:Load-shifting appliances and grid-responsive systems for utility cost reduction. Germany's FERC-equivalent network codes and California's time-of-use tariffs automate peak pricing window responses through smart home energy management systems.
- Security & Surveillance:Camera networks, motion sensors, and access control with cloud storage subscriptions. Thread-compatible smart locks are overtaking Z-Wave installations as Matter certification simplifies multi-vendor deployments.
- Health Monitoring:Continuous physiological tracking with preventive care applications. China's MIIT enforces GB standards on wireless transmission power and cybersecurity for domestic and exported health-monitoring wearables.
- Personal Assistance:Voice-activated task management and ambient computing interfaces. Amazon and Google capture lifetime value through platform-locked subscription bundles in US metropolitan markets.
Energy Management anchors current hardware attach rates; Health Monitoring is gaining share fastest as clinical validation expands reimbursable use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting module assembly toward jurisdictions with lower compliance overhead, as GDPR data-localization mandates and EU AI Act certification costs compress margins on European-bound devices.
United States
Utility rebate programs in California and Texas metropolitan markets drive smart home energy management attach rates, with FERC-interfaced grid codes automating peak pricing responses. FCC spectrum allocation rules for Wi-Fi 6E and Matter-over-Thread shape device certification timelines. Seattle and Austin anchor voice-assistant development clusters where Amazon and Google capture platform-locked subscription bundles.
Germany
Residential buyers prioritize grid-responsive appliances under Bundesnetzagentur network codes that mandate automated load shifting during peak windows. EU AI Act algorithmic transparency requirements force architecture redesigns for health-monitoring wearables sold to European consumers. Munich and Stuttgart host Thread-native module design centers where cross-brand interoperability testing accelerates Matter certification cycles.
China
Domestic ecosystem integration through Xiaomi and Huawei manufacturing clusters concentrates demand for smart appliances with MIIT-enforced GB standards on wireless transmission power. Shenzhen and Dongguan anchor global volume production of edge AI processors and sub-gigahertz radio modules. Export-oriented fabricators face cybersecurity compliance divergence between Brussels and Beijing.
India
Production-linked incentive schemes for semiconductor assembly and testing attract module manufacturers seeking alternative supply origins to China. BIS certification requirements for wireless devices create localized testing infrastructure in Bengaluru and Hyderabad. Domestic wearable demand concentrates in Maharashtra and Gujarat where price-sensitive buyers favor entry-level health-monitoring devices.
Japan
METI standards for energy-efficient home automation systems drive premium-tier demand in Tokyo and Osaka metropolitan markets. Clinical-grade sensor miniaturization from Kansai-based component suppliers enables preventive health monitoring applications. Domestic OEMs prioritize Thread-compatible designs for aging-in-place residential installations.
Consumer IoT Market Key Industry Players
Platform ecosystem consolidation dominates the current landscape as voice-assistant providers capture lifetime value through subscription attach. The market structures around three tiers: cloud-backed platform operators with recurring revenue models, vertically integrated hardware manufacturers with captive silicon supply, and modular component suppliers selling radio modules across OEMs. Competitive moves concentrate on strategic partnerships for utility integration and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Among platform operators, Amazon, Google, and Apple occupy positions defined by voice-assistant penetration and smart home energy management service bundles. Samsung Electronics and Huawei exemplify vertically integrated hardware manufacturers controlling module fabrication through captive semiconductor supply. Xiaomi represents scale-driven entry-level specialists flooding price-sensitive Asian and European markets with wearable devices and smart appliances.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Samsung Electronics |
| Huawei |
| Philips |
| Xiaomi |
| Intel |
| Sony |
| Others |
Cost & Logistics Intelligence
Captive silicon fabrication through in-house semiconductor production anchors both supply security and margin protection for vertically integrated Consumer IoT manufacturers. Samsung Electronics and Huawei leverage internal chip design capabilities to buffer against foundry pricing volatility while maintaining cost discipline across Thread-native radio modules and edge AI processors.
Pricing Analysis
Distributor margin compression in European channels reflects GDPR data-localization infrastructure costs passed through to sub-$100 wearable devices. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and ecosystem lock-in depth, with Matter-certified hardware commanding 15-20 point spreads over legacy Zigbee equivalents. Pricing pressure stems from Xiaomi's manufacturing scale flooding entry-level Asian markets. Residential buyers in India and Southeast Asia exhibit highest price sensitivity, while German and Japanese metropolitan markets tolerate premium tiers for clinical-grade health monitoring.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing is reshaping sourcing patterns for semiconductor assembly and testing operations seeking alternatives to China. Advanced node edge AI processors draw from Taiwan and South Korea fabrication, while sub-gigahertz radio modules and battery management ICs rest on China and Vietnam assembly capacity. Single-source vulnerability concentrates in Taiwan's leading-edge foundry capacity for sub-7nm neural processing units. Distribution runs through Shenzhen and Dongguan export hubs for global OEM fulfillment, with regional certification testing localized in Bengaluru and Munich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's PLI-subsidized assembly costs and Europe's compliance-heavy localization requirements creates margin expansion opportunities for module manufacturers repositioning supply origins.
For Market Incumbents: Extend Matter certification coverage across full product portfolios before interoperability mandates harden in European markets. Samsung Electronics should deepen backward integration into Thread-native radio silicon through captive supply agreements with Nordic Semiconductor, while Amazon defends against Google Home encroachment by locking utility rebate program certifications in California and Texas metropolitan markets. For New Entrants and Emerging Players: Utility partnership channels offer the most penetrable white-space for energy-as-a-service business models in Germany and California where grid-responsive appliance demand concentrates. Target hospitality sector deployments for financed smart home installations creating recurring revenue streams beyond hardware margins. Lead with ambient computing convergence featuring radar-based presence sensing to differentiate from established voice-assistant platforms. For Investors and Strategic Acquirers: Roll-up economics work for modular radio module specialists because protocol consolidation around Matter is compressing hardware differentiation and forcing ecosystem consolidation. Five-to-ten year viability hinges on acquisition of Thread-native design houses with existing certification pipelines. Watch Matter certification timeline compression as the inflection signal—four-to-six month testing cycles collapsing toward twelve weeks indicates vendor base consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-brand interoperability testing with CSA accelerates European market access for OEMs. |
| Utility Partnership Formation | FERC-interfaced grid codes in California enable automated peak pricing response services. |
| Thread-Native Module Design | Silicon Labs and Nordic Semiconductor volume shipments reduce SKU complexity for battery-powered sensors. |
| GDPR-Compliant Cloud Infrastructure | Regional data-localization architecture satisfies EU AI Act mandates for health-monitoring wearables. |
| Clinical-Grade Sensor Miniaturization | Photoplethysmography advances from Kansai suppliers expand reimbursable preventive monitoring applications. |
Research Approach
Multiple input streams — semiconductor supply chain databases, regulatory filing repositories, and connected device shipment records — were reconciled through bottom-up and top-down triangulation. Primary interviews with IoT platform engineering directors, smart home procurement leads at European utilities, FCC certification consultants, and module manufacturer supply chain heads informed demand-side validation. Secondary sources included MIIT GB standard filings, CSA Matter certification registries, EIA smart grid deployment data, and SEC 10-K disclosures from vertically integrated electronics manufacturers.
Data-stream reconciliation across product type, connectivity protocol, and geographic regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates and replacement cycle compression in mature categories. Forecast inputs incorporated Thread protocol adoption curves, EU AI Act implementation timelines, and India's PLI scheme capacity buildout trajectories without specifying year markers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry geopolitical disruption and Brussels-Washington-Beijing regulatory divergence on algorithmic transparency mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IoT Data Governance Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
IoT at Workplace Market