
 Iot-Enabled Devices Market | 2026-2036
Iot-Enabled Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Iot-Enabled Devices Market Foresight
ISO/IEC 27001 certification for information security management is reorganizing vendor eligibility across enterprise IoT procurement, particularly in healthcare and industrial verticals where data integrity carries liability exposure. Microsoft leverages its Azure Sphere secure microcontroller platform to anchor cloud-to-edge trust architectures for Fortune 500 deployments. Cisco competes through its IoT networking hardware and edge intelligence software that extends visibility into operational technology environments. Bosch specializes in sensor fusion and embedded systems for automotive and manufacturing IoT, sustaining its position through deep vertical integration from MEMS fabrication to fleet analytics software.
IoT-enabled devices integrate microprocessors, wireless communication modules, sensors, and embedded software to collect, transmit, and act on environmental or operational data with minimal human intervention, typically operating across temperature ranges from minus 40 to 85 degrees Celsius for industrial-grade hardware. Their primary purpose centers on real-time decision automation, asset tracking, and predictive intervention across physical infrastructure. Industrial IoT Devices currently command the deepest margin pools where long equipment lifecycles and high switching costs protect incumbent positions. Cellular connectivity represents the fastest-expanding technology segment as 5G RedCap and satellite-terrestrial hybrid networks reduce power requirements for wide-area asset monitoring. Remote Monitoring applications lead volume adoption, though Predictive Maintenance is narrowing the gap as oil and gas operators, wind farm operators, and freight rail systems prioritize uptime economics over simple telemetry.
The FCC governs spectrum allocation and device authorization for unlicensed and licensed radio modules in the United States, directly constraining which frequency bands and power levels manufacturers can deploy. ETSI and CE marking requirements in Europe mandate electromagnetic compatibility and radio equipment compliance testing that adds six to twelve months to product launch timelines for non-European vendors. FDA software-as-medical-device oversight and the EU AI Act's risk classification system for biometric and health-critical algorithms are converging to raise compliance barriers for connected healthcare monitors. Stakeholders must monitor whether fragmented national cybersecurity certification schemes fragment addressable markets or consolidate around mutual recognition frameworks that preserve scale economics for component suppliers.
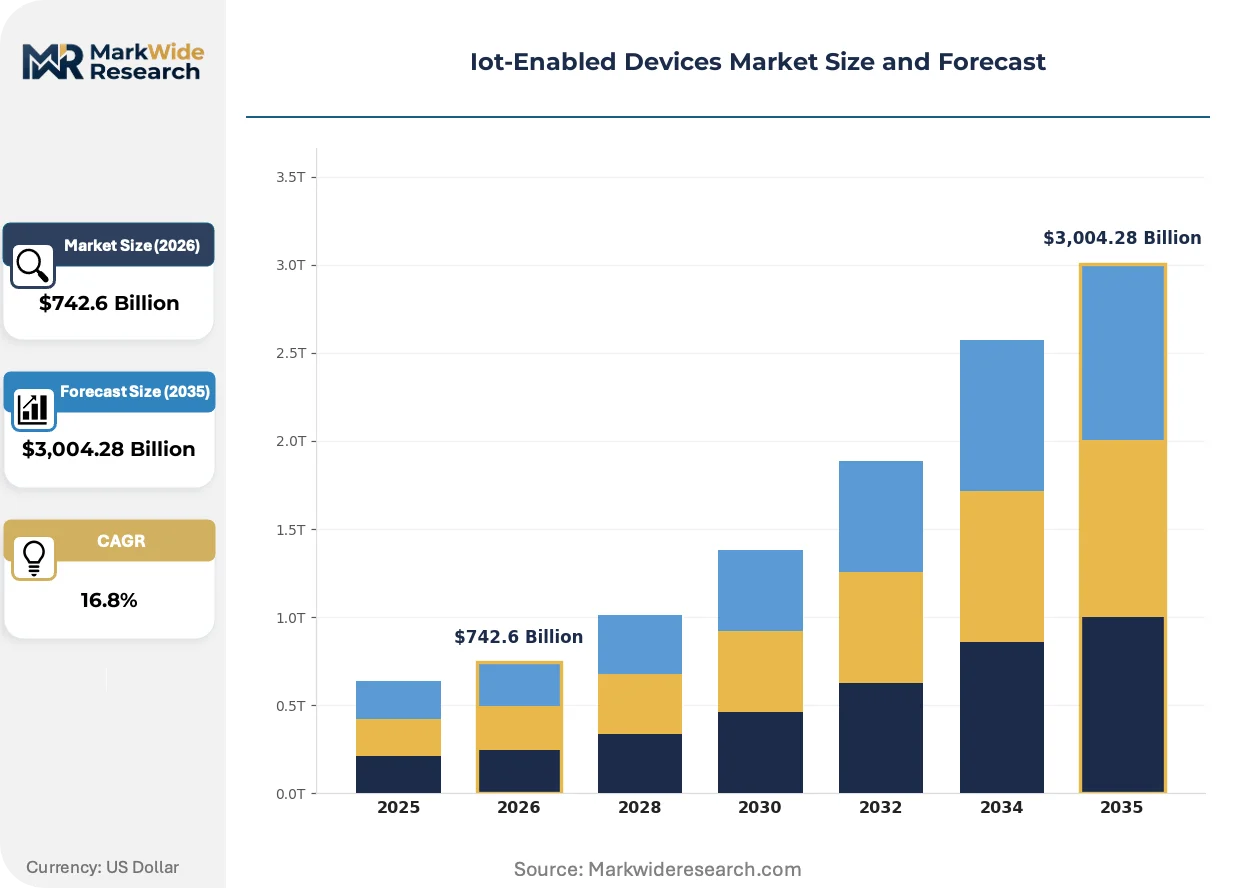
Market Dynamics
Cellular connectivity architectures are compressing power budgets for wide-area monitoring, while ISO/IEC 27001 certification gates are narrowing vendor pools in healthcare and industrial procurement.
Growth Catalysts
- 5G RedCap Deployment:Reduced capability 5G modules cut power consumption by half versus full 5G, enabling battery-operated asset trackers in freight rail and agriculture.
- FDA Software-as-Medical-Device Pathway:Clearer premarket authorization routes accelerate connected monitor launches for chronic disease management.
- German Industrial Automation Corridor:Bosch and Siemens anchor smart factory ecosystems that pull sensor and edge computing demand from automotive and precision manufacturing.
Market Restraints
- Silicon Supply Concentration:Advanced microcontroller fabrication concentrates in Taiwan and South Korea, exposing module vendors to single-source disruption.
- ETSI Compliance Burden:CE marking and electromagnetic compatibility testing add six to twelve months to European product launches for non-EU hardware vendors.
- Legacy SCADA Integration Costs:Brownfield industrial sites require custom protocol gateways that inflate deployment budgets by thirty to fifty percent versus greenfield.
Strategic Opportunities
- EU AI Act Risk Classification:Biometric and health-critical algorithm mandates create compliance service revenue streams for certification consultancies and testing labs.
- Satellite-Terrestrial Hybrid Networks:Low-earth orbit constellations combined with cellular backhaul unlock remote monitoring for offshore wind and mining operations beyond terrestrial coverage.
- Wind Farm Predictive Maintenance:Uptime economics in renewable energy drive sensor density per turbine threefold higher than fossil generation assets.
Industry Challenges
- Embedded Security Engineering Talent:Secure boot implementation and hardware root-of-trust design skills command premium compensation that mid-tier vendors struggle to match.
- Multi-Jurisdiction Certification Overlap:FCC Part 15, ETSI EN 300 328, and MIC Japan radio approvals require redundant testing that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iot-Enabled Devices Market |
| Market Size in 2026 | $742.6 Billion |
| Market Size in 2035 | $3,004.28 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Smart Home Appliances, Industrial IoT Devices, Healthcare Monitors Technology: Bluetooth, Wi-Fi, Zigbee, Cellular End User: Healthcare Providers, Smart Home Users, Industrial Operators, Retail Businesses Application: Remote Monitoring, Automation, Predictive Maintenance, Supply Chain Management |
| Companies Covered | Microsoft, Amazon Web Services (AWS), Cisco, Huawei, Intel, Google, IBM, Bosch, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iot-Enabled Devices Market Shifts & Advancements
Edge-native AI inference is compressing cloud dependency for latency-critical applications, while regulatory fragmentation across cybersecurity certification schemes is forcing modular compliance architectures.
AI accelerators embedded at the sensor node are displacing cloud-only inference for vibration analysis and acoustic monitoring in rotating equipment. Oil and gas operators deploy these chips in upstream drilling systems where satellite bandwidth costs prohibit real-time cloud upload. The shift is compressing data sovereignty risks and enabling sub-ten-millisecond anomaly detection.
The EU AI Act's risk-based classification system is mandating conformity assessments for biometric identification and health-critical algorithms before market entry. Connected healthcare monitor vendors must document training data provenance and algorithmic performance metrics under notified body supervision. Germany and France are moving fastest on delegated act implementation, pulling compliance investment toward Western European product launches.
Outcome-based service contracts are displacing capital equipment sales in industrial IoT procurement. Buyers in automotive and semiconductor manufacturing now pay per unit of uptime or throughput rather than owning sensor hardware. This shift concentrates vendor selection on predictive accuracy track records and compresses margins for hardware-only suppliers.
Iot-Enabled Devices Market Segmentation
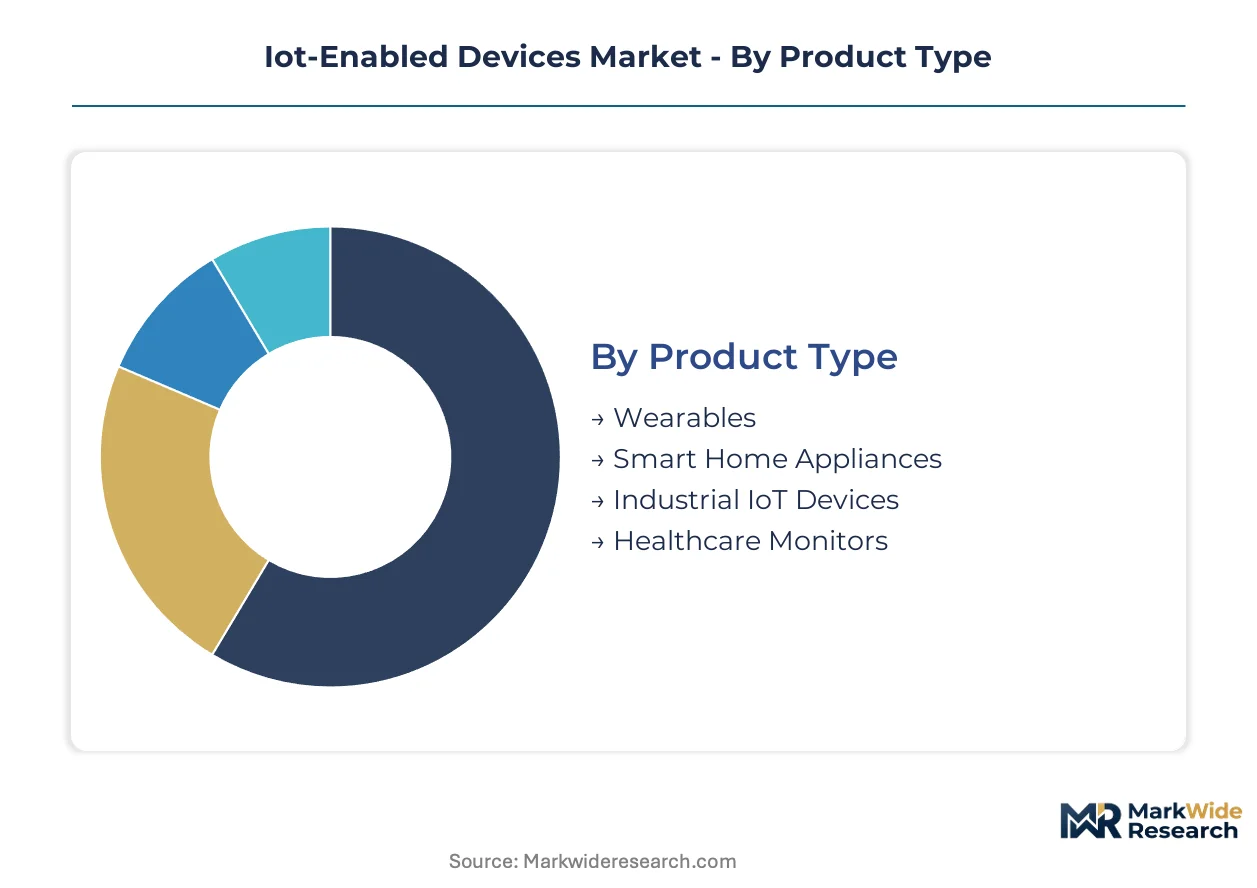
IoT-enabled devices fragment across hardware form factors, connectivity protocols, and operational contexts that dictate procurement priorities. Understanding these divisions reveals where margin pools concentrate and which integration challenges dominate deployment economics.
Product Type:
Domestic demand anchors Wearables and Smart Home Appliances, while Industrial IoT Devices and Healthcare Monitors derive substantial revenue from export-led manufacturing corridors in Germany and Taiwan.
- Wearables:Compact sensor arrays measuring biometrics, motion, and environmental exposure through wrist-worn or body-integrated form factors. Demand concentrates in consumer electronics channels across the United States and China, constrained by battery chemistry limitations that cap continuous monitoring duration.
- Smart Home Appliances:Connected refrigerators, thermostats, lighting systems, and security devices with embedded voice recognition and occupancy sensing. European markets drive specification requirements through Ecodesign regulations and interoperability mandates under the EU Cybersecurity Act.
- Industrial IoT Devices:Ruggedized sensors, programmable logic controllers, and edge gateways operating in factory and field environments. These units withstand temperature extremes from minus 40 to 85 degrees Celsius.
- Healthcare Monitors:FDA-cleared and CE-marked devices for continuous physiological tracking, including pulse oximeters, cardiac event recorders, and glucose sensors.
Industrial IoT Devices commands the established base. The steepest expansion runs through Healthcare Monitors.
Technology:
Cost tier structures separate short-range protocols for consumer applications from cellular modules requiring carrier certification and recurring subscription economics.
- Bluetooth:Low-energy 2.4 GHz protocol enabling peer-to-peer device pairing with sub-10 milliwatt power draw. Wearables and Smart Home Appliances in North American and European retail channels standardize on this specification for proximity-based control.
- Cellular:Licensed spectrum connectivity spanning 4G LTE through 5G RedCap with wide-area coverage and carrier-managed security. Freight rail operators and agricultural sensor networks in Australia and Brazil deploy these modules where terrestrial infrastructure exists but Wi-Fi penetration fails.
- Wi-Fi:Unlicensed 2.4 and 5 GHz radio for high-bandwidth local area networking in residential and commercial buildings. Smart home ecosystems rely on this protocol for video streaming and firmware updates.
- Zigbee:Mesh networking specification optimized for low-power device-to-device communication in building automation and lighting control systems.
Bluetooth anchors volume deployment. Cellular gains share fastest as 5G RedCap reduces module cost and power consumption thresholds.
End User:
Customer type determines procurement sophistication, with Industrial Operators and Healthcare Providers imposing certification requirements that consumer channels ignore.
- Healthcare Providers:Hospital systems, physician networks, and home health agencies deploying FDA-authorized and CE-marked devices under clinical governance. Remote patient monitoring programs in the United States and Germany drive recurring revenue models for connected diagnostic hardware.
- Industrial Operators:Manufacturing facilities, oil and gas producers, and logistics companies integrating sensors with SCADA and enterprise asset management systems. Predictive maintenance contracts in German automotive plants and Saudi petrochemical complexes prioritize uptime guarantees over capital expenditure.
- Smart Home Users:Residential consumers purchasing through retail and direct-to-consumer channels for convenience and energy management applications.
- Retail Businesses:Inventory tracking, cold chain monitoring, and customer analytics deployments in grocery, pharmaceutical, and apparel supply chains.
Industrial Operators command the established base. Healthcare Providers show the steepest expansion trajectory as reimbursement codes align with remote monitoring outcomes.
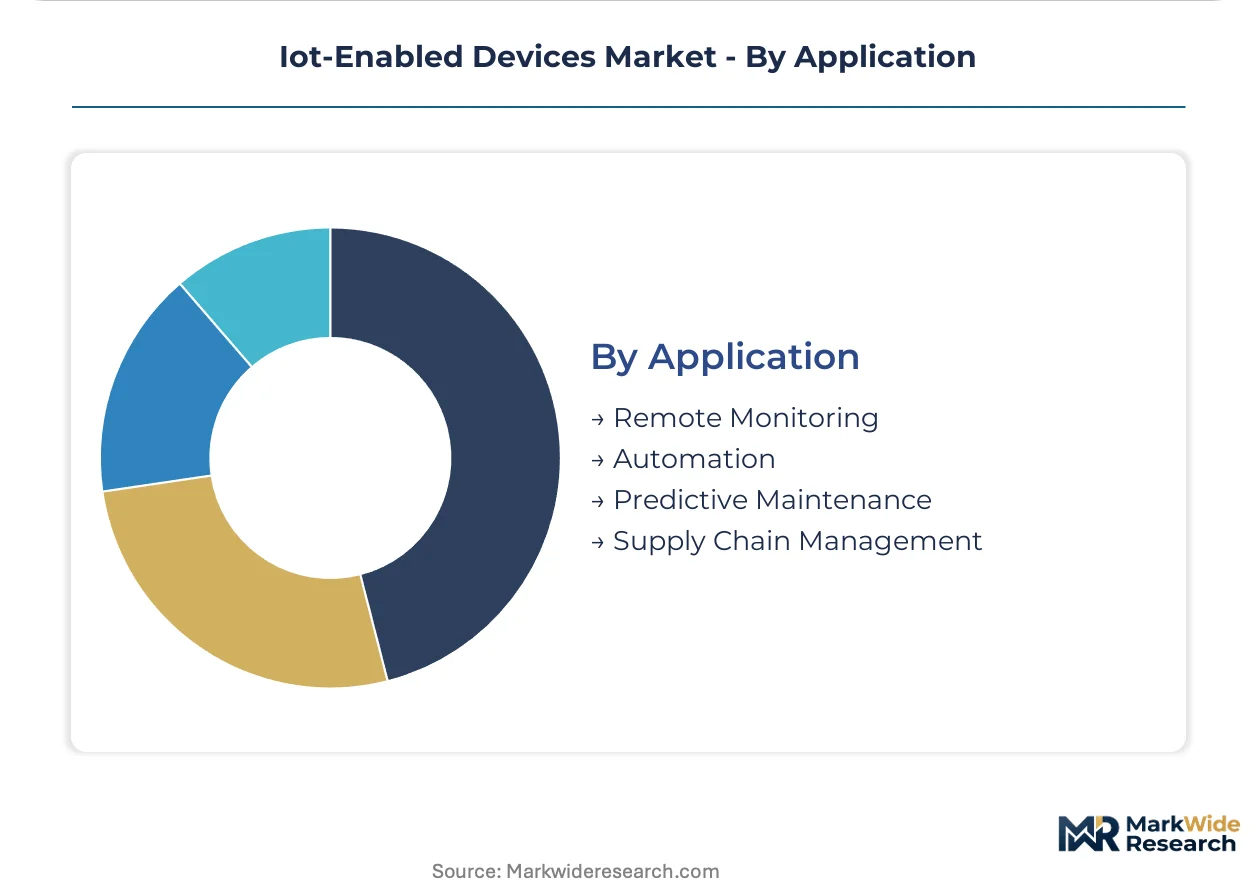
Application:
Volume concentration sits with telemetry-focused use cases, while value concentration shifts toward intervention systems that prevent failure rather than merely report status.
- Remote Monitoring:Continuous data collection from dispersed assets, patients, or environmental conditions with centralized dashboard visibility. Wind farm operators in Denmark and offshore platforms in the North Sea deploy dense sensor networks for condition tracking.
- Predictive Maintenance:Algorithmic analysis of vibration, thermal, and acoustic signatures to forecast equipment degradation before functional failure. Freight rail systems across the United States and mining haul trucks in Western Australia prioritize this application to avoid catastrophic downtime costs.
- Automation:Closed-loop control systems adjusting machinery, climate, or lighting based on real-time sensor feedback without human intervention.
- Supply Chain Management:Asset tracking, inventory visibility, and condition monitoring across multi-modal logistics networks from manufacturing through last-mile delivery.
Remote Monitoring commands the established base. Predictive Maintenance climbs the fastest as uptime economics reshape procurement criteria in capital-intensive sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
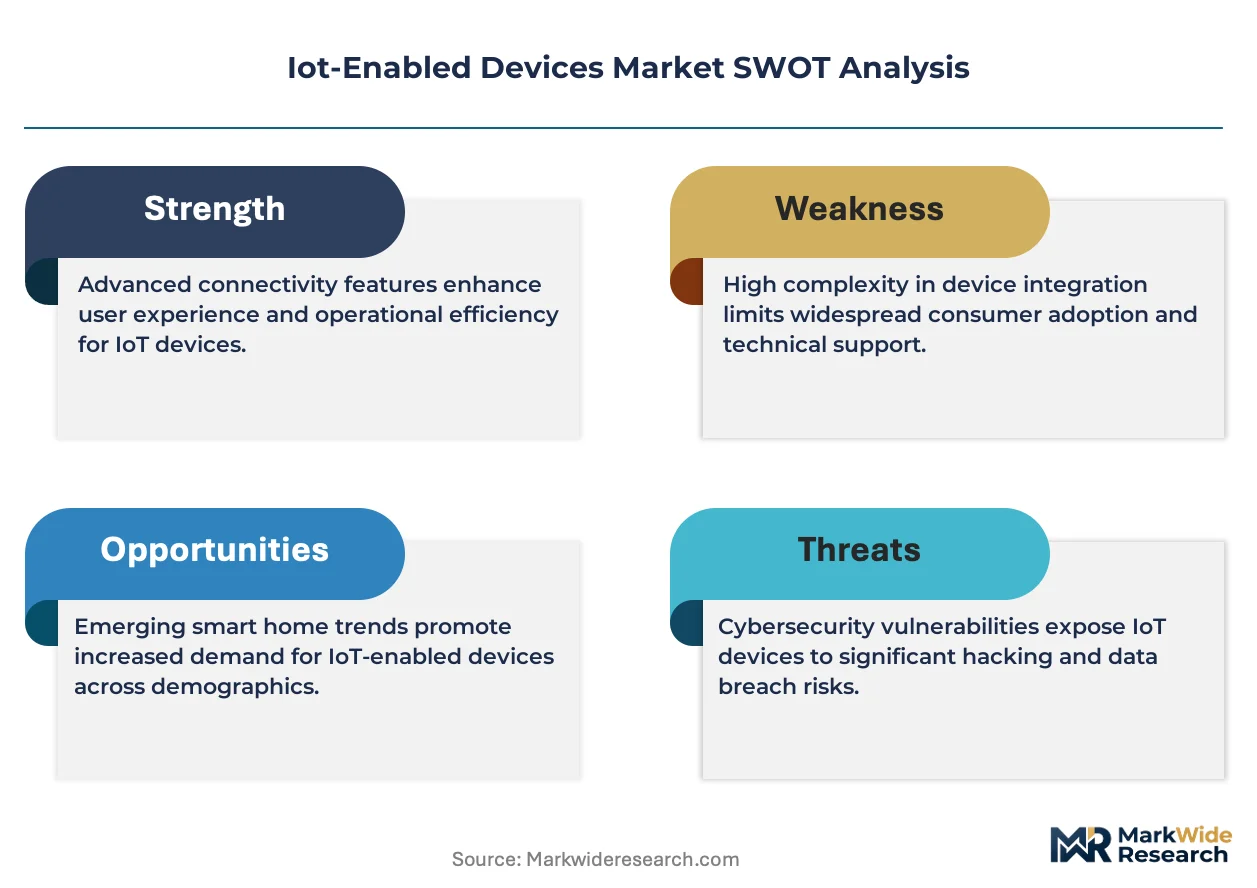
Government incentives for industrial digitalization and healthcare modernization are redirecting capital flows across national boundaries. The EU AI Act and FDA software-as-medical-device pathways are tightening compliance requirements that reshape vendor eligibility. Germany's industrial automation corridor anchors European demand through Bosch and Siemens ecosystems.
United States
FDA software-as-medical-device oversight accelerates connected monitor launches for chronic disease management. FCC spectrum allocation governs which frequency bands manufacturers deploy for unlicensed and licensed radio modules. The Boston-Cambridge healthcare technology cluster concentrates remote patient monitoring development under clinical governance frameworks.
Germany
Bosch and Siemens anchor smart factory ecosystems that pull sensor and edge computing demand from automotive and precision manufacturing. ETSI and CE marking requirements mandate electromagnetic compatibility testing that extends product launch timelines. The Baden-Württemberg industrial corridor sustains deep vertical integration from MEMS fabrication to fleet analytics software.
China
MIIT standards and GB certification frameworks govern domestic IoT device deployment across manufacturing and smart city applications. Dual carbon goals drive sensor density in renewable energy installations and industrial efficiency monitoring. The Yangtze River Delta manufacturing belt concentrates module production and supply chain integration for export markets.
Japan
METI industrial digitalization programs subsidize predictive maintenance deployments in automotive and semiconductor manufacturing. JIS standards and PMDA oversight create parallel compliance tracks for healthcare-connected devices. The Chubu-Nagoya manufacturing hub concentrates edge-native AI inference development for rotating equipment monitoring.
South Korea
MFDS medical device regulations align with international standards to accelerate connected health product approvals. Advanced microcontroller fabrication concentrates in domestic foundries, reducing single-source exposure for module vendors. The Seoul Capital Area anchors 5G RedCap deployment for wide-area asset tracking in logistics and agriculture.
Iot-Enabled Devices Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and embedded hardware domains. The vendor base organizes into three tiers: hyperscale cloud platforms, networking equipment incumbents, and vertical-integrated industrial specialists. Strategic differentiation runs through secure microcontroller architectures, edge intelligence software, and sensor fusion capabilities. Dominant competitive moves include M&A for AI talent acquisition and strategic partnerships for satellite-terrestrial hybrid connectivity.
Within the cloud-platform archetype, Microsoft and Amazon Web Services occupy positions anchoring cloud-to-edge trust architectures for enterprise deployments. Cisco exemplifies the networking equipment tier through IoT networking hardware and edge intelligence software. Bosch represents vertical-integrated industrial specialists with positions spanning MEMS fabrication to fleet analytics. These three anchors illustrate how competitive positioning fragments across infrastructure layers rather than consolidating around end-to-end control.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services (AWS) |
| Cisco |
| Huawei |
| Intel |
| IBM |
| Bosch |
| Samsung |
| Others |
Supply & Pricing Matrix
ISO/IEC 27001 certification gates both supplier qualification and price differentiation simultaneously, creating tiered access to healthcare and industrial procurement channels where uncertified vendors face exclusion regardless of cost position. Buyers in German automotive and North American hospital systems now bundle security compliance with volume commitments, compressing margin flexibility for mid-tier module vendors.
Pricing Analysis
Certification level (ISO 27001/CE/FDA-grade) creates the primary spread between premium and standard tiers. Subscription-based SaaS pricing dominates for connected health monitors and predictive maintenance platforms, while transactional per-unit sales persist in consumer wearables and smart home devices. Price differentiation rests on security certification depth and after-sales service bundling. Cost compression in the standard tier is intensifying because Taiwanese foundry capacity constraints inflate microcontroller costs. Healthcare providers show the least price sensitivity due to liability exposure, while retail smart home channels demand aggressive economy positioning.
Supply Chain Analysis
Inventory buffers for industrial-grade sensors currently stretch eighteen to twenty-four months as buyers hoard qualified components ahead of ETSI compliance deadlines. Advanced microcontroller fabrication concentrates in Taiwan and South Korea, with MEMS sensor production anchored in Germany and China. Supply chains draw from silicon wafers, rare earth magnets for precision motors, and lithium-ion cells for battery-operated devices. Single-source vulnerability in Taiwanese foundry capacity exposes module vendors to disruption. Distribution runs through authorized distributors for industrial verticals and direct-to-consumer e-commerce for retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and US hospital purchasing committees, fragmenting vendor pools as procurement centralizes around outcome-based contracts and security certification mandates.
For Market Incumbents: Secure embedded security engineering talent through targeted acquisition of hardware root-of-trust design teams before compensation premiums escalate beyond mid-tier reach. Deepen backward integration into MEMS fabrication to reduce exposure to single-source Taiwanese foundry disruption. Lock in long-term capacity reservations with South Korean foundry partners as 5G RedCap module demand accelerates.
For New Entrants and Emerging Players: Lead with satellite-terrestrial hybrid connectivity solutions for offshore wind and mining operations beyond terrestrial coverage, where incumbent cellular providers lack service footprints. Target Australian agricultural sensor networks and Brazilian freight rail operators as the most penetrable wide-area monitoring segments. Pursue direct sales to industrial operators with outcome-based uptime guarantees rather than competing on hardware cost.
For Investors and Strategic Acquirers: The EU AI Act's delegated act implementation reshapes the acquisition landscape by concentrating compliance investment toward Western European product launches and penalizing late entrants. Long-term viability favors specialists with documented training data provenance and notified body relationships for health-critical algorithms. Watch FDA software-as-medical-device premarket authorization velocity as the signal for connected health monitor market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Investment | Opens enterprise procurement channels in German automotive and US healthcare systems. |
| 5G RedCap Module Development | Enables battery-operated asset tracking for Australian agriculture and Brazilian logistics. |
| Satellite-Terrestrial Hybrid Partnership | Extends coverage to offshore wind farms and remote mining beyond cellular infrastructure. |
| Edge-Native AI Inference Acquisition | Reduces cloud dependency for oil and gas drilling systems with satellite bandwidth constraints. |
| Outcome-Based Service Contract Pivot | Aligns vendor economics with uptime guarantees demanded by Saudi petrochemical operators. |
Research Methodology
A standing panel of IoT platform architects, hospital biomedical engineers, industrial maintenance directors, and FCC regulatory consultants provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, ETSI compliance databases, SEC equipment supplier disclosures, and hyperscaler capex reports. Bottom-up unit economics triangulated against top-down market sizing from trade flow data and carrier subscription disclosures.
External benchmark consistency checks validated volume and value outputs against foundry capacity announcements and carrier infrastructure deployment schedules across the projection horizon. Segmentation dimensions modeled include hardware form factor, connectivity protocol, end-user sophistication, and application criticality. CAGRs derived from installed base growth curves and replacement cycle compression in industrial verticals. Forecast inputs incorporated 5G RedCap module cost trajectories and EU AI Act implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor fabrication capacity expansion or mutual recognition of cybersecurity certification schemes would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization and foundry geographic diversification. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Smart Tracker Market