
 IoT in Retail Market | 2026-2036
IoT in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Retail Market Analysis
Apparel and grocery retail is broadening its share of IoT deployment budgets as these sectors pursue real-time shelf analytics and frictionless checkout. Amazon.com Inc. leverages its cloud infrastructure to dominate edge-to-cloud retail data pipelines. Cisco Systems Inc. sustains channel control through networking hardware that anchors in-store connectivity architectures. Impinj Inc. specializes in RAIN RFID endpoint silicon, occupying a narrow but critical tier of the tag ecosystem.
IoT in retail encompasses networked sensor arrays, edge gateways, and cloud-native platforms that collect, process, and act on operational data across physical stores and distribution nodes. Systems typically integrate RFID interrogators operating in the 860–960 MHz UHF band, Bluetooth Low Energy beacons, and computer vision cameras feeding inference engines at the network edge. Smart shelves and RFID tags capture structural margin pools as these hardware categories command recurring replacement cycles and firmware upgrade revenues. Supply chain management applications lead current deployment value, while artificial intelligence integration within data analytics platforms represents the fastest-expanding technology layer as retailers automate demand forecasting and shrinkage detection.
FCC equipment authorization governs UHF RFID and unlicensed spectrum deployment across US retail estates, while GDPR and EU AI Act provisions in Europe constrain cross-border customer data processing and algorithmic decision transparency. Retailers navigating multi-jurisdictional compliance must architect data residency and consent management into platform design from inception. Stakeholders should monitor how NIST cybersecurity frameworks and emerging state-level biometric privacy laws reshape hardware procurement criteria and vendor qualification timelines.
Market Dynamics
Cloud-to-edge architecture migration is compressing latency requirements for real-time inventory systems while forcing retailers to rebuild data pipelines around distributed inference nodes rather than centralized warehouses.
Growth Catalysts
- Smart checkout deployment:Grocery chains in the United States are scaling sensor networks to eliminate friction at point-of-sale, driving hardware refresh cycles across RFID interrogators and edge gateways.
- GDPR compliance architecture:European retailers must embed consent management and data residency into platform design, creating demand for privacy-preserving edge computing solutions that process biometric and behavioral data locally.
- RAIN RFID endpoint proliferation:Fashion retailers deploying item-level tagging at scale are accelerating silicon demand for 860–960 MHz UHF band interrogators, particularly for shrinkage detection and automated replenishment.
Market Restraints
- Silicon supply concentration:RAIN RFID endpoint chip fabrication concentrates among a limited set of foundry operators, exposing tag vendors to capacity allocation risk during semiconductor demand surges.
- FCC equipment authorization timelines:UHF RFID and unlicensed spectrum device approvals in the United States create 6–12 month qualification delays for new hardware form factors, compressing product launch windows.
- Legacy POS integration complexity:Mainframe-era transaction systems at established retailers resist API-native connectivity, forcing expensive middleware layers that erode IoT project ROI.
Strategic Opportunities
- EU AI Act algorithmic transparency:Retailers operating across European jurisdictions must document automated decision logic for demand forecasting and pricing, creating service revenue for compliance tooling vendors.
- India organized retail expansion:Reliance Retail and Tata's retail arms are piloting computer vision and smart shelf networks in Mumbai and Bangalore, representing underpenetrated deployment terrain for full-stack IoT providers.
- Computer vision-edge convergence:The fusion of GPU-accelerated inference at store gateways with low-power Bluetooth beacon meshes enables shelf-state analytics without cloud round-trips, opening new latency-sensitive applications.
Industry Challenges
- Edge AI talent scarcity:Retailers lack internal capability to optimize TensorRT and ONNX runtimes for store-deployed inference engines, forcing reliance on vendor professional services.
- Biometric privacy law fragmentation:Illinois BIPA and emerging state-level statutes in Texas and Washington create conflicting consent requirements for facial recognition deployments in loss prevention.
- Gateway firmware lifecycle management:Distributed edge hardware across thousands of store locations complicates security patching and feature rollout, exposing retailers to CVE disclosure response gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Retail Market |
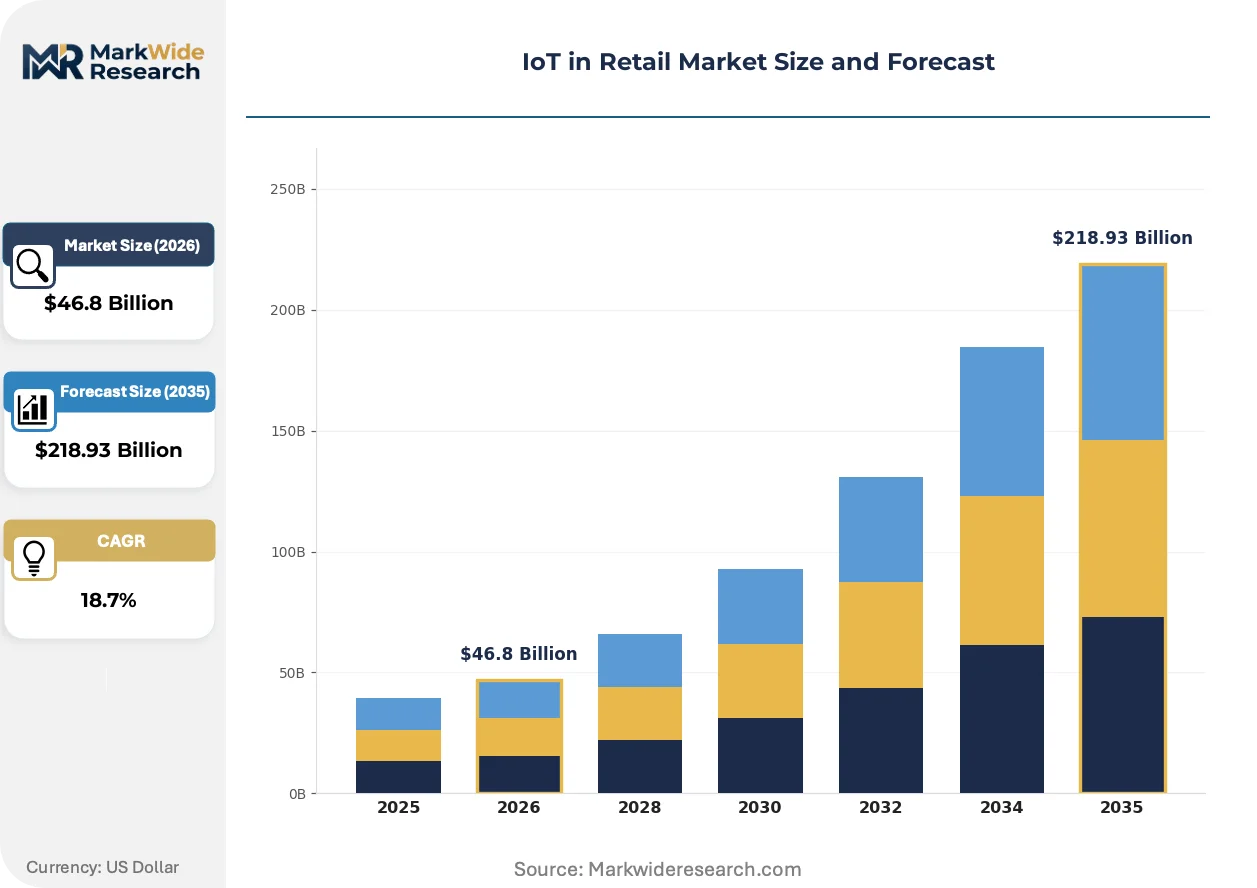
| Market Size in 2026 | $46.8 Billion |
| Market Size in 2035 | $218.93 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Shelves, Beacons, RFID Tags, Wearable Devices Application: Supply Chain Management, Inventory Tracking, Customer Engagement, In-Store Navigation Technology: Cloud Computing, Edge Computing, Data Analytics, Artificial Intelligence End User: Brick-and-Mortar Stores, E-Commerce Platforms, Supermarkets, Specialty Retailers |
| Companies Covered | Huawei Technologies Co. Ltd., Nedap NV, Amazon.com Inc., Honeywell International Inc., Impinj Inc., Cisco Systems Inc., Microsoft Corp., Cooler Screens, IBM Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Retail Market Emerging Trajectories
Retail IoT architectures are pivoting from cloud-centric batch processing to edge-native real-time inference, compressing decision latency while fragmenting vendor control across hardware, software, and connectivity layers.
Edge-native computer vision is decentralizing shelf-state analytics by embedding GPU-accelerated inference directly into store gateway hardware. Grocery and mass-merchandise chains in Germany and France are deploying these systems at pilot scale, with full rollout timelines compressing from 18-month enterprise cycles to 6-month franchisee-driven deployments. This architecture is decentralizing competitive advantage away from centralized cloud providers toward vertically integrated hardware-software vendors that control both camera silicon and model optimization toolchains.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for automated inventory replenishment and dynamic pricing systems. Retailers operating in France and the Netherlands must now document training data provenance and decision logic for systems affecting product availability. Mid-market apparel chains with cross-border operations are responding by bifurcating their tech stacks—deploying simpler rule-based systems in EU markets while maintaining ML-driven forecasting in the United States and Asia-Pacific.
Franchisee-led procurement of IoT hardware is fragmenting traditional enterprise sales channels. Regional grocery cooperatives in Spain and Italy are negotiating directly with Shenzhen-based gateway manufacturers, bypassing systems integrators that historically mediated retail technology adoption. This pattern is most visible in southern European markets where franchisee associations wield purchasing power comparable to corporate IT departments, compressing vendor margin structures and accelerating hardware commoditization cycles.
IoT in Retail Market Segmentation
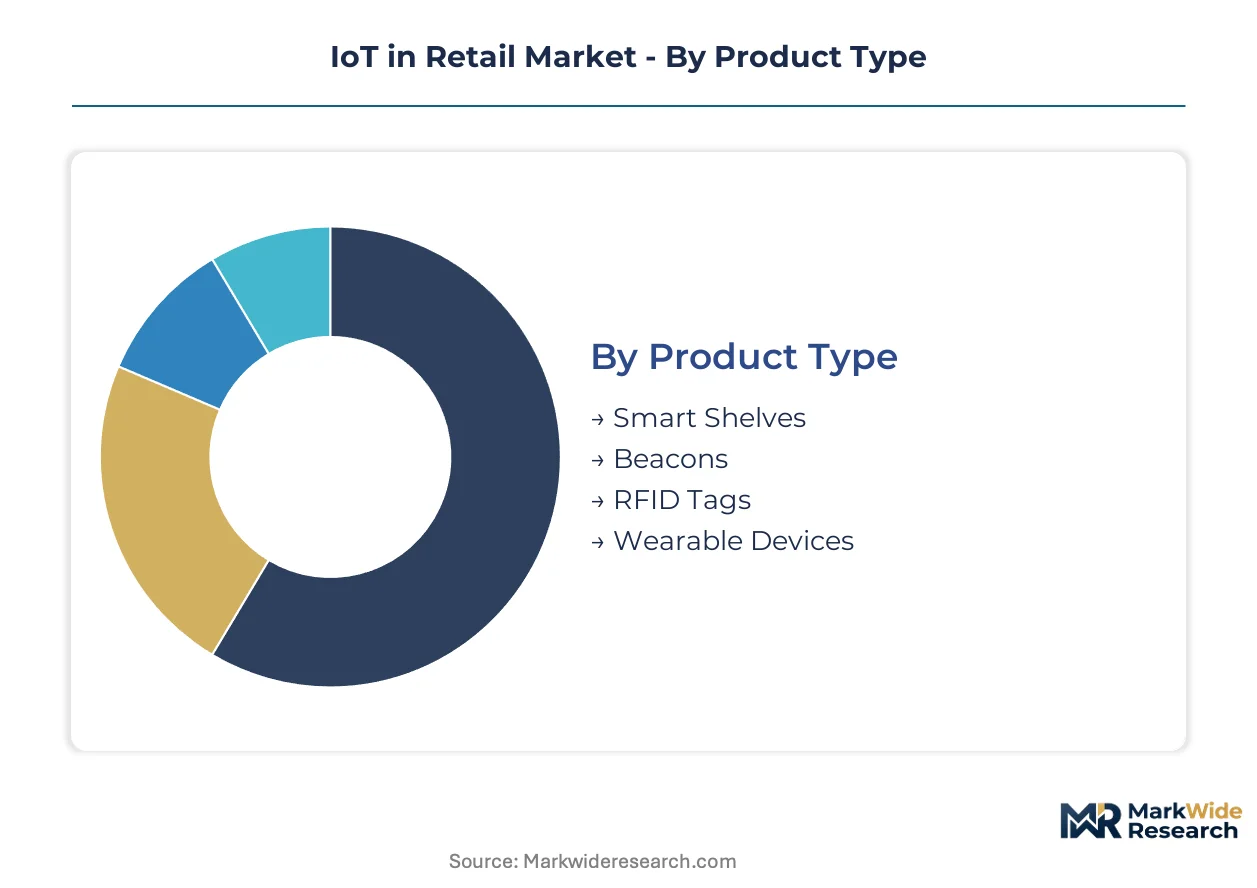
IoT deployment in retail fragments across hardware form factors, software layers, and operational use cases, each carrying distinct certification burdens and integration complexity. Vendors must architect solutions around specific FCC equipment authorizations for UHF RFID, GDPR consent frameworks for customer-facing sensors, and NIST cybersecurity guidelines for edge gateways. Procurement decisions increasingly hinge on which segments align with existing infrastructure and compliance maturity.
Product Type:
RFID Tags and Smart Shelves trigger FCC Part 15 authorization for 860–960 MHz operation, while Beacons fall under unlicensed spectrum rules with shorter approval cycles. Wearable Devices face the heaviest regulatory load, requiring FCC certification plus state-level biometric privacy compliance where cameras or biometrics are embedded.
- Smart Shelves:Sensor-embedded shelving units integrate weight sensors, computer vision cameras, and Bluetooth Low Energy modules to track stock levels and shopper interactions in real time. Grocery chains in the United States deploy these at scale for automated replenishment alerts, though Illinois BIPA compliance adds consent-layer complexity for any biometric capture.
- RFID Tags:Passive UHF inlays operating in the 860–960 MHz band enable item-level tracking without onboard power, with RAIN RFID endpoint silicon driving per-tag costs below five cents at volume. Fashion retailers in France and the Netherlands accelerate adoption for shrinkage detection, navigating EU AI Act documentation requirements when tag data feeds automated replenishment algorithms.
- Beacons:Bluetooth Low Energy transmitters broadcast proximity signals to smartphones for indoor positioning and promotional triggering.
- Wearable Devices:Staff-worn scanners and customer-facing smartwatches enable hands-free inventory operations and frictionless checkout.
RFID Tags sit at the top of the volume ranking, with Smart Shelves climbing the fastest as computer vision-embedded units displace basic weight-sensor models.
Application:
Supply Chain Management and Inventory Tracking concentrate capital expenditure among grocery and mass-merchandise operators, while Customer Engagement and In-Store Navigation attract franchisee-led procurement with shorter payback horizons. Cost tiering separates enterprise-wide deployments from pilot-scale franchisee investments.
- Supply Chain Management:End-to-end visibility platforms integrate RFID interrogators at distribution centers, GPS-enabled trailers, and edge gateways at store receiving docks to track goods from manufacturer to shelf. United States-based grocery chains dominate deployment value, driven by FDA Food Safety Modernization Act traceability mandates that require lot-level tracking for high-risk foods.
- Inventory Tracking:Real-time stock visibility systems combine smart shelf sensors, handheld RFID readers, and cloud-native dashboards to automate cycle counting and reduce out-of-stock incidents. Specialty retailers in Germany pilot these systems for high-value apparel, with EU GDPR constraining how shelf-dwell-time data links to individual shopper profiles.
- Customer Engagement:Proximity-triggered promotions and personalized recommendations via beacon networks and mobile apps.
- In-Store Navigation:Indoor positioning systems guide shoppers to product locations through smartphone interfaces.
Supply Chain Management commands the largest deployment budgets, with Inventory Tracking gaining share fastest as computer vision-embedded smart shelves reach commercial scale.
Technology:
Edge Computing and Artificial Intelligence carry the steepest talent and optimization burdens, while Cloud Computing and Data Analytics represent mature procurement categories with established vendor relationships. Technology selection follows a maturity curve from centralized data lakes toward distributed inference nodes.
- Cloud Computing:Centralized data reservoirs and API-native platforms aggregate sensor feeds from thousands of store locations, with Amazon Web Services and Microsoft Azure dominating retail sector contracts. United States-based chains favor cloud-heavy architectures for demand forecasting, though GDPR data residency requirements force European operators toward hybrid models.
- Edge Computing:GPU-accelerated gateways process computer vision inference locally, compressing latency for shelf-state analytics and eliminating cloud round-trips for biometric data. Grocery cooperatives in Spain negotiate directly with Shenzhen-based gateway manufacturers, bypassing traditional systems integrators to reduce per-store deployment costs.
- Data Analytics:Business intelligence dashboards and historical reporting tools for operational KPIs.
- Artificial Intelligence:Machine learning models for demand forecasting, shrinkage prediction, and automated pricing.
Cloud Computing anchors current infrastructure spend, with Edge Computing expanding most quickly as latency requirements tighten for real-time inventory systems.
End User:
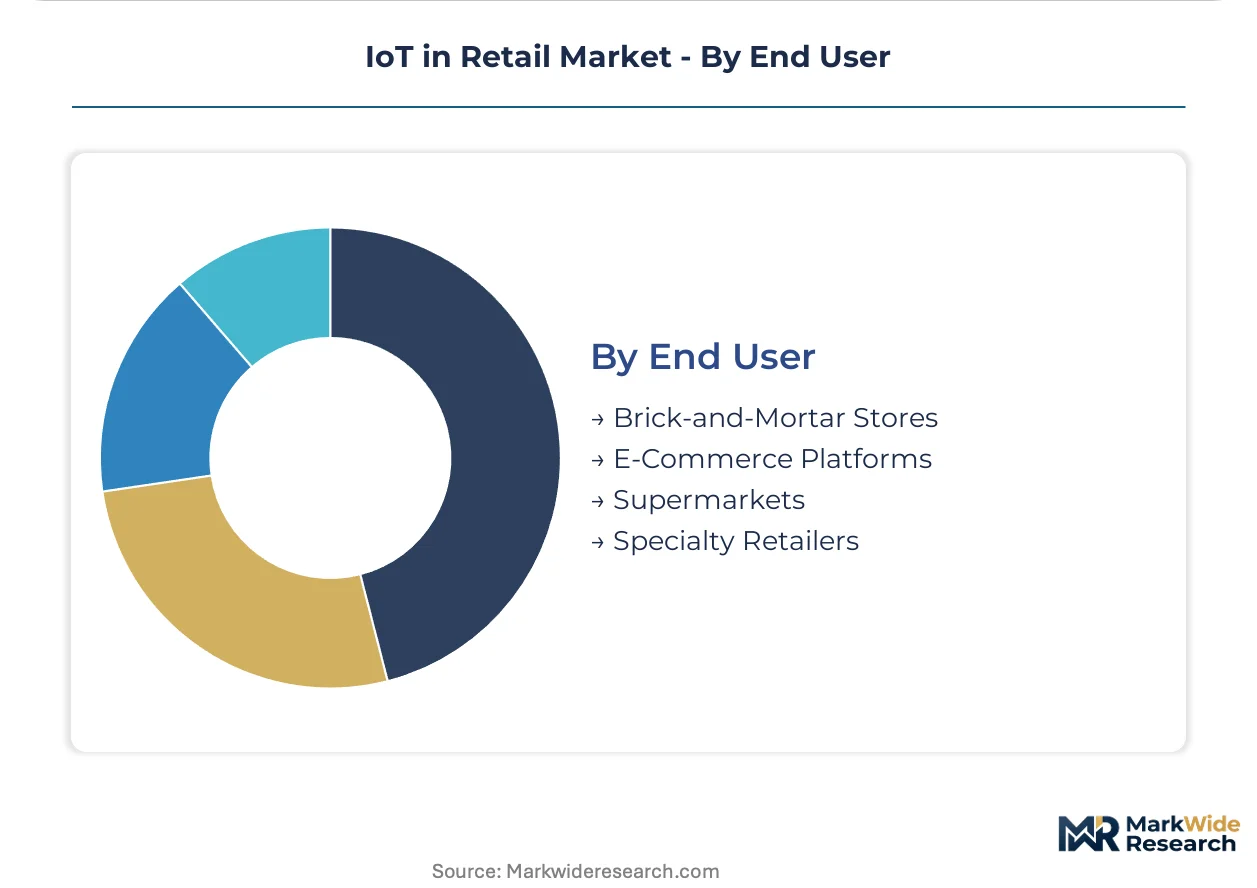
Brick-and-Mortar Stores and Supermarkets drive hardware refresh cycles at scale, while E-Commerce Platforms and Specialty Retailers concentrate investment in last-mile and flagship experience differentiation. Customer type determines whether procurement flows through corporate IT or franchisee associations.
- Brick-and-Mortar Stores:Physical retail estates deploy comprehensive sensor networks spanning RFID interrogators, smart shelves, and edge gateways to unify online and offline inventory visibility. United States grocery and fashion chains lead capital deployment, with FCC equipment authorization timelines stretching 6–12 months for new UHF RFID hardware form factors.
- Supermarkets:High-velocity food retail operations prioritize smart checkout elimination and automated replenishment for perishable categories. Reliance Retail in India pilots computer vision and smart shelf networks in Mumbai, representing underpenetrated terrain for full-stack IoT providers as organized retail expands.
- E-Commerce Platforms:Online-first retailers deploying IoT for warehouse automation and last-mile tracking.
- Specialty Retailers:Niche operators focusing on high-touch customer experience and limited SKU depth.
Brick-and-Mortar Stores dominate installed base, with Supermarkets showing the steepest expansion trajectory as smart checkout deployment accelerates among grocery chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors retail IoT innovation through cloud-to-edge architecture migration, while regulatory fragmentation across major economies reshapes deployment patterns. FCC equipment authorization timelines and GDPR compliance requirements create divergent qualification pathways for hardware vendors.
United States
Grocery chains deploy smart checkout systems at scale, driving hardware refresh cycles for RFID interrogators and edge gateways. FDA Food Safety Modernization Act traceability mandates require lot-level tracking for high-risk foods, accelerating sensor network investment. Chicago and Dallas-Fort Worth metro areas concentrate pilot deployments for computer vision-embedded smart shelves.
Germany
Specialty retailers pilot real-time inventory tracking for high-value apparel, with EU AI Act documentation requirements constraining automated replenishment algorithms. ECHA chemical safety standards influence hardware material specifications for in-store sensors. The Rhine-Ruhr industrial corridor hosts systems integrators bridging legacy POS infrastructure with API-native IoT platforms.
France
Franchisee-led procurement of gateway hardware fragments traditional enterprise sales channels, with regional grocery cooperatives negotiating directly with Asian manufacturers. CNIL data protection authority mandates strict consent frameworks for customer-facing biometric sensors. Lyon and Marseille retail clusters drive adoption of privacy-preserving edge computing solutions.
India
Organized retail expansion by Reliance Retail and Tata creates underpenetrated terrain for full-stack IoT providers piloting computer vision networks. BIS certification requirements for imported electronics hardware extend deployment timelines. Mumbai and Bangalore concentrate smart shelf pilots targeting automated replenishment for perishable categories.
United Kingdom
Fashion retailers accelerate item-level RFID tagging for shrinkage detection, navigating post-Brexit divergence from EU equipment authorization frameworks. Information Commissioner's Office guidance constrains cross-border customer data processing for behavioral analytics. London and Manchester anchor demand for cloud-native inventory visibility platforms.
IoT in Retail Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors bridge hardware, software, and connectivity layers. The vendor base organizes around three tiers: cloud hyperscalers controlling data pipelines, networking specialists anchoring in-store connectivity, and component suppliers capturing silicon economics. Two archetypes command attention: vertically integrated platform providers and narrow specialists in endpoint silicon. Competitive intensity concentrates on M&A activity targeting edge AI capabilities and geographic expansion into underpenetrated Asian markets.
Among cloud-native platform providers, Amazon.com Inc. and Microsoft Corp. occupy positions anchoring retail data infrastructure, while Impinj Inc. exemplifies the specialized silicon tier controlling RAIN RFID endpoint supply. These three entities represent the dominant competitive anchors—platform scale versus component specialization—shaping margin capture across the value chain.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Nedap NV |
| Amazon.com Inc. |
| Honeywell International Inc. |
| Impinj Inc. |
| Cisco Systems Inc. |
| Microsoft Corp. |
| Cooler Screens |
| IBM Corp. |
| Others |
Supply Flow & Price Mechanics
Captive silicon fabrication for RAIN RFID endpoint chips anchors supply positioning and pricing power for tag vendors serving fashion retailers, while outsourced gateway assembly from Shenzhen-based contract manufacturers compresses margins for edge hardware providers competing on per-store deployment costs.
Pricing Analysis
Silicon wafer cost pass-through dominates RAIN RFID tag economics, with foundry capacity allocation risk forcing tag vendors toward long-term offtake contracts that lock in volume commitments. Price differentiation rests on firmware customization depth and FCC Part 15 certification tier, with fully certified interrogators commanding premium positioning over uncertified modules. Cost compression in gateway hardware intensifies because franchisee-led procurement bypasses traditional systems integrator markups. Regional grocery cooperatives in southern Europe exhibit the sharpest price sensitivity, while enterprise grocery chains in the United States prioritize latency performance over per-unit hardware costs.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to European retail estates complicates just-in-time gateway deployment timelines for computer vision-embedded smart shelves. Component sourcing concentrates in Taiwan for GPU silicon, South Korea for memory modules, and China for Bluetooth Low Energy beacon assembly. Raw material dependencies span gallium arsenide for RF front-ends, rare earth elements for magnetics in shelf sensors, and copper-laminated substrates for RFID inlays. Single-source vulnerability in RAIN RFID endpoint foundry capacity exposes tag vendors to allocation shocks during semiconductor demand surges. Distribution runs through direct manufacturer relationships with franchisee associations, bypassing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT in retail market compounds steadily as smart checkout deployment across grocery chains generates recurring hardware refresh cycles and firmware upgrade revenue streams.
For Market Incumbents: Lock in channel control through exclusive gateway supply agreements with top-ten grocery chains, insulating against Shenzhen-based manufacturer encroachment. Deepen backward integration into RAIN RFID endpoint silicon through captive foundry relationships, reducing exposure to semiconductor allocation risk. Prioritize GDPR-compliant edge computing architectures to capture European franchisee procurement migrating from cloud-heavy stacks. For New Entrants and Emerging Players: Begin with computer vision-embedded smart shelf pilots in India's organized retail expansion, where Reliance Retail and Tata operations represent underpenetrated terrain lacking incumbent relationships. Target Mumbai and Bangalore retail clusters with localized BIS certification support and Hindi-language technical documentation. Pursue direct manufacturer-to-franchisee sales models that bypass systems integrator markups and compress deployment timelines. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated platform providers because edge AI talent scarcity forces retailers toward bundled hardware-software-vendor relationships rather than best-of-breed component sourcing. The 5-10 year viability window favors acquisitions of gateway manufacturers with GPU-accelerated inference capabilities and existing FCC Part 15 certification portfolios. Monitor FCC equipment authorization backlog duration as an inflection indicator for hardware vendor pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Capability Acquisition | GPU-accelerated inference talent scarcity forces retailers toward bundled vendor relationships. |
| GDPR-Compliant Architecture Development | CNIL consent mandates create service revenue for privacy-preserving edge computing solutions. |
| Direct Franchisee Channel Establishment | Regional grocery cooperatives in Spain and Italy negotiate directly with Asian manufacturers. |
| RAIN RFID Silicon Capacity Securement | Foundry allocation risk during semiconductor demand surges threatens tag vendor margins. |
| India Market Entry Localization | BIS certification requirements and organized retail expansion create first-mover advantages. |
Methodological Framework
Bottom-up brick-and-mortar deployment modeling reconciled against top-down silicon supply tracking forms the analytical core, combining primary interviews with IoT platform engineering directors, grocery chain procurement officers, RFID systems integrators, and FCC regulatory consultants with secondary validation from SEC filings, customs import records, and equipment authorization databases. Primary fieldwork captured deployment timelines, hardware refresh cycles, and franchisee procurement decision criteria across United States, German, French, and Indian retail estates. Secondary sources span FDA Food Safety Modernization Act traceability guidance, EU AI Act risk classification documentation, and BIS electronics certification requirements.
Historical trendline analysis of smart checkout deployment velocity and RAIN RFID tag volume shipments established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include hardware form factor, software layer, operational use case, and geographic regulatory cluster. CAGRs derive from installed base expansion rates, replacement cycle compression, and average revenue per store trajectories. Industry-specific forecast inputs incorporate FCC equipment authorization timeline distributions and GDPR compliance architecture adoption curves.
Caveats apply where semiconductor foundry allocation shocks, biometric privacy law fragmentation across Illinois BIPA and emerging state statutes, or EU AI Act enforcement intensity could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Internet of Things in Energy Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market