
 Wifi IoT Market | 2026-2036
Wifi IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Wifi IoT Market Analytics
Enterprise-grade WiFi 6 certification is rotating from niche premium to baseline procurement threshold across industrial deployments. Cisco Systems leverages its networking hardware dominance to anchor gateway sales into manufacturing environments. Qualcomm differentiates through silicon specialization for low-latency IoT chipsets. Huawei Technologies competes aggressively on price in emerging market infrastructure builds.
Wifi IoT encompasses wirelessly connected devices that transmit telemetry, control signals, and status data over IEEE 802.11 protocols, typically operating in 2.4 GHz or 5 GHz bands with throughput requirements scaling from 20 kbps for sensors to 9.6 Gbps for WiFi 6 video streams. Its primary purpose is enabling real-time monitoring and automation without dedicated wired infrastructure. Smart Sensors within the Device Type dimension occupy the highest volume tier though Wearable Devices generate superior per-unit margins. WiFi 6 within the Technology dimension leads replacement cycles as enterprises retire WiFi 5 installations. Smart Healthcare within the Application dimension represents the fastest structural expansion as hospitals consolidate device management onto unified wireless fabrics.
The FCC in the United States governs spectrum allocation and device certification for unlicensed WiFi operations, while the EU Cyber Resilience Act and CE marking framework collectively reshape product design requirements for devices entering European markets. China's MIIT enforces domestic cybersecurity review standards that foreign vendors must satisfy for network equipment approvals. Stakeholders must monitor evolving spectrum policy in major economies and pre-position compliance investments before certification deadlines harden market access barriers.
Market Dynamics
WiFi 6 protocol migration is compressing replacement cycles across industrial wireless deployments, forcing infrastructure vendors to recertify hardware stacks against stricter latency benchmarks while hospital networks consolidate device management onto unified fabrics.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory baseline security certifications for connected devices entering member states are accelerating enterprise procurement of pre-certified hardware. German industrial automation corridors anchor smart factory rollouts.
- Smart healthcare facilities:Hospital networks are driving device deployment as WiFi 6 standards replace legacy protocols, consolidating telemetry, control signals, and status data onto unified wireless fabrics.
- Low-latency silicon specialization:Chipset architectures optimized for sub-10ms response times are enabling real-time automation in manufacturing environments without dedicated wired infrastructure.
Market Restraints
- Input cost volatility:RF component supply concentrates among a limited base of specialized foundries, exposing procurement budgets to semiconductor wafer pricing fluctuations.
- Regulatory fragmentation:China's MIIT enforces domestic cybersecurity review standards that foreign vendors must satisfy, creating parallel certification tracks and extending time-to-market for network equipment approvals.
- Technical limitation:WiFi 6E spectrum access remains uneven across national regulators, constraining deployment of 6 GHz-dependent applications in markets without allocation clarity.
Strategic Opportunities
- Underpenetrated industrial verticals:India's manufacturing hubs present white space for WiFi 6 infrastructure builds as domestic automation adoption accelerates under PLI scheme incentives.
- Technology convergence:Edge computing architectures merging with WiFi 6 access points are enabling localized data processing for latency-sensitive control loops in smart factory environments.
- Regulatory tailwind:Japan's METI efficiency mandates for industrial facilities are creating preference shifts toward connected sensor networks that WiFi 6 fabrics can consolidate.
Industry Challenges
- Certification timeline compression:FCC device certification for unlicensed WiFi operations now runs parallel to EU CE marking and MIIT review cycles, stretching engineering resources across three regulatory tracks.
- Integration complexity:Legacy WiFi 5 installations in hospital and factory environments require phased migration strategies that preserve operational continuity during protocol transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wifi IoT Market |
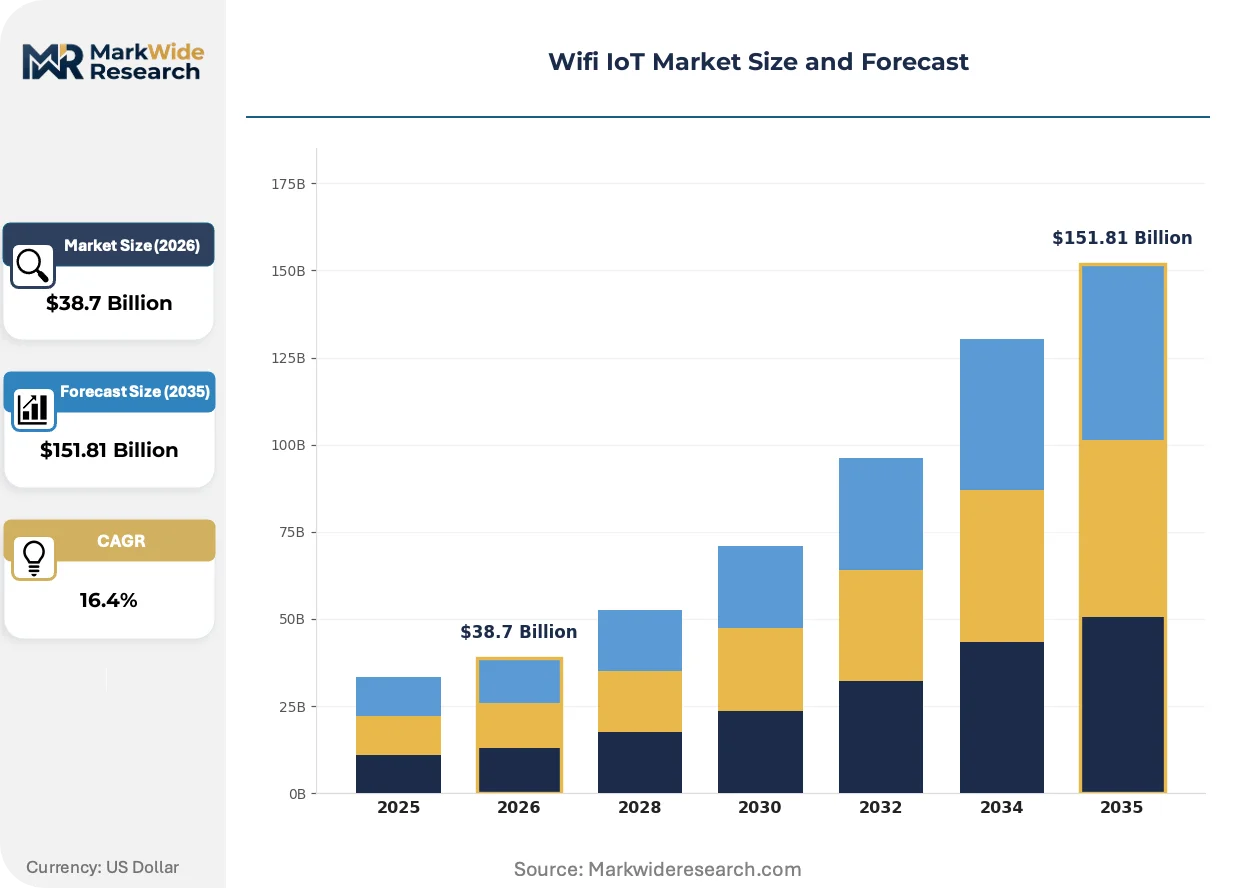
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Sensors, Smart Appliances, Wearable Devices, Security Cameras Technology: WiFi 6, WiFi 5, Mesh Networking, Cloud-Based Solutions Application: Home Automation, Industrial Monitoring, Smart Healthcare, Smart Retail End User: Residential, Commercial, Healthcare Facilities, Industrial Sites |
| Companies Covered | Amazon Web Services, Microsoft, Cisco Systems, Intel, Qualcomm, Huawei Technologies, IBM, Broadcom, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wifi IoT Market Evolving Landscape
Active protocol migration is reshaping competitive positioning across the wireless infrastructure layer, with silicon specialization and regulatory compliance emerging as the primary axes of differentiation.
WiFi 6 is supplanting legacy 802.11ac installations in industrial settings. Manufacturing facilities in Germany's automation corridor are retiring WiFi 5 access points at accelerated cadences. This protocol shift is compressing hardware refresh cycles from seven-year norms toward four-year replacement windows.
The EU Cyber Resilience Act is mandating baseline security certifications for connected devices sold in member states. Product design requirements now embed hardware security modules and firmware signing as standard features. Smart healthcare facilities face the steepest compliance burden as hospitals consolidate mixed-vendor device fleets onto unified wireless fabrics.
Buyer procurement patterns are rotating from best-of-breed component selection toward pre-integrated system contracts. Hospital IT departments are favoring single-vendor wireless fabric solutions that bundle access points, management software, and security certification. This concentration is most visible in German and French healthcare networks where procurement authority has centralized at regional system levels.
Wifi IoT Market Segmentation
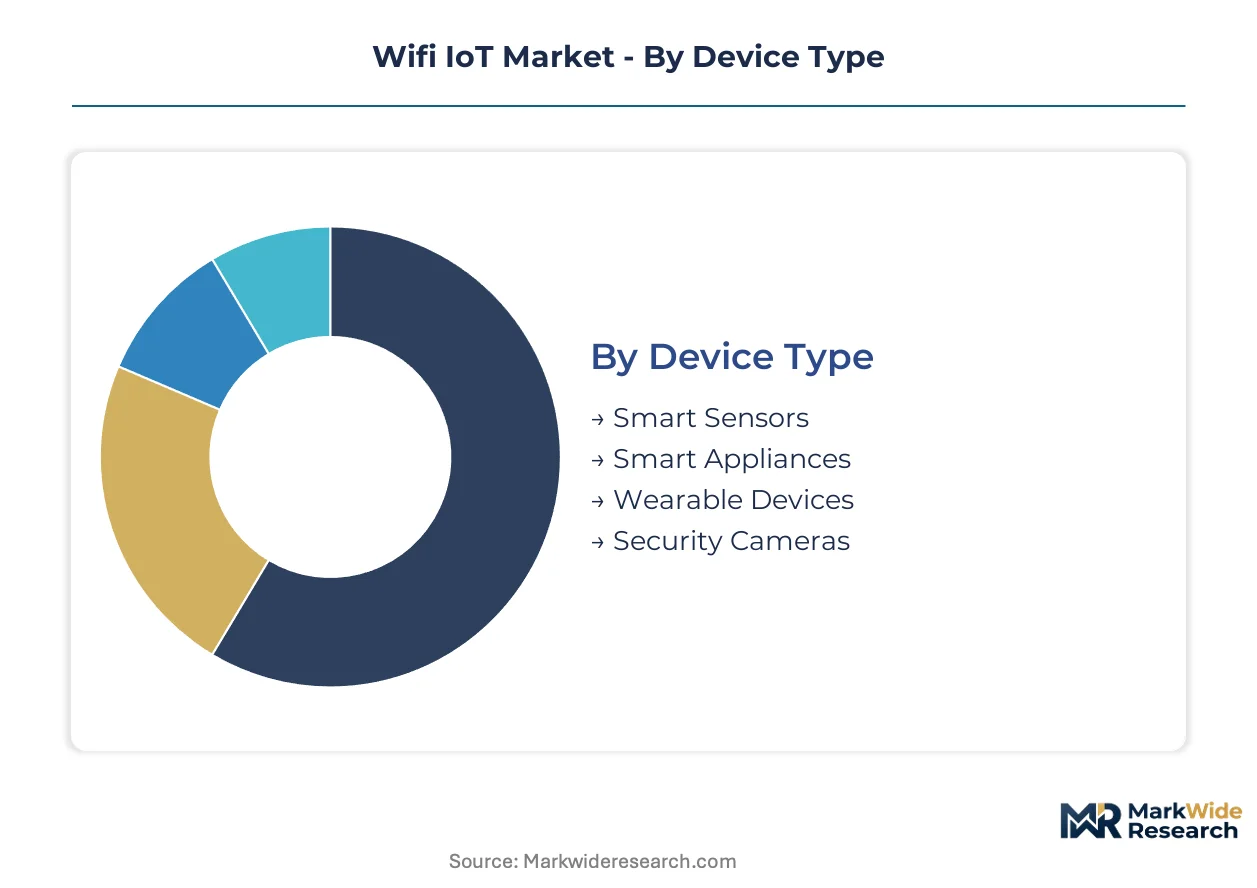
Device type, technology generation, and application vertical each impose distinct certification burdens and procurement cycles. Procurement committees weight these dimensions differently depending on whether deployments target regulated healthcare environments or price-sensitive residential installations.
Device Type:
FCC device certification for unlicensed WiFi operations varies in stringency across device categories, with medical-adjacent hardware facing elevated RF exposure testing requirements.
- Smart Sensors:Compact telemetry units transmitting status data at 20 kbps over 2.4 GHz bands. Demand concentrates in Germany's industrial automation corridor where Siemens and Bosch anchor smart factory rollouts requiring sub-10ms response times for control loops.
- Wearable Devices:Battery-optimized form factors with integrated biometric acquisition and local edge processing. Smart healthcare facilities in France and Germany are consolidating these onto unified WiFi 6 fabrics to satisfy EU Cyber Resilience Act baseline security certifications.
- Smart Appliances:White goods and HVAC controllers with intermittent connectivity requirements and multi-year replacement cycles.
- Security Cameras:Video streaming endpoints demanding 9.6 Gbps throughput for WiFi 6-dependent 4K analytics feeds.
Established volume favors Smart Sensors; emerging adoption favors Wearable Devices.
Technology:
Cost tier stratification separates enterprise-grade infrastructure from consumer-grade hardware, with certification complexity widening the procurement gap between tiers.
- WiFi 6:IEEE 802.11ax protocol with OFDMA scheduling and target wake time for battery-constrained IoT. Hospital networks across the United States, Germany, and Japan are retiring WiFi 5 installations at accelerated cadences to consolidate device management onto unified wireless fabrics.
- WiFi 5:Legacy 802.11ac installations requiring phased migration strategies that preserve operational continuity during protocol transitions.
- Mesh Networking:Self-healing multi-hop topologies extending coverage without wired backhaul in residential and light commercial settings.
- Cloud-Based Solutions:Centralized management planes abstracting firmware updates and security policy across distributed device fleets.
Procurement momentum concentrates in WiFi 6; residual replacement cycles sustain WiFi 5 through mid-decade.
Application:
Margin structure varies sharply across verticals, with regulated healthcare commanding certification premiums and residential automation competing on bill-of-materials efficiency.
- Smart Healthcare:Clinical-grade telemetry and patient monitoring systems subject to HIPAA in the United States and MDR in Europe. This vertical is climbing the fastest as hospitals consolidate mixed-vendor device fleets onto unified wireless fabrics with embedded hardware security modules.
- Industrial Monitoring:Predictive maintenance sensors and environmental controls in manufacturing environments.
- Home Automation:Consumer lighting, climate, and entertainment integration with price elasticity limiting silicon specialization.
- Smart Retail:Inventory tracking and customer analytics deploying beacon density at scale.
Certification overhead elevates Smart Healthcare margins; volume scale concentrates in Home Automation.
End User:
Customer type determines procurement authority centralization, with healthcare networks and industrial sites consolidating vendor selection at regional system levels.
- Healthcare Facilities:Hospital IT departments with centralized procurement authority favoring single-vendor wireless fabric solutions that bundle access points, management software, and EU Cyber Resilience Act pre-certification.
- Industrial Sites:Manufacturing engineering teams specifying latency benchmarks for real-time automation without dedicated wired infrastructure.
- Commercial:Office and retail property managers balancing coverage density against operational expenditure constraints.
- Residential:Individual consumers selecting best-of-breed components through retail channels with minimal integration requirements.
Procurement consolidation favors Healthcare Facilities; unit volume concentrates in Residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's manufacturing hubs exhibit acute price sensitivity, while German hospital networks prioritize certification compliance over procurement cost, creating divergent demand elasticity across major deployment zones.
United States
FCC spectrum allocation for unlicensed WiFi operations drives infrastructure investment across hospital networks and industrial corridors. HIPAA compliance requirements elevate procurement standards for clinical-grade telemetry systems. The Southeast manufacturing belt and Texas industrial parks anchor smart factory rollouts demanding sub-10ms latency benchmarks.
Germany
Siemens and Bosch anchor automation demand in the industrial corridor stretching from Munich to Stuttgart. The EU Cyber Resilience Act mandates baseline security certifications for connected devices entering member states. Bavaria's smart factory clusters are retiring WiFi 5 installations at accelerated cadences to satisfy latency requirements for real-time control loops.
China
MIIT enforces domestic cybersecurity review standards that foreign vendors must satisfy for network equipment approvals. The Yangtze River Delta and Pearl River Delta manufacturing hubs drive volume demand for WiFi 6 infrastructure builds. Shenzhen and Shanghai anchor aggressive price competition among infrastructure vendors.
Japan
METI efficiency mandates for industrial facilities create preference shifts toward connected sensor networks. WiFi 6E spectrum allocation remains uneven, constraining 6 GHz-dependent applications in markets without regulatory clarity. The Chubu region around Nagoya and Kansai corridor near Osaka concentrate automotive and electronics manufacturing automation.
India
PLI scheme incentives accelerate domestic automation adoption across manufacturing hubs. TRAI spectrum policy evolution shapes deployment economics for industrial wireless networks. Maharashtra and Gujarat industrial corridors present white space for WiFi 6 infrastructure builds as engineering teams specify latency benchmarks for predictive maintenance sensors.
Wifi IoT Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the WiFi IoT infrastructure layer. The vendor base stratifies into three tiers: integrated platform providers, silicon specialists, and regional infrastructure builders. Network hardware incumbents and cloud platform operators represent distinct strategic archetypes. Competitive moves concentrate on strategic partnerships for vertical integration and geographic licensing arrangements for regulatory pre-positioning.
Within the integrated platform tier, Cisco Systems and Amazon Web Services occupy positions spanning hardware and cloud management planes. Qualcomm exemplifies silicon specialization for low-latency IoT chipsets. Huawei Technologies anchors price-competitive positioning in emerging market infrastructure builds. These three players represent the dominant archetype configurations: full-stack integration, component specialization, and cost-optimized regional deployment.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Cisco Systems |
| Intel |
| Qualcomm |
| Huawei Technologies |
| IBM |
| Broadcom |
| Siemens |
| Others |
Value Network & Pricing Analysis
Foundry scale economies in Taiwan and South Korea concentrate RF component manufacturing among a limited supplier base, compressing margins for WiFi 6 chipset vendors while elevating price floors for enterprise-grade access points that must absorb certification and silicon specialization costs.
Pricing Analysis
The EU Cyber Resilience Act dictates the pricing tier structure across European deployments, separating pre-certified hardware bundles from uncertified commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because Shenzhen-based vendors flood residential channels with WiFi 5 legacy stock. Healthcare facilities in Germany and France exhibit lowest price sensitivity due to centralized procurement authority and compliance mandates.
Supply Chain Analysis
Port congestion along the Shanghai-Ningbo corridor and container availability constraints on the transpacific eastbound lane elevate inbound logistics costs for North American infrastructure deployments. Semiconductor wafer supply concentrates in Taiwan, South Korea, and the United States, while RF filter and power amplifier components draw from Japanese and German specialty manufacturers. Single-source vulnerability in 6 GHz RF front-end modules creates exposure for WiFi 6E product lines awaiting regulatory clarity. Distribution runs through OEM-direct contracts for enterprise healthcare and industrial accounts, with retail channels serving residential automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular LPWAN substitution threatens WiFi IoT in low-bandwidth sensor applications, forcing incumbents to defend protocol relevance through latency performance and unified fabric consolidation.
For Market Incumbents: Fortify gateway hardware margins by embedding hardware security modules that satisfy EU Cyber Resilience Act pre-certification requirements, creating switching costs for hospital IT departments. Deepen backward integration into RF component sourcing through foundry partnerships in Taiwan to offset wafer pricing volatility. Counter cellular substitution threats by emphasizing sub-10ms latency benchmarks that 5G IoT cannot economically match at scale.
For New Entrants and Emerging Players: Lead with India's PLI scheme corridors as the most penetrable geography, where domestic automation adoption accelerates without entrenched vendor relationships. Target predictive maintenance sensor networks in Maharashtra and Gujarat industrial clusters as the whitespace application. Pursue channel partnerships with Siemens and Bosch ecosystem integrators as the go-to-market angle rather than direct enterprise sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silicon specialists with low-latency IoT chipset portfolios over full-stack hardware vendors facing compressed replacement cycles. Long-term viability rests on regulatory pre-positioning across FCC, CE marking, and MIIT certification tracks simultaneously. Acquisition target archetype: regional infrastructure builders with existing MIIT approvals and Yangtze River Delta manufacturing relationships. Monitor 6 GHz spectrum allocation clarity in Japan and India as the signal to watch for WiFi 6E inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Cyber Resilience Act Pre-Certification | Hardware security module integration accelerates hospital procurement cycles in Germany and France. |
| Low-Latency Silicon Specialization | Sub-10ms chipset architectures differentiate industrial automation deployments against cellular alternatives. |
| India PLI Corridor Expansion | Maharashtra and Gujarat manufacturing hubs present whitespace for WiFi 6 infrastructure builds. |
| Edge Computing Convergence | Localized data processing at WiFi 6 access points enables latency-sensitive smart factory control loops. |
| Multi-Regulatory Certification Parallelization | Simultaneous FCC, CE marking, and MIIT tracks reduce time-to-market for network equipment vendors. |
Research Methodology
Operator-level perspectives from hospital IT directors, industrial automation engineers, semiconductor procurement leads, and wireless infrastructure deployment managers anchored the qualitative base. Primary interviews combined with secondary validation against FCC device certification databases, EU CE marking registries, MIIT network equipment approval filings, and hyperscaler capex disclosures. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending analysis across the United States, Germany, China, Japan, and India.
Sensitivity analysis tested forecast outputs against regulatory timeline delays, semiconductor wafer pricing volatility, and 6 GHz spectrum allocation uncertainty across the projection horizon. Segmentation dimensions modeled include device type, technology generation, application vertical, and end-user procurement authority structure, with regional regulatory cluster as an industry-specific overlay. CAGRs derived from replacement cycle compression analysis and enterprise procurement pattern shifts, incorporating WiFi 5 retirement cadences and WiFi 6E adoption elasticity as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained enterprise infrastructure spending, harmonized cybersecurity certification timelines, or stable RF component supply would require recalibration. Forecasts reflect documented assumptions regarding protocol migration rates and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Location of Things Market