
 Global Smart Offices Market | 2026-2036
Global Smart Offices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Offices Market Foresight
The capital-intensity divergence between full-stack platform providers and point-solution vendors is collapsing as cloud infrastructure commoditizes hardware deployment. Schneider Electric leverages its integrated building automation portfolio to anchor large corporate campus contracts across Europe. Siemens AG competes through deep manufacturing scale in HVAC-integrated control systems. Johnson Controls International Plc specializes in security-system convergence with environmental monitoring, extending its footprint in North American government office retrofits.
Smart offices encompass networked building systems that deploy IoT sensors, artificial intelligence, and edge computing to automate lighting, climate, security, and spatial utilization across commercial facilities, typically operating through centralized cloud platforms with sub-second local processing at the edge. Building automation solutions dominate current revenue as legacy HVAC and lighting retrofits absorb the majority of capital expenditure, while workspace analytics represents the fastest-expanding margin pool as corporate tenants demand occupancy-driven lease economics. Energy management applications are maturing in technology parks where solar microgrids and battery storage integration has standardized, though machine learning-based predictive maintenance remains underpenetrated in co-working spaces with high churn and fragmented ownership.
The EU AI Act imposes risk-classification requirements on automated decision systems in workplace environments, compelling vendors to redesign algorithmic transparency features for European deployments. The EPA's ENERGY STAR certification program and Japan's METI building efficiency standards both mandate granular energy disclosure, directly stimulating procurement of cloud-connected metering infrastructure. Stakeholders must monitor whether national data-localization rules fragment cloud architecture strategies or consolidate vendor selection around regionally compliant platform operators.
Market Dynamics
Cloud infrastructure commoditization is collapsing capital barriers between full-stack platform providers and point-solution vendors, forcing Schneider Electric, Siemens AG, and Johnson Controls International Plc to compete directly on deployment speed rather than hardware differentiation. This structural compression accelerates vendor consolidation across European and North American corporate campus contracts.
Growth Catalysts
- EU AI Act risk-classification mandates:Automated decision systems in workplace environments now require algorithmic transparency features, compelling vendors to redesign European deployments and creating upgrade cycles for legacy sensor networks.
- Japan METI building efficiency standards:Granular energy disclosure mandates stimulate procurement of cloud-connected metering infrastructure across Tokyo and Osaka commercial districts.
- Edge computing sub-second processing:Localized data processing at building perimeters reduces latency for climate and security automation, enabling real-time responsiveness that cloud-only architectures cannot match.
Market Restraints
- Silicon supply concentration:IoT sensor chip fabrication concentrates in Taiwan and South Korea, exposing deployment timelines to geopolitical disruption and foundry allocation constraints.
- Copper and rare earth price volatility:HVAC-integrated control systems and power distribution hardware face input cost instability from concentrated mining operations in Chile and the Democratic Republic of Congo.
- Legacy BACnet protocol incompatibility:Decades-old building automation networks resist seamless integration with IP-based smart office platforms, forcing expensive gateway middleware or full infrastructure replacement.
Strategic Opportunities
- Co-working space predictive maintenance:Machine learning-based failure anticipation remains underpenetrated in high-churn, fragmented-ownership environments across London, Berlin, and New York.
- India BIS smart building standards:Emerging certification frameworks for commercial real estate in Mumbai and Bangalore create first-mover advantage for vendors establishing local cloud infrastructure partnerships.
- Solar microgrid-battery storage convergence:Technology parks in Germany and California standardize distributed energy resource integration, opening bundled platform contracts that combine metering, storage optimization, and workspace analytics.
Industry Challenges
- Cross-functional talent scarcity:Facility managers lack training in both HVAC engineering and data science, slowing deployment of AI-driven climate optimization systems.
- Multi-vendor cybersecurity certification:Fragmented sensor ecosystems from lighting, access control, and environmental monitoring suppliers create compliance complexity under ISO 27001 and IEC 62443 frameworks.
- Lease structure misalignment:Tenant improvement allowances rarely cover smart infrastructure capex, while landlords recover costs through base rent adjustments that delay payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Offices Market |
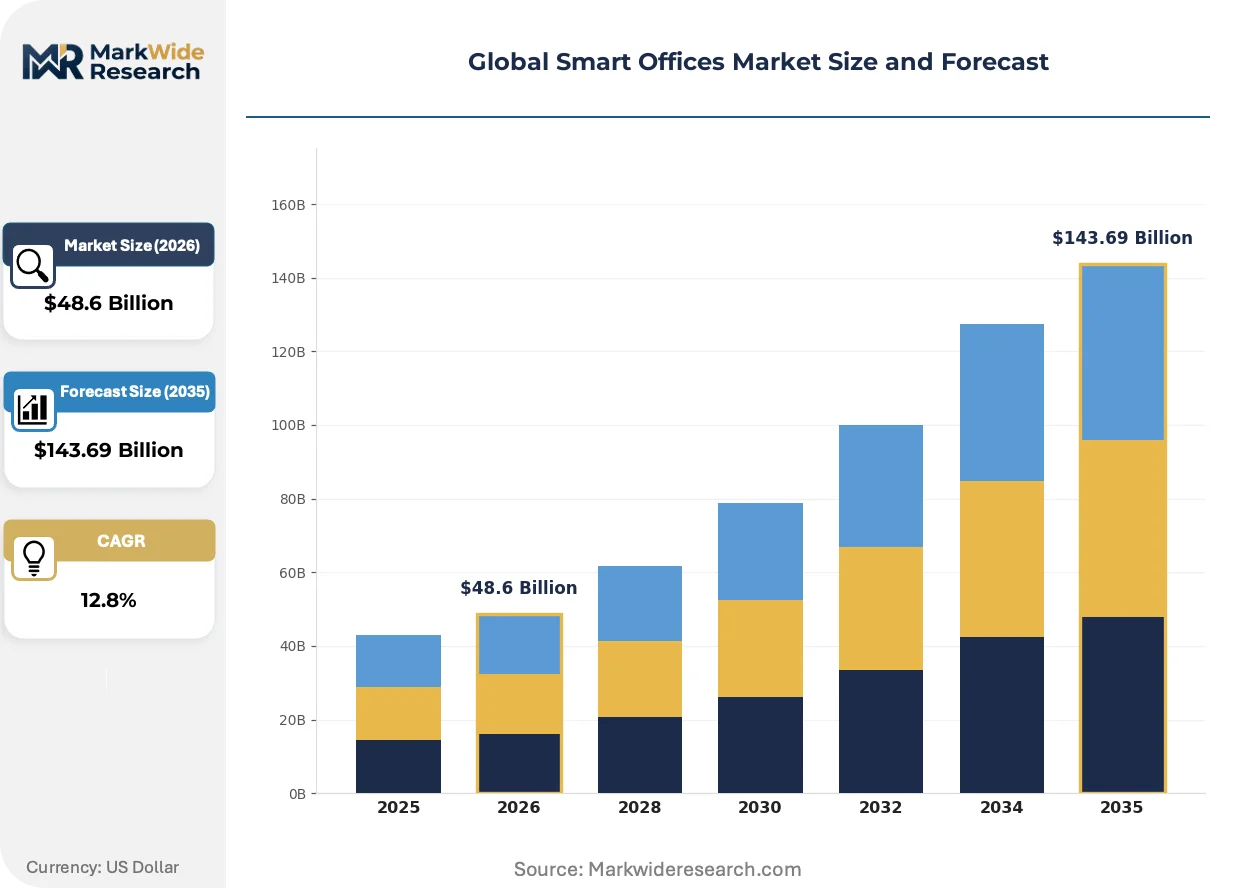
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $143.69 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Building Automation, Security Systems, Energy Management, Workspace Analytics, Collaboration Tools Technology: IoT Sensors, Artificial Intelligence, Machine Learning, Cloud Computing, Edge Computing Application: Space Optimization, Resource Scheduling, Environmental Monitoring, Employee Productivity, Asset Tracking End User: Corporate Campuses, Co-working Spaces, Government Offices, Technology Parks, Educational Institutions |
| Companies Covered | Schneider Electric, Siemens AG, Johnson Controls International Plc, Honeywell International Inc., ABB Ltd., Cisco Systems Inc., Lutron Electronics Co. Inc., Signify Holding, Crestron Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Offices Market Shifts & Advancements
Digital twin architecture is replacing static building management dashboards with dynamic simulation layers that predict occupancy patterns and energy loads. This shift compresses the feedback loop between spatial design and operational performance.
LiDAR-based spatial analytics is supplanting traditional PIR motion sensors for occupancy detection. Corporate real estate teams in Frankfurt and San Francisco deploy ceiling-mounted depth sensors to capture precise headcount and movement patterns. This technology is supplanting lease economics based on square footage with outcome-based pricing tied to actual utilization rates.
EPA ENERGY STAR certification program revisions now mandate continuous commissioning data streams rather than annual spot audits. Commercial property owners in Chicago and Houston retrofit legacy buildings with permanent submetering infrastructure to maintain eligibility. Large portfolio operators respond by centralizing facility data lakes that aggregate across dozens of properties for automated compliance reporting.
Corporate tenants now specify API-accessible building systems in lease negotiations, rejecting proprietary black-box platforms that lock operational data behind vendor portals. Landlords in Amsterdam and Singapore respond by demanding open-protocol guarantees from system integrators. This behavioral shift concentrates procurement authority with enterprise IT departments rather than traditional facilities management, altering vendor sales cycles and technical requirements documentation.
Global Smart Offices Market Segmentation
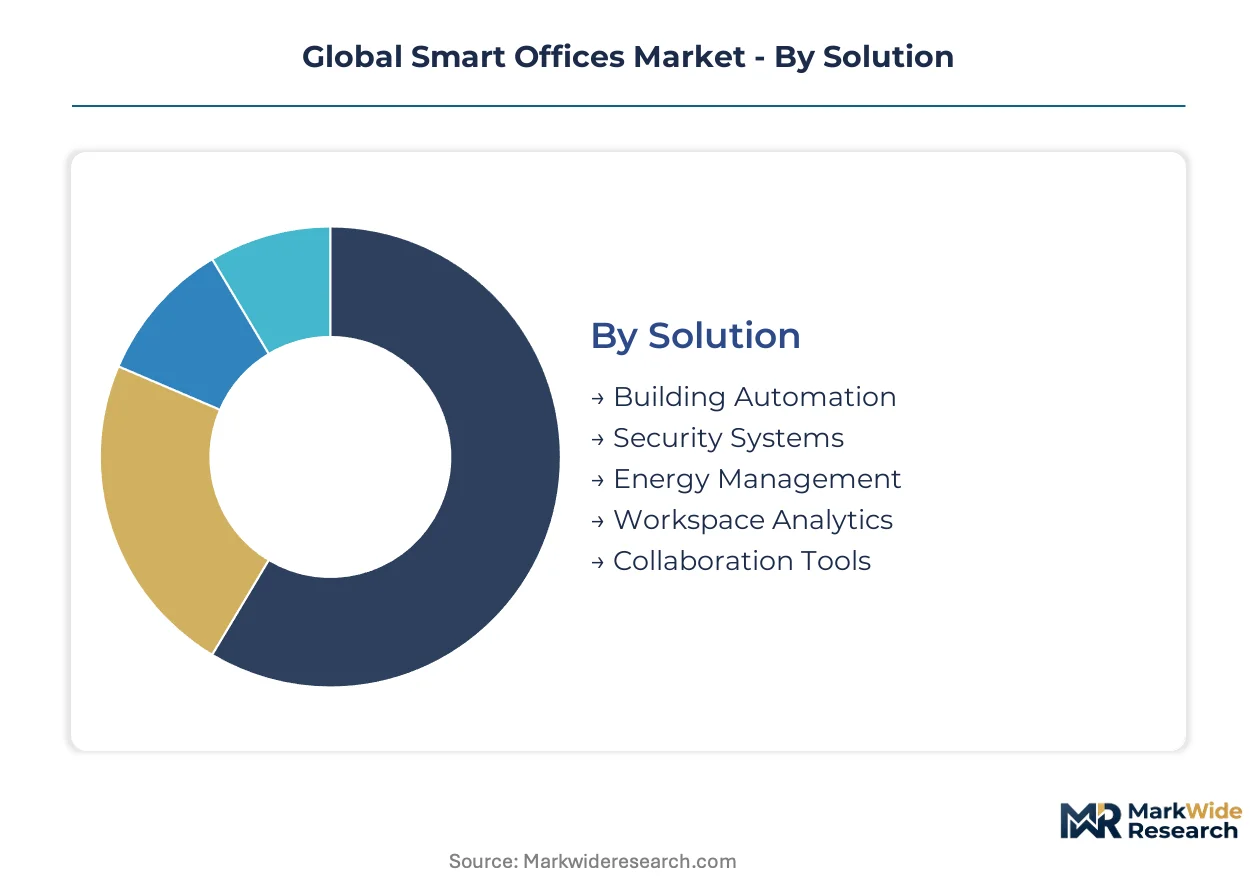
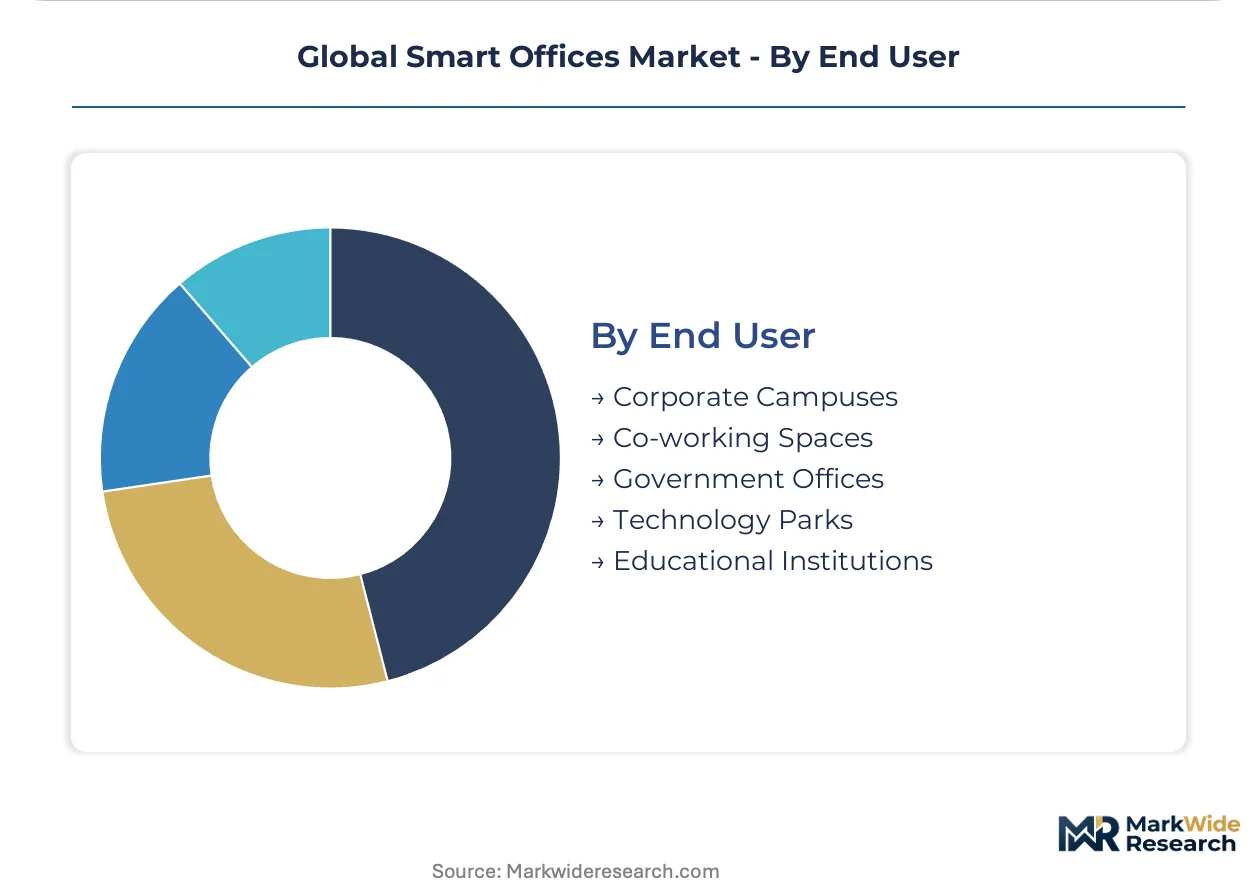
Segmentation in smart offices reveals how procurement authority shifts between facilities management and enterprise IT based on solution complexity. Vendors must calibrate sales approaches across distinct buyer profiles with divergent technical fluency and budget authority.
Solution:
EU AI Act risk-classification tiers and EPA ENERGY STAR disclosure mandates are reshaping which solution categories absorb capital expenditure versus operating budgets.
- Building Automation:Integrated HVAC, lighting, and access control systems operating through BACnet or IP-based protocols. Corporate campuses in Germany and the United States dominate procurement as green building codes tighten thermal performance requirements.
- Security Systems:Biometric access control, video analytics, and intrusion detection with AI-enabled threat classification. Government offices across North America and Europe drive demand following cybersecurity directives for critical infrastructure protection.
- Energy Management:Cloud-connected metering infrastructure with solar microgrid integration.
- Workspace Analytics:Occupancy sensing and utilization tracking for lease economics optimization.
- Collaboration Tools:Integrated AV systems with room booking and hybrid work coordination.
Established volume favors Building Automation; emerging adoption favors Workspace Analytics.
Technology:
Cost tiers separate legacy retrofit compatibility from greenfield AI-native deployments, with edge infrastructure commanding premium pricing over pure cloud architectures.
- IoT Sensors:Distributed environmental, occupancy, and energy monitoring devices with wireless mesh networking. Technology parks in California and Germany standardize deployment as base infrastructure for all subsequent platform layers.
- Artificial Intelligence:Predictive algorithms for climate optimization, security anomaly detection, and space utilization forecasting. Co-working spaces in London and New York represent the steepest expansion trajectory as operators compete on operational efficiency.
- Machine Learning:Adaptive models refining predictions based on building-specific occupancy patterns.
- Cloud Computing:Centralized data lakes aggregating multi-property portfolios for compliance reporting.
- Edge Computing:Sub-second local processing at building perimeters for latency-critical automation.
Maturity concentration sits with IoT Sensors; capability differentiation centers on Edge Computing.
Application:
Customer type determines whether applications prioritize cost reduction or employee experience metrics, splitting vendor roadmaps between operational efficiency and talent retention value propositions.
- Space Optimization:LiDAR and depth-sensor analytics converting square footage metrics to actual utilization rates. Corporate real estate teams in Frankfurt and San Francisco deploy ceiling-mounted systems to renegotiate lease economics.
- Environmental Monitoring:Continuous air quality, thermal comfort, and lighting quality tracking with automated remediation. Educational institutions in Japan and the United States adopt systems following ventilation standards revisions.
- Resource Scheduling:Room booking platforms integrated with calendar systems and occupancy sensors.
- Employee Productivity:Biometric and behavioral analytics correlating environmental conditions with performance metrics.
- Asset Tracking:Real-time location systems for equipment, furniture, and personnel movement patterns.
Procurement scale favors Space Optimization; regulatory tailwinds favor Environmental Monitoring.
End User:
Ownership structure fragments procurement cycles, with landlord-controlled assets facing misaligned incentive structures compared to corporate-owned campuses.
- Corporate Campuses:Single-tenant facilities with centralized IT and facilities management. Schneider Electric and Siemens AG anchor large contracts across European headquarters as integrated platform requirements consolidate vendor selection.
- Government Offices:Public sector facilities with cybersecurity certification mandates and budget approval cycles. Johnson Controls International Plc extends its footprint in North American retrofits following federal efficiency directives.
- Co-working Spaces:High-churn, fragmented-ownership environments with limited capital for predictive maintenance deployment.
- Technology Parks:Multi-tenant innovation districts standardizing solar microgrid and battery storage integration.
- Educational Institutions:University and research facilities with deferred maintenance backlogs and grant-dependent procurement.
Contract value concentrates in Corporate Campuses; deployment complexity peaks in Co-working Spaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes smart office technology primarily through corporate campus retrofits, while Germany and Japan emphasize factory-integrated building systems, and India pursues greenfield certification-driven deployments.
United States
Corporate headquarters in Chicago and Houston drive demand for ENERGY STAR-compliant submetering infrastructure. The EPA's continuous commissioning mandates force portfolio operators to aggregate facility data lakes across multi-property holdings. Silicon Valley technology parks standardize solar microgrid integration with battery storage optimization.
Germany
Industrial conglomerates in Munich and Stuttgart anchor integrated building automation contracts spanning HVAC and lighting control. The EU AI Act compels vendors to redesign algorithmic transparency features for risk-classified automated decision systems. Frankfurt's financial district leads LiDAR-based spatial analytics deployment for lease economics renegotiation.
Japan
Tokyo and Osaka commercial districts stimulate procurement of cloud-connected metering infrastructure under METI building efficiency standards. Educational institutions adopt environmental monitoring systems following revised ventilation guidelines. Nagoya's manufacturing corridors integrate smart office platforms with adjacent production facilities.
India
Mumbai and Bangalore emerging certification frameworks create first-mover opportunities for vendors establishing local cloud infrastructure partnerships. The Bureau of Indian Standards develops smart building standards for commercial real estate. Hyderabad's technology parks attract bundled platform contracts combining workspace analytics with energy management.
United Kingdom
London's corporate real estate teams deploy occupancy sensing for outcome-based lease pricing tied to actual utilization rates. The Building Safety Regulator imposes digital record-keeping requirements on building system documentation. Manchester and Birmingham co-working operators compete on operational efficiency through machine learning-based space optimization.
Global Smart Offices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack platform providers competing directly on deployment speed as cloud infrastructure commoditizes hardware differentiation. The market structure compresses capital barriers between point-solution vendors and comprehensive system integrators. Two dominant competitive moves are reshaping positioning: vendor consolidation through strategic acquisitions and geographic expansion through regional cloud infrastructure partnerships. Strategic archetypes include integrated automation conglomerates, security-system convergence specialists, and lighting-control pure-plays.
Among European-integrated automation providers, Schneider Electric and Siemens AG exemplify the full-stack platform archetype through their building automation portfolios. Johnson Controls International Plc occupies a distinct position at the intersection of environmental monitoring and security-system convergence. These three anchors illustrate how vendor selection increasingly consolidates around deployment velocity rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| Johnson Controls International Plc |
| Honeywell International Inc. |
| ABB Ltd. |
| Cisco Systems Inc. |
| Lutron Electronics Co. Inc. |
| Signify Holding |
| Crestron Electronics Inc. |
| Others |
Supply & Pricing Matrix
EPA ENERGY STAR certification revisions gate both vendor qualification and price differentiation simultaneously, compelling landlords in Chicago and Houston to absorb premium hardware costs for continuous commissioning compliance while squeezing margins on legacy retrofit projects that fail disclosure thresholds.
Pricing Analysis
Long-term offtake contracts dominate corporate campus procurement as facility managers seek locked-in deployment costs across multi-year building automation rollouts. Three-tier pricing structure across premium, standard, and economy levels separates full-stack platform providers from point-solution vendors and gateway middleware suppliers. Cost compression in the economy tier is intensifying because cloud infrastructure commoditization collapses hardware differentiation. Government offices exhibit highest price sensitivity due to budget approval cycles, while technology parks show lowest sensitivity when bundling solar microgrid integration.
Supply Chain Analysis
Inventory lead times for IoT sensor chipsets stretch to six months or more as foundry allocation constraints ripple through procurement timelines. Taiwan and South Korea anchor semiconductor fabrication for edge computing modules, while China and Mexico concentrate power distribution hardware assembly. Copper and rare earth dependencies from Chile and the Democratic Republic of Congo expose HVAC-integrated control systems to commodity price volatility. Distribution runs through system integrators who consolidate multi-vendor sensor ecosystems for corporate campus contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors who control scarce cross-functional talent combining HVAC engineering with data science, as facility managers struggle to deploy AI-driven climate optimization without external implementation support.
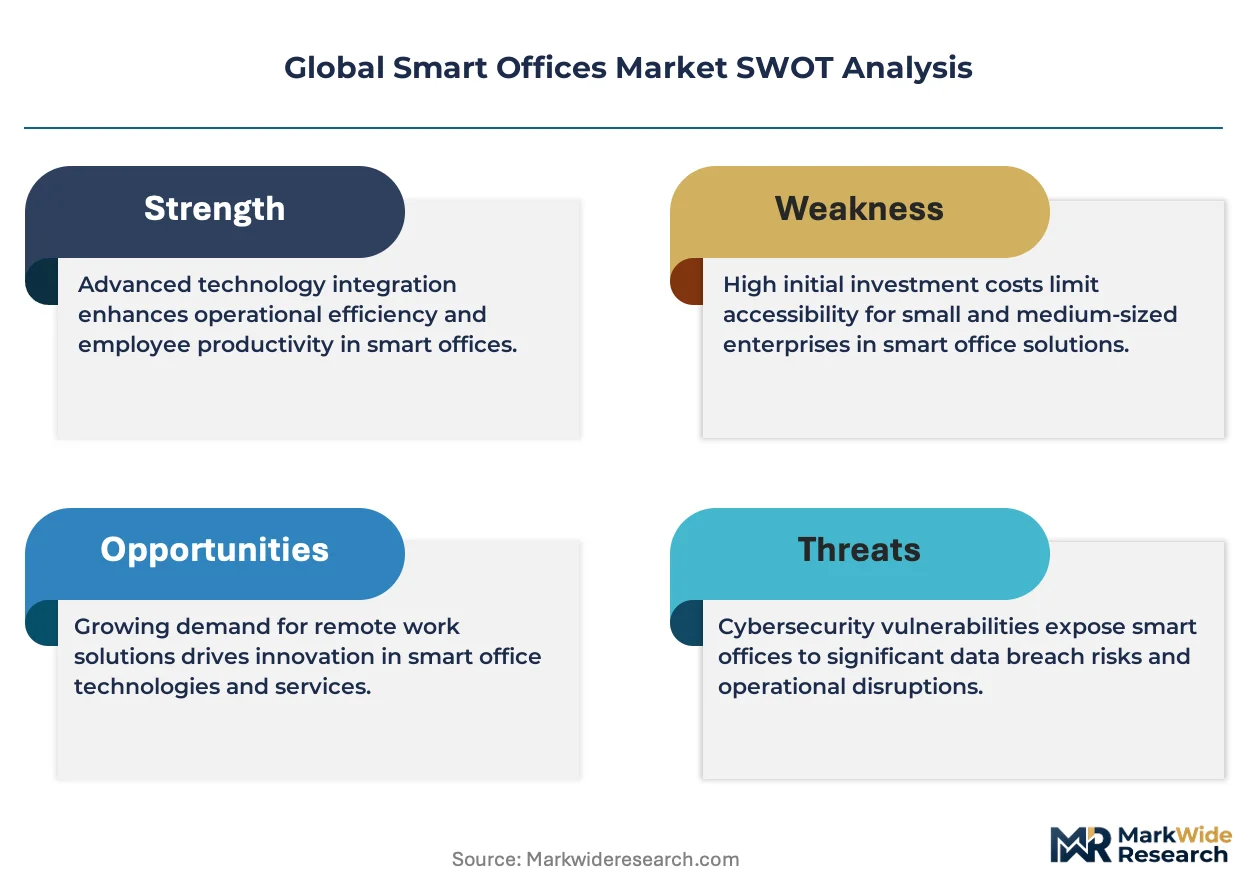
For Market Incumbents: Compound platform stickiness through deep integration of workspace analytics with existing building automation deployments. Acquire edge computing specialists to defend against cloud-native entrants attacking latency-critical automation segments. Invest in algorithmic transparency tooling ahead of EU AI Act enforcement waves. For New Entrants and Emerging Players: Differentiate on predictive maintenance capabilities for co-working spaces in London, Berlin, and New York where fragmentation and high churn have suppressed incumbent penetration. Target India BIS certification partnerships as a go-to-market anchor for greenfield commercial real estate in Mumbai and Bangalore. For Investors and Strategic Acquirers: EU AI Act risk-classification mandates reshape the acquisition landscape toward vendors with pre-built algorithmic transparency features. Five-to-ten-year viability favors platform operators with regional cloud infrastructure partnerships over hardware-dependent point-solution vendors. Watch for national data-localization rule announcements as inflection indicators for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cloud Infrastructure Partnership | Establishes compliance architecture for EU AI Act and emerging data-localization mandates. |
| Predictive Maintenance Platform Launch | Captures underpenetrated co-working space segment with machine learning-based failure anticipation. |
| Edge Computing Capability Acquisition | Secures sub-second processing differentiation for latency-critical climate and security automation. |
| Solar Microgrid Integration Bundle | Combines metering, storage optimization, and workspace analytics for technology park contracts. |
| Algorithmic Transparency Certification | Pre-qualifies European deployments ahead of automated decision system risk-classification enforcement. |
Research Methodology
The analysis maps building automation, security systems, energy management, workspace analytics, and collaboration tools, each validated through facility managers, enterprise IT procurement officers, system integrators, and commercial real estate portfolio operators. Primary interviews with these stakeholders combine with secondary validation against EPA ENERGY STAR filings, EU regulatory databases, METI efficiency standard disclosures, and BIS certification frameworks. Bottom-up deployment projections triangulate against top-down corporate capex trend analysis.
Consistency checks validate volume and value outputs against hyperscaler facility investment disclosures, green building certification databases, and regional utility rebate program uptake statistics. Segmentation dimensions span solution category, technology layer, application type, and end-user ownership structure across the projection horizon. CAGRs derive from installed base expansion rates and replacement cycle timing, with specific inputs including IoT sensor deployment density per square meter and edge computing node penetration in new construction versus retrofit.
The analysis sits within stated boundaries; outcomes outside sustained corporate real estate investment, stable semiconductor supply, or unfragmented regulatory frameworks would require recalibration. Forecasts reflect documented assumptions about technology adoption curves and compliance timeline adherence. Geopolitical disruption to Taiwan foundry output or copper supply chains represents specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
India ICT Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Service Mesh Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Shipping Software Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Europe Multichannel Order Management Market