
 Marine Internet of Things Market | 2026-2036
Marine Internet of Things Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Internet of Things Market Foresight
Project finance for satellite-IoT infrastructure is narrowing the competitive field to capitalized technology providers. Kongsberg Maritime leverages its integrated vessel control systems to bundle IoT subscriptions with propulsion automation. Wärtsilä Corporation anchors its position through captive supply of engine diagnostics hardware that feeds proprietary analytics platforms. Cisco Systems competes by extending enterprise-grade cybersecurity architectures into maritime satellite links.
Marine Internet of Things denotes networked sensor arrays, edge computing nodes, and satellite backhaul systems operating aboard commercial vessels, offshore platforms, and port infrastructure to capture real-time operational telemetry. These systems typically process data through mesh-networked gateways with latency thresholds under 100 milliseconds for engine-critical alerts. Smart Sensors and Monitoring Systems currently occupy the largest margin pools as hardware-software bundles generate recurring calibration revenues. Fleet Management applications within the Application dimension are recording the fastest uptake as charterers mandate visibility into vessel performance for demurrage calculations.
The International Maritime Organization enforces emissions verification protocols that compel shipping companies to install certified fuel-flow sensors and exhaust analyzers. The EU MRV regulation and the US Coast Guard's cyber risk management guidelines further shape product certification requirements for equipment vendors. Stakeholders must monitor how the EU AI Act's risk classifications apply to autonomous collision-avoidance algorithms before committing platform development resources.
Market Dynamics
Commercial shipping operators face simultaneous pressure from the International Maritime Organization's carbon intensity regulations and charterer demands for real-time performance visibility. This dual enforcement mechanism is compressing deployment timelines for sensor networks and edge computing infrastructure across vessel fleets.
Growth Catalysts
- EU MRV Regulation:Mandatory emissions verification protocols compel shipping companies to install certified fuel-flow sensors and exhaust analyzers, creating hardware replacement cycles across European-flagged fleets.
- Mesh-networked gateways:Latency thresholds under 100 milliseconds for engine-critical alerts are standardizing edge computing architectures that process telemetry locally before satellite backhaul.
- Norway's Kongsberg cluster:Concentrated maritime technology expertise accelerates vendor development cycles and reduces integration friction for vessel control system bundles.
Market Restraints
- Lithium battery supply:Sensor network power systems depend on battery chemistry subject to price volatility and concentrated Asian cell manufacturing capacity.
- Satellite bandwidth scarcity:L-band and Ku-band spectrum allocation constraints limit real-time data throughput for remote oceanic routes outside terrestrial coverage.
- Legacy vessel retrofit costs:Pre-2010 commercial fleets require extensive cabling and gateway installation that absorbs capital budgets otherwise allocated to newbuild sensor suites.
Strategic Opportunities
- Autonomous collision-avoidance algorithms:The EU AI Act's risk classifications will clarify certification pathways for AI-enabled navigation systems, opening regulated deployment channels.
- Port infrastructure digitization:Singapore's smart port initiatives demonstrate demand for berth optimization sensors and container tracking mesh networks in Asian transshipment hubs.
- Engine diagnostics unbundling:Charterers increasingly procure vessel performance data separately from hull and machinery insurance, creating standalone subscription revenue streams.
Industry Challenges
- Maritime cybersecurity certification:The US Coast Guard's cyber risk management guidelines require vessel operators to document sensor network vulnerability assessments, extending commissioning timelines.
- Sensor calibration workforce:Specialized technicians capable of certifying fuel-flow accuracy under ISO standards remain concentrated in Northern European maritime clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Internet of Things Market |
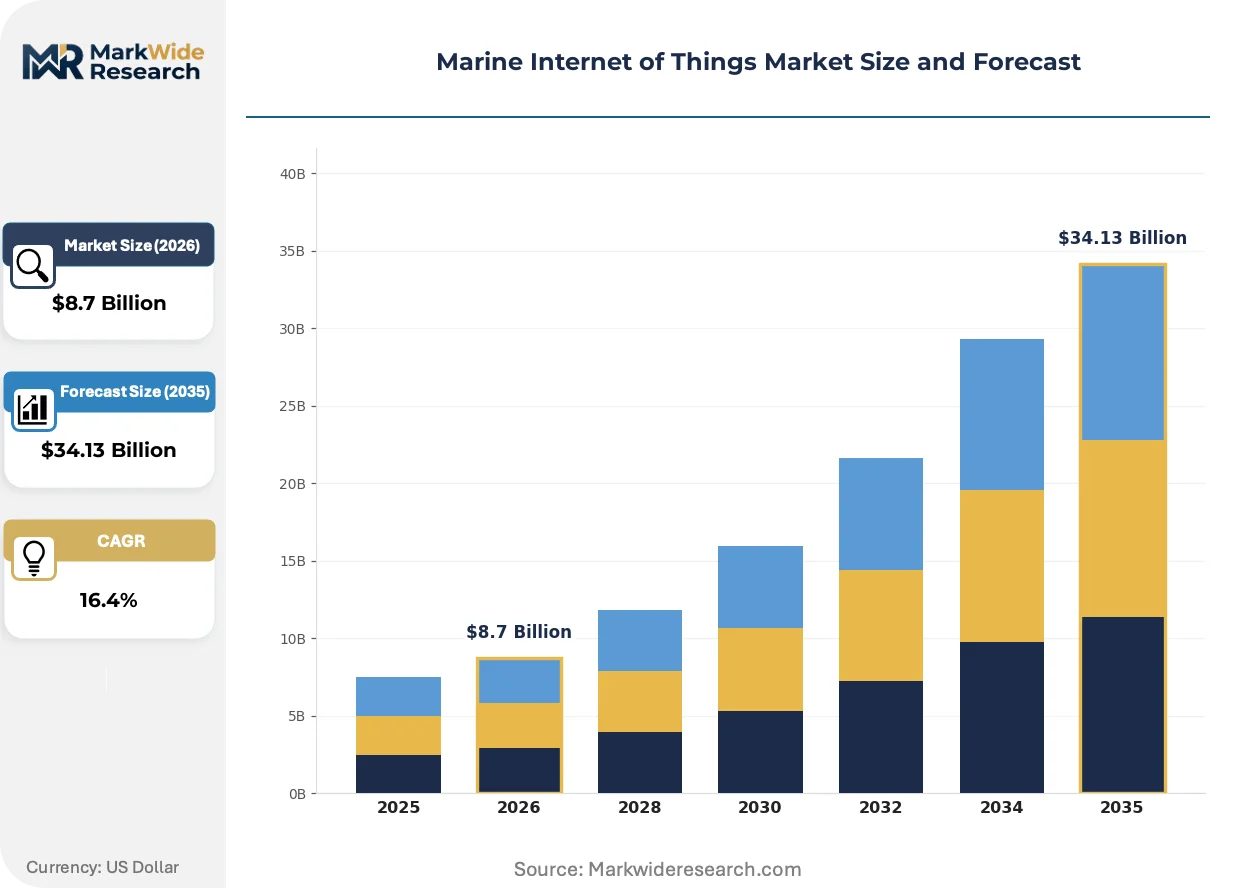
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Connectivity Devices, Monitoring Systems, IoT Platforms Application: Vessel Tracking, Predictive Maintenance, Fleet Management, Environmental Monitoring End User: Shipping Companies, Ports, Fisheries, Offshore Energy Technology: Satellite Communication, Cellular Networks, Mesh Networking, Edge Computing |
| Companies Covered | Cisco Systems, Danelec A/S, Kongsberg Maritime, Maersk, NAVTOR AS, Wärtsilä Corporation, Cobham SATCOM, Siemens AG, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Internet of Things Market Shifts & Advancements
Sensor hardware architectures are fragmenting between low-power wide-area protocols for asset tracking and high-bandwidth links for predictive maintenance video feeds. This divergence is forcing platform vendors to support heterogeneous radio stacks rather than unified connectivity layers.
Edge computing nodes with local inference capability are migrating from centralized server racks to distributed engine-room installations. Deep-sea fishing operators in the North Atlantic are piloting these architectures to reduce satellite transmission costs for acoustic monitoring arrays. The migration from cloud-dependent processing to vessel-side analytics is compressing alert response times from minutes to seconds for machinery fault detection.
The EU AI Act's risk-based classification system for autonomous systems is reshaping product development roadmaps for collision-avoidance platforms. Vendors must now document algorithmic transparency and human oversight protocols before commercial deployment. Norwegian maritime technology developers are restructuring engineering teams to embed compliance documentation into iterative software releases rather than post-hoc certification preparation.
Charterers in the dry bulk segment are mandating open API access to vessel performance data as a contract condition, displacing proprietary fleet management portals. This data portability requirement enables third-party analytics providers to aggregate cross-operator benchmarks. Greek shipping families with diversified fleet holdings are driving this standardization to compare fuel efficiency across multiple technical management providers.
Marine Internet of Things Market Segmentation
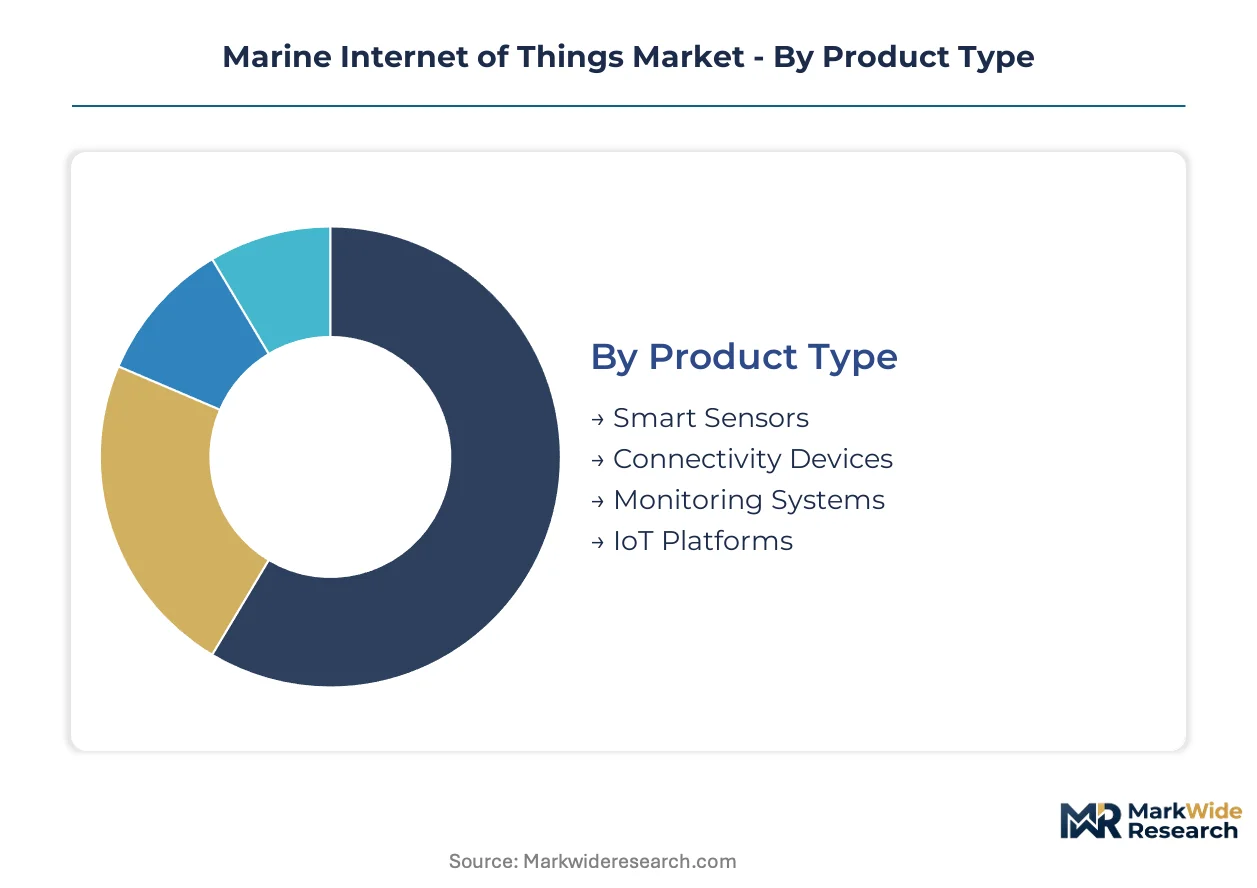
Marine Internet of Things deployments fragment across hardware layers, connectivity protocols, and operational use cases. Understanding these boundaries clarifies where capital concentrates and which technology stacks command pricing premiums.
Product Type:
Mature hardware categories dominate installed base volumes while emerging software layers capture expanding margin pools.
- Smart Sensors:Fuel-flow meters, exhaust gas analyzers, and hull stress gauges with ISO-certified calibration protocols. Norwegian-flagged fleets drive replacement demand as Kongsberg Maritime bundles these with propulsion automation retrofits.
- Connectivity Devices:Satellite terminals, cellular gateways, and mesh radio nodes bridging vessel-side networks to shore infrastructure. L-band spectrum scarcity constrains throughput for deep-ocean routes beyond terrestrial coverage.
- Monitoring Systems:Integrated hardware-software bundles generating recurring calibration revenues.
- IoT Platforms:Cloud and edge-native analytics layers processing telemetry into operational dashboards.
Smart Sensors handles the majority of throughput; IoT Platforms is the fastest mover on share.
Application:
Cost tier separation distinguishes capital-intensive predictive systems from subscription-based tracking services.
- Fleet Management:Charterer-mandated visibility portals for demurrage calculations and performance benchmarking. Greek dry bulk operators now require open API access as standard contract terms, displacing proprietary fleet portals.
- Predictive Maintenance:Machine learning models forecasting machinery failures from vibration, thermal, and oil analysis data. Edge computing migration reduces alert latency from minutes to seconds for engine-critical faults.
- Vessel Tracking:Real-time position reporting for cargo visibility and route optimization.
- Environmental Monitoring:Emissions verification systems satisfying EU MRV and IMO carbon intensity regulations.
Fleet Management commands the largest addressable spend; Predictive Maintenance shows the steepest expansion trajectory.
End User:
Customer type determines procurement complexity and integration requirements.
- Shipping Companies:Container, bulk, and tanker operators deploying fleet-wide sensor networks under dual pressure from IMO regulations and charterer data mandates.
- Ports:Singapore's smart port initiatives demonstrate berth optimization and container tracking demand in Asian transshipment hubs.
- Fisheries:North Atlantic deep-sea operators piloting edge computing for acoustic monitoring arrays to compress satellite transmission costs.
- Offshore Energy:Platform operators requiring redundant connectivity for safety-critical systems.
Shipping Companies absorb the dominant share of platform investment; Ports are gaining share fastest on infrastructure digitization budgets.
Technology:
Supply concentration shapes vendor competitive positioning across connectivity layers.
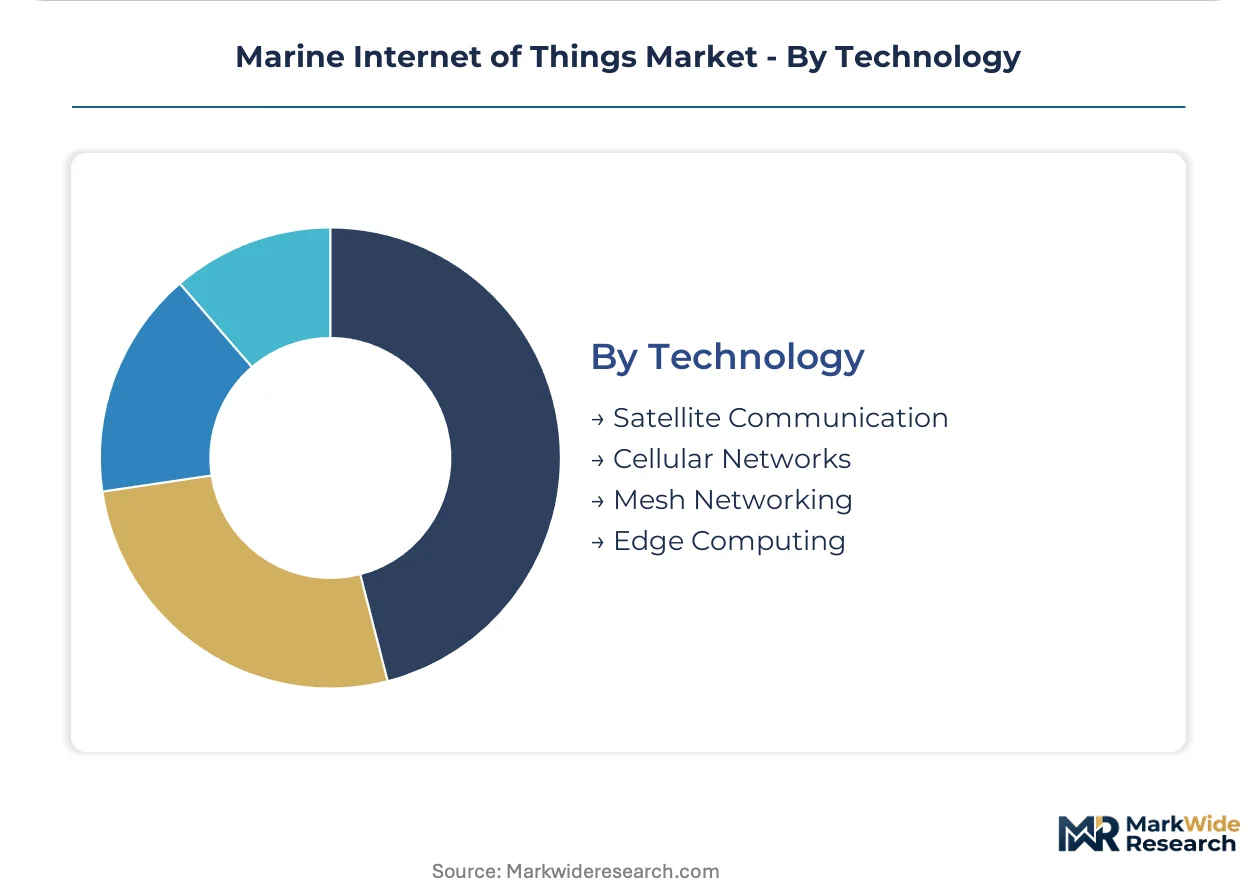
- Satellite Communication:L-band and Ku-band backhaul for oceanic routes outside terrestrial coverage. Project finance constraints narrow the competitive field to capitalized providers with orbital infrastructure.
- Edge Computing:Distributed inference nodes migrating from centralized server racks to engine-room installations. Vessel-side analytics reduce satellite bandwidth consumption for machinery fault detection.
- Cellular Networks:Coastal and port-area connectivity leveraging 4G/5G infrastructure.
- Mesh Networking:Self-healing radio arrays connecting sensors across vessel compartments with sub-100 millisecond latency thresholds.
Satellite Communication carries the heaviest infrastructure investment; Edge Computing is climbing the fastest on latency reduction requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Northern European maritime technology clusters while Asian manufacturing centers compete on hardware volume. Norway commands premium positioning through integrated vessel control systems. China and South Korea absorb sensor production scale.
Norway
Kongsberg Maritime anchors Europe's dominant maritime technology cluster with bundled propulsion automation and IoT subscriptions. The Norwegian Maritime Authority enforces stringent emissions verification protocols that accelerate certified sensor deployment. Stavanger and Oslo house concentrated engineering talent developing edge computing architectures for sub-100 millisecond engine alerts.
United States
Commercial shipping operators along the Gulf Coast face dual pressure from charterer data mandates and Coast Guard cyber risk guidelines. The US Coast Guard's cyber risk management requirements extend commissioning timelines for sensor network vulnerability assessments. Houston's offshore energy corridor drives redundant connectivity demand for platform safety systems.
Singapore
Smart port initiatives demonstrate berth optimization sensor demand across Asian transshipment hubs. The Maritime and Port Authority of Singapore accelerates infrastructure digitization through container tracking mesh network mandates. The city-state's terminal operators pilot distributed gateway installations reducing satellite bandwidth consumption.
Germany
Industrial automation specialists in Hamburg and Bremen supply engine diagnostics hardware feeding proprietary analytics platforms. The country's implementation of EU MRV regulations forces certified fuel-flow sensor replacement cycles across European-flagged fleets. Northern port cities concentrate ISO-certified calibration technician expertise.
China
Deep-sea fishing operators in the North Atlantic source edge computing nodes from Chinese manufacturers to compress satellite transmission costs. The Ministry of Industry and Information Technology shapes domestic connectivity device standards for vessel-side mesh networks. Shenzhen's electronics manufacturing base supplies lithium-dependent sensor power systems subject to cell chemistry price volatility.
Marine Internet of Things Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified hardware. The vendor base stratifies between consolidated maritime technology conglomerates and fragmented sensor calibration services. Three archetypes dominate: integrated vessel control providers bundling subscriptions, engine diagnostics specialists with captive hardware supply, and satellite infrastructure operators narrowing on capital constraints. Competitive moves concentrate on backward integration into sensor manufacturing and strategic partnerships with classification societies for certification acceleration.
Among Nordic integrated platform providers, Kongsberg Maritime and Wärtsilä Corporation exemplify the bundled-system archetype, while Cisco Systems occupies a position extending enterprise cybersecurity architectures into maritime satellite links. These three represent contrasting geographic origins and structural approaches to vessel-side data capture.
| Leading Market Players |
|---|
| Cisco Systems |
| Danelec A/S |
| Kongsberg Maritime |
| Maersk |
| NAVTOR AS |
| Wärtsilä Corporation |
| Cobham SATCOM |
| Siemens AG |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
Shenzhen's electronics manufacturing base anchors global sensor power system supply, with lithium cell chemistry volatility transmitting directly into hardware procurement costs for vessel operators. Norwegian maritime technology clusters capture premium pricing through bundled propulsion automation and IoT subscription models that lock in recurring calibration revenues.
Pricing Analysis
Industrial OEM buyers anchor a subscription-dominated pricing structure across marine IoT deployments. Three-tier pricing stratifies across ISO-certified premium sensors, standard commercial-grade hardware, and economy retrofit kits for legacy fleets. Price differentiation hinges on certification grade and after-sales calibration service bundling. Cost compression in the economy tier is intensifying because charterers now mandate open API access as standard contract terms, eroding proprietary portal premiums. Greek dry bulk operators show highest price sensitivity, while Norwegian-flagged fleets under strict emissions verification protocols absorb premium tier markups without volume pushback.
Supply Chain Analysis
Lithium carbonate feedstock draws from concentrated Chilean and Australian mining operations, with Chinese cell manufacturers controlling downstream battery pack assembly. Satellite terminal chipsets rest on Taiwanese semiconductor foundry capacity, while mesh radio components source from South Korean and Japanese electronics suppliers. Single-source vulnerability concentrates in L-band spectrum allocation controlled by a handful of orbital infrastructure operators. Distribution runs through maritime technology integrators in Norway and Germany who bundle hardware with proprietary analytics platforms, compressing direct channel access for component specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine IoT sits in early-cycle expansion as dual regulatory enforcement from IMO carbon intensity rules and charterer data mandates accelerates fleet-wide sensor deployment. Penetration remains below saturation even in Northern European flag states, leaving substantial runway for platform consolidation.
For Market Incumbents: Pre-empt platform unbundling by charterers through deeper backward integration into sensor manufacturing and captive calibration service networks. Lock in classification society partnerships for accelerated certification pathways before EU AI Act risk classifications clarify autonomous navigation compliance requirements. The open API mandate from Greek dry bulk operators threatens proprietary fleet portal revenues; counter through exclusive data analytics subscriptions that retain performance benchmarking value even when raw telemetry becomes portable.
For New Entrants and Emerging Players: Southeast Asian port infrastructure digitization offers the most penetrable expansion corridor, with Singapore's smart port initiatives demonstrating berth optimization sensor demand that neighboring transshipment hubs have yet to match. Target fisheries and offshore energy segments where edge computing migration for acoustic monitoring and safety-critical redundancy creates greenfield deployment opportunities outside established shipping company procurement relationships. Lead with cybersecurity-certified gateway hardware to exploit US Coast Guard commissioning timeline extensions that disadvantage unvetted vendors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized sensor calibration services with ISO-certified technician networks, as hardware commoditization concentrates margin capture in recurring certification revenues. Long-term viability rests on regulatory enforcement durability rather than technology differentiation, given IMO emissions verification protocols are structurally embedded in international maritime law. Watch for EU AI Act implementing guidance on autonomous collision-avoidance algorithms as the inflection signal that will clarify which platform vendors can deploy AI-enabled navigation without protracted compliance delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Kongsberg Maritime bundles proprietary fuel-flow meters with propulsion automation to lock charterer subscription revenues. |
| Classification Society Partnership | Wärtsilä Corporation accelerates engine diagnostics hardware certification through DNV and Lloyd's Register co-development programs. |
| Cybersecurity Architecture Extension | Cisco Systems captures vessel commissioning timelines extended by US Coast Guard vulnerability assessment requirements. |
| Edge Computing Node Distribution | North Atlantic fishing operators reduce satellite bandwidth costs through vessel-side acoustic monitoring inference. |
| Open API Platform Development | Third-party analytics providers aggregate cross-operator benchmarks as Greek shipping families mandate data portability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vessel fleet managers, maritime technology procurement leads, sensor calibration technicians, port authority digitization officers, and satellite infrastructure planners. Secondary validation drew from IMO regulatory filings, EU MRV compliance databases, US Coast Guard cyber risk management guidelines, Norwegian Maritime Authority emissions protocols, and customs records for connectivity device trade flows. Bottom-up vessel fleet deployment estimates triangulated against top-down maritime technology market sizing from shipping company capex disclosures.
Calibration against historical sensor replacement cycles and regulatory compliance deadlines shaped volume projections across the analysis window. Segmentation modeling captured product type tiers, application use cases, end-user procurement complexity, and technology stack heterogeneity. CAGRs derived from weighted average of adoption curve penetration rates and hardware replacement cycle frequencies. Forecast inputs incorporated L-band spectrum allocation constraints, lithium battery chemistry price indices, and charterer contract term standardization trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese electronics manufacturers into sensor calibration services or satellite operators into direct platform competition would shift outcomes substantially. Cross-checking against Lloyd's List vessel equipment installation databases and DNV maritime technology certification records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Narrowband IoT Enterprise Application Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
IoT Data Governance Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Massive IoT Market