
 Global Smart City Market | 2026-2036
Global Smart City Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart City Market Outlook
Advanced interoperability specifications is rotating from legacy municipal IT toward open-architecture platforms that integrate real-time sensor networks. Cisco Systems leverages its networking infrastructure dominance to anchor large-scale urban deployments across multiple continents. Siemens competes through deep vertical specialization in energy and building automation systems. Huawei Technologies controls significant manufacturing scale in 5G-enabled street infrastructure, though its geographic reach faces regulatory constraints in select Western markets.
Smart city solutions constitute integrated urban technology ecosystems combining IoT sensor arrays, edge computing nodes, and centralized data analytics platforms to optimize municipal service delivery, resource allocation, and citizen safety outcomes. These systems typically process telemetry from thousands of distributed endpoints with sub-second latency requirements for critical applications such as emergency response and traffic signal optimization. The technology segment shows AI and IoT combinations capturing the dominant share of new municipal procurement budgets, while the application dimension reveals energy management platforms outpacing legacy smart lighting installations in margin contribution. Service type dynamics favor managed services over professional consulting as cities seek outcome-based operational partnerships rather than one-time system integration contracts.
The EU AI Act and GDPR frameworks impose algorithmic transparency mandates on automated urban decision systems, while the US FCC governs spectrum allocation for municipal IoT networks and the EPA sets emissions benchmarks that smart grid deployments must demonstrate. India's BIS certification requirements and PLI scheme incentives are shaping vendor eligibility for national smart city tenders. Stakeholders must monitor divergence between EU algorithmic accountability standards and US sector-specific approaches as this regulatory fragmentation threatens to fragment platform interoperability and increase compliance costs for multi-jurisdiction deployments.
Market Dynamics
Municipal procurement patterns are pivoting toward integrated platform contracts that bundle hardware, software, and long-term operations, compressing vendor margins while locking in decade-long revenue streams for winning bidders.
Growth Catalysts
- India's PLI scheme incentives:Domestic manufacturing subsidies for IoT hardware and edge computing equipment are accelerating local production capacity for smart street infrastructure deployments.
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated urban decision systems are forcing municipal procurement toward certified vendors with documented model governance.
- 5G-enabled sensor networks:Ultra-low latency connectivity is unlocking real-time traffic signal optimization and emergency response coordination previously impossible with legacy cellular.
Market Restraints
- Semiconductor supply concentration:Dependence on East Asian foundries for specialized IoT chipsets creates vulnerability to export control disruptions and capacity constraints.
- Legacy system integration costs:Proprietary protocols in existing municipal IT infrastructure require expensive middleware development before new platforms can interoperate.
- Cybersecurity certification timelines:Extended evaluation periods under national critical infrastructure frameworks delay deployment schedules by 12-18 months.
Strategic Opportunities
- Sub-Saharan African urban corridors:Rapidly expanding secondary cities lack legacy infrastructure, enabling greenfield deployment of integrated smart city platforms without retrofit constraints.
- Digital twin convergence:Integration of Building Information Modeling with real-time sensor feeds is creating new service categories around predictive maintenance and scenario simulation.
- Outcome-based municipal partnerships:Performance-guaranteed contracts tying vendor payments to measurable reductions in energy consumption or traffic congestion are displacing capital expenditure procurement models.
Industry Challenges
- Interoperability standard fragmentation:Competing industry consortia are promoting incompatible data exchange protocols, forcing vendors to support multiple specifications simultaneously.
- Edge AI talent scarcity:Shortage of engineers capable of optimizing machine learning models for resource-constrained municipal hardware limits deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart City Market |
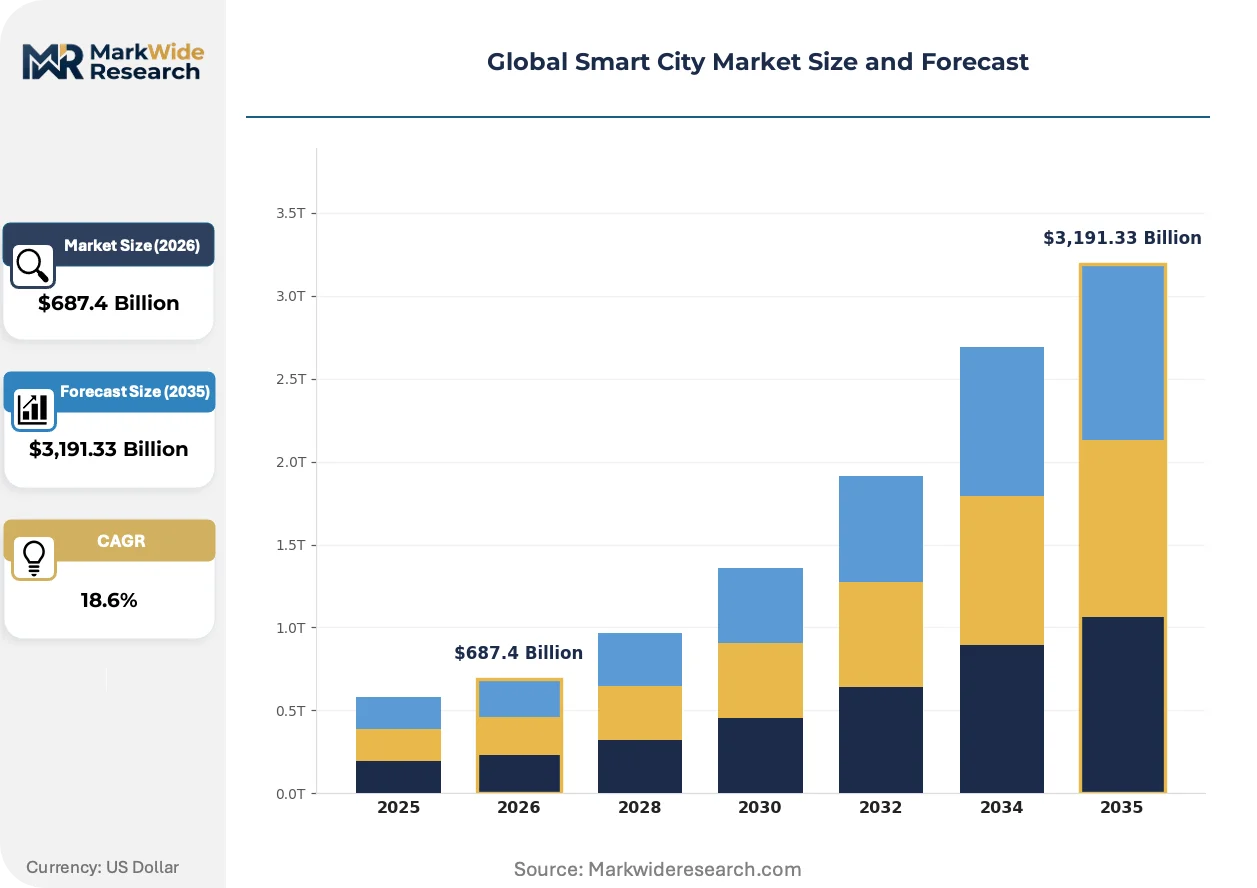
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $3,191.33 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Big Data Analytics, Cloud Computing Application: Traffic Management, Waste Management, Energy Management, Smart Lighting End User: Government, Transportation Agencies, Utility Providers, Real Estate Developers Service Type: Managed Services, Professional Services, Consulting, Integration Services |
| Companies Covered | Cisco Systems, IBM, Siemens, Microsoft, Schneider Electric, Huawei Technologies, Hitachi, Honeywell International, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart City Market Strategic Shifts
Urban technology stacks are converging around open-architecture platforms that aggregate previously siloed municipal functions, creating new competitive battlegrounds around data sovereignty and cross-domain analytics capabilities.
Edge-native AI inference engines are displacing cloud-dependent processing for latency-critical applications like pedestrian detection and traffic flow optimization. European transit authorities are mandating sub-100 millisecond response times for safety-critical systems, forcing vendors to deploy localized compute rather than centralized data center architectures. This shift is compressing margins for pure-play cloud providers while favoring hardware-integrated platform vendors.
The EU AI Act's risk classification framework for automated urban systems is restructuring vendor qualification requirements across European procurement. High-risk applications including biometric surveillance and predictive policing now require conformity assessments by notified bodies before deployment. German and French municipal authorities are consolidating supplier lists to pre-certified vendors, raising barriers for new market entrants.
Municipal buyers are consolidating vendor relationships around multi-decade service agreements that transfer operational risk to technology providers. Singapore and Dubai authorities pioneered availability-based contracts for smart lighting and waste management, with payment tied to uptime and service level achievement. This model is displacing traditional equipment purchase plus maintenance arrangements across Middle Eastern and Southeast Asian urban developments.
Global Smart City Market Segmentation
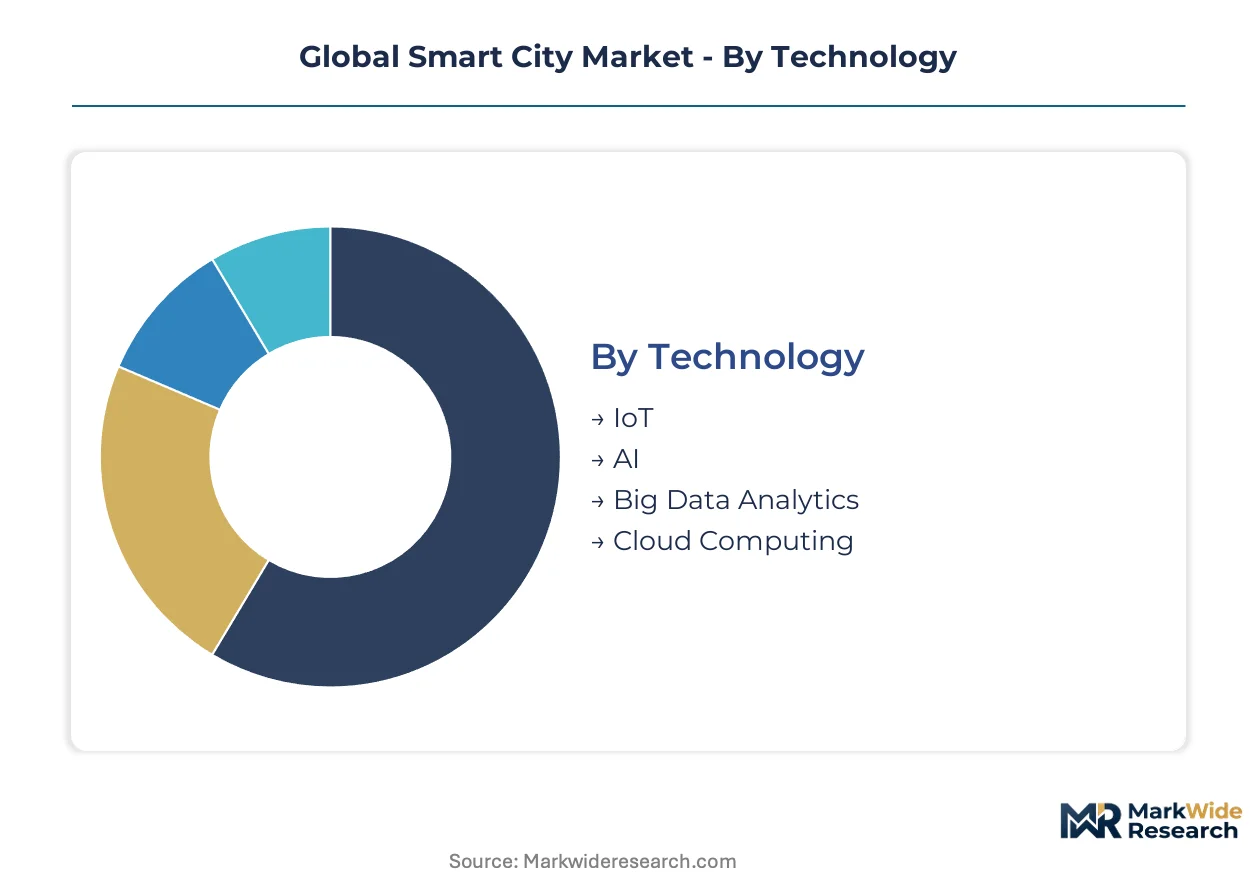
Smart city procurement demands granular segmentation to align vendor capabilities with municipal procurement frameworks and regulatory compliance tiers. Technology stacks, application domains, and service delivery models each carry distinct certification requirements and margin profiles that shape competitive positioning.
Technology:
EU AI Act risk classifications and India's BIS certification standards are bifurcating procurement eligibility across technology categories, with high-risk automated systems facing mandatory conformity assessments.
- IoT:Distributed sensor networks and edge devices form the telemetry backbone for traffic, energy, and environmental monitoring systems. Demand concentrates in Indian smart city tenders where PLI scheme subsidies favor domestic IoT hardware manufacturing for street infrastructure deployments.
- AI:Machine learning models power predictive analytics for congestion forecasting, energy load balancing, and emergency response optimization. German and French municipal authorities are consolidating supplier lists to pre-certified vendors under EU AI Act high-risk system requirements, accelerating share concentration among compliant providers.
- Big Data Analytics:Centralized platforms aggregate multi-source urban telemetry for pattern recognition and resource optimization.
- Cloud Computing:Scalable infrastructure services host municipal data lakes and cross-departmental analytics workloads.
IoT handles the majority of throughput; AI is the fastest mover on share.
Application:
Municipal budget allocation patterns reveal energy management platforms commanding premium margins while traffic systems drive the largest absolute contract values.
- Energy Management:Integrated grid optimization, distributed generation coordination, and demand-response systems reduce municipal consumption and emissions. Singapore and Dubai authorities have pioneered availability-based contracts tying vendor payments to measurable reductions in energy consumption, displacing traditional capital expenditure procurement models.
- Traffic Management:Real-time signal optimization, incident detection, and multimodal transit coordination require sub-100 millisecond response times. European transit authorities mandate these latency thresholds for safety-critical systems, forcing localized edge compute deployment rather than centralized architectures.
- Waste Management:Sensor-enabled collection routing and fill-level monitoring optimize fleet utilization and service frequency.
- Smart Lighting:LED retrofit programs with networked controls deliver energy savings but face margin compression as legacy installations saturate mature markets.
Traffic management commands the largest contract values; energy management delivers the steepest margin expansion.
End User:
Procurement authority fragmentation across government tiers and agency types creates divergent vendor engagement models and contract structures.
- Government:Municipal and regional authorities hold primary procurement authority for integrated platform deployments. India's national smart cities mission continues to drive large-scale infrastructure digitization through centralized tendering mechanisms that bundle hardware, software, and long-term operations.
- Transportation Agencies:Transit authorities and traffic departments specify latency-critical systems with stringent uptime requirements. These entities are consolidating vendor relationships around multi-decade service agreements that transfer operational risk to technology providers.
- Utility Providers:Electricity, water, and gas distributors procure smart grid and metering infrastructure under regulated rate-base frameworks.
- Real Estate Developers:Private sector actors deploy building-level and district-scale systems within greenfield urban developments.
Government entities originate the majority of procurement volume; transportation agencies are expanding most quickly as 5G-enabled networks unlock new service categories.
Service Type:
Outcome-based commercial models are restructuring revenue recognition from upfront system integration toward recurring operational partnerships.
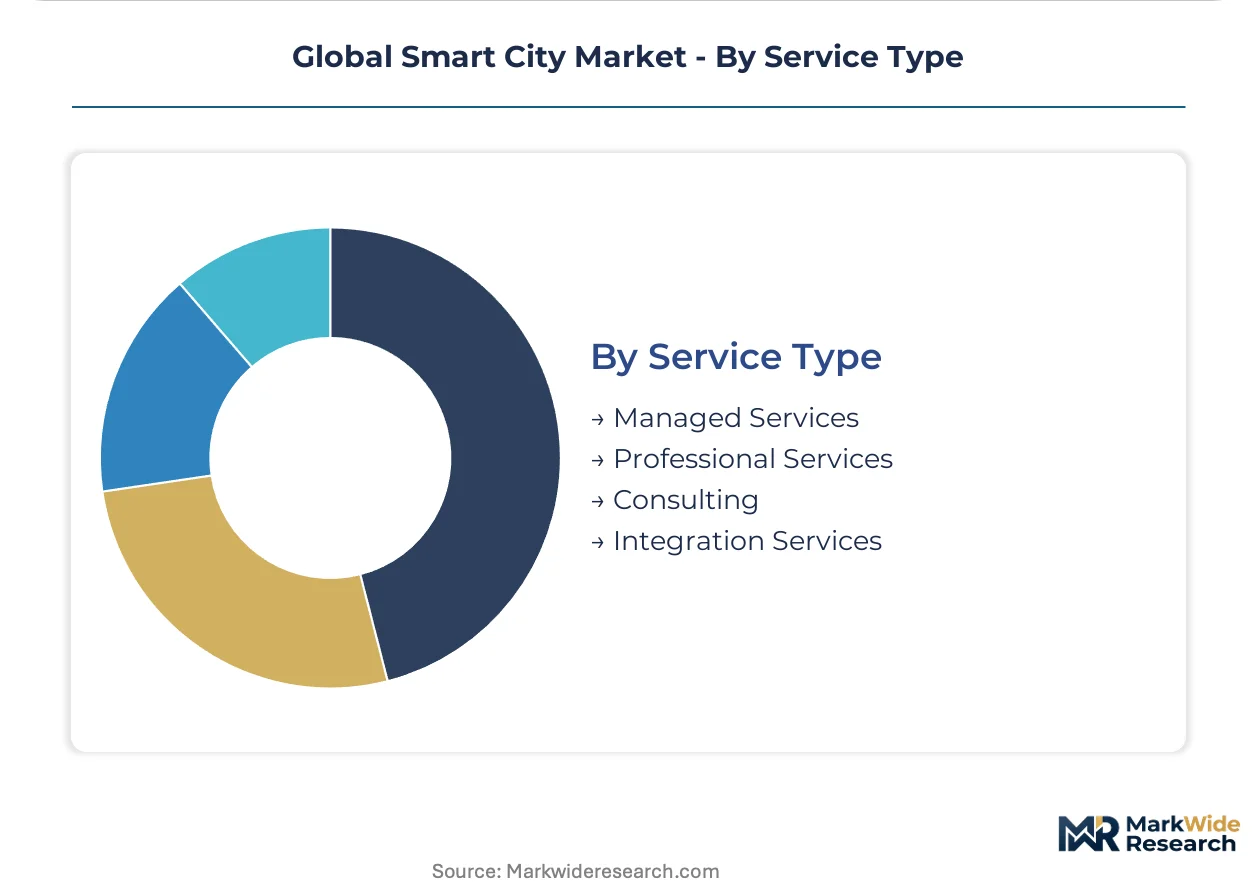
- Managed Services:Long-term operational contracts bundle monitoring, maintenance, and performance optimization with availability guarantees. Singapore and Dubai pioneered this model for smart lighting and waste management, with payment tied to uptime and service level achievement, now displacing traditional arrangements across Middle Eastern and Southeast Asian markets.
- Professional Services:System design, implementation, and integration project work faces margin compression as cities shift toward operational partnerships.
- Consulting:Strategic advisory and digital transformation planning engagements support municipal technology roadmapping.
- Integration Services:Middleware development and legacy system interoperability work addresses proprietary protocol constraints in existing municipal IT infrastructure.
Managed services capture the expanding share of municipal technology budgets; professional services face compression as procurement pivots toward outcome-based structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the lowest price elasticity as centralized procurement under the national smart cities mission bundles long-term operations contracts, while European municipalities face compressed budgets that heighten vendor sensitivity to unit economics.
United States
Municipal procurement concentrates in Sun Belt metropolitan areas where population growth strains legacy infrastructure. The FCC governs spectrum allocation for municipal IoT networks, creating compliance thresholds for 5G-enabled deployments. Dallas and Phoenix anchor large-scale integrated platform rollouts combining traffic management with grid optimization.
Germany
Industrial automation heritage drives demand for predictive maintenance systems in municipal asset portfolios. The EU AI Act imposes conformity assessments on high-risk automated urban decision systems, consolidating supplier lists toward pre-certified vendors. The Rhine-Ruhr corridor hosts concentrated pilot programs for digital twin integration in district heating networks.
India
Secondary cities under the national smart cities mission drive volume procurement of integrated traffic and energy platforms. BIS certification requirements and PLI scheme incentives shape vendor eligibility for centralized tenders. Pune and Surat lead deployment velocity for sensor-enabled waste management and street lighting retrofits.
Singapore
Availability-based contracting models pioneered here now diffuse across Southeast Asian procurement frameworks. The city-state's Smart Nation initiative mandates interoperability standards that vendors must satisfy for platform certification. Marina Bay and Jurong Lake District serve as testbeds for outcome-guaranteed service agreements tying payments to uptime metrics.
United Arab Emirates
Greenfield urban developments enable integrated platform deployment without legacy system retrofit constraints. MOHAP and local regulators coordinate data governance frameworks for biometric surveillance and predictive systems. Dubai's EXPO 2020 legacy district and Abu Dhabi's Masdar City anchor concentrated demand for managed services contracts.
Global Smart City Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with networking infrastructure specialists commanding premium positioning while hardware-integrated platform vendors compete on deployment scale. The vendor base spans three tiers: diversified technology conglomerates with cross-domain portfolios, specialized industrial automation houses with deep vertical expertise, and telecommunications equipment manufacturers with captive 5G infrastructure. Consolidation pressure intensifies as municipal buyers favor decade-long operational partnerships over discrete system sales. Strategic moves center on backward integration into edge computing hardware and geographic expansion through local manufacturing incentives.
Within the diversified technology tier, Cisco Systems and IBM occupy positions anchored by enterprise networking and cloud infrastructure heritage respectively. Siemens exemplifies the industrial automation archetype through its energy and building systems specialization. Huawei Technologies sits within the telecommunications-integrated segment, though regulatory constraints in select Western markets limit its addressable geography. These three anchors illustrate how vendor qualification increasingly depends on certification status under the EU AI Act and India's BIS frameworks rather than pure technical capability.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM |
| Siemens |
| Microsoft |
| Schneider Electric |
| Huawei Technologies |
| Hitachi |
| Honeywell International |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
Edge-native AI inference engines replacing cloud-dependent processing simultaneously redistribute supply geography toward localized compute hardware manufacturing and compress pricing power for pure-play cloud providers. This substitution dynamic concentrates value capture among hardware-integrated platform vendors while fragmenting procurement across municipal buyers seeking sub-100 millisecond latency guarantees.
Pricing Analysis
Managed services contracts spanning decade-long operational terms drive lifetime value capture as cities abandon capital expenditure procurement models. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU AI Act certification status and edge compute performance tiers. Cost compression in professional services integration work intensifies because municipal buyers bundle hardware, software, and operations into single-vendor contracts. Transportation agencies exhibit lowest price sensitivity due to safety-critical latency mandates, while secondary cities in India demonstrate highest elasticity under PLI scheme domestic manufacturing incentives.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites semiconductor supply risk for specialized IoT chipsets powering municipal sensor networks. Manufacturing concentrates in Taiwan, South Korea, and mainland China for edge computing processors, 5G baseband modules, and AI accelerators. Component dependencies draw from gallium nitride substrates, high-precision MEMS sensors, and automotive-grade lithium cells. Single-source vulnerability intensifies as export control restrictions fragment foundry access. Distribution runs through systems integrators holding municipal procurement certifications rather than direct vendor-to-city relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services revenue layers expand faster than hardware sales as availability-based contracts displace equipment purchase arrangements across Middle Eastern and Southeast Asian markets. This service-attach opportunity rewards vendors capable of operational risk transfer and performance-guaranteed uptime delivery.
For Market Incumbents: Secure pre-certification status under EU AI Act high-risk system requirements before German and French municipal authorities finalize consolidated supplier lists. Anchor backward integration into edge computing hardware manufacturing through India's PLI scheme incentives to defend against emerging telecommunications-integrated challengers. Control channel access by embedding operations teams within transportation agencies seeking multi-decade service agreements.
For New Entrants and Emerging Players: Lead with digital twin convergence offerings targeting Sub-Saharan African urban corridors lacking legacy infrastructure retrofit constraints. Penetrate greenfield secondary cities in Nigeria and Kenya where integrated platform deployment faces no proprietary protocol middleware development costs. Position through outcome-based municipal partnerships tying payments to measurable energy consumption reductions rather than capital equipment sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed industrial automation specialists holding deep vertical expertise in energy and building systems. Long-term viability over the extended municipal procurement horizon depends on certification moats under tightening algorithmic transparency mandates. Monitor divergence between EU AI Act conformity assessment timelines and US FCC spectrum allocation frameworks as the inflection signal for multi-jurisdiction platform interoperability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges siloed traffic, energy, and waste systems under unified data sovereignty architectures. |
| EU AI Act Certification Investment | Unlocks high-risk automated system procurement in German and French municipal tenders. |
| Geographic Expansion via PLI Scheme | Establishes domestic manufacturing eligibility for India's national smart cities mission tenders. |
| Strategic Partnership with Telecom Operators | Captures 5G-enabled sensor network deployment through captive infrastructure access. |
| Acquisition of Edge AI Specialist | Addresses talent scarcity limiting machine learning optimization for resource-constrained municipal hardware. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of municipal procurement databases, EU regulatory filings, and hyperscaler capex disclosures. Interviews with smart city program directors, transportation agency technology officers, and edge computing hardware procurement leads inform demand-side validation. Secondary sources include BIS certification records, SEC 10-K infrastructure segment disclosures, and smart city tender documentation from Pune, Surat, and Singapore authorities. Bottom-up project pipeline analysis triangulates against top-down national budget allocation frameworks.
Segmentation dimensions modeled span technology category, application domain, end-user authority type, and service delivery structure across the projection horizon. CAGRs derive from weighted municipal procurement velocity indicators and regulatory compliance timeline assumptions. Forecast inputs incorporate PLI scheme subsidy disbursement patterns and EU AI Act conformity assessment capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained municipal budget commitment levels or accelerated semiconductor export control expansion would require recalibration. Practitioners should keep alternative scenarios live as EU-US regulatory divergence and India domestic manufacturing incentive evolution reshape vendor qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Smart City Framework Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
E-Governance Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart Ticketing Solutions Market