
 Aviation IoT Solutions Market | 2026-2036
Aviation IoT Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation IoT Solutions Market Outlook
The aftermarket service channel is rewriting how aviation IoT platforms reach end users, with OEMs and independent MRO networks competing for data access contracts. Honeywell International leverages its installed base of auxiliary power units and environmental control systems to bundle predictive maintenance subscriptions. Cisco Systems anchors enterprise networking relationships that extend into airport operations centers and airline IT backbones. Thales Group competes through avionics integration, embedding IoT gateways directly into flight management hardware.
Aviation IoT Solutions encompass networked sensor arrays, edge computing nodes, and cloud analytics platforms that collect, transmit, and process operational data from aircraft, ground support equipment, and airport infrastructure. These systems typically operate across 1090 MHz ADS-B, satellite communications links, and proprietary 802.11 protocols to deliver real-time telemetry for asset tracking, engine health monitoring, and baggage flow optimization. Fleet Management applications dominate current deployment value as carriers prioritize fuel burn reduction and route optimization through connected flight operations. Predictive Maintenance represents the fastest-expanding application segment, where machine learning models applied to vibration and thermal sensor data are displacing scheduled overhaul intervals with condition-based interventions. Ground Handlers occupy a narrower but strategically important end-user position, since tarmac equipment connectivity directly influences turnaround time metrics that airlines track for operational performance.
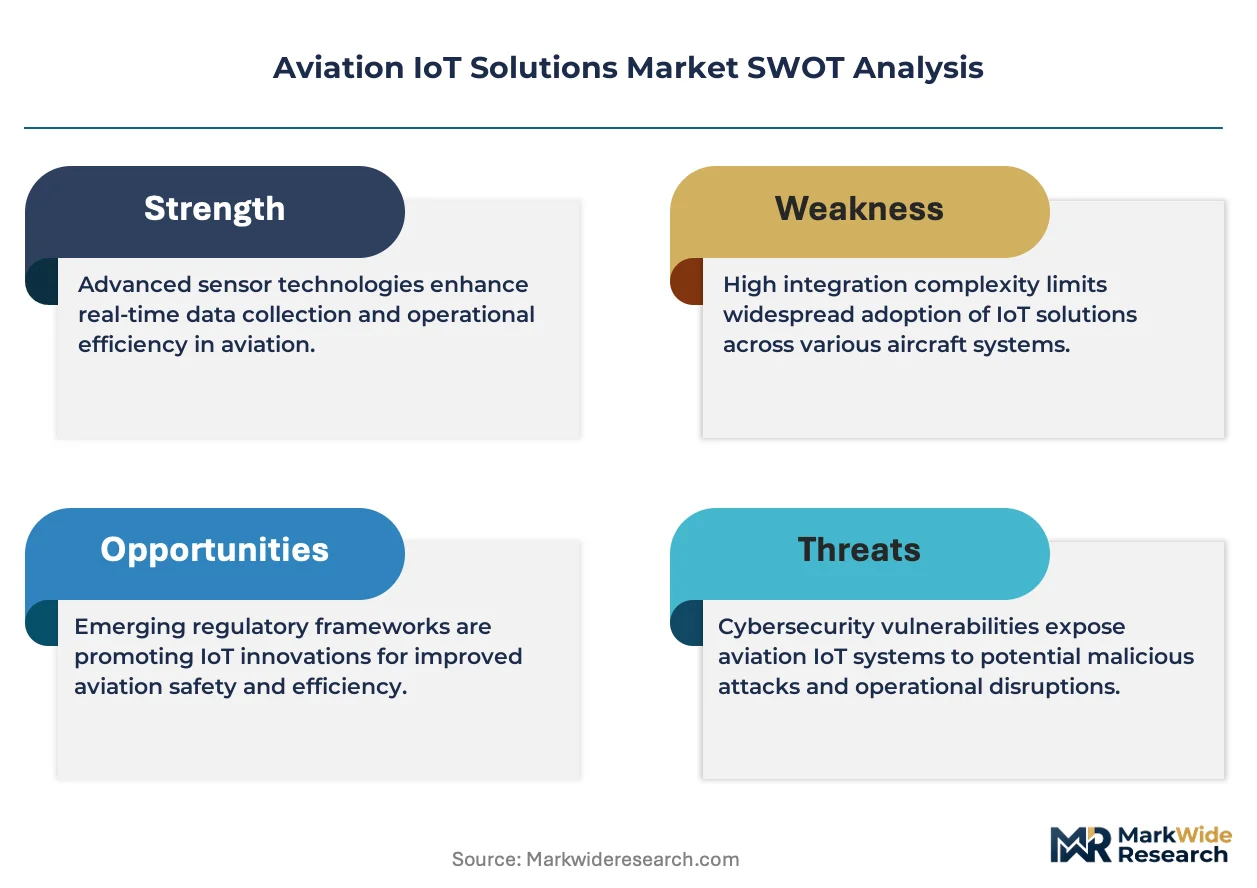
The FAA mandates DO-178C software assurance and DO-254 hardware verification for connected systems installed on certified aircraft, creating compliance barriers that filter out non-aerospace technology suppliers. EASA's continuing airworthiness regulations and the EU AI Act's risk classification framework for automated decision systems will reshape how European operators deploy predictive algorithms for maintenance scheduling. Stakeholders must monitor divergence between FAA and EASA cybersecurity certification pathways, as incompatible standards would fragment platform development roadmaps and raise compliance costs for suppliers serving both regulatory domains.
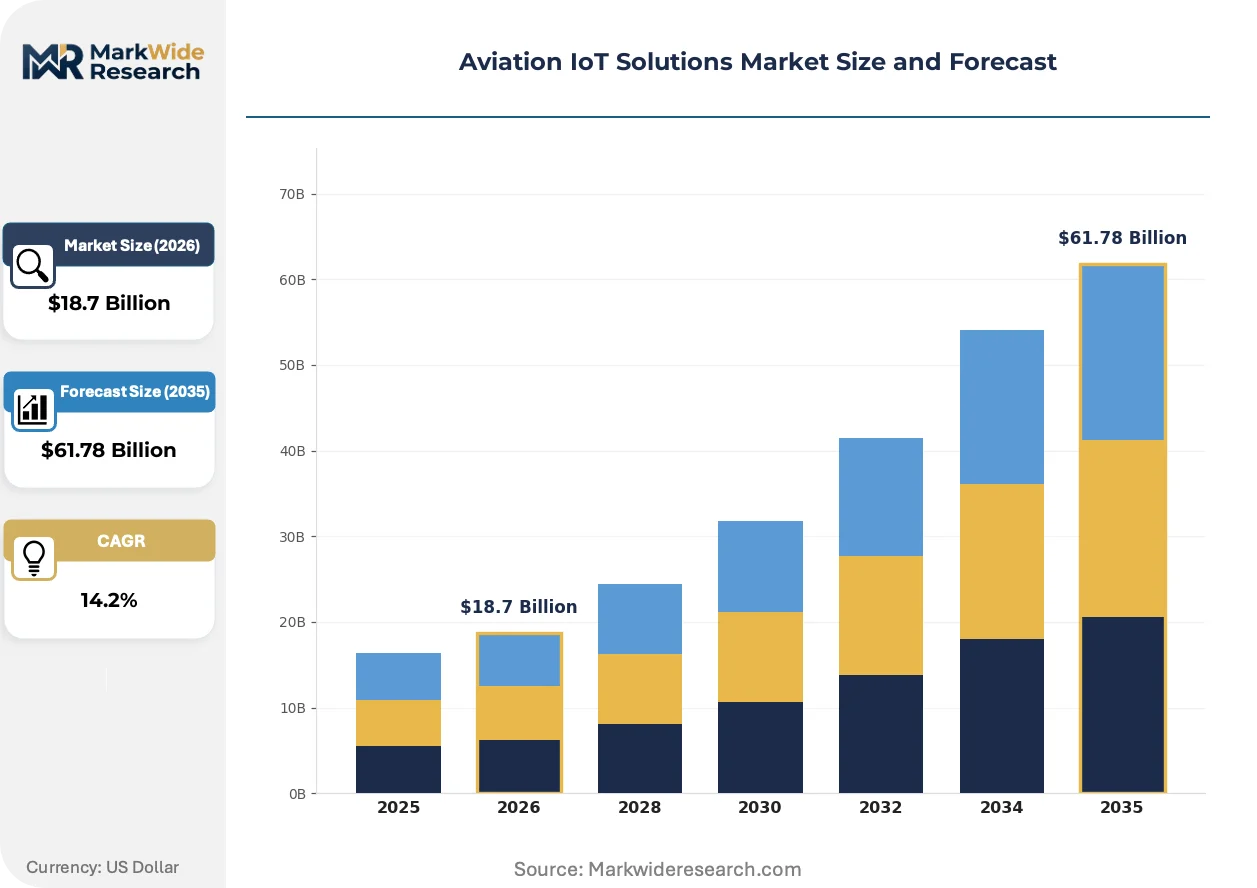
Market Dynamics
Airlines are consolidating flight data streams from auxiliary power units, environmental control systems, and flight management hardware into unified edge-computing architectures, compressing the traditional separation between airframe OEMs and independent MRO networks.
Growth Catalysts
- FAA Airworthiness Directives:Tightening certification requirements for connected aircraft systems are forcing hardware and software upgrades across installed fleets, creating replacement demand for compliant sensor arrays and gateways.
- Predictive Maintenance Algorithms:Machine learning models applied to vibration and thermal sensor data are displacing scheduled overhaul intervals with condition-based interventions, reducing unplanned downtime for major carriers.
- United States Hub Deployment:Edge-computing infrastructure concentration at Atlanta, Dallas-Fort Worth, and Chicago O'Hare is accelerating real-time telemetry processing for fuel burn optimization and route planning.
Market Restraints
- DO-178C Compliance Costs:Software assurance verification for safety-critical connected systems imposes documentation and testing burdens that filter out non-aerospace technology suppliers.
- Semiconductor Supply Concentration:Specialized avionics-grade processors face allocation constraints from limited foundry capacity serving defense-aerospace dual-use demand.
- Satellite Bandwidth Pricing:In-flight connectivity dependencies on Ku-band and Ka-band leases expose operators to volatile recurring costs that compress IoT platform margins.
Strategic Opportunities
- Ground Handler Connectivity:Tarmac equipment telematics for baggage flow optimization and turnaround time metrics remain underpenetrated compared to airborne fleet management.
- EASA-EU AI Act Convergence:Risk classification frameworks for automated maintenance scheduling decisions create first-mover advantage for suppliers certifying predictive algorithms under European automated system governance.
- 5G Private Networks:Airport-specific 802.11 and cellular convergence enables ultra-low latency for engine health monitoring during pushback and taxi operations.
Industry Challenges
- DO-254 Hardware Verification Timelines:Complex programmable logic device certification for IoT gateways extends development cycles and delays platform deployment.
- Cybersecurity Standard Divergence:Incompatible FAA and EASA certification pathways for connected system security architectures fragment supplier development roadmaps and raise compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation IoT Solutions Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS, Sensors, Telematics Application: Fleet Management, Predictive Maintenance, Cargo Tracking, Passenger Experience End User: Aerospace Manufacturers, Airlines, Ground Handlers, Maintenance Providers Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Honeywell International, Cisco Systems, IBM Corporation, Collins Aerospace, Huawei Technologies, GE Aviation, Thales Group, Microsoft Corporation, Amadeus IT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation IoT Solutions Market Strategic Shifts
Aviation IoT architectures are converging airborne, ground, and airport infrastructure data into unified analytics platforms, dissolving historical silos between flight operations, maintenance control, and ground handling.
Edge computing is hybridizing with traditional cloud-based fleet analytics, enabling real-time inference for engine health monitoring during flight rather than post-landing batch processing. Low Earth orbit satellite constellations are accelerating adoption among long-haul carriers operating beyond terrestrial coverage zones. This compression of decision latency is enabling dynamic rerouting based on live mechanical telemetry rather than pre-flight static plans.
EASA's continuing airworthiness regulations are tightening software lifecycle documentation requirements for predictive maintenance algorithms deployed on European-registered aircraft. Operators must demonstrate traceability from sensor input to maintenance action recommendation under emerging automated decision system governance. Narrow-body fleets serving high-frequency short-haul routes face the steepest compliance adaptation curves due to compressed turnaround windows.
Carrier procurement patterns are consolidating vendor relationships around platforms offering bundled hardware, connectivity, and analytics subscriptions. Discrete component sourcing for sensors, gateways, and software is yielding to integrated fleet management contracts with performance guarantees. This bundling is most advanced among United States network carriers with centralized technical operations centers.
Aviation IoT Solutions Market Segmentation
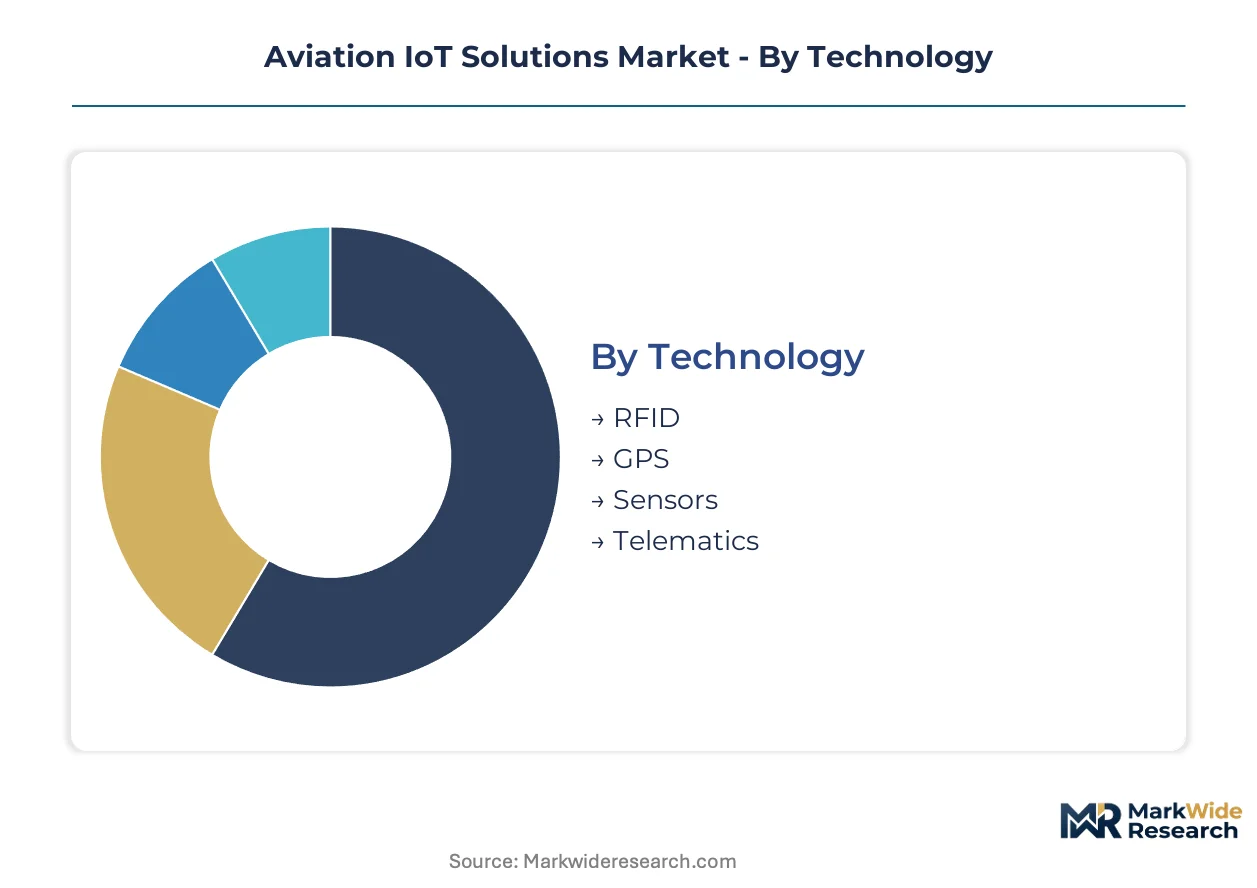
Technology and application boundaries in aviation IoT are dissolving as unified platforms absorb discrete point solutions. Procurement patterns increasingly favor integrated deployments over standalone sensor or software purchases, reshaping how vendors position across traditional segment divides.
Technology:
RFID tags and GPS modules turn over fastest due to consumable wear and battery degradation cycles, while telematics platforms and sensor networks embed for decade-long airframe lifespans.
- Sensors:Vibration, thermal, and pressure transducers form the data foundation for engine health monitoring and environmental control system diagnostics. Airlines operating Boeing 737 and Airbus A320 narrow-body fleets in the United States drive replacement demand as FAA airworthiness directives mandate upgraded fire detection and bleed air monitoring capabilities.
- Telematics:Integrated communication hubs aggregate multiple data streams through 1090 MHz ADS-B, satellite links, and proprietary 802.11 protocols. Major carriers at Atlanta and Dallas-Fort Worth hubs prioritize telematics refreshes to enable real-time fuel burn optimization during pushback and taxi operations.
- RFID:Passive and active tags track high-value components through maintenance cycles and supply chains.
- GPS:Multi-constellation receivers provide redundant positioning for ground support equipment fleet management.
Sensors anchor the volume base while telematics gains share at the steepest rate.
Application:
Commercial significance clusters around operational cost reduction, with fleet management and predictive maintenance commanding premium pricing against narrower cargo and passenger solutions.
- Fleet Management:Unified platforms consolidate flight data from auxiliary power units, environmental control systems, and flight management hardware for route optimization and fuel efficiency analytics. United States network carriers with centralized technical operations centers dominate procurement, seeking performance-guaranteed subscriptions that bundle hardware, connectivity, and cloud analytics.
- Predictive Maintenance:Machine learning models applied to sensor telemetry displace scheduled overhaul intervals with condition-based interventions. EASA's continuing airworthiness regulations and the EU AI Act's risk classification framework for automated decision systems are reshaping how European operators deploy these algorithms for maintenance scheduling.
- Cargo Tracking:Temperature and location monitoring for pharmaceutical and perishable shipments through cold chain logistics.
- Passenger Experience:In-flight connectivity provisioning and cabin environment personalization through connected seat-back and overhead systems.
Fleet management generates the largest revenue pool while predictive maintenance climbs the fastest.
End User:
Procurement authority and technical sophistication vary sharply, with airlines and aerospace manufacturers driving specification standards that ground handlers and independent maintenance providers must follow.
- Airlines:Network carriers with hub-and-spoke operations in the United States consolidate vendor relationships around integrated fleet management contracts. These operators demand edge-computing infrastructure at Atlanta, Dallas-Fort Worth, and Chicago O'Hare to compress decision latency for dynamic rerouting based on live mechanical telemetry.
- Aerospace Manufacturers:Airframe and engine OEMs embed IoT gateways directly into certified hardware, controlling data architecture from initial design. DO-178C software assurance and DO-254 hardware verification requirements filter out non-aerospace technology suppliers from their approved vendor lists.
- Ground Handlers:Tarmac equipment telematics for baggage flow optimization and turnaround time metrics remain underpenetrated compared to airborne fleet management.
- Maintenance Providers:Independent MRO networks compete with OEM-affiliated service operations for access to flight data streams and predictive algorithm deployment rights.
Airlines dominate current procurement volume while ground handlers present the steepest expansion trajectory.
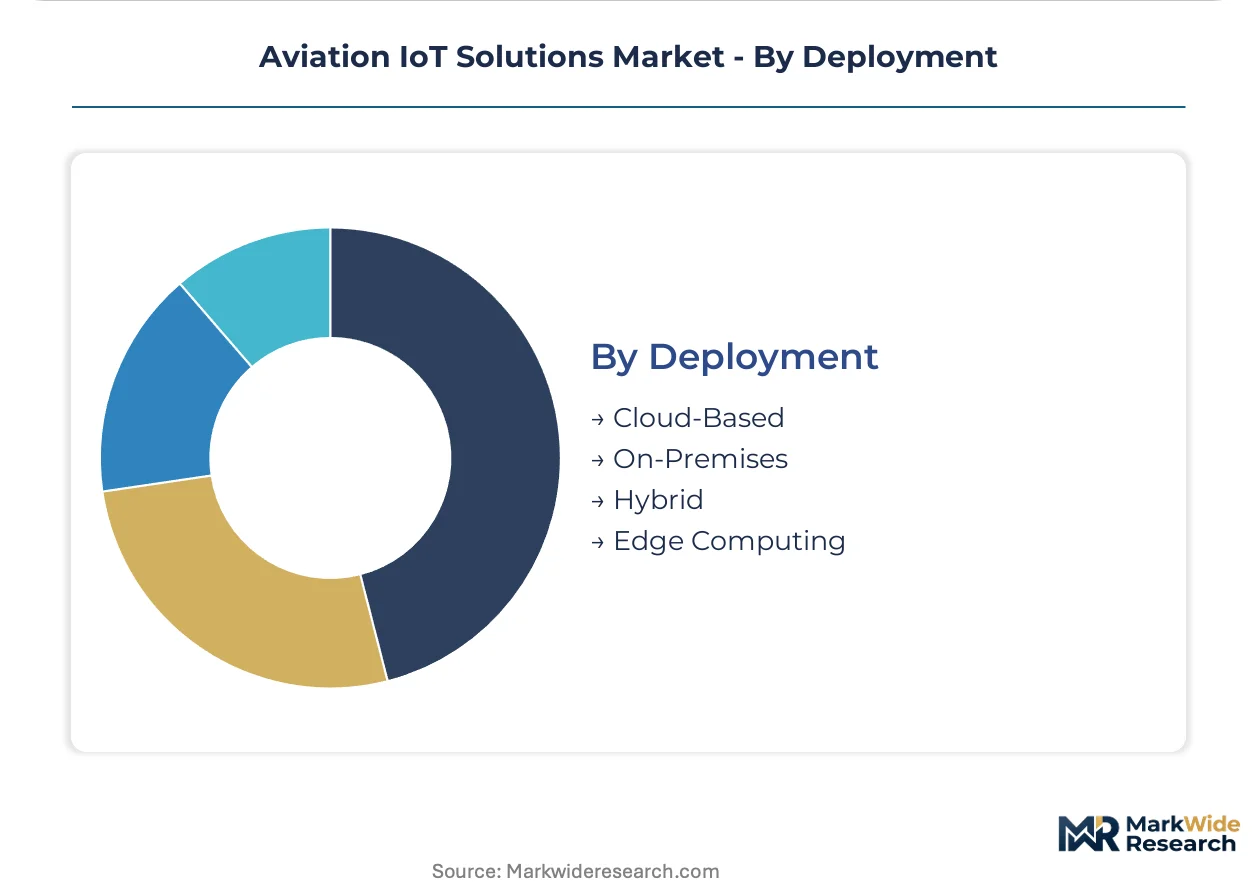
Deployment:
Latency requirements and data sovereignty concerns push architectures toward distributed models, with pure cloud solutions losing favor for safety-critical airborne applications.
- Edge Computing:Real-time inference engines process engine health and flight management data during operations rather than post-landing batch transmission. United States carriers prioritize edge nodes at hub airports to maintain telemetry continuity through satellite coverage gaps during descent and taxi phases.
- Hybrid:Architectures split processing between airborne edge nodes and ground-based cloud analytics, optimizing bandwidth costs against latency requirements. This model accommodates FAA cybersecurity certification pathways while preserving flexibility for EASA compliance divergence.
- Cloud-Based:Centralized fleet analytics platforms aggregate historical data for long-term trend analysis and machine learning model training.
- On-Premises:Dedicated infrastructure for defense and government aviation operators with classified data handling requirements.
Hybrid deployments dominate current implementations while edge computing captures the steepest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's airworthiness directive pipeline and the concentration of major carrier hubs at Atlanta Hartsfield-Jackson, Dallas-Fort Worth, and Chicago O'Hare anchor United States market leadership in aviation IoT deployment.
United States
Network carriers with centralized technical operations centers drive edge-computing infrastructure investment at hub airports. FAA mandates DO-178C software assurance and DO-254 hardware verification for connected aircraft systems, filtering non-aerospace suppliers from certification pathways. Atlanta, Dallas-Fort Worth, and Chicago O'Hare host the densest concentrations of real-time telemetry processing nodes for fuel burn optimization.
Germany
Lufthansa Technik and independent MRO networks compete for predictive maintenance algorithm deployment rights on European-registered fleets. EASA's continuing airworthiness regulations tighten software lifecycle documentation requirements for automated decision systems. The Hamburg aviation cluster concentrates avionics integration expertise where IoT gateway certification timelines determine competitive positioning.
France
Airframe OEMs embed IoT architectures directly into flight management hardware from initial design phases. The EU AI Act's risk classification framework for automated maintenance scheduling reshapes how operators deploy machine learning models. The Toulouse aerospace corridor hosts integration facilities where Thales Group competes through avionics-embedded gateway solutions.
United Kingdom
Heathrow and Gatwick ground handlers face pressure to compress turnaround times through tarmac equipment telematics adoption. The Civil Aviation Authority aligns with EASA cybersecurity certification pathways while monitoring FAA divergence risks. London's technical operations centers concentrate procurement authority for bundled fleet management subscriptions.
China
Commercial Aircraft Corporation of China drives domestic avionics certification timelines for connected flight systems on indigenous narrow-body programs. MIIT standards for airborne telecommunications equipment create parallel regulatory pathways to Western frameworks. The Shanghai-Beijing aviation corridor concentrates airline technical operations investment in predictive maintenance platform deployment.
Aviation IoT Solutions Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform providers that bundle hardware, connectivity, and analytics subscriptions. Tiered competitive positioning separates avionics-embedded specialists from enterprise networking extenders and independent software vendors. Strategic archetypes include airframe OEM-affiliated service operations, diversified industrial conglomerates with installed base leverage, and cloud-native analytics entrants. Dominant competitive moves encompass vertical integration into sensor manufacturing and exclusive data access contracting with major carrier technical operations centers.
Within the diversified industrial tier, Honeywell International and GE Aviation exemplify archetypes leveraging installed bases of auxiliary power units and engine systems to bundle predictive maintenance offerings. Cisco Systems occupies a position anchoring enterprise networking relationships that extend into airport operations centers. Thales Group sits within the avionics-embedded specialist category, competing through hardware integration directly into flight management systems rather than aftermarket add-on deployment.
| Leading Market Players |
|---|
| Honeywell International |
| Cisco Systems |
| IBM Corporation |
| Collins Aerospace |
| Huawei Technologies |
| GE Aviation |
| Thales Group |
| Microsoft Corporation |
| Amadeus IT Group |
| Others |
Value Chain & Pricing Dynamics
Foundry undercapacity for avionics-grade processors in Taiwan and South Korea compresses supplier pricing power while inflating lead-time premiums for safety-critical IoT gateways, forcing buyers toward multi-year subscription contracts that lock in component allocation priority.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating DO-178C certified platforms from uncertified commercial alternatives and economy-grade retrofit kits. Price differentiation centers on certification grade and after-sales service bundling, with FAA-compliant systems commanding substantial premiums over commercial equivalents. Cost compression in the retrofit tier intensifies as non-aerospace technology suppliers filter out of certification pathways. Ground handlers exhibit the highest price sensitivity due to thin turnaround-time margins, while network carriers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for aviation IoT hardware. Manufacturing concentrates in Taiwan, South Korea, and the United States for specialized avionics-grade processors, while China anchors assembly for commercial-grade sensor modules. Raw material dependencies include gallium nitride substrates, high-reliability capacitors, and radiation-hardened memory. Single-source vulnerability in foundry capacity serving defense-aerospace dual-use demand threatens component allocation. Distribution runs through OEM-affiliated service operations and independent MRO networks competing for data access contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation IoT incumbents face substitution pressure from cloud-native analytics entrants bundling predictive maintenance algorithms without legacy hardware dependencies, requiring defensive repositioning around certification moats and installed base data lock-in.
For Market Incumbents: Harden certification barriers by accelerating DO-178C and DO-254 investment to filter out non-aerospace technology suppliers, while consolidating exclusive data access contracts with major carrier technical operations centers to neutralize cloud-native algorithm substitution. Backward integration into sensor manufacturing secures component allocation against foundry capacity constraints. For New Entrants and Emerging Players: Pursue ground handler connectivity as the most penetrable white space, where tarmac equipment telematics for baggage flow optimization remains underdeployed relative to airborne fleet management. Target independent MRO networks with algorithm-as-a-service offerings that circumvent OEM data architecture control. Position through 5G private network deployment partnerships at hub airports. For Investors and Strategic Acquirers: Capital is best deployed toward avionics-embedded specialists with established FAA certification pathways and flight management hardware integration capabilities, given the decade-long airframe replacement cycles that sustain incumbent positions. The signal to watch is EASA-EU AI Act convergence timelines, which will determine first-mover advantage for predictive algorithm certification in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration | DO-178C software assurance investment filters non-aerospace suppliers from FAA pathways. |
| Edge Computing Deployment | Hub airport infrastructure at Atlanta and Dallas-Fort Worth compresses decision latency for fuel optimization. |
| Algorithm Licensing | Predictive maintenance model deployment rights determine competitive positioning in European markets. |
| 5G Private Network Partnership | Airport-specific cellular convergence enables ultra-low latency for engine health monitoring during taxi operations. |
| Data Access Contracting | Exclusive agreements with carrier technical operations centers lock out independent MRO network competition. |
Study Parameters
A standing panel of airline technical operations directors, MRO network procurement leads, avionics certification engineers, and airport IT infrastructure managers provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation through FAA airworthiness directive filings, EASA continuing airworthiness documentation, SEC 10-K disclosures from diversified industrial conglomerates, and customs records for avionics-grade component trade flows. Bottom-up sensor deployment counts and top-down carrier capital expenditure triangulation anchored volume estimates.
Scenario-bracketing framed projections across the analysis window, modeling technology segmentation by hardware certification tier, application by fleet management versus predictive maintenance deployment intensity, end user by airline versus ground handler procurement authority, and deployment by edge versus hybrid versus cloud architecture. CAGRs derived from airframe replacement cycle timing, regulatory mandate implementation schedules, and satellite bandwidth cost trajectory assumptions. Forecast inputs included narrow-body fleet renewal rates at United States hub carriers and EASA-EU AI Act risk classification framework adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native analytics entrants or accelerated regulatory divergence between FAA and EASA cybersecurity pathways would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Smart Home M2M Market