
 Smart Signaling Market | 2026-2036
Smart Signaling Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Signaling Market Analysis
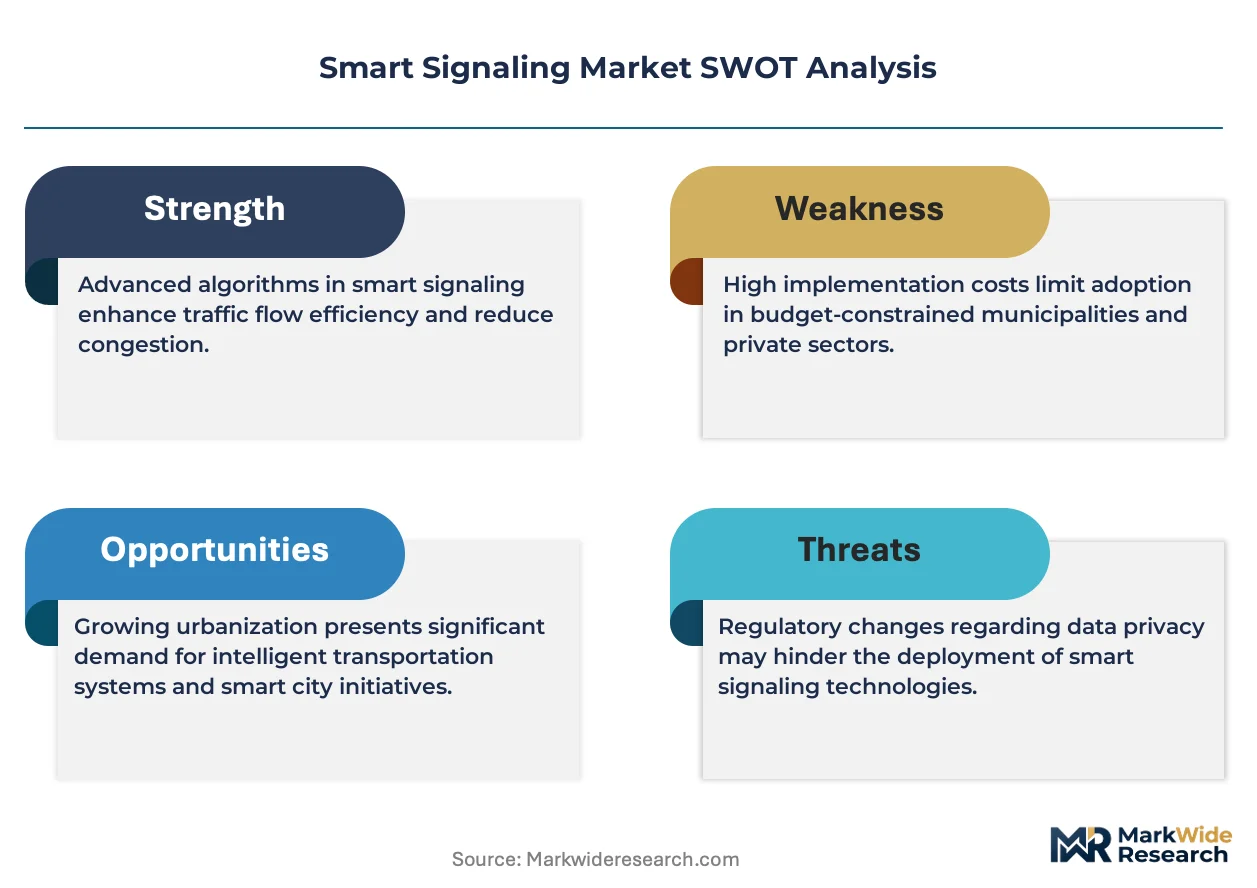
A widening capital-intensity gap between integrated platform providers and component specialists is rotating procurement leverage toward full-stack vendors. Siemens Mobility leverages its rail-traffic convergence portfolio to anchor large-scale municipal contracts across European transit corridors. Schneider Electric competes through energy-efficient signal hardware that sustains margin pools in power-constrained deployment environments.
Smart signaling encompasses sensor-networked traffic control infrastructure that processes real-time vehicle, pedestrian, and environmental data through edge-computing nodes to optimize flow dynamics, typically operating on sub-100-millisecond latency thresholds for safety-critical intersection decisions. The technology segment spans V2X, centralized control, adaptive traffic control, and cloud-based systems, with adaptive traffic control capturing concentrated investment as cities retrofit legacy fixed-timing infrastructure. Application demand clusters in traffic management and public transportation, where municipal budget cycles favor multi-year integrated deployments over point solutions.
The U.S. Department of Transportation's MUTCD compliance requirements and the EU's CE marking under the Radio Equipment Directive shape product certification pathways, while China's GB standards administered by MIIT mandate domestic cybersecurity testing for connected signal controllers. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting architecture partners for cross-border deployment pipelines.
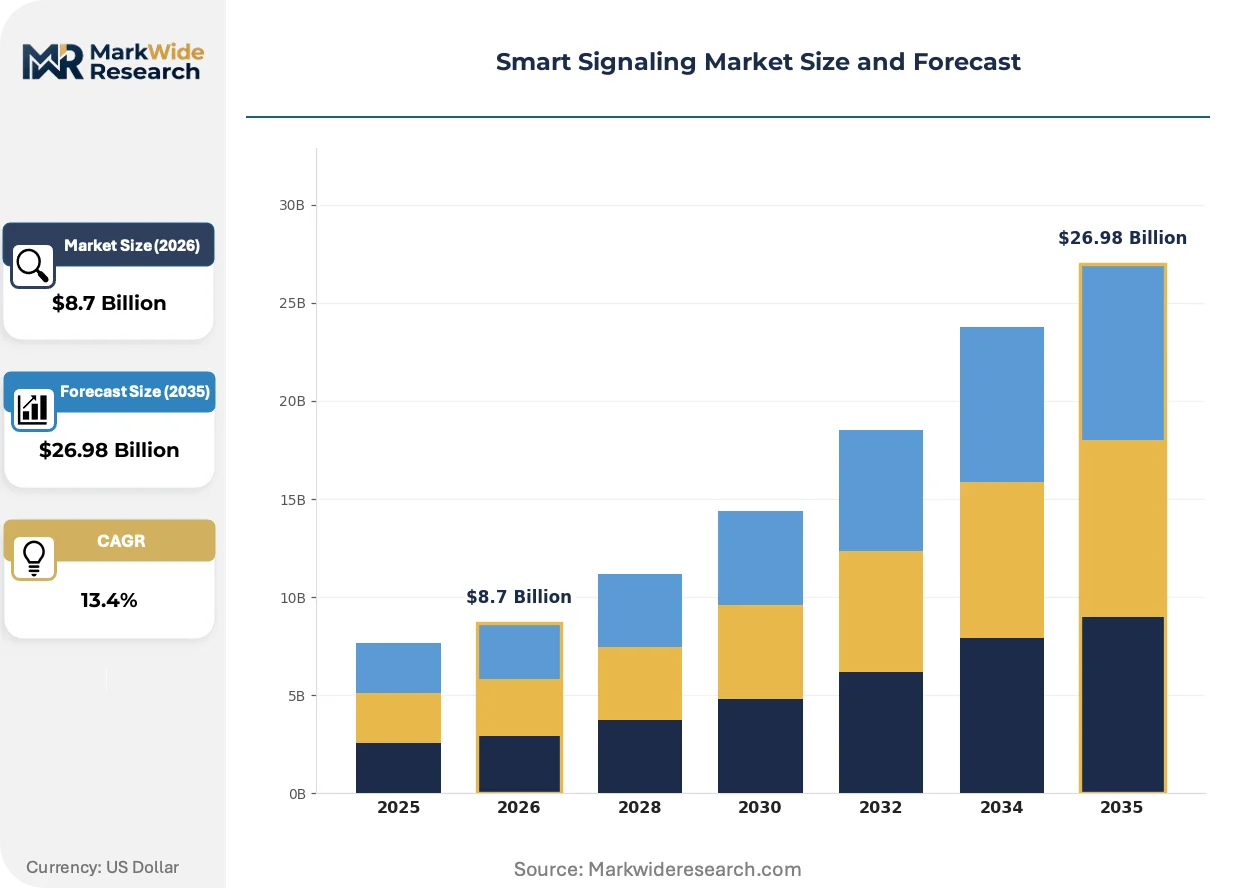
Market Dynamics
The convergence of edge-computing architectures with legacy traffic infrastructure is compressing retrofit timelines across municipal procurement cycles. Cities now demand sub-100-millisecond latency guarantees for safety-critical intersection decisions, forcing vendors to restructure hardware-software integration roadmaps.
Growth Catalysts
- EU Green Deal urban mobility mandates:Emission-performance requirements for signal infrastructure are tightening procurement specifications across German and Dutch transit authorities, accelerating adaptive controller deployments.
- Congestion pricing trials:Tier-one Chinese megacities including Shanghai and Beijing are expanding real-time traffic optimization budgets to support road-pricing infrastructure.
- V2X communication protocols:Vehicle-to-everything interoperability standards are unlocking federal highway modernization funding streams in the United States.
Market Restraints
- Semiconductor supply concentration:Edge-computing node production depends on concentrated East Asian foundry capacity, exposing signal controller lead times to geopolitical disruption.
- Cybersecurity certification friction:China's GB standards administered by MIIT mandate domestic testing protocols that extend product approval timelines for foreign vendors.
- Copper and rare-earth input volatility:Inductive loop sensors and power-efficient hardware require stable commodity pricing that procurement budgets rarely hedge against.
Strategic Opportunities
- Rail-traffic convergence platforms:Integrated multimodal control systems that unify urban rail and road signaling represent underpenetrated white space in European transit corridors.
- Power-constrained deployment environments:Energy-efficient signal hardware tailored for grid-weak municipalities in Southeast Asia and sub-Saharan Africa commands premium positioning.
- Cloud-based centralized control:Software-as-a-service traffic management architectures are displacing capital-heavy on-premise installations in mid-sized North American cities.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for sub-100-millisecond safety-critical decisions requires specialized skill sets concentrated among automotive and aerospace labor pools.
- Legacy intersection controller integration:Municipal maintenance contracts often bind agencies to decades-old electromechanical timing systems that resist digital retrofit without full replacement.
- Cross-border certification fragmentation:The U.S. MUTCD, EU CE marking under the Radio Equipment Directive, and China's MIIT cybersecurity testing create divergent compliance pathways that fragment product architecture standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Signaling Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: V2X, Centralized Control, Adaptive Traffic Control, Cloud-Based Systems Application: Traffic Management, Fleet Management, Emergency Services, Public Transportation End User: Municipalities, Transportation Agencies, Private Operators, Urban Planners Solution: Hardware, Software, Services, Integration Solutions |
| Companies Covered | Siemens Mobility, Schneider Electric, Honeywell International Inc., Hitachi Ltd., Kapsch TrafficCom AG, Cisco Systems, Thales Group, Mitsubishi Electric, Cubic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Signaling Market Emerging Trajectories
Real-time data fusion at the network edge is compressing the boundary between traffic sensing and actuation, collapsing traditional hierarchies of centralized command-and-control. Municipal buyers now prioritize platforms that unify multimodal inputs rather than siloed point solutions.
Edge-native AI inference engines are supplanting rule-based adaptive algorithms in next-generation intersection controllers. German transit authorities in Munich and Hamburg are piloting these systems for predictive pedestrian crossing optimization. The technology is supplanting legacy fixed-timing infrastructure by enabling dynamic signal phasing that responds to real-time multimodal demand fluctuations rather than historical traffic patterns.
The EU AI Act's risk-classification framework is redefining liability boundaries for autonomous traffic decision systems. Signal controllers processing safety-critical outputs now face conformity assessment requirements previously reserved for medical devices and automotive systems. European vendors are responding by restructuring quality management systems to capture algorithmic audit trails for regulatory examination.
Municipal procurement offices are consolidating vendor relationships around multi-year integrated deployment contracts. Point-solution specialists find themselves excluded from RFP shortlists that favor full-stack platform providers with captive maintenance capabilities. This concentration is most visible in Australian state-level transport departments, where single-vendor ten-year agreements now dominate over annual equipment purchases.
Smart Signaling Market Segmentation
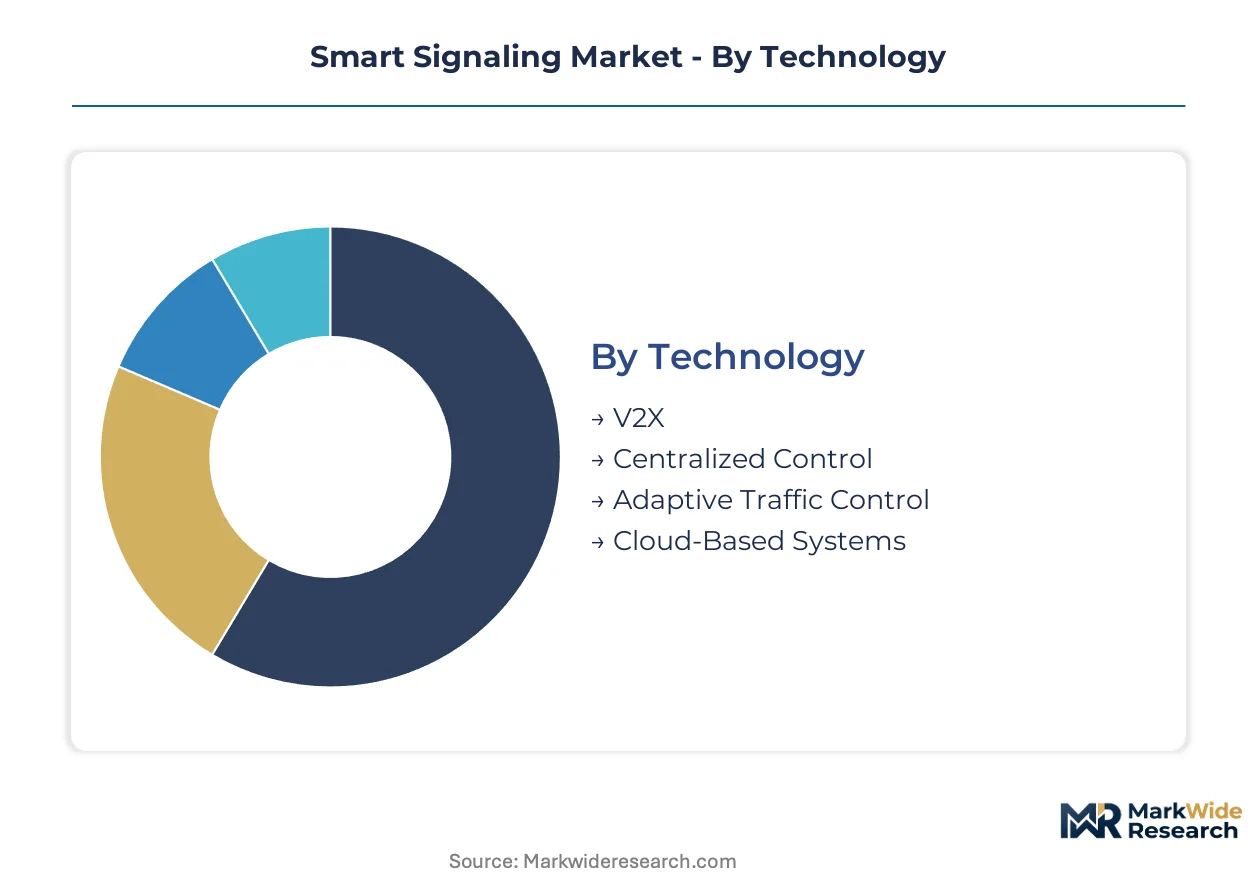
Smart signaling procurement flows through distinct channel architectures that vary by technology maturity and municipal budget cycles. Vendors must align segment-specific value propositions with whether buyers favor capital-heavy integrated deployments or recurring software subscriptions.
Technology:
Channel mix varies sharply across technology segments, with hardware-intensive categories flowing through municipal RFP processes while software-centric offerings migrate to SaaS procurement frameworks.
- Adaptive Traffic Control:Edge-computing nodes process real-time multimodal data to dynamically adjust signal phasing, replacing legacy fixed-timing infrastructure. German transit authorities in Munich and Hamburg are retrofitting intersections with these systems under EU Green Deal procurement mandates.
- V2X:Vehicle-to-everything protocols enable direct communication between connected vehicles and signal infrastructure, requiring roadside unit deployment alongside controller upgrades. Federal highway modernization funding in the United States is concentrating demand along interstate corridors where NHTSA interoperability standards apply.
- Centralized Control:Hub-and-spoke architectures aggregate intersection data at municipal traffic management centers.
- Cloud-Based Systems:Software-as-a-service platforms displace on-premise installations in mid-sized North American cities seeking operational expenditure flexibility.
Adaptive Traffic Control dominates installed base. Cloud-Based Systems are where expansion concentrates most quickly.
Application:
Cost tier stratification separates mission-critical safety applications from efficiency-optimization use cases, with emergency services commanding premium pricing while fleet management competes on volume.
- Traffic Management:Real-time flow optimization across arterial networks and intersection grids constitutes the core revenue pool. Tier-one Chinese megacities including Shanghai and Beijing are expanding budgets to support congestion pricing infrastructure integration.
- Public Transportation:Signal priority systems for buses and trams reduce dwell time at intersections and improve schedule adherence. European transit corridors are unifying rail and road signaling through multimodal convergence platforms.
- Emergency Services:Preemption systems grant priority passage to ambulances and fire apparatus.
- Fleet Management:Commercial vehicle routing optimization leverages signal timing data for fuel efficiency gains.
Traffic Management anchors current revenue. Public Transportation is climbing the fastest as cities prioritize modal shift targets.
End User:
Customer type determines contract structure, with public agencies favoring multi-year integrated agreements and private operators seeking modular point solutions.
- Municipalities:City traffic departments procure comprehensive intersection modernization through single-vendor ten-year agreements. Australian state-level transport departments have consolidated procurement around captive maintenance capabilities.
- Transportation Agencies:Regional and national bodies coordinate corridor-level signal coordination across jurisdictional boundaries.
- Private Operators:Shopping center developers and campus managers deploy localized adaptive systems.
- Urban Planners:Consultancies specify signaling requirements for new district developments and retrofit studies.
Municipalities control the deepest procurement budgets. Transportation Agencies are gaining share fastest as corridor-level coordination expands.
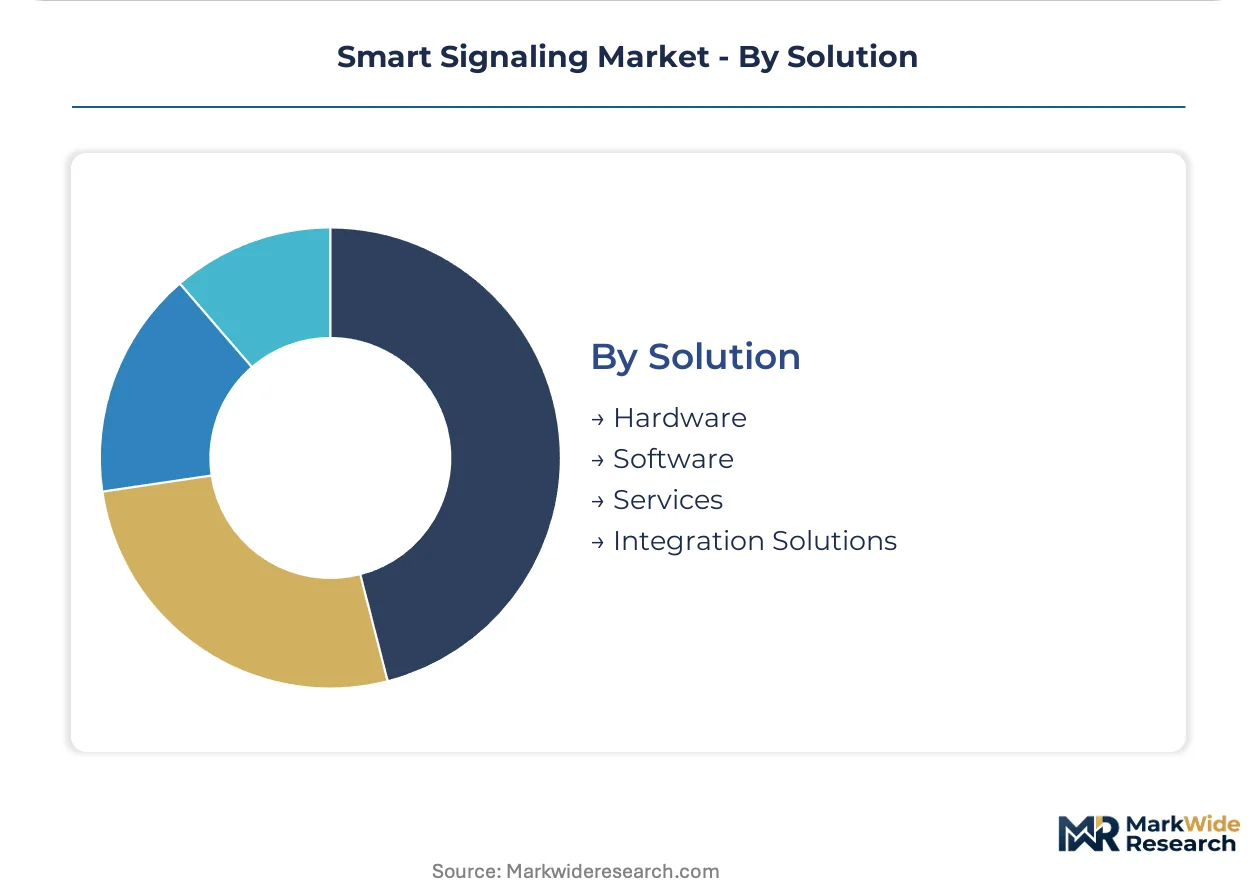
Solution:
Margin structure diverges across the solution stack, with integration services capturing premium pricing while hardware faces commodity pressure from power-efficient component competition.
- Hardware:Signal controllers, sensors, and roadside units form the capital foundation of deployments. Schneider Electric competes through energy-efficient designs that sustain margins in grid-constrained Southeast Asian and sub-Saharan African markets.
- Software:Adaptive algorithms and traffic management platforms enable recurring revenue streams. Edge-native AI inference engines are supplanting rule-based systems in next-generation controller specifications.
- Services:Installation, calibration, and ongoing maintenance contracts bind agencies to vendor ecosystems.
- Integration Solutions:Full-stack deployment unifying legacy retrofit with new infrastructure commands premium positioning.
Hardware dominates installed base. Software is where expansion concentrates as municipal buyers shift toward operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in smart signaling hardware tilt toward import dependence across emerging economies while established manufacturing bases in Germany, Japan, and the United States sustain equipment export surpluses. Component specialization in East Asian semiconductor foundries concentrates edge-computing node supply, creating vulnerability in procurement timelines for European and North American transit authorities.
United States
Federal highway modernization funding under the Infrastructure Investment and Jobs Act is channeling investment toward V2X corridor deployment along interstate networks. NHTSA interoperability standards and FCC spectrum allocation for connected vehicle communications shape vendor certification requirements. The I-95 corridor from Washington to Boston represents the densest concentration of adaptive intersection retrofit activity.
Germany
Munich and Hamburg transit authorities are expanding procurement of edge-native AI inference systems for predictive pedestrian optimization. KBA vehicle-type approval processes and EU Green Deal urban mobility mandates tighten emission-performance specifications for signal infrastructure. The Rhine-Ruhr metropolitan region anchors continental demand for rail-traffic convergence platforms.
China
Shanghai and Beijing municipal governments are accelerating real-time traffic optimization budgets to support congestion pricing trial infrastructure. MIIT-administered GB standards mandate domestic cybersecurity testing protocols for connected signal controllers, extending approval timelines for foreign equipment vendors. The Yangtze River Delta cluster concentrates manufacturing capacity for inductive loop sensors and power-efficient controllers.
Japan
Tokyo Metropolitan Government is deploying centralized traffic management centers with sub-100-millisecond latency guarantees for the 2025-2030 capital region renewal plan. METI industrial standards and JIS certification requirements govern edge-computing hardware specifications for safety-critical applications. The Kansai corridor linking Osaka, Kyoto, and Kobe represents the second-largest adaptive controller installed base in Asia-Pacific.
Australia
State-level transport departments in New South Wales and Victoria have consolidated procurement around single-vendor ten-year integrated deployment agreements. TGA-equivalent infrastructure safety frameworks and state-level climate resilience mandates shape hardware durability specifications. The Sydney-Canberra-Melbourne corridor dominates Oceania demand for cloud-based centralized control migration.
Smart Signaling Market Vendor Landscape
Concentration sits with integrated platform providers that command multi-year municipal contracts through captive maintenance capabilities and rail-traffic convergence portfolios. Siemens Mobility leverages its multimodal control heritage to anchor large-scale European transit corridor deployments. Schneider Electric competes through energy-efficient signal hardware that sustains margin pools in grid-constrained Southeast Asian and sub-Saharan African markets. Strategic moves center on backward integration into edge-computing semiconductor sourcing and geographic expansion through state-level transport department consolidation in Australia and the United States.
Within the full-stack platform tier, Siemens Mobility and Schneider Electric exemplify divergent positioning strategies—one through rail-road convergence dominance, the other through power-constrained deployment specialization. Kapsch TrafficCom AG occupies a position representing European V2X protocol leadership. Hitachi Ltd. and Mitsubishi Electric anchor Japanese-origin supply for latency-critical Asian megacity deployments. These five entities collectively illustrate the competitive spectrum from energy-efficiency hardware to multimodal software integration.
| Leading Market Players |
|---|
| Siemens Mobility |
| Schneider Electric |
| Honeywell International Inc. |
| Hitachi Ltd. |
| Kapsch TrafficCom AG |
| Cisco Systems |
| Thales Group |
| Mitsubishi Electric |
| Cubic Corporation |
| Others |
Supply Flow & Price Mechanics
Controller lead times stretching 18-24 months concentrate pricing power with foundry-integrated vendors while fragmenting procurement leverage among municipal buyers locked into legacy maintenance contracts. This inventory compression reshapes vendor selection criteria toward suppliers with captive semiconductor sourcing and forward-committed foundry slots.
Pricing Analysis
The customization-premium spread between configured-to-order edge-computing nodes and standard adaptive controllers spans project-based capital deployments and recurring SaaS subscriptions for cloud-based traffic management. Price differentiation hinges on CE marking tier under the EU Radio Equipment Directive and after-sales service bundling through captive maintenance agreements. Cost compression in standard hardware tiers intensifies as Schneider Electric and Siemens Mobility compete on energy-efficiency specifications. Municipalities exhibit highest price sensitivity due to multi-year budget cycles, while private operators in campus and shopping center deployments absorb premiums for rapid deployment timelines.
Supply Chain Analysis
Strategic stockpiling of inductive loop sensors and power-efficient controllers dominates procurement behavior among German and Australian transit authorities confronting semiconductor allocation volatility. Manufacturing concentration centers on China for inductive loop sensors, Taiwan for edge-computing node foundry capacity, and Germany for rail-traffic convergence platforms. Raw material dependencies include copper for sensor coils, rare-earth elements for power-efficient magnetics, and advanced lithography for AI inference chips. Single-source vulnerability in East Asian semiconductor foundries exposes signal controller delivery schedules to geopolitical disruption. Distribution runs through municipal RFP processes for hardware-intensive categories and direct SaaS procurement frameworks for software-centric offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart signaling hardware commoditization accelerates service-attach revenue expansion as cloud-based traffic management platforms and predictive maintenance contracts outpace controller unit growth. Municipal procurement consolidation around ten-year integrated agreements elevates recurring revenue streams above one-time installation margins.
For Market Incumbents: Fortify captive maintenance capabilities through backward integration into edge-computing semiconductor sourcing, securing foundry allocation priority against fabless challengers. Deepen rail-traffic convergence platform penetration across European transit corridors where EU Green Deal mandates tighten emission-performance specifications. Expand state-level transport department consolidation in Australia and the United States to lock out point-solution specialists from RFP shortlists.
For New Entrants and Emerging Players: Differentiate on power-constrained deployment specialization targeting grid-weak municipalities in Southeast Asia and sub-Saharan Africa where energy-efficient hardware commands premium positioning. Target mid-sized North American cities migrating from capital-heavy on-premise installations to SaaS-based centralized control architectures. Pursue corridor-level coordination contracts through transportation agencies gaining procurement share fastest.
For Investors and Strategic Acquirers: Long-term, this sits as a subscription-revenue play because municipal procurement consolidation favors full-stack vendors with recurring maintenance contracts over hardware-only suppliers. Acquisition targets should display captive edge-computing firmware development capabilities and established relationships with German KBA or Australian state-level transport departments. The signal to watch is V2X protocol standardization progress under NHTSA interoperability mandates, which would unlock federal highway modernization funding streams and reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge-Computing Semiconductors | Secures foundry allocation priority against fabless competitors facing MIIT certification delays. |
| Rail-Traffic Convergence Platform Expansion | Captures EU Green Deal procurement mandates across Rhine-Ruhr and Munich-Hamburg transit corridors. |
| SaaS Migration for Mid-Sized Municipalities | Displaces capital-heavy on-premise installations with operational expenditure flexibility in North America. |
| Power-Constrained Hardware Specialization | Commands premium positioning in grid-weak Southeast Asian and sub-Saharan African deployment environments. |
| State-Level Transport Department Consolidation | Locks in ten-year integrated agreements excluding point-solution specialists from Australian RFP shortlists. |
Methodological Framework
The analysis maps adaptive traffic control, V2X communication, centralized control, and cloud-based systems segments, each validated through municipal traffic engineers, transit authority procurement officers, signal controller firmware developers, and edge-computing hardware specialists. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed infrastructure vendors, EU procurement databases tracking German and Dutch adaptive controller deployments, MIIT GB standards documentation, and NHTSA interoperability guidance. Bottom-up unit economics triangulated against top-down municipal budget allocation data across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including federal highway modernization funding disclosures, EU Green Deal urban mobility allocation reports, and tier-one Chinese megacity congestion pricing infrastructure budgets. The analytical framework modeled technology deployment mode, application criticality tier, end-user contract structure, and solution stack position across the projection horizon. CAGRs derived from intersection retrofit pipeline analysis, V2X roadside unit deployment trajectories, and SaaS migration rates among mid-sized North American cities.
Forecasts assume regulatory continuity in FCC spectrum allocation, EU CE marking under the Radio Equipment Directive, and MIIT cybersecurity testing protocols; material policy shifts would require re-modeling certification pathway timelines and vendor approval schedules. Revision becomes warranted when semiconductor foundry capacity utilization or copper commodity price volatility crosses thresholds that alter controller unit economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Smart Space Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Global Smart City Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Smart City Platform Market