
 Smart Thermostat Market | 2026-2036
Smart Thermostat Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Thermostat Market Intelligence
Modular bundling of thermostats with heat-pump and ventilation systems is recalibrating buyer choice away from standalone hardware. Honeywell International leverages its building-automation heritage to anchor premium integrated-system contracts. Ecobee specializes in voice-native interfaces that differentiate its position in the DIY channel.
A smart thermostat is a network-connected environmental control device that regulates heating, ventilation, and air conditioning through sensors, algorithms, and user-programmable setpoints, typically operating via Wi-Fi or wired protocols with temperature accuracy within 0.5 degrees Celsius. Its primary commercial purpose is to reduce energy consumption while maintaining occupant comfort through automated scheduling and remote management. Wi-Fi Enabled units dominate volume because retrofit compatibility lowers installation friction, while Smart Learning variants capture disproportionate margin pools through subscription-backed energy analytics. Residential end users still account for the largest absolute base, though Commercial deployments are expanding fastest as facility managers adopt centralized portfolio controls.
EPA ENERGY STAR certification shapes product design thresholds for North American market access, while EU Ecodesign requirements and the F-Gas Regulation tighten interoperability and refrigerant-handling standards across European HVAC replacements. China's GB standards and MIIT network-security rules add compliance layers for connected-device imports. Stakeholders must monitor how grid-interactive demand-response tariffs in multiple jurisdictions reshape thermostat firmware requirements and partnership strategies with utility platforms.
Market Dynamics
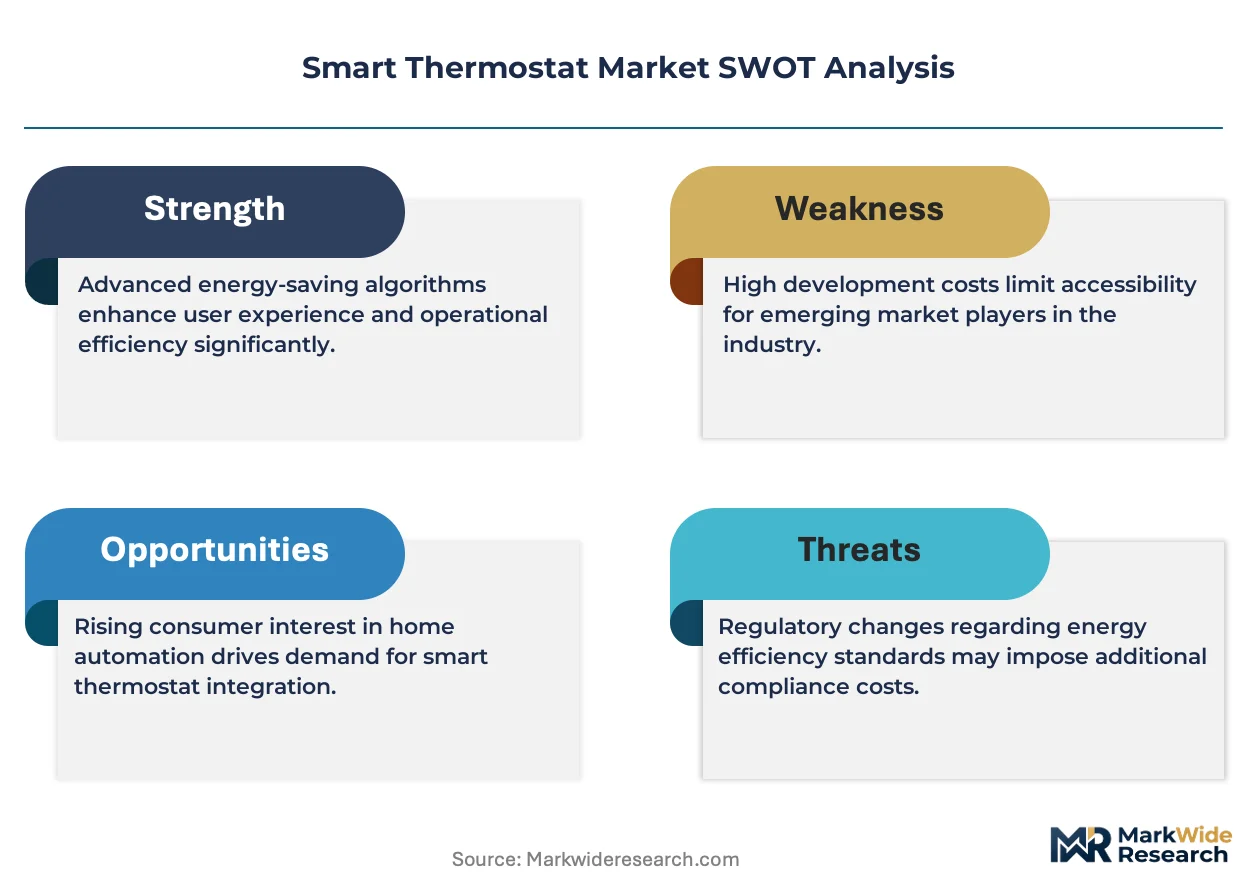
Grid-interactive demand-response programs are restructuring procurement priorities across the smart thermostat value chain, forcing hardware manufacturers to embed firmware that communicates with utility platforms rather than optimizing solely for consumer convenience.
Growth Catalysts
- EPA ENERGY STAR Certification:North American market access now requires meeting strict energy-efficiency thresholds that retrofit buyers prioritize when replacing legacy programmable units.
- China's MIIT Network-Security Rules:Import compliance layers for connected devices are accelerating partnerships between foreign OEMs and domestic firmware developers to satisfy data-localization mandates.
- Heat-Pump Bundling:HVAC replacement cycles in Germany and the United States increasingly specify thermostats as integrated system components rather than standalone purchases.
Market Restraints
- Semiconductor Supply Concentration:Wi-Fi and Bluetooth module sourcing remains concentrated among a limited set of Asian contract manufacturers, exposing lead-time volatility.
- F-Gas Regulation Friction:The EU's refrigerant-phaseout mandates compress installation windows for bundled thermostat-HVAC upgrades, creating inventory coordination complexity.
- Legacy Wiring Infrastructure:Residential buildings without C-wire compatibility require professional installation or adapter hardware, raising total cost of ownership.
Strategic Opportunities
- Commercial Building Portfolios:Facility managers in the United States are centralizing climate controls across distributed real estate assets, opening bulk-contract channels.
- Voice-Native Interface Convergence:Integration between natural-language processing and occupancy sensing creates differentiation in the DIY retail channel.
- India's PLI Scheme for Electronics:Domestic manufacturing incentives for connected devices reduce import duties and enable price-competitive positioning in South Asian markets.
Industry Challenges
- Cybersecurity Certification Timelines:UL 2900 and IEC 62443 testing protocols extend product launch schedules by six to nine months for new connected-device entrants.
- Utility Platform Fragmentation:Proprietary demand-response APIs across regional power authorities force manufacturers to maintain multiple firmware branches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Thermostat Market |
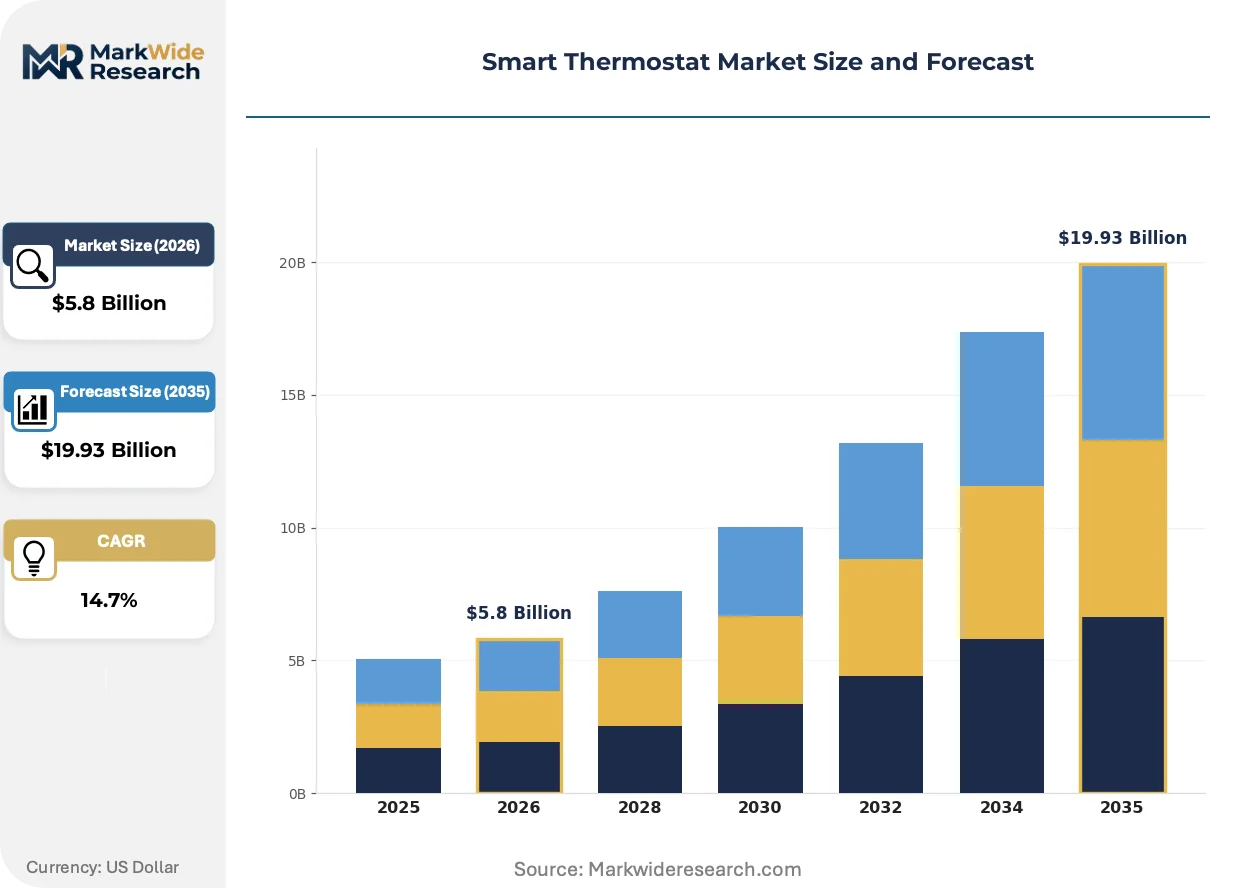
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.93 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Enabled, Wired, Battery Operated, Smart Learning End User: Residential, Commercial, Industrial, Retail Technology: Touchscreen, Voice Control, Remote Access, Mobile App Installation: Professional, DIY, Integrated Systems, Retrofit |
| Companies Covered | Emerson Electric, Johnson Controls, Honeywell International, Siemens AG, Trane Technologies, Google Nest, Carrier Corporation, Lennox International, Ecobee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Thermostat Market Strategic Shifts & Innovations
Machine-learning inference at the edge is displacing cloud-dependent temperature prediction, reducing latency while addressing data-privacy concerns that have slowed enterprise adoption.
Occupancy-sensing algorithms using millimeter-wave radar and passive infrared fusion are consolidating environmental control logic into single-chip architectures. Commercial building operators in Germany and the United States are specifying these integrated sensors for open-plan offices where traditional thermostat placement fails. The technology is consolidating vendor margins by eliminating separate motion-detector hardware from BOMs.
The EU F-Gas Regulation is tightening interoperability requirements for HVAC replacement bundles, mandating that new thermostats communicate with heat-pump defrost cycles and refrigerant-pressure sensors. Equipment manufacturers serving the German and French markets are redesigning control boards to satisfy these telemetry standards. Residential installers now face retraining obligations to maintain certification under the EU Green Deal implementation frameworks.
Subscription-backed energy analytics are unbundling from hardware purchase prices, shifting buyer relationships toward ongoing service engagement. Property management firms in the United States are piloting these models across multifamily housing portfolios. The pattern is most visible in California and Texas, where time-of-use electricity tariffs create measurable savings that justify recurring fees.
Smart Thermostat Market Segmentation
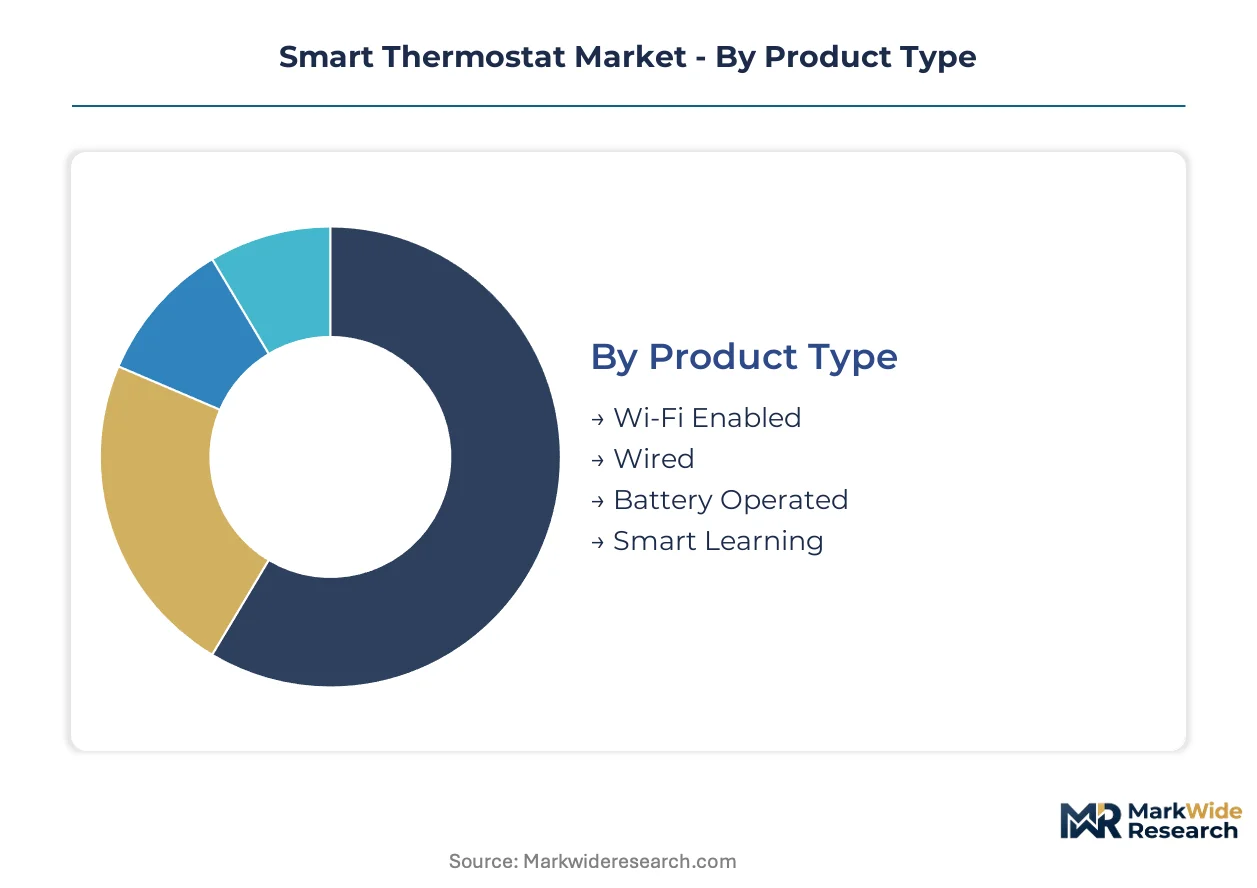
Replacement cycles for HVAC infrastructure create divergent demand profiles across thermostat categories. Builders, facility managers, and homeowners select different feature bundles based on installation constraints and system integration requirements.
Product Type:
Retrofit compatibility and upgrade friction determine which hardware formats capture replacement demand.
- Wi-Fi Enabled:Units connect via standard 802.11 protocols to existing residential routers, eliminating dedicated wiring runs. Demand concentrates in suburban North American retrofits where homeowners prioritize smartphone control without electrical contractor visits.
- Smart Learning:Algorithms ingest occupancy patterns and weather data to autonomously adjust setpoints, typically requiring cloud connectivity for model training. Germany and California utilities specify these units for time-of-use tariff participation, bundling hardware subsidies with demand-response enrollment.
- Wired:Ethernet or proprietary bus connections deliver deterministic latency for commercial building automation systems. Industrial facilities in China specify wired protocols to satisfy MIIT network-security rules on critical infrastructure segmentation.
- Battery Operated:Low-power radio modules extend deployment to locations lacking C-wire or neutral conductor access. Rental property managers in the United States favor these for rapid installation turnover.
Volume placements concentrate in Wi-Fi Enabled units; the faster expansion belongs to Smart Learning.
End User:
Decision authority and procurement scale fragment the customer base across installation types.
- Residential:Single-family homeowners and multifamily tenants purchase through retail channels or HVAC contractor recommendations. The United States dominates absolute unit volume through utility rebate programs and ENERGY STAR certification requirements.
- Commercial:Facility managers centralize climate controls across distributed real estate portfolios, specifying networked thermostats with centralized dashboards. Germany's F-Gas Regulation accelerates bundled replacements in office buildings undergoing heat-pump conversions.
- Industrial:Manufacturing plants deploy thermostats as subcomponents of process control systems, prioritizing reliability over consumer features. China's GB standards mandate specific interoperability protocols for industrial HVAC imports.
- Retail:Big-box stores and restaurant chains standardize on specific thermostat models to simplify maintenance training and spare parts inventory across hundreds of locations.
Residential channels move the highest unit volumes; commercial deployments are climbing the fastest.
Technology:
Interface modality shapes differentiation and margin capture in crowded hardware markets.
- Mobile App:Smartphone-native control layers dominate consumer expectations, with firmware updates delivered over-the-air. China's MIIT rules require domestic data localization for app-connected devices, favoring partnerships with local cloud providers.
- Voice Control:Natural-language processing integration enables hands-free adjustment, differentiating DIY retail positioning. Amazon Alexa and Google Assistant compatibility has become table stakes in North American consumer channels.
- Touchscreen:Capacitive displays with haptic feedback replace physical buttons for schedule programming and energy reporting visualization.
- Remote Access:Cloud portals enable property managers to adjust setpoints across dispersed assets without on-site visits.
Mobile App interfaces anchor current shipments; Voice Control is gaining share fastest.
Installation:
Labor requirements and system architecture determine channel economics and customer acquisition costs.
- DIY:Battery-powered or C-wire-compatible units target homeowners seeking weekend projects without contractor scheduling. Retail margins compress as hardware commoditizes, shifting profit pools to subscription energy analytics.
- Professional:Licensed electricians handle C-wire installation, panel upgrades, and commissioning for integrated system performance. Germany's EU Green Deal certification frameworks require installer retraining for heat-pump bundle compliance.
- Integrated Systems:Thermostats ship pre-configured with heat pumps, ventilation units, and refrigerant sensors from single OEMs. The F-Gas Regulation mandates this bundling for new HVAC installations across France and Germany.
- Retrofit:Adapter hardware and wireless relays extend smart control to legacy furnace and boiler systems without full replacement.
Professional installation handles the bulk of integrated-system volume; DIY channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while consumption tilts toward North American and European retrofit markets. Utility rebate programs and refrigerant-phaseout mandates are synchronizing replacement cycles across three continents.
United States
Utility-sponsored demand-response programs in California and Texas drive Smart Learning thermostat adoption through tariff-linked subsidies. EPA ENERGY STAR certification gates retail distribution in big-box channels. The Dallas-Fort Worth metroplex anchors contractor-network density for heat-pump bundle installations.
Germany
Heat-pump conversion timelines under the EU Green Deal compress installation windows for bundled thermostat upgrades. The F-Gas Regulation mandates refrigerant-pressure sensor interoperability in new HVAC controls. Bavaria's building-automation clusters supply firmware integration for pan-European OEMs.
China
MIIT network-security rules and GB standards fragment import compliance for connected climate devices. Domestic OEMs capture volume in industrial wired-protocol segments. The Yangtze River Delta concentration of Wi-Fi module fabricators supplies contract manufacturers serving North American retail brands.
India
PLI scheme incentives for electronics manufacturing reduce landed costs for battery-operated thermostat SKUs targeting rental housing. BIS certification requirements extend product launch timelines for foreign entrants. Maharashtra's Pune-Aurangabad corridor hosts emerging assembly operations for South Asian distribution.
Japan
METI efficiency standards and JIS interoperability protocols shape premium product specifications for residential retrofits. Voice-native interface adoption lags North American penetration due to language-localization requirements. The Kansai region's HVAC component suppliers integrate occupancy-sensing modules for export markets.
Smart Thermostat Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with building-automation heritage. Three tiers have crystallized: integrated-system OEMs bundling thermostats with heat pumps; voice-native specialists targeting DIY retail; and contract manufacturers supplying private-label hardware. Consolidation pressure runs through utility-platform certification requirements that favor firmware scale. Geographic expansion and technology licensing dominate strategic moves as players navigate regional compliance fragmentation.
Among diversified industrial groups, Honeywell International and Siemens AG exemplify the integrated-system archetype through building-controls heritage. Johnson Controls occupies a parallel position in commercial facility-management channels. Ecobee represents the voice-native specialist tier, differentiated by natural-language interface positioning in North American retail. Emerson Electric and Carrier Corporation anchor the HVAC-OEM bundling segment, where thermostat specification follows heat-pump and ventilation system procurement. Google Nest sits within the platform-ecosystem tier, leveraging cloud infrastructure and consumer electronics distribution scale.
| Leading Market Players |
|---|
| Emerson Electric |
| Johnson Controls |
| Honeywell International |
| Siemens AG |
| Trane Technologies |
| Google Nest |
| Carrier Corporation |
| Lennox International |
| Ecobee |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between ENERGY STAR-qualified and non-certified hardware manifests in both pricing power and supply chain sourcing strategies. Premium-tier manufacturers command hardware margins through EPA certification gating while commodity producers compete on module cost from Yangtze River Delta fabricators. This divergence forces buyers to choose between rebate-eligible efficiency premiums and upfront cost minimization.
Pricing Analysis
Margin tightening in Wi-Fi enabled retrofits reflects semiconductor module commoditization from concentrated Asian contract manufacturers. Three-tier pricing structure across premium learning algorithms, standard connected units, and economy battery-operated SKUs separates subscription-backed analytics from transactional hardware. Cost-down pressure on DIY channels accelerates because retail buyers prioritize smartphone compatibility over occupancy-sensing precision. Property management firms show lowest price sensitivity given bulk-contract scale, while individual homeowners in replacement cycles exhibit highest elasticity.
Supply Chain Analysis
UL 2900 and IEC 62443 cybersecurity certifications gate component sourcing from Taiwan, China, and South Korea module suppliers. Wi-Fi radio stacks, millimeter-wave radar sensors, and low-power microcontrollers draw from East Asian electronics clusters with limited alternative sourcing. Single-source vulnerability concentrates in Bluetooth LE fabricators serving voice-native interface specialists. Distribution runs through HVAC contractor networks for integrated-system bundles and big-box retail for DIY retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a cost-of-compliance moat that advantages incumbents with refrigerant-handling telemetry integration, forcing new entrants to absorb six-to-nine-month certification timelines before market access.
For Market Incumbents: Anticipate firmware fragmentation from utility-platform API divergence by maintaining multiple demand-response branches rather than consolidating on single-stack architectures. Defensive positioning requires backward integration into occupancy-sensing chip design to eliminate separate motion-detector BOMs and protect margin pools from voice-native specialists. Channel control through HVAC installer certification programs locks out unbundled thermostat competitors in German and French replacement cycles. For New Entrants and Emerging Players: Battery-operated rental property managers in the United States represent an underserved buyer archetype with rapid-installation requirements and low brand loyalty. This segment tolerates stripped feature sets in exchange for turnover-speed compatibility. White-space targeting should prioritize India's PLI scheme manufacturing corridors for duty-advantaged South Asian positioning. Go-to-market execution through property technology platforms rather than retail distribution bypasses incumbent channel saturation. For Investors and Strategic Acquirers: Re-rating potential sits with voice-native interface specialists given natural-language processing convergence as the next differentiation vector. Long-term viability over a five-to-ten-year horizon favors acquisition targets with utility-platform certification scale rather than hardware-only positioning. The signal to watch is grid-interactive tariff rollout velocity in Texas and California as inflection indicator for subscription analytics attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Platform Certification | EPA ENERGY STAR and F-Gas interoperability mandates gate rebate-eligible distribution channels. |
| Edge Machine Learning Integration | On-device inference reduces cloud latency while addressing MIIT data-localization requirements in China. |
| Heat-Pump Bundle Partnerships | EU Green Deal compressor replacement cycles specify pre-integrated thermostat controls in Germany. |
| Subscription Analytics Unbundling | Time-of-use tariff participation in California creates recurring revenue pools beyond hardware margins. |
| Occupancy Sensor Consolidation | Millimeter-wave radar fusion eliminates separate PIR hardware from commercial building BOMs. |
Research Approach
Independent corroboration across HVAC contractor interviews, utility demand-response program administrators, and building automation system integrators underwrites the qualitative findings. Primary fieldwork engaged thermostat OEM product managers, firmware developers, and commercial facility managers alongside secondary validation through EPA ENERGY STAR certification databases, EU F-Gas Regulation implementation filings, and MIIT network-security compliance disclosures. Bottom-up unit shipment estimates triangulate against top-down replacement-cycle modeling across residential, commercial, and industrial end-use segments.
Rate-of-change decomposition separates volume growth from value expansion across Wi-Fi enabled, Smart Learning, wired-protocol, and battery-operated product categories throughout the forecast period. Segmentation dimensions modeled include installation type, end-user decision authority, and technology interface modality alongside geographic regulatory cluster alignment. CAGRs derive from HVAC replacement cycle timing, utility rebate program enrollment trajectories, and refrigerant-phaseout mandate synchronization. Forecast inputs incorporate heat-pump conversion timelines under EU Green Deal frameworks and semiconductor module lead-time volatility indices.
Revisions become necessary when utility demand-response API standardization accelerates or cybersecurity certification timelines extend beyond current baselines. Forecasts reflect documented assumptions regarding rebate program continuity and refrigerant-handling installer certification penetration. A model refresh is warranted upon material change in grid-interactive tariff adoption velocity or F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market