
 Industrial Internet of Things (Iiot) Market | 2026-2036
Industrial Internet of Things (Iiot) Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Internet of Things (Iiot) Market Intelligence
Multi-source procurement of industrial sensors and edge hardware is consolidating around a smaller set of platform providers with proven interoperability. Siemens AG leverages its digital twin portfolio to anchor large manufacturing accounts in Europe. Honeywell International Inc. competes through vertical integration into process control software and safety systems. Cisco Systems Inc. specializes in secure networking infrastructure that bridges operational technology with enterprise IT environments.
The Industrial Internet of Things denotes networked sensor arrays, edge gateways, and cloud analytics platforms that collect, process, and act upon operational data in industrial settings. Systems typically operate on sub-10 millisecond latency thresholds for safety-critical loops while transmitting aggregated telemetry to centralized dashboards for longer-horizon optimization. Predictive maintenance within solution offerings commands the deepest margin pools as asset-intensive industries prioritize uptime over incremental efficiency gains. Smart manufacturing applications attract the fastest deployment velocity as factories retrofit legacy equipment with retrofit sensor kits rather than greenfield builds.
The EU AI Act and NIST Cybersecurity Framework shape product certification requirements for connected industrial systems sold across European and North American jurisdictions. China's MIIT issues GB standards that mandate data localization for critical infrastructure operators, fragmenting cloud architecture strategies for multinational vendors. Stakeholders must monitor divergence between regional compliance regimes when architecting cross-border IIoT deployments.
Market Dynamics
The convergence of edge computing architectures with tightening cybersecurity mandates is compressing vendor qualification timelines while elevating platform consolidation around interoperability-certified providers.
Growth Catalysts
- EU AI Act certification requirements:Industrial operators in Germany and France accelerate platform migrations to preempt compliance deadlines for high-risk AI systems in manufacturing environments.
- Predictive maintenance software stacks:Automotive OEMs and heavy machinery fleets deploy sensor-to-cloud pipelines that convert vibration and thermal telemetry into failure probability scores.
- China's MIIT data localization mandates:Multinational industrial cloud providers establish sovereign infrastructure zones to serve state-owned energy and transportation operators.
Market Restraints
- Semiconductor supply concentration:Edge gateway manufacturers face allocation constraints for industrial-grade SoCs fabricated at Taiwan and South Korea foundries.
- NIST Cybersecurity Framework implementation costs:Mid-sized process manufacturers defer full OT-IT segmentation projects due to engineering service scarcity and hardware refresh cycles.
- Legacy protocol fragmentation:Brownfield facilities operate incompatible fieldbus standards that require costly protocol translation layers for unified data ingestion.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Industrial sensor and edge hardware vendors establish local assembly operations to serve domestic steel and cement digitalization programs.
- Digital twin convergence with physics simulation:Aerospace and power generation operators integrate real-time sensor streams with computational fluid dynamics models for asset optimization.
- Outcome-based maintenance contracts:Equipment OEMs in the United States pilot uptime-guarantee pricing models that shift revenue from hardware sales to performance-based subscriptions.
Industry Challenges
- OT cybersecurity skill scarcity:Industrial operators compete for personnel certified in ISA/IEC 62443 standards who can architect zone-based network segmentation.
- Multi-year certification timelines:Safety-critical IIoT devices for process industries face extended validation cycles under ATEX and IECEx hazardous area directives.
- Interoperability testing burden:Platform vendors maintain certification labs to validate gateway compatibility across proprietary SCADA and MES environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Internet of Things (Iiot) Market |
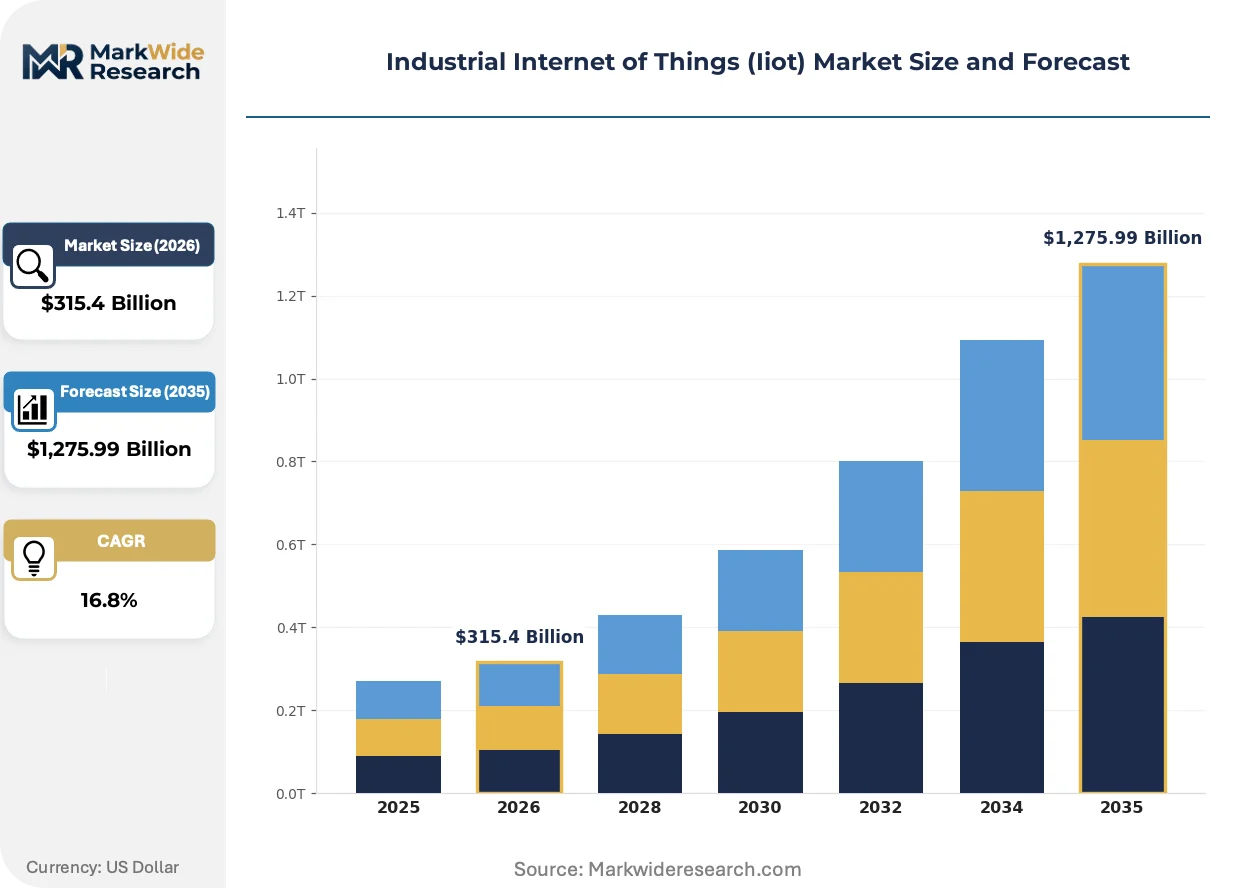
| Market Size in 2026 | $315.4 Billion |
| Market Size in 2035 | $1,275.99 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, Edge Computing, Hybrid, On-Premises Solution Offering: Asset Tracking, Predictive Maintenance, Energy Management, Supply Chain Optimization, Quality Control Application: Smart Manufacturing, Remote Monitoring, Industrial Automation, Condition Monitoring, Safety Management End User Industry: Oil & Gas, Power Generation, Mining, Chemicals, Aerospace |
| Companies Covered | Siemens AG, General Electric, Cisco Systems Inc., IBM Corporation, Intel Corporation, ABB Ltd., Honeywell International Inc., Rockwell Automation Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Internet of Things (Iiot) Market Strategic Shifts & Innovations
Real-time inference at the network edge is displacing cloud-dependent analytics architectures while regulatory fragmentation forces modular compliance engineering.
Time-sensitive networking (TSN) standards over Ethernet is automating deterministic control loop execution for robotics and motion systems. Automotive battery assembly lines in Germany and South Korea deploy TSN-enabled switches to synchronize welding robots within microsecond tolerances. This deterministic connectivity layer is automating the migration from proprietary fieldbus networks toward unified IP-based plant infrastructures.
The EU AI Act's risk classification framework imposes conformity assessment obligations on industrial AI systems deployed in safety-critical environments. Manufacturers of predictive maintenance algorithms must now document training data provenance and model robustness for notified body review. European process industries are responding by segmenting AI deployments into high-risk and limited-risk tiers with differential validation requirements.
Buyers in asset-intensive sectors now demand proof-of-concept deployments before enterprise-scale commitments. Procurement teams at German chemical conglomerates and Japanese steelmakers structure phased pilot contracts with explicit scalability gates and interoperability checkpoints. This validation-first pattern is most pronounced in North American oil and gas operations where capital committees require demonstrated ROI from edge analytics before authorizing refinery-wide rollouts.
Industrial Internet of Things (Iiot) Market Segmentation
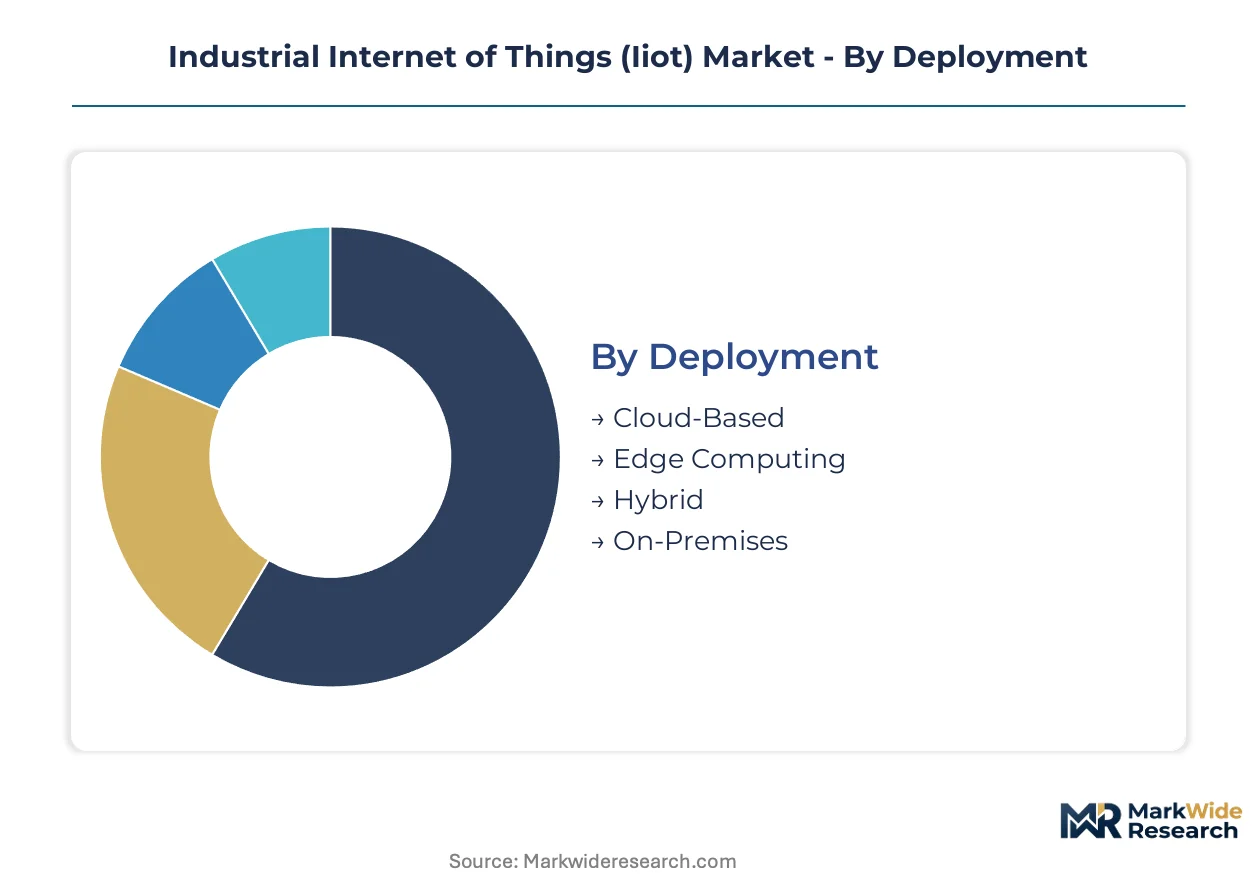
IIoT market segmentation reveals divergent technology maturity across deployment architectures and solution types. Procurement patterns in automotive and heavy machinery sectors favor predictive maintenance bundles over standalone sensor hardware. Application-level segmentation tracks the shift from legacy SCADA retrofit toward greenfield digital twin deployments.
Deployment:
Volume concentration clusters in cloud-based architectures while premium pricing attaches to edge-native deployments with deterministic latency guarantees.
- Cloud-Based:Centralized data lakes aggregate telemetry from distributed sensor fleets for long-horizon optimization analytics. Demand concentrates among mid-sized process manufacturers in Germany and the United States seeking to defer capital expenditure on on-site infrastructure. NIST Cybersecurity Framework compliance costs compress margins for providers serving this tier.
- Edge Computing:Sub-10 millisecond inference executes directly on gateway hardware for safety-critical control loops. Automotive OEMs in South Korea and power generation operators in China deploy these architectures to preempt cloud latency vulnerabilities. EU AI Act certification requirements elevate vendor qualification barriers for European deployments.
- Hybrid:Workload orchestration splits deterministic control to edge nodes while streaming aggregated telemetry to cloud analytics layers.
- On-Premises:Fully air-gapped deployments serve critical infrastructure operators under China's MIIT data localization mandates.
Mature deployment sits with Cloud-Based architectures. Newer deployment is concentrated in Edge Computing configurations.
Solution Offering:
Margin pools deepen with outcome-based contracting models while hardware-centric offerings face procurement consolidation.
- Predictive Maintenance:Vibration and thermal telemetry feeds machine learning models that generate failure probability scores for asset replacement scheduling. Heavy machinery fleets and oil & gas operators command the deepest contract values as uptime guarantees displace traditional service agreements. Semiconductor supply concentration for industrial-grade SoCs constrains gateway availability for these pipelines.
- Asset Tracking:Real-time location systems monitor mobile equipment and work-in-progress inventory across distributed facilities.
- Energy Management:Sub-metering analytics identify load optimization opportunities in power-intensive process industries.
- Supply Chain Optimization:End-to-end visibility platforms integrate supplier telemetry with manufacturing execution systems.
- Quality Control:Machine vision and acoustic inspection automate defect detection at production line speeds.
Revenue expansion runs fastest through Predictive Maintenance subscriptions. Asset Tracking commands the widest addressable base across facility types.
Application:
Smart manufacturing retrofit projects outpace greenfield automation in current capital deployment cycles.
- Smart Manufacturing:Retrofit sensor kits digitize legacy equipment without production line replacement, enabling brownfield facilities to capture efficiency gains. German chemical conglomerates and Japanese steelmakers structure phased pilot contracts with explicit scalability gates before enterprise commitments. Legacy protocol fragmentation between fieldbus standards elevates integration costs for unified data ingestion.
- Remote Monitoring:Distributed asset oversight reduces site visit frequency for geographically dispersed infrastructure.
- Industrial Automation:Closed-loop control systems replace manual intervention in repetitive process operations.
- Condition Monitoring:Continuous health assessment extends maintenance intervals while preventing catastrophic failures.
- Safety Management:Personnel tracking and hazardous area monitoring satisfy ATEX and IECEx certification requirements.
Procurement velocity peaks in Smart Manufacturing retrofit programs. Safety Management carries the longest validation timelines under hazardous area directives.
End User Industry:
Capital intensity and regulatory exposure determine platform sophistication requirements across vertical markets.
- Oil & Gas:Refinery-wide sensor deployments monitor corrosion, vibration, and process deviation across upstream and downstream operations. North American capital committees require demonstrated ROI from edge analytics before authorizing full-facility rollouts. FERC pipeline safety regulations mandate continuous pressure and flow monitoring with encrypted telemetry transmission.
- Power Generation:Turbine and generator health monitoring integrates with grid dispatch systems for optimized asset dispatch.
- Mining:Autonomous haulage and remote equipment operation reduce personnel exposure in hazardous extraction environments.
- Chemicals:Batch process optimization and emissions monitoring satisfy EPA and ECHA reporting obligations.
- Aerospace:Digital twin convergence with computational fluid dynamics models enables real-time engine performance optimization.
Platform consolidation concentrates among Oil & Gas operators with multi-site standardization mandates. Aerospace presents the steepest expansion trajectory through physics-simulation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial digitalization programs concentrate capital deployment across Germany, the United States, and China, with regulatory divergence fragmenting cloud architecture strategies for multinational vendors.
United States
Automotive OEMs and oil & gas operators drive predictive maintenance adoption through sensor-to-cloud pipelines. The NIST Cybersecurity Framework imposes OT-IT segmentation requirements that elevate implementation costs for mid-sized process manufacturers. Houston's energy corridor hosts refinery-wide pilot programs requiring demonstrated ROI before full-facility authorizations.
Germany
Chemical conglomerates and automotive battery assembly lines deploy Time-Sensitive Networking switches for microsecond-tolerance robotics synchronization. The EU AI Act accelerates platform migrations as manufacturers preempt conformity assessment deadlines for high-risk manufacturing systems. Stuttgart's automotive cluster structures phased pilot contracts with explicit scalability gates before enterprise commitments.
China
State-owned energy and transportation operators mandate sovereign infrastructure zones under MIIT data localization requirements. GB standards fragment cloud strategies for multinational industrial cloud providers serving critical infrastructure. Yangtze River Delta manufacturing hubs retrofit legacy equipment with sensor kits rather than greenfield builds.
South Korea
Automotive battery assembly lines deploy edge-native architectures with sub-10 millisecond inference for safety-critical control loops. METI-aligned industrial standards facilitate cross-border interoperability certification with Japanese process control vendors. Seoul Capital Area semiconductor foundries face allocation constraints for industrial-grade SoCs destined for edge gateway manufacturers.
India
Steel and cement digitalization programs attract industrial sensor vendors establishing local assembly under the PLI scheme for electronics manufacturing. CEA grid modernization mandates create demand for turbine health monitoring integration. Gujarat's industrial corridor hosts brownfield retrofit projects addressing legacy protocol fragmentation between incompatible fieldbus standards.
Industrial Internet of Things (Iiot) Market Key Industry Players
Platform consolidation dominates the current landscape as interoperability certification elevates vendor qualification barriers. The supplier base stratifies between diversified industrial conglomerates, specialized networking infrastructure providers, and cloud-native software platforms. Three archetypes anchor competitive positioning: digital twin portfolio holders, vertical safety system integrators, and secure OT-IT bridge specialists. M&A activity and strategic partnerships concentrate capability around proven cross-platform compatibility.
Within the diversified industrial tier, Siemens AG and General Electric exemplify conglomerate-scale platform providers. Cisco Systems Inc. occupies the secure networking infrastructure archetype bridging operational technology with enterprise IT environments. Honeywell International Inc. anchors vertical integration patterns into process control software and safety systems. These three entities represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Siemens AG |
| General Electric |
| Cisco Systems Inc. |
| IBM Corporation |
| Intel Corporation |
| ABB Ltd. |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
Industrial-grade NAND flash price indices cascade through edge gateway manufacturing into three distinct procurement tiers. Automotive OEMs in South Korea absorb premium pricing for deterministic-latency-certified hardware, while mid-sized German process manufacturers defer capital expenditure through cloud-based subscription models.
Pricing Analysis
Volume concentration in cloud-based deployments compresses per-unit margins, while edge-native configurations with sub-10 millisecond guarantees capture premium pricing. Three-tier pricing structure across premium, standard, and economy levels separates ISA/IEC 62443-certified safety systems from uncertified commercial hardware. Pricing pressure stems from semiconductor supply concentration at Taiwan and South Korea foundries constraining industrial-grade SoC allocation. Mid-sized process manufacturers exhibit highest price sensitivity, deferring full OT-IT segmentation projects due to engineering service scarcity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for industrial sensor and gateway hardware. Manufacturing concentration clusters in Taiwan, South Korea, and China for industrial-grade SoCs, with Germany and the United States contributing specialized safety-certified components. Raw material dependencies center on silicon wafers, rare earth magnets for sensor actuators, and copper for connectivity infrastructure. Single-source vulnerability at Taiwan foundries poses structural risk for edge gateway availability. Distribution runs through authorized industrial automation distributors with certified integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Internet of Things market sits in a protocol-transition phase as Time-Sensitive Networking over Ethernet displaces proprietary fieldbus architectures. This technology replacement cycle compresses vendor qualification timelines while elevating interoperability-certified providers.
For Market Incumbents: Lock in platform consolidation advantages by acquiring specialized edge analytics firms with proven SCADA integration capabilities. Threat of cloud-native software platforms entering safety-critical control loops demands defensive certification investment in EU AI Act conformity assessment. Backward integration into industrial-grade SoC supply through long-term foundry offtake agreements secures allocation priority. For New Entrants and Emerging Players: AI-first predictive maintenance algorithms offer entry wedge into brownfield manufacturing facilities with legacy equipment retrofit demand. White-space concentrates in India's steel and cement digitalization programs under PLI scheme incentives, plus mid-sized US process manufacturers deferred on NIST Cybersecurity Framework compliance. Go-to-market through outcome-based uptime-guarantee contracts shifts buyer risk perception. For Investors and Strategic Acquirers: Distressed-cycle entries favor edge-native hardware specialists with sovereign infrastructure deployment capabilities in China. Long-term viability across the analysis window hinges on regulatory compliance engineering rather than pure technology differentiation. Acquisition target archetype: platform vendors with certification lab infrastructure validating gateway compatibility across proprietary MES environments. Signal to watch: divergence between EU AI Act and China's MIIT GB standards forcing modular compliance architecture investment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies edge analytics with Siemens digital twin portfolios for automotive OEM accounts. |
| Strategic Partnership | Links Cisco secure networking with Honeywell process control software for refinery deployments. |
| Acquisition of Specialist Firm | Adds predictive maintenance algorithm capabilities to diversified industrial conglomerates. |
| Geographic Expansion | Establishes sovereign infrastructure zones under China's MIIT data localization mandates. |
| Product Launch | Introduces TSN-enabled switches for microsecond-tolerance robotics synchronization in Germany. |
Research Approach
SEC filings, EIA industrial power consumption data, and EU regulatory notification databases formed the secondary backbone for this analysis. Primary interviews with plant engineers, maintenance directors at automotive OEMs, OEM procurement teams, and aftermarket service heads validated demand assumptions. Bottom-up sensor deployment counts triangulated against top-down industrial digitalization program budgets across Germany, the United States, and China.
Historical trendline analysis of edge computing adoption rates and predictive maintenance software penetration informed projection mechanics. Segmentation modeling spanned deployment architecture, solution offering, application type, and end-user industry vertical. CAGRs derived from regression analysis against industrial capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs incorporated semiconductor supply allocation constraints and OT cybersecurity skill scarcity metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended EU AI Act certification timelines or Taiwan foundry disruption scenarios. Outputs reflect documented assumptions around regulatory implementation schedules and industrial capital commitment patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Global IoT in Warehouse Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market