
 IoT in Warehouse Management Market | 2026-2036
IoT in Warehouse Management Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Warehouse Management Market Analytics
Platform licensing revenue is tilting away from perpetual software sales toward recurring cloud subscriptions in warehouse IoT. Zebra Technologies Corp. dominates rugged mobile computing and real-time location hardware for distribution centers. Cisco Systems Inc. extends its networking infrastructure into edge-computing nodes that process sensor data locally. PTC Inc. specializes in digital thread platforms that connect warehouse execution systems to broader supply chain visibility layers.
IoT in warehouse management refers to networked sensor arrays, RFID tags, wireless gateways, and cloud analytics platforms that capture, transmit, and process operational data across storage and fulfillment facilities. These systems typically operate at sub-second latency for automated guided vehicle coordination and maintain 99.9% inventory location accuracy through ultra-wideband positioning. Cloud-based deployment now captures the fastest expansion as operators trade capital intensity for elastic compute scaling during seasonal demand spikes. RFID technology leads installed base volume but sensors for environmental monitoring and predictive maintenance command premium pricing per node. E-commerce end users represent the most aggressive adoption cohort, driven by same-day delivery promises that require real-time inventory visibility.
The EU AI Act imposes risk-classification requirements on automated decision systems in warehouse robotics, compelling vendors to document algorithmic logic for high-throughput sorting applications. The FCC governs spectrum allocation for ultra-wideband and private 5G networks that underpin warehouse wireless communication in the United States. ISO standards for supply chain security and data interoperability shape procurement criteria for multinational operators seeking unified visibility across regional distribution networks. Stakeholders must weigh regulatory compliance costs against latency advantages when selecting edge-versus-cloud architectures for autonomous material handling.
Market Dynamics
Cloud-native warehouse management platforms are collapsing capital barriers for mid-tier operators, compressing deployment timelines from eighteen months to under ninety days while shifting cost structures from capex-heavy perpetual licenses to elastic operational expenditure models.
Growth Catalysts
- EU AI Act compliance mandates:Automated sorting and robotic fulfillment systems in Germany, France, and the Netherlands face algorithmic documentation requirements that drive replacement cycles for legacy equipment lacking audit trails.
- Automotive manufacturing clusters:German industrial zones around Stuttgart and Wolfsburg deploy ultra-wideband positioning networks to synchronize just-in-sequence parts delivery with assembly line takt times.
- Private 5G spectrum allocation:FCC mid-band auctions enable US distribution centers to bypass Wi-Fi congestion for autonomous vehicle coordination and real-time inventory tracking.
Market Restraints
- Silicon supply concentration:RF chip and edge processor fabrication concentrates in Taiwan and South Korea, exposing warehouse IoT hardware vendors to geopolitical disruption risks.
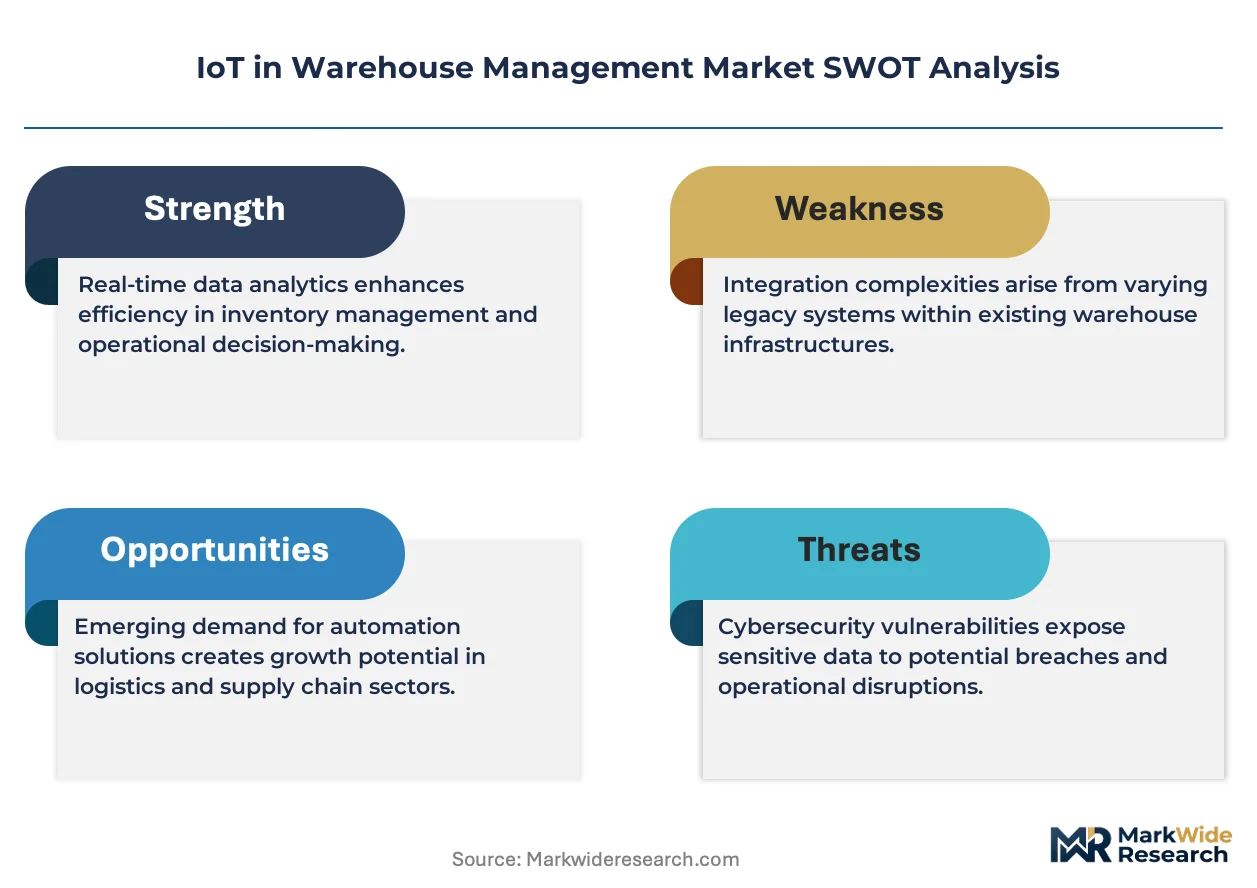
- Interoperability friction:Proprietary data protocols from incumbent warehouse execution system vendors lock operators into single-source architectures that resist modular sensor integration.
- Cyber insurance cost escalation:Ransomware attacks against logistics networks drive premium increases of forty to sixty percent for facilities lacking segmented network architectures.
Strategic Opportunities
- Cold chain expansion in India:FSSAI temperature-monitoring mandates for pharmaceutical distribution create demand for wireless environmental sensors in Mumbai and Hyderabad warehousing corridors.
- Digital thread convergence:Integration of warehouse execution data with product lifecycle management platforms enables automotive suppliers to trace component genealogy from inbound receipt through finished goods dispatch.
- Edge AI inference:On-premise neural network processing for quality inspection and damage detection reduces cloud egress costs while maintaining sub-hundred-millisecond response times for high-velocity sortation.
Industry Challenges
- RF engineering talent scarcity:Ultra-wideband network design and antenna optimization skills concentrate among semiconductor vendors, forcing warehouse operators to outsource deployment architecture.
- Legacy WMS integration complexity:Proprietary middleware from 1990s-era warehouse management systems requires custom API development to ingest IoT sensor streams, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Warehouse Management Market |
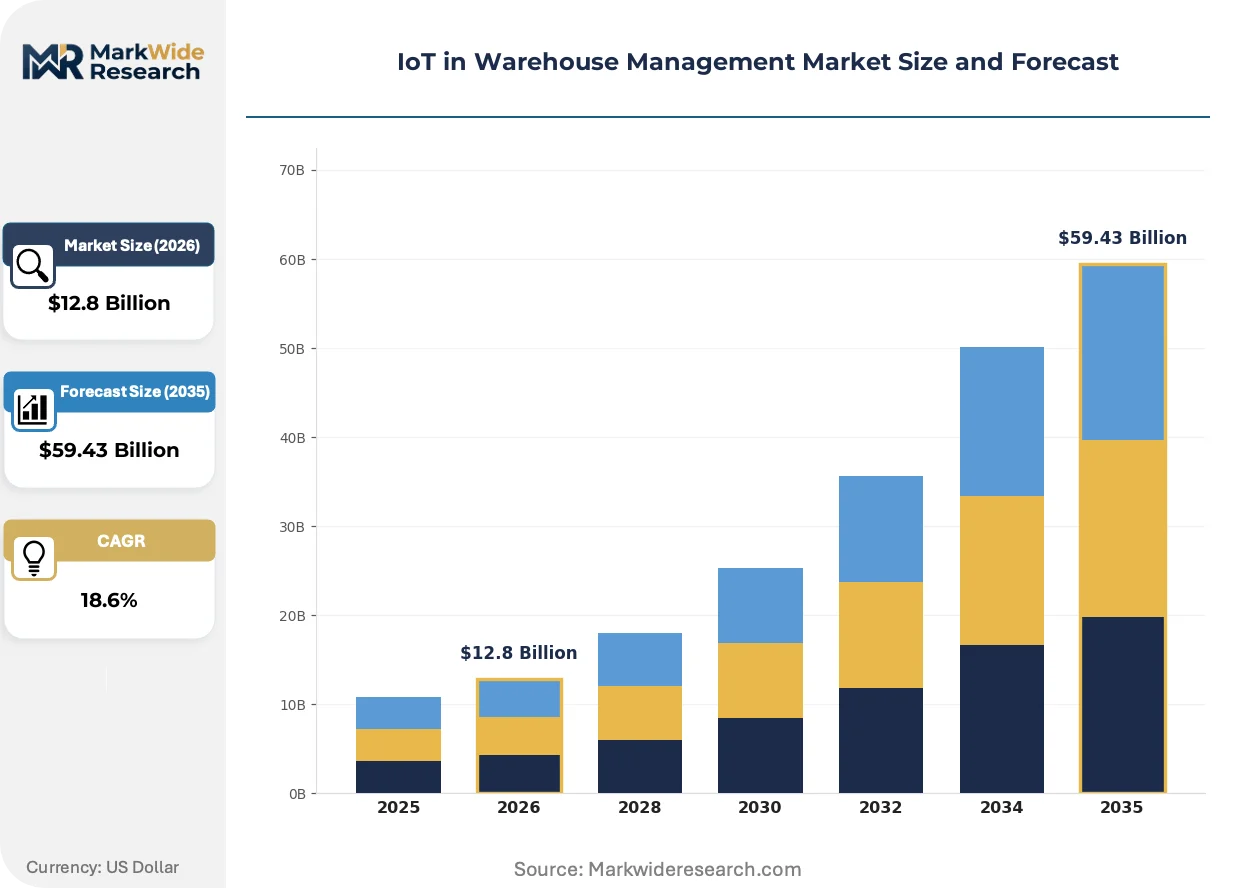
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.43 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Sensors, Wireless Communication, Cloud Computing Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Retailers, Third-Party Logistics, Manufacturers, E-commerce Application: Inventory Management, Transportation Management, Order Fulfillment, Asset Tracking |
| Companies Covered | IBM Corporation, Oracle Corporation, HCL Technologies Limited, PTC Inc., Software AG, Zebra Technologies Corp., Tecsys Inc., Cisco Systems Inc., Infor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Warehouse Management Market Evolving Landscape
Computational workloads are migrating toward the network edge, compressing latency for time-critical warehouse automation while fragmenting the traditional cloud-centric architecture into distributed processing topologies.
Ultra-wideband positioning infrastructure is collapsing the cost-performance tradeoff that previously forced operators to choose between RFID-based zone accuracy and expensive vision systems. E-commerce fulfillment centers in Germany and the United States are deploying sub-meter location networks at one-third the per-node cost of camera arrays. This compression enables real-time slotting optimization that was previously economically viable only for aerospace and pharmaceutical verticals.
The EU AI Act's risk-classification framework for automated decision systems imposes documentation burdens on high-throughput sorting robotics deployed across Benelux distribution hubs. Vendors must now maintain algorithmic audit trails and human-in-the-loop override protocols for parcel routing decisions. German automotive logistics providers are responding by segregating AI-enabled handling equipment into isolated network segments with dedicated compliance monitoring.
Third-party logistics procurement patterns are fragmenting from multi-year enterprise contracts toward modular service subscriptions indexed to throughput volume. Amazon-scale e-commerce operators in the United States now unbundle warehouse automation from facility leases, selecting best-of-breed IoT stacks through competitive pilot programs. This behavioral shift pressures incumbent platform vendors to expose granular API access and consumption-based pricing.
IoT in Warehouse Management Market Segmentation
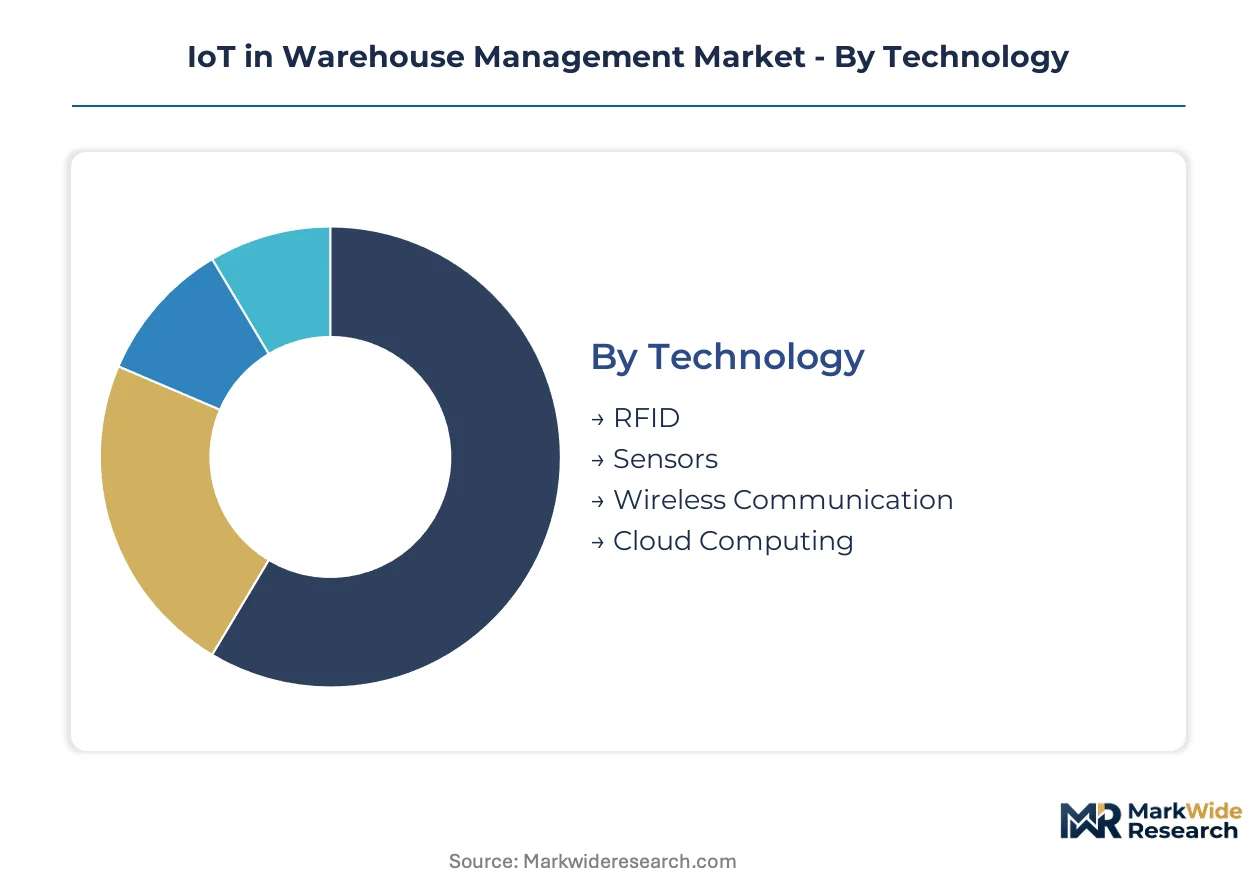
Warehouse IoT deployments fragment across technology maturity, infrastructure topology, and operational use case, with each axis demanding distinct integration architectures and recurring service commitments. Understanding these splits reveals where hardware margins compress against software annuity value and which verticals absorb premium sensor pricing.
Technology:
After-sales-service intensity varies sharply across technology categories, with sensor networks requiring continuous calibration contracts and RFID systems demanding tag replenishment programs that lock in multi-year vendor relationships.
- RFID:Passive and active radio-frequency identification tags enable automated inventory counts without line-of-sight scanning, with ultra-high-frequency systems achieving read rates exceeding 1,000 items per second in dense pallet configurations. German automotive suppliers around Stuttgart deploy RFID-tagged component bins to synchronize just-in-sequence delivery with assembly line takt times, though tag collision in metal-dense environments necessitates ongoing antenna tuning services.
- Sensors:Environmental and condition-monitoring devices track temperature, humidity, vibration, and shock events through battery-powered nodes with 3-5 year lifecycles. Cold chain operators in India face FSSAI-mandated temperature logging for pharmaceutical distribution, driving demand for wireless sensor deployments in Mumbai and Hyderabad warehousing corridors where calibration drift requires quarterly maintenance visits.
- Wireless Communication:Ultra-wideband, private 5G, and Wi-Fi 6E infrastructure provide sub-meter positioning and deterministic latency for autonomous vehicle coordination. FCC mid-band spectrum auctions enable US distribution centers to bypass congested unlicensed bands for mission-critical robotics traffic.
- Cloud Computing:Elastic compute and storage resources process telemetry streams from distributed sensor arrays, with multi-tenant architectures reducing per-warehouse infrastructure costs for mid-tier 3PL operators.
By volume, RFID leads. By growth pace, sensors for predictive maintenance and environmental compliance are expanding most quickly.
Deployment:
Capital structure preferences reshape deployment choices, with cloud-native architectures trading upfront infrastructure investment for operational expenditure flexibility that aligns costs with seasonal throughput volatility.
- Cloud-Based:Fully managed SaaS platforms deliver warehouse management functionality through browser-based interfaces, eliminating local server maintenance and enabling elastic scaling during peak demand periods. E-commerce fulfillment centers in the United States compress deployment timelines from eighteen months to under ninety days by adopting cloud-native stacks, though recurring subscription costs accumulate over five-year total cost of ownership horizons.
- Edge Computing:On-premise neural network processing for quality inspection and damage detection reduces cloud egress fees while maintaining sub-hundred-millisecond response times for high-velocity sortation. German automotive logistics providers deploy edge nodes to satisfy EU AI Act algorithmic audit requirements without transmitting sensitive production data beyond facility perimeters.
- On-Premise:Self-hosted software and hardware infrastructure retains full data sovereignty and customization control, appealing to defense contractors and pharmaceutical manufacturers with stringent compliance mandates.
- Hybrid:Architectures partition sensitive operations to local infrastructure while leveraging cloud analytics for non-critical reporting, balancing latency requirements against capital efficiency.
Cloud-based deployments command the steepest expansion trajectory among mid-tier operators, while edge computing gains share fastest in regulated European manufacturing clusters.
End User:
Procurement sophistication and integration complexity diverge across buyer categories, with enterprise manufacturers demanding digital thread connectivity and 3PLs prioritizing rapid reconfigurability across multi-tenant facilities.
- E-commerce:Same-day delivery promises drive aggressive adoption of real-time inventory visibility and automated sortation, with Amazon-scale operators unbundling automation from facility leases through competitive pilot programs. United States-based e-commerce fulfillment centers represent the most technology-forward cohort, absorbing premium pricing for sub-meter positioning infrastructure.
- Third-Party Logistics:Multi-tenant warehousing operations serving fragmented shipper bases require rapid reconfiguration capabilities and consumption-based pricing models. 3PL procurement patterns fragment from multi-year enterprise contracts toward modular service subscriptions indexed to throughput volume.
- Manufacturers:Industrial production facilities integrate warehouse execution with product lifecycle management platforms to trace component genealogy from inbound receipt through finished goods dispatch.
- Retailers:Omnichannel distribution networks unify store fulfillment and direct-to-consumer shipping through centralized inventory visibility layers.
E-commerce leads absolute technology spend, while 3PLs exhibit the fastest procurement velocity as competitive pressure forces rapid stack modernization.
Application:
Functional priority and ROI measurement frameworks vary by application domain, with inventory management offering quantifiable accuracy gains and transportation management requiring cross-enterprise data integration.
- Inventory Management:Real-time location systems and cycle-counting automation eliminate manual stock checks and reduce shrinkage through continuous visibility. Ultra-wideband positioning networks achieve 99.9% inventory location accuracy at one-third the per-node cost of camera arrays, enabling slotting optimization previously viable only for aerospace and pharmaceutical verticals.
- Asset Tracking:Returnable container and equipment monitoring reduces capital tied up in misplaced pallets and rental fleet underutilization. German industrial zones deploy tagged reusable packaging to synchronize just-in-sequence parts delivery with automotive assembly schedules.
- Order Fulfillment:Pick-path optimization and automated sortation accelerate throughput in high-velocity distribution environments.
- Transportation Management:Yard management and carrier coordination systems bridge warehouse execution with inbound and outbound logistics scheduling.
Inventory management captures the largest installed base, while asset tracking demonstrates the steepest growth curve as circular packaging mandates expand across European supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive logistics clusters deploy ultra-wideband positioning for just-in-sequence delivery synchronization, while Indian pharmaceutical corridors absorb wireless environmental sensors under cold-chain mandates, and US e-commerce operators bypass Wi-Fi congestion through private 5G spectrum auctions.
Germany
Automotive manufacturing clusters around Stuttgart and Wolfsburg drive ultra-wideband network deployments for assembly line takt-time synchronization. The EU AI Act imposes algorithmic documentation requirements on high-throughput sorting robotics across Benelux distribution hubs. Industrial zones in Baden-Württemberg segregate AI-enabled handling equipment into isolated network segments with dedicated compliance monitoring.
United States
Amazon-scale e-commerce fulfillment centers represent the most technology-forward adoption cohort for real-time inventory visibility infrastructure. FCC mid-band spectrum auctions enable distribution centers to bypass congested unlicensed bands for autonomous vehicle coordination. Southeast logistics corridors compress cloud-native deployment timelines from eighteen months to under ninety days.
India
FSSAI temperature-monitoring mandates for pharmaceutical distribution create demand for wireless environmental sensors in Mumbai and Hyderabad warehousing corridors. The PLI scheme for electronics manufacturing incentivizes domestic sensor assembly capacity expansion. Cold chain operators face quarterly calibration maintenance requirements due to sensor drift in tropical humidity conditions.
China
Dual carbon goals accelerate warehouse energy management IoT deployments for consumption optimization in Yangtze River Delta logistics hubs. MIIT spectrum allocation frameworks govern private 5G network licensing for autonomous material handling. Shenzhen-based equipment vendors integrate edge computing nodes for quality inspection neural network processing.
Netherlands
Rotterdam port logistics complexes deploy RFID-tagged container tracking for intermodal transfer coordination. REACH chemical handling regulations mandate environmental sensor networks for hazardous materials warehousing. Randstad distribution clusters absorb premium pricing for 99.9% inventory location accuracy through sub-meter positioning infrastructure.
IoT in Warehouse Management Market Competitive Landscape
Capability concentration sits with semiconductor networking specialists; scale advantage sits with enterprise software platforms and rugged hardware manufacturers. The vendor base organizes into three tiers: networking infrastructure providers, digital thread platform specialists, and mobile computing hardware fabricators. Consolidation pressure intensifies as cloud-native deployment collapses capital barriers for mid-tier operators. Dominant competitive moves include API ecosystem expansion and consumption-based pricing model adoption.
Within the networking infrastructure tier, Cisco Systems Inc. anchors edge-computing node deployment for localized sensor data processing. Zebra Technologies Corp. exemplifies the rugged mobile computing archetype through real-time location hardware specialization. PTC Inc. occupies the digital thread convergence position, connecting warehouse execution systems to broader supply chain visibility layers.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| HCL Technologies Limited |
| PTC Inc. |
| Software AG |
| Zebra Technologies Corp. |
| Tecsys Inc. |
| Cisco Systems Inc. |
| Infor Inc. |
| Others |
Value Network & Pricing Analysis
Taiwanese semiconductor foundries in Hsinchu Science Park anchor global supply for RF chips and edge processors, concentrating upstream capacity that feeds downstream pricing power into warehouse IoT hardware tiers. Their fabrication dominance shapes how sensor vendors and rugged mobile computing manufacturers structure contract terms across procurement cycles.
Pricing Analysis
Long-term offtake agreements dominate procurement for ultra-wideband infrastructure and private 5G hardware, while spot purchasing governs RFID tag replenishment and consumable sensors. Price differentiation centers on certification grade—ISO 27001-compliant edge nodes command substantial premiums over uncertified alternatives—and volume scale, with enterprise 3PLs extracting steep discounts through multi-warehouse commitments. Pricing pressure stems from cloud-native platform commoditization compressing software margins. Mid-tier operators exhibit highest price sensitivity, whereas automotive manufacturers absorb premium positioning infrastructure for takt-time synchronization.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor fabrication equipment to China concentrate RF chip and edge processor supply in Taiwan and South Korea, with secondary sourcing from Japan. Raw material dependencies include silicon wafers, gallium arsenide substrates, and rare-earth magnet components for antenna assemblies. Supply chain risk centers on single-source vulnerability for sub-7nm processor nodes. Distribution runs through tier-one electronics distributors serving OEM integration channels, with direct procurement relationships emerging for hyperscale e-commerce operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment—EU AI Act compliance documentation creates switching costs that lock warehouse operators into validated vendor ecosystems. Algorithmic audit trail requirements raise barriers for unproven entrants.
For Market Incumbents: Insulate platform positions by deepening API ecosystem breadth to capture 3PL procurement fragmentation toward modular subscriptions. Acquire edge-AI inference specialists to satisfy EU AI Act data sovereignty requirements without cloud egress. Cement relationships with German automotive logistics clusters where just-in-sequence synchronization mandates create captive demand for ultra-wideband infrastructure. For New Entrants and Emerging Players: Cold chain pharmaceutical corridors in India represent the most penetrable entry point, where FSSAI temperature-monitoring mandates drive sensor deployment without incumbent platform saturation. Target mid-tier US distribution centers bypassing Wi-Fi congestion through FCC private 5G spectrum allocations. Lead with consumption-based pricing models that unbundle automation from facility leases, mirroring Amazon-scale procurement patterns. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU AI Act documentation burdens and FCC spectrum licensing create durable competitive barriers. Target acquisition archetypes: edge-computing hardware vendors with embedded algorithmic audit capabilities. Watch for inflection when private 5G network deployment velocity in US Southeast logistics corridors accelerates beyond pilot-phase thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem expansion captures 3PL procurement shift toward modular service subscriptions indexed to throughput. |
| Acquisition of Specialist Firm | Edge-AI inference vendors satisfy EU AI Act algorithmic audit requirements without transmitting sensitive production data. |
| Geographic Expansion | Indian pharmaceutical corridors under FSSAI mandates absorb wireless environmental sensors with quarterly calibration services. |
| Strategic Partnership | Private 5G spectrum holders partner with autonomous vehicle coordinators to bypass Wi-Fi congestion in US distribution centers. |
| Product Launch | Sub-meter ultra-wideband positioning networks collapse cost-performance tradeoffs previously forcing RFID-versus-vision choices. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse operations directors, 3PL procurement executives, IoT platform engineers, and edge-computing infrastructure architects and refined through secondary validation against FCC spectrum allocation records, EU AI Act regulatory filings, ISO supply chain security standards, and customs data for RF chip imports. Bottom-up sensor deployment estimates triangulated against top-down cloud-native platform revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling technology segments, deployment topologies, end-user verticals, and application domains alongside regional regulatory cluster intensity. CAGRs derived from elasticity-adjusted adoption curves incorporating private 5G spectrum auction timing and EU AI Act enforcement phase-ins. Industry-specific inputs included ultra-wideband network deployment density in German automotive zones and FSSAI compliance penetration in Indian pharmaceutical warehousing.
Stress conditions across semiconductor supply disruption, EU AI Act enforcement stringency, and private 5G adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cloud-native deployment compression timelines and edge-computing latency requirements. Material shifts in Taiwan semiconductor fabrication capacity or FCC mid-band spectrum allocation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market