
 Unified Network Management Market | 2026-2036
Unified Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
Unified Network Management Market Intelligence
Demand from Managed Service Providers is collapsing the traditional, capex-heavy procurement model previously dominated by large telecom operators. Cisco Systems, Inc. leverages its incumbency and broad product portfolio to secure enterprise accounts. Juniper Networks, Inc. competes on its AI-driven automation and software-defined networking strengths. Broadcom Inc. specializes in the underlying silicon and hardware components that power high-performance networks.
Unified network management provides a centralized software platform for overseeing disparate network elements like routers, switches, and firewalls, processing real-time telemetry data. Its purpose is to simplify complexity and reduce operational overhead in hybrid IT environments. Cloud-based deployment is becoming the standard over on-premise tools due to scalability. Within solutions, security management is integrating tightly with performance management to address modern cyber threats.
The EU's GDPR framework shapes how network data is processed and stored, influencing security management features. In the United States, the FCC sets standards for network service quality that operators must monitor and report. Global standards like ISO/IEC 27001 guide security best practices for platform vendors. Future vendor selection will depend on the ability to deliver integrated security and compliance reporting across multi-cloud and edge computing infrastructures.
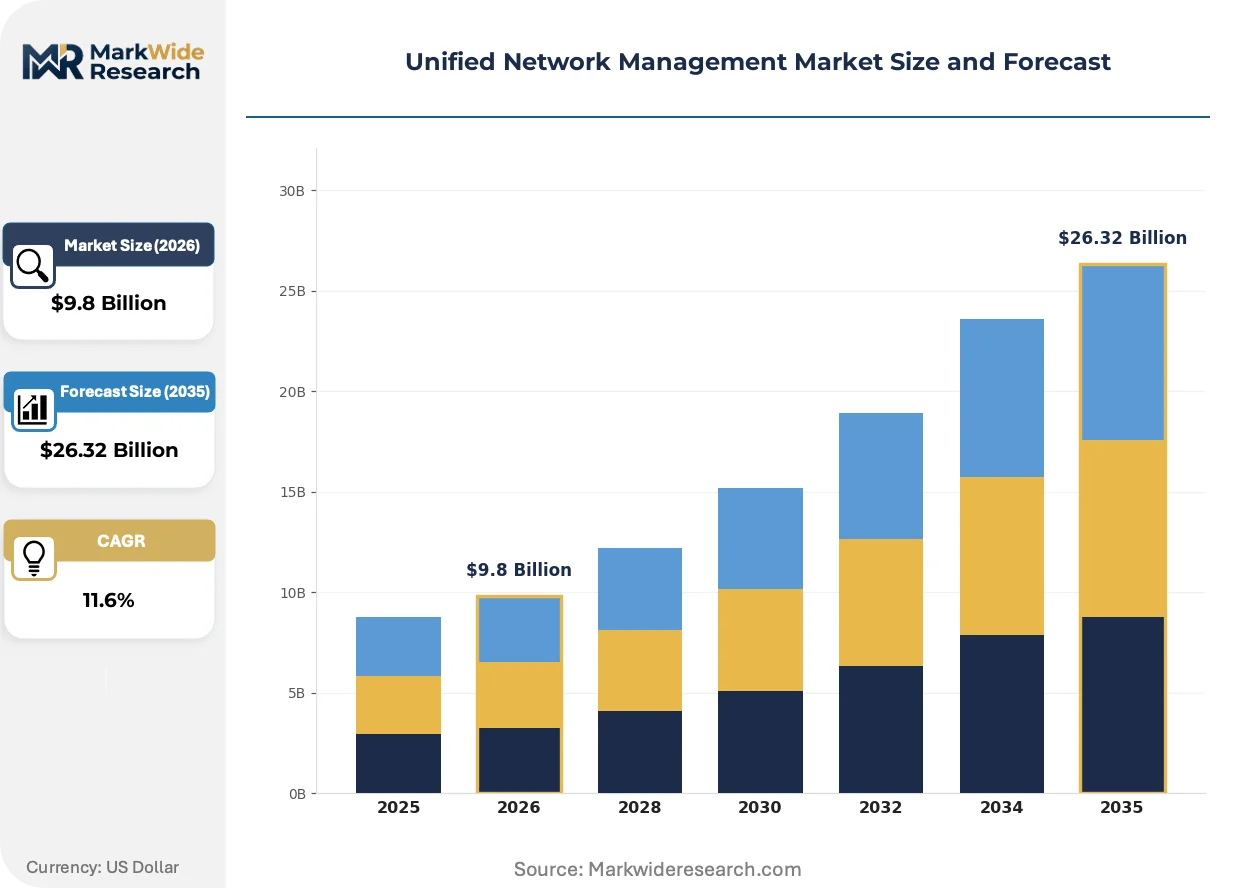
Market Dynamics
The shift from capital-intensive procurement by telecom operators to flexible, software-driven models by Managed Service Providers is the central force redefining the market. This transition is accelerated by cloud-based deployments.
Growth Catalysts
- AI Integration:
AI-powered predictive analytics reduce network downtime in data centers by identifying potential faults before they impact service.
- MSP Demand:
Managed Service Providers use unified platforms to consolidate client infrastructure management, reducing overhead and enabling scalable services.
- Cloud Infrastructure Growth:
High concentrations of data centers and cloud services in the United States create dense demand for centralized network oversight.
Market Restraints
- Legacy System Integration:
Integrating modern platforms with older, proprietary hardware from diverse vendors remains a significant technical hurdle in enterprise networks.
- High Subscription Costs:
The total cost of ownership for advanced, AI-enabled cloud platforms can be prohibitive for small businesses with limited budgets.
- Open-Source Alternatives:
Freely available open-source tools present a labor-intensive but cost-effective substitute for commercial unified management solutions.
Strategic Opportunities
- Edge Computing Expansion:
Extending management to the network edge offers growth in monitoring IoT devices and distributed computing assets.
- Integrated SecOps Platforms:
Converging network performance monitoring with SIEM tools creates a new product category for unified security and operations.
- Southeast Asian Markets:
Rapid cloud adoption in countries like Singapore and Indonesia presents an underpenetrated market for network management vendors.
Industry Challenges
- Specialized Skills Gap:
A shortage of professionals skilled in software-defined networking, AIOps, and traditional engineering constrains enterprise adoption.
- Data Harmonization:
Normalizing telemetry data from multi-vendor network devices into a consistent, actionable format remains a primary technical challenge.
- Regulatory Compliance:
Adhering to data residency laws like the EU's GDPR across global operations adds complexity and cost to platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unified Network Management Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $26.32 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution/Offering: Fault Management, Configuration Management, Performance Management, Security Management, Inventory Management Application: Data Center Management, WAN Optimization, Bandwidth Monitoring, Network Automation, Asset Tracking End User: Telecom Operators, Managed Service Providers, Government Agencies, Financial Institutions |
| Companies Covered | Cisco Systems, Inc., Hewlett Packard Enterprise Company, Huawei Technologies Co., Ltd., Broadcom Inc., Juniper Networks, Inc., IBM Corp., Telefonaktiebolaget LM Ericsson, Extreme Networks, NetScout Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unified Network Management Market Strategic Shifts & Innovations
Intelligent automation is fundamentally altering network operations. The market is moving away from manual, reactive troubleshooting toward predictive, self-healing networks driven by software-defined principles and machine learning, reducing human intervention.
AI for IT Operations (AIOps) provides predictive insights by analyzing real-time telemetry data with machine learning algorithms. Large enterprises and cloud service providers are rapidly adopting AIOps to enhance network resilience and automate root cause analysis. This technology is supplanting traditional, alert-based network monitoring tools that require extensive manual configuration and intervention.
The ISO/IEC 27001 standard for information security management is becoming a key purchasing criterion for enterprises. This global standard requires vendors to embed auditable security controls and compliance reporting features within their platforms. Consequently, vendors targeting regulated sectors like finance and healthcare must demonstrate adherence to secure development and data handling practices.
A distinct shift from perpetual licensing to consumption-based subscription models is reordering the market's commercial dynamics. This change allows customers, particularly Managed Service Providers, to align costs with usage and avoid large upfront capital expenditures. This trend is most visible in North American and European markets where OpEx-based IT procurement is preferred.
Unified Network Management Market Segmentation
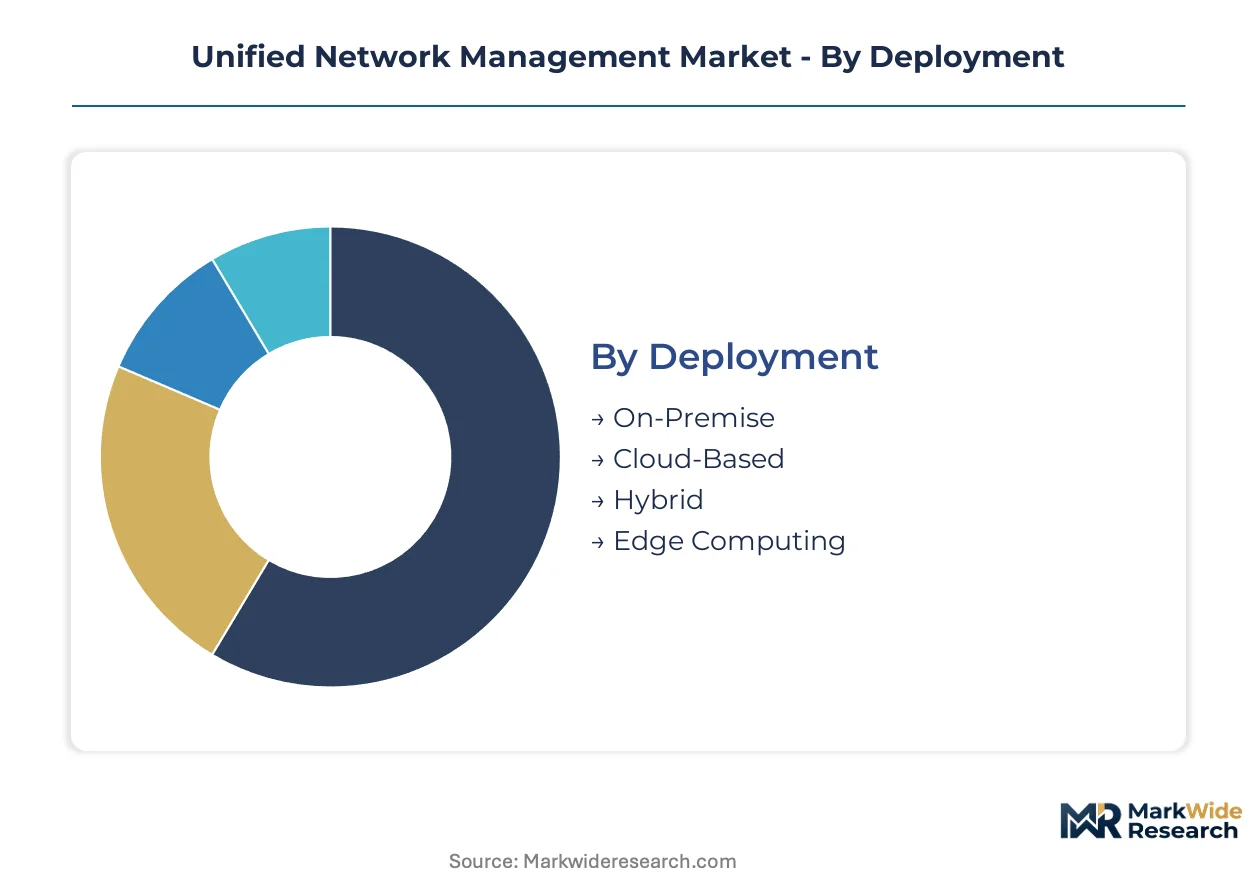
Segmentation clarifies the diverse needs driving the Unified Network Management Market, highlighting the varied procurement models and technological adoptions across different user groups. Understanding these distinctions is crucial for vendors to tailor offerings and address specific operational challenges within hybrid IT environments.
Deployment:
Deployment models for unified network management solutions directly influence the channel mix, from on-premise installations requiring direct vendor engagement to cloud-based services accessed via managed service providers or public cloud marketplaces.
- Cloud-Based:Centralized platforms delivered as a service, accessible via web browsers or APIs, reduce local infrastructure requirements. Demand concentrates in the United States, driven by extensive cloud service provider deployments and the need for scalable operations.
- Edge Computing:Distributed management of network devices and IoT sensors located at the network perimeter supports localized processing. Demand is expanding rapidly for monitoring critical infrastructure and real-time processing requirements in manufacturing.
- On-Premise:Traditional software installations managed directly within an organization's own data center provide maximum control over data residency.
- Hybrid:Combines on-premise infrastructure with cloud services to balance control, data sovereignty, and scalability for complex enterprise networks.
By volume, Cloud-Based deployments currently lead the market. By growth pace, Edge Computing deployments are expanding most quickly.
Solution/Offering:
The specific solution offerings address distinct operational pain points across diverse customer types, influencing vendor specialization and product development strategies.
- Security Management:Tools monitor network traffic for threats, enforce access policies, and manage firewalls and intrusion detection systems. Demand concentrates in financial institutions and government agencies due to stringent regulatory compliance and data protection requirements.
- Performance Management:Systems track network latency, bandwidth utilization, and device health to optimize service delivery and user experience. Demand is high among Managed Service Providers seeking to guarantee client service level agreements and proactively identify bottlenecks.
- Fault Management:Identifies, isolates, and resolves network errors and outages to maintain continuous operation and minimize downtime.
- Configuration Management:Automates the setup, provisioning, and updates of network devices across the infrastructure, ensuring consistency and compliance.
- Inventory Management:Maintains a detailed record of all network hardware, software, and their interconnections for asset tracking and lifecycle management.
Security Management solutions command premium pricing due to their critical role in protecting sensitive data. Performance Management offerings are experiencing significant demand from large enterprises.
Application:
Specific applications for unified network management reflect varying levels of operational maturity and automation requirements across different enterprise environments.
- Network Automation:Leverages software-defined networking and AI to provision, configure, and manage network resources with minimal human intervention. Demand is accelerating in cloud service providers and large enterprises aiming to reduce operational overhead and improve agility.
- Data Center Management:Centralized oversight of network infrastructure within a data center environment, including servers, storage, and interconnects. Demand is particularly strong in the United States, driven by extensive data center deployments requiring efficient resource allocation.
- WAN Optimization:Techniques and technologies designed to improve the performance of Wide Area Networks by reducing latency and increasing data transfer efficiency for distributed workforces.
- Bandwidth Monitoring:Tracks network traffic usage to identify congestion, optimize resource allocation, and ensure service quality across various applications.
- Asset Tracking:Identifies and monitors the location, status, and lifecycle of physical and virtual network assets for compliance and resource planning.
Network Automation applications are transforming operational models by integrating AIOps capabilities. Data Center Management represents a foundational requirement for cloud infrastructure providers.
End User:
End-user segments exhibit distinct procurement patterns and margin sensitivities, shaping vendor sales strategies and service level agreements.
- Managed Service Providers:Organizations that manage IT services for other businesses, leveraging unified platforms to consolidate client infrastructure. Demand from MSPs is redefining procurement models, shifting towards flexible, software-driven solutions.
- Telecom Operators:Large communication service providers that manage extensive network infrastructures for voice, data, and internet services. These operators historically dominated procurement but are now shifting from capex-heavy models.
- Government Agencies:Public sector entities requiring secure and compliant network management for critical national infrastructure and sensitive data handling.
- Financial Institutions:Banks and other financial services firms demanding robust security and performance for high-volume transaction processing and regulatory adherence.
Managed Service Providers are increasingly influencing product roadmaps with their demand for scalable, multi-tenant solutions. Telecom Operators remain significant consumers of underlying network hardware and foundational management tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive data center and cloud service provider deployments in the United States underwrite its role as a primary demand center for unified network management solutions. This market benefits from diverse regulatory landscapes and varying infrastructure maturity levels across key global regions.
United States
Demand for advanced network management solutions stems from the country's extensive cloud infrastructure and large enterprise deployments. The FCC sets standards for network service quality, requiring robust monitoring and reporting capabilities from operators. Silicon Valley and other tech hubs like Ashburn, Virginia, represent dense concentrations of data centers driving significant demand for centralized oversight.
Germany
Digital transformation initiatives across the industrial sector and robust data protection laws drive demand for secure and efficient network management. The EU's GDPR framework heavily influences data processing and storage practices within German enterprises. Major industrial centers such as Bavaria and North Rhine-Westphalia are implementing unified solutions to manage complex manufacturing networks.
Singapore
Rapid cloud adoption and smart city initiatives propel demand for scalable and integrated network management platforms. The Personal Data Protection Act (PDPA) mandates strict data handling, influencing security management features in local deployments. Singapore's role as a regional data center hub further concentrates demand for sophisticated network oversight.
Japan
Advanced IT infrastructure and a strong focus on operational efficiency create significant demand for network automation and AIOps capabilities. METI promotes digital transformation, encouraging enterprises to modernize their network architectures. Tokyo and Osaka remain key metropolitan areas where large corporations and service providers deploy comprehensive network management systems.
United Kingdom
The financial services sector and a growing reliance on hybrid cloud environments drive requirements for integrated security and performance management. The UK GDPR, post-Brexit, continues to shape data residency and compliance features for network platforms. London's financial district and technology clusters across the Southeast demand high-performance, secure network solutions.
Unified Network Management Market Key Industry Players
Listed leaders compete with private specialists across the unified network management market, which exhibits a tiered structure. Established networking giants leverage their broad portfolios, while pure-play software vendors focus on cloud-native solutions. Hardware-centric companies concentrate on underlying infrastructure components. Dominant competitive moves include strategic partnerships to expand solution ecosystems and continuous technology integration to enhance platform capabilities.
Established networking vendors like Cisco Systems, Inc. occupy a significant position, leveraging their incumbency across enterprise accounts. Juniper Networks, Inc. exemplifies a focus on AI-driven automation and software-defined networking strengths. Broadcom Inc. sits within the hardware and silicon specialist archetype, anchoring the performance of high-throughput networks.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Company |
| Huawei Technologies Co., Ltd. |
| Broadcom Inc. |
| Juniper Networks, Inc. |
| IBM Corp. |
| Telefonaktiebolaget LM Ericsson |
| Extreme Networks |
| NetScout Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Consumption-based subscription models are displacing perpetual licensing, reshaping software delivery from on-premise to cloud-centric models. This transition simultaneously reconfigures pricing from capital expenditure to operational expenditure, influencing procurement patterns for Managed Service Providers.
Pricing Analysis
Volume-discount tiering structures characterize the unified network management market's subscription-based pricing. Price differentiation often stems from the customization level for advanced enterprise features and the inclusion of premium after-sales service for Managed Service Providers. Pricing softness reflects the availability of open-source alternatives, particularly for small businesses with limited budgets. Large enterprises, prioritizing robust performance and security, exhibit the least price sensitivity.
Supply Chain Analysis
Software-defined solution inventories are predominantly digital, minimizing physical lead-time concerns for the core platform. However, underlying hardware components for high-performance networks draw from concentrated manufacturing hubs in Taiwan, South Korea, and China. Specialized silicon chips and network processors represent critical input dependencies. Single-source vulnerability for advanced semiconductor components presents a structural risk, while distribution runs through direct sales and channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Unified Network Management Market reflects a significant buyer-power shift, driven by Managed Service Providers consolidating client infrastructure management. This consolidation redefines procurement dynamics, favoring flexible, software-driven solutions over traditional capex models.
For Market Incumbents: Shield existing enterprise accounts by deepening AI-driven automation capabilities within current product portfolios. Expand cloud-native solution offerings to counter pure-play software vendors and open-source alternatives. Investing in AIOps R&D and securing long-term service contracts with large enterprises provides a strong defensive lever. This approach mitigates the threat of specialized software vendors displacing traditional infrastructure.
For New Entrants and Emerging Players: Service-layer gaps exist in integrated SecOps platforms tailored for mid-market businesses and edge computing deployments. New entrants can target Managed Service Providers in underpenetrated Southeast Asian markets like Singapore and Indonesia. Offering outcome-based pricing models and rapid, low-code deployment solutions provides a compelling go-to-market angle. This strategy leverages agility against incumbent complexity.
For Investors and Strategic Acquirers: GDPR and other data residency laws reshape the acquisition landscape, favoring platforms with embedded compliance features. The unified network management market remains viable long-term, essential for managing complex hybrid IT environments over the next five to ten years. Investors should seek pure-play AIOps or integrated SecOps specialists with strong multi-cloud capabilities. Consolidation among security and performance management vendors serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating with major cloud service providers enhances interoperability for hybrid IT environments. |
| AI/ML R&D Investment | Developing predictive analytics capabilities reduces network downtime by identifying potential faults. |
| Geographic Expansion | Targeting Southeast Asian markets capitalizes on rapid cloud adoption and digital transformation initiatives. |
| Strategic Partnership | Collaborating with SIEM vendors creates unified SecOps platforms for comprehensive security management. |
| Subscription Model Refinement | Optimizing consumption-based pricing tiers attracts Managed Service Providers seeking cost alignment with usage. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, complemented by extensive secondary validation. Stakeholders included CTOs, IT procurement officers, network engineers, and Managed Service Provider executives. Secondary data sources comprised SEC filings, technology vendor whitepapers, and government regulatory documents from the FCC and EU GDPR. This approach enabled bottom-up and top-down triangulation for comprehensive market insights.
Quantitative modeling was applied across the analysis window to project market trajectories. Segmentation dimensions included deployment model, solution offering, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from historical data and projected growth drivers. Key forecast inputs included cloud infrastructure expansion rates and AIOps technology adoption trends.
Underlying assumptions cover technological stability and the prevailing regulatory environment, with deviation risk concentrated in the pace of AI innovation. Global cybersecurity threat landscape evolution and macroeconomic shifts could also influence market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Microduct Market
Network Technology
Network Performance Monitoring Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Private Network Services Market
Network Technology
Protocol Analyzer Market
Network Technology
Managed Switches Market
Network Technology
Data Center Switches Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Global Home Networking Device Market
Network Technology
Open RAN Market
Network Technology
IT Connector Market