
 Internet Protocol Address Management (IPAM) Market | 2026-2036
Internet Protocol Address Management (IPAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Internet Protocol Address Management (IPAM) Market Foresight
GDPR's network-traceability requirements is consolidating compliance budgets toward platforms that unify IP auditing with identity governance. Infoblox leverages deep DNS-DHCP-IPAM integration to anchor enterprise contracts in regulated sectors. BlueCat Networks competes through hybrid deployment flexibility that spans on-premises data centers and AWS or Azure footprints. EfficientIP sustains European market presence with DNS security extensions that satisfy France's ANSSI certification frameworks.
Internet Protocol Address Management (IPAM) encompasses software systems that plan, track, and manage IP address spaces across IPv4 and IPv6 networks, typically integrating with DNS and DHCP services through automated discovery protocols and REST APIs. Its primary commercial purpose is to eliminate address conflicts, ensure subnet utilization efficiency, and maintain audit trails for security forensics and regulatory compliance. Cloud-Based and SaaS product types are capturing the fastest expansion as enterprises abandon spreadsheet-based tracking for API-driven orchestration, while On-Premises deployments retain margin pools in defense and classified government environments where data sovereignty rules apply. The Deployment Model dimension shows Multi-Cloud configurations gaining traction as organizations distribute workloads across AWS, Azure, and Google Cloud, each requiring synchronized IP federation.
The US Federal Risk and Authorization Management Program (FedRAMP) and the EU NIS2 Directive are reshaping procurement criteria by mandating continuous IP asset inventory and threat-response automation. ISO 27001 certification requirements further tighten vendor qualification for financial services and healthcare buyers across multiple geographies. Stakeholders must weigh the pace of IPv6 exhaustion against software-defined perimeter architectures that abstract IP visibility entirely.
Market Dynamics
IPv6 exhaustion timelines and software-defined perimeter architectures are generating contradictory pressures on IP visibility requirements, forcing enterprises to maintain granular address governance while abstracting network layers.
Growth Catalysts
- EU NIS2 Directive:Network and Information Systems 2 mandates continuous asset inventory across critical infrastructure operators, compelling procurement of automated IP discovery platforms in Germany, France, and the Netherlands.
- Hyperscaler expansion:AWS, Azure, and Google Cloud are exhausting IPv4 blocks at unprecedented rates, driving cloud-native IPAM adoption for federated address management across distributed regions.
- Zero-trust architecture mandates:US federal agencies under FedRAMP guidelines require microsegmentation with dynamic IP assignment, creating demand for API-driven orchestration that integrates with identity providers.
Market Restraints
- IPv4 address scarcity premiums:Regional Internet Registries have depleted available IPv4 pools, forcing enterprises to pay transfer market rates that consume 15-40% of network infrastructure budgets.
- Legacy DHCP server concentration:Microsoft and ISC BIND deployments in on-premises data centers create vendor lock-in that slows cloud migration timelines and fragments address management workflows.
- Skills fragmentation:Network engineering talent proficient in both IPv6 subnetting and cloud-native automation remains concentrated in Silicon Valley, London, and Bangalore, creating hiring bottlenecks.
Strategic Opportunities
- Edge computing deployments:Manufacturing and autonomous vehicle sectors in Japan and South Korea require localized IPAM instances for 5G-connected factory floors and vehicle-to-infrastructure networks.
- API-first platform convergence:Integration between IPAM, IT service management, and security orchestration tools is creating new product categories for workflow automation vendors.
- India's data localization requirements:The Personal Data Protection Bill and RBI guidelines for financial institutions mandate domestic IP address tracking, opening market entry for regional SaaS providers.
Industry Challenges
- Multi-cloud IP federation complexity:Enterprises operating across AWS, Azure, and Google Cloud struggle to maintain consistent subnet policies and prevent address overlap during workload migration.
- DNSSEC deployment timelines:ANSSI, BSI, and other national cybersecurity agencies require signed DNS zones, but certificate management and key rotation workflows extend implementation cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet Protocol Address Management (IPAM) Market |
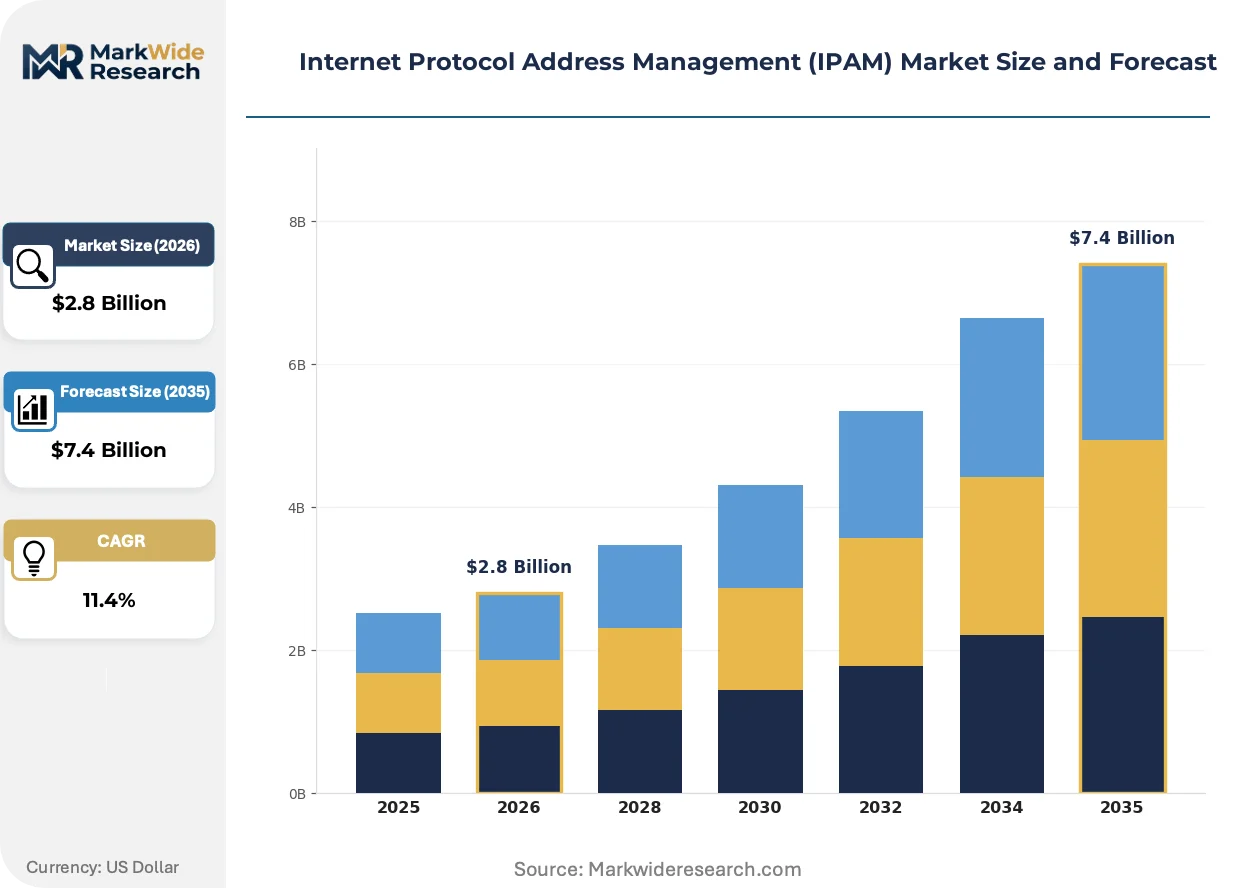
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing End User: Large Enterprises, SMEs, Telecom Providers, Managed Service Providers Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | EfficientIP, Men & Mice, Infoblox, NetBox, phpIPAM, SolarWinds, ManageEngine, Cisco Systems, BlueCat Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet Protocol Address Management (IPAM) Market Shifts & Advancements
Container networking and service mesh architectures are dissolving traditional IP address permanence, forcing IPAM vendors to reinvent discovery mechanisms for ephemeral workloads.
Intent-based networking (IBN) is electrifying enterprise campus and data center deployments by translating business policies into automated subnet provisioning. Fortune 500 manufacturers in Germany and automotive suppliers in Michigan are piloting Cisco DNA Center and Juniper Mist integrations that collapse provisioning time from days to minutes. This shift is compressing margins for professional services-dependent implementation models while elevating API subscription revenue.
France's ANSSI certification framework and Germany's BSI baseline protection standards are mandating DNS security extensions and IP asset traceability for operators of essential services. Healthcare networks and energy grid operators must now maintain audit-ready address inventories with 72-hour incident response capabilities. French critical infrastructure providers are consolidating vendor relationships around platforms that unify IPAM with DNS firewall functions to satisfy dual compliance requirements.
Enterprise buyers are unbundling implementation services from software licenses, preferring consumption-based pricing tied to managed IP address volumes rather than perpetual seat models. This pattern is most visible among mid-market retailers and logistics operators in the United Kingdom and the Netherlands, where CFOs demand OpEx alignment with cloud spending patterns. Vendors responding with usage-metered SaaS offerings are capturing switching accounts from traditional on-premises incumbents.
Internet Protocol Address Management (IPAM) Market Segmentation
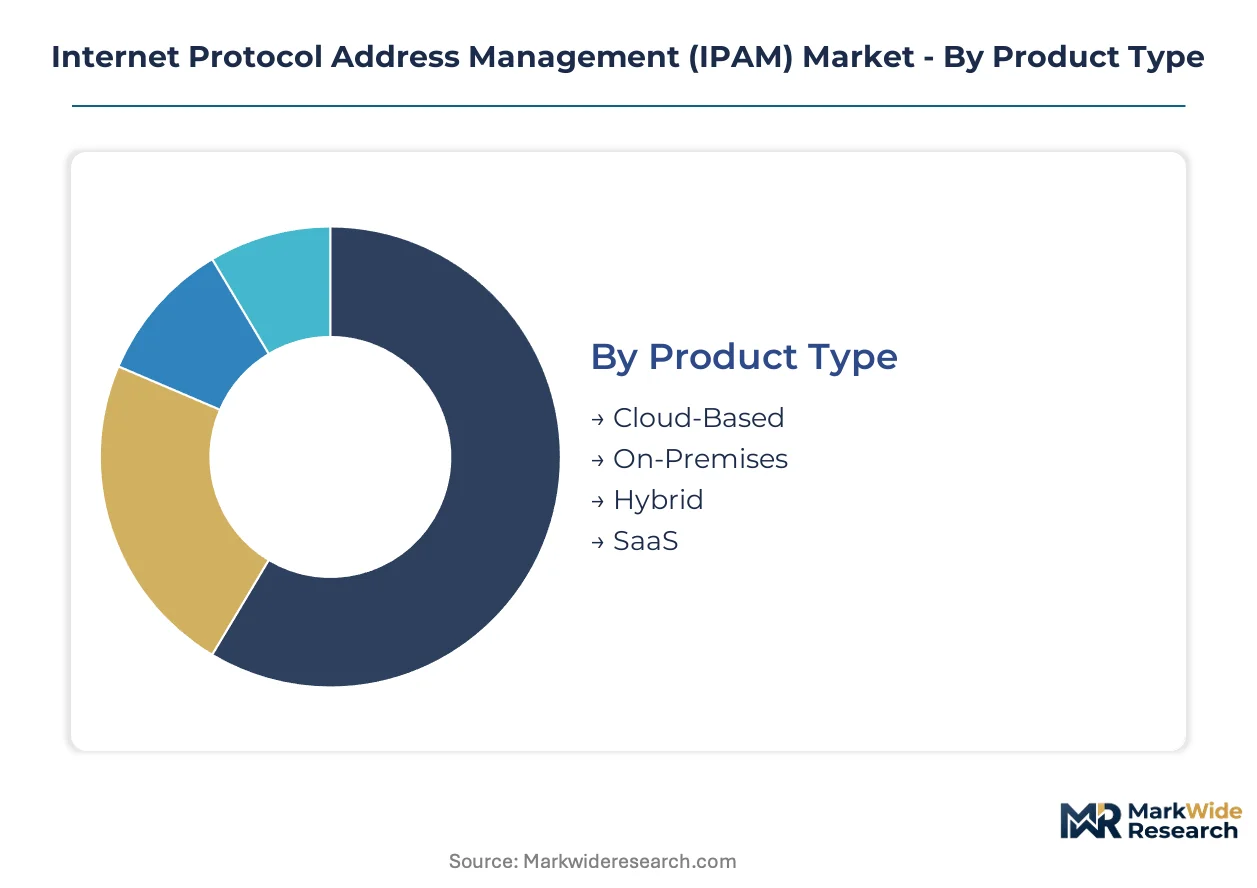
IPAM procurement patterns diverge sharply between organizations seeking standalone orchestration platforms and those embedding address management within broader infrastructure stacks. Segmentation clarity helps vendors align R&D investment with deployment friction points and compliance workflows.
Product Type:
Cloud-native architectures favor API-first delivery models, while regulated sectors maintain on-premises control for audit sovereignty.
- Cloud-Based:Distributed infrastructure with regional failover clusters serves hyperscaler customers managing IPv6 exhaustion across AWS, Azure, and Google Cloud footprints. Financial services firms in Singapore and Switzerland select these deployments for DR resilience without data center capital.
- On-Premises:Hardware-anchored installations with local database persistence dominate defense contractors and classified government facilities subject to FedRAMP High baselines. German automotive manufacturers also favor this mode for factory floor isolation.
- Hybrid:Synchronized on-premise and cloud control planes bridge legacy DHCP estates with container orchestration.
- SaaS:Metered subscription access with REST API gateways attracts mid-market retailers seeking OpEx alignment.
Volume placements concentrate in On-Premises; the faster expansion belongs to Cloud-Based.
Deployment Model:
Workload distribution patterns determine whether organizations prioritize single-cloud simplicity or federated address governance.
- Public Cloud:Native IPAM services integrated with AWS VPC, Azure VNet, or Google Cloud networking accelerate provisioning for DevOps teams. Israeli cybersecurity startups and Dutch e-commerce operators standardize here for speed-to-market.
- Private Cloud:OpenStack or VMware NSX-based deployments retain subnet control within sovereign data centers. Saudi Aramco and other national oil companies mandate this architecture for SCADA network segmentation.
- Multi-Cloud:Cross-platform federation prevents address collision during workload migration between providers.
- Edge Computing:Lightweight agents on factory gateways and 5G base stations enable localized DHCP for autonomous systems.
Multi-Cloud configurations command premium pricing; Edge Computing is climbing the fastest among manufacturing verticals.
End User:
Procurement sophistication varies from centralized IT governance to distributed MSP-led administration.
- Large Enterprises:Global address hierarchies spanning 50,000+ endpoints require workflow integration with ServiceNow and Splunk. US federal agencies and EU banking consortia drive feature roadmaps for audit automation.
- Telecom Providers:Subscriber management at scale demands real-time IP allocation for broadband and mobile cores.
- SMEs:Template-driven deployments with minimal customization suit resource-constrained IT shops.
- Managed Service Providers:Multi-tenant dashboards with client isolation enable outsourced network operations.
Telecom Providers generate the highest absolute address volumes; SMEs are expanding most quickly as SaaS lowers entry barriers.
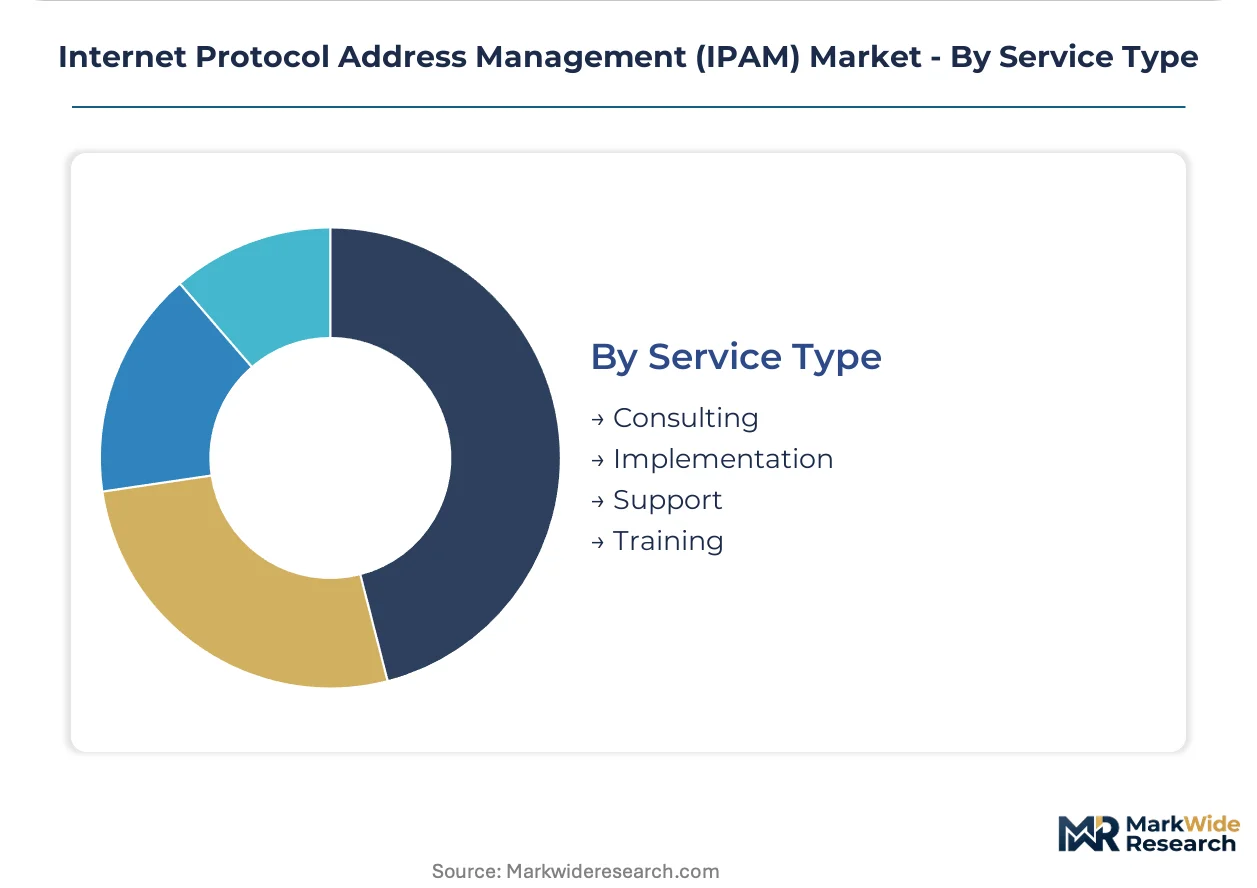
Service Type:
Revenue mix shifts from perpetual license bundles toward consumption-aligned delivery models.
- Implementation:Migration engineering from spreadsheet or BIND legacy systems commands project-based fees. French critical infrastructure operators under ANSSI mandates require 12-18 month phased rollouts with DNSSEC integration.
- Support:Tiered response SLAs with 24/7 escalation paths anchor enterprise renewal rates.
- Consulting:IPv6 transition planning and subnet optimization studies address skills gaps.
- Training:Certification programs for cloud-native automation build internal competency.
Support contracts dominate recurring revenue; Implementation services show steepest expansion trajectory amid cloud migration waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal agencies and hyperscaler operations concentrate the heaviest IPAM procurement volumes, while European regulatory mandates and Asia-Pacific cloud expansion create parallel demand corridors.
United States
FedRAMP authorization requirements and zero-trust architecture mandates drive federal IT modernization budgets toward automated IP discovery platforms. The Department of Defense and civilian agencies must maintain continuous asset inventories under NIST SP 800-207 guidelines. Northern Virginia's data center corridor hosts the densest concentration of cloud-native IPAM deployments as AWS, Azure, and Google Cloud expand regional capacity.
Germany
BSI baseline protection standards and critical infrastructure regulations compel energy grid operators and automotive manufacturers to upgrade network visibility tools. The country's industrial Mittelstand requires hybrid IPAM architectures bridging on-premises SCADA systems with cloud orchestration. Bavaria's automotive supplier cluster around Munich leads factory-floor implementations for connected manufacturing networks.
France
ANSSI certification frameworks mandate DNS security extensions and IP asset traceability for operators of essential services under the NIS2 Directive implementation. Healthcare networks and nuclear energy operators face 72-hour incident response requirements. The Paris-Saclay research cluster drives early adoption of intent-based networking integrations for campus and laboratory environments.
Japan
METI's cybersecurity guidelines for critical infrastructure and 5G network expansion accelerate IPAM adoption among telecommunications providers and manufacturing conglomerates. The country's automotive and electronics sectors require localized address management for autonomous vehicle testing and smart factory deployments. Toyota City and the Kansai industrial corridor represent concentrated pilot sites for edge-computing IPAM instances.
India
RBI guidelines for financial institutions and the Personal Data Protection Bill mandate domestic IP address tracking and data localization for banking and insurance networks. The country's SaaS ecosystem and IT services exporters require multi-cloud federation capabilities for client workload management. Bangalore's technology corridor and Mumbai's financial district anchor the fastest-growing regional deployment base.
Internet Protocol Address Management (IPAM) Market Competitive Landscape
United States vendors anchor the premium integration tier; European specialists hold compliance-certification positions. The market structures around three concentration layers: incumbent network infrastructure providers with embedded IPAM modules, pure-play software vendors with API-first architectures, and open-source projects with commercial support ecosystems. Competitive dynamics center on strategic partnerships with hyperscaler marketplaces and vertical integration into adjacent DNS security and identity governance platforms.
Within the pure-play tier, Infoblox and BlueCat Networks represent deep DNS-DHCP-IPAM integration archetypes, while EfficientIP occupies a position emphasizing European regulatory certification coverage. These three exemplify contrasting geographic anchoring strategies: United States-based incumbents leveraging federal procurement relationships, and France-based specialists exploiting ANSSI and BSI compliance pathways. Cisco Systems sits within the infrastructure-embedded category, representing network hardware vendors that bundle address management with routing and switching platforms. NetBox and phpIPAM exemplify the open-source commercialization archetype, where community-developed cores support managed service provider and enterprise customization markets.
| Leading Market Players |
|---|
| EfficientIP |
| Men & Mice |
| Infoblox |
| NetBox |
| phpIPAM |
| SolarWinds |
| ManageEngine |
| Cisco Systems |
| BlueCat Networks |
| Others |
Supply & Pricing Matrix
IPv4 address transfer market indices cascade through IPAM vendor pricing tiers, compressing margins on perpetual-license offerings while elevating subscription-based SaaS premiums for automated orchestration platforms.
Pricing Analysis
Volume placements concentrate in on-premises perpetual licenses with compressed margins, while cloud-native SaaS tiers capture expanding margin pools through API consumption metering. Price differentiation hinges on FedRAMP authorization tier and DNS-DHCP integration depth. Pricing pressure stems from hyperscaler marketplace listings that commoditize basic IP discovery functions. Mid-market retailers exhibit highest price sensitivity; defense contractors under FedRAMP High baselines demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan semiconductor fabrication for specialized network processors and Ireland data center hosting for EU data sovereignty compliance. Geographic supply concentration centers on the United States, Ireland, and Singapore for cloud infrastructure nodes. Raw material dependencies include silicon photonics components, encryption acceleration chips, and renewable energy contracts for data center power. Supply chain risk manifests through regulatory restriction on cross-border data flows under GDPR and India's Personal Data Protection Bill. Distribution runs through hyperscaler marketplaces and direct enterprise sales with professional services bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IPAM market positioning is accelerating into a vertical-integration race, with vendors pursuing downstream control over adjacent DNS security and identity governance platforms to anchor enterprise contracts.
For Market Incumbents: To counter open-source alternatives like NetBox and phpIPAM, deepen API-first platform convergence with IT service management tools and security orchestration platforms. Prioritize FedRAMP High authorization investment to lock federal procurement channels against emerging cloud-native entrants.
For New Entrants and Emerging Players: Begin with India's data localization requirements under RBI guidelines, where domestic IP address tracking mandates create white-space for regional SaaS providers. Target mid-market financial institutions in Mumbai and Bangalore with consumption-metered offerings that align with OpEx budgeting patterns.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European compliance-certified specialists in France and Germany, where ANSSI and BSI mandates extend implementation timelines and deepen vendor stickiness. Watch for IPv6 exhaustion acceleration as the inflection signal for cloud-native IPAM valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Unifies IPAM with ServiceNow and Splunk workflows for Fortune 500 manufacturers. |
| FedRAMP Authorization Pathway | Unlocks Department of Defense and civilian agency procurement under NIST guidelines. |
| DNS Security Extension Certification | Satisfies France ANSSI and Germany BSI mandates for critical infrastructure operators. |
| Multi-Cloud Federation Capability | Prevents address collision across AWS, Azure, and Google Cloud workload migrations. |
| Edge Computing Localization | Captures 5G-connected factory floor deployments in Japan and South Korea. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU NIS2 implementation guidance formed the secondary backbone, cross-referenced with primary interviews with network engineering directors, cloud infrastructure architects, federal procurement officers, and managed service provider operations leads. Bottom-up address volume estimates from telecom providers and hyperscaler regions were triangulated against top-down IT security spending allocations.
Historical trendline analysis of IPv4 exhaustion timelines and cloud migration waves anchored the projection framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory intensity, and geographic data sovereignty requirements. CAGRs were derived from fitted growth curves incorporating IPv6 adoption acceleration and zero-trust architecture mandate implementation pacing.
Regulatory enforcement variance, hyperscaler IPv4 block exhaustion timing, and software-defined perimeter adoption velocity are the dominant revision risks to modeled outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Cloud Managed Access Points Market
Network Technology
Hyperconnectivity Market
Network Technology
Passive Optical Network Market
Network Technology
ISP Management Systems Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Routing Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
US Private 5G Network Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
North America Network Management Solutions Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Mobile Network Optimization Market