
 DNS DHCP and IPAM Market | 2026-2036
DNS DHCP and IPAM Market Size, Share, and Industry Trends Forecast 2026-2036
DNS DHCP and IPAM Market Analysis
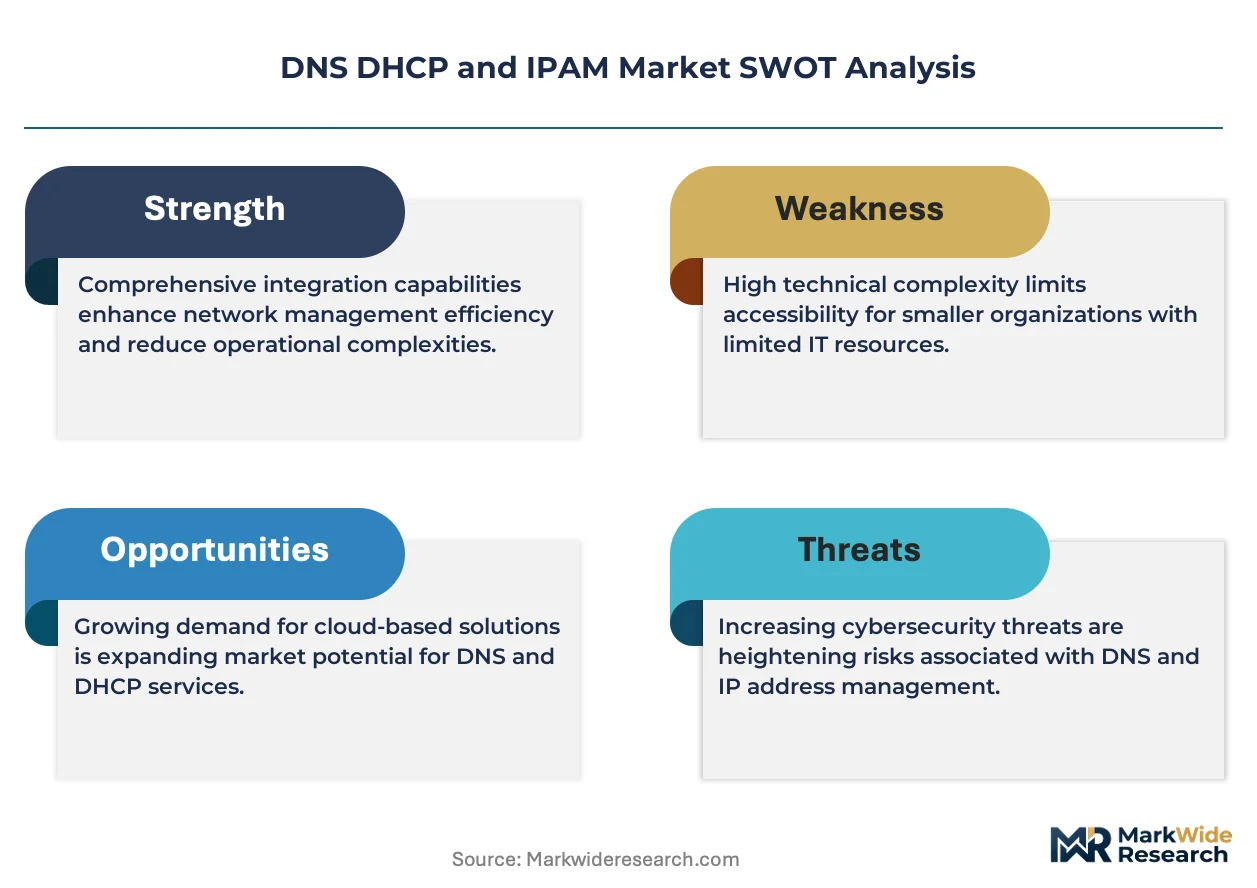
GDPR Article 32 and the EU NIS2 Directive are recalibrating the cost-of-entry calculus for network infrastructure vendors serving European enterprises. Infoblox leverages deep protocol specialization to anchor premium positioning in regulated sectors. Cisco Systems sustains broad channel control through embedded DDI modules within its campus and data center switching portfolios. BlueCat Networks differentiates via upstream control over DNS security extensions and threat intelligence integration.
DNS DHCP and IPAM (DDI) denotes the integrated management of domain name resolution, dynamic host configuration, and IP address inventory within enterprise and service provider networks, typically operating through BIND, ISC DHCP, or proprietary protocol stacks with REST API orchestration layers. The primary purpose is eliminating address conflicts, ensuring service continuity, and enabling automated provisioning across physical, virtual, and containerized infrastructure. Cloud-based deployment models are capturing the fastest expansion as multi-cloud DNS sprawl forces centralized visibility, while on-premises integrated systems retain the largest installed base and renewal revenue pools. IPv6 technology segments are accelerating as address exhaustion and 5G core deployments drive dual-stack mandates, though IPv4 still dominates legacy enterprise refresh cycles.
The Federal Communications Commission in the United States enforces network reliability standards that cascade into DDI resilience requirements for telecommunications carriers, while the European Union Agency for Cybersecurity (ENISA) operationalizes NIS2 compliance timelines that shape procurement specifications. China's Ministry of Industry and Information Technology (MIIT) mandates domestic encryption standards for DNS infrastructure that filter market access for foreign vendors. Stakeholders must monitor the divergence between sovereign cloud mandates and unified DDI orchestration architectures as a decisive tension in platform strategy.
Market Dynamics
Zero-trust security mandates and IPv6 dual-stack requirements are compressing refresh cycles for DDI infrastructure across federal agencies and cloud-native enterprises. These forces are recalibrating procurement specifications toward automated orchestration and threat intelligence integration.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators across energy, transport, and healthcare verticals face mandatory network resilience standards that elevate DDI to core compliance infrastructure.
- Container orchestration platforms:Kubernetes and OpenShift deployments require dynamic IP allocation at pod scale, forcing enterprises to replace static DHCP with API-driven address management.
- 5G core buildouts:Mobile network operators in South Korea and Japan are deploying IPv6-native DDI stacks to support network slicing and massive IoT addressing.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in BIND protocol internals and DNSSEC implementation concentrates among a narrow pool of network architects, inflating implementation costs.
- On-premises sunk investment:Legacy appliance deployments in financial services and government sectors create switching friction that delays cloud migration timelines.
- Fragmented multi-vendor environments:Heterogeneous DNS estates spanning Infoblox, Microsoft, and open-source BIND complicate unified policy enforcement and audit trails.
Strategic Opportunities
- Edge computing nodes:Distributed micro data centers require localized DDI instances with centralized policy orchestration, opening greenfield deployment opportunities.
- DNS security extensions (DNSSEC) automation:Regulatory pressure from ENISA is creating demand for turnkey key management and rollover services.
- API-first SaaS delivery:Cloud-native enterprises are displacing perpetual licenses with consumption-based DDI subscriptions that align spend with workload growth.
Industry Challenges
- IPv6 migration complexity:Dual-stack coexistence requires rearchitecting address allocation logic, DHCPv6 option sets, and reverse DNS zones without service disruption.
- Certificate lifecycle management:DNSSEC and DANE implementations demand automated key generation, storage, and rotation workflows that most IT organizations lack operational maturity to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNS DHCP and IPAM Market |
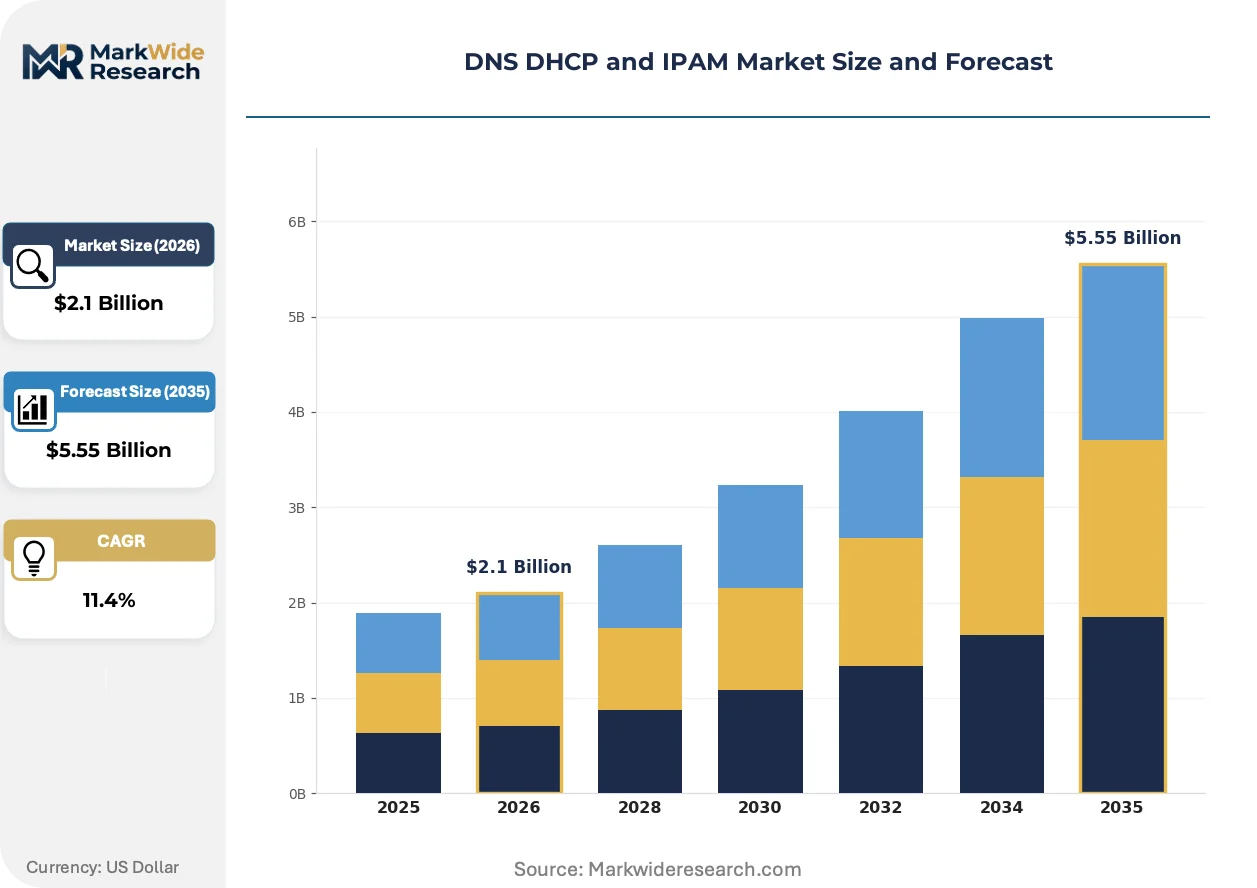
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNS Services, DHCP Solutions, IPAM Software, Integrated Systems Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services End User: Enterprises, Service Providers, Government Agencies, Educational Institutions Technology: IPv4, IPv6, Software-Defined Networking, Automation Tools |
| Companies Covered | Cisco Systems, SolarWinds, Infoblox, Men & Mice, TCPWave, BlueCat Networks, Microsoft, FusionLayer, EfficientIP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNS DHCP and IPAM Market Emerging Trajectories
Artificial intelligence and machine learning are embedding into DDI platforms to automate anomaly detection and predictive capacity planning. These capabilities are shifting competitive differentiation from protocol compliance toward operational intelligence.
DNS-over-HTTPS (DoH) and DNS-over-TLS (DoT) protocols are integrating encryption directly into recursive resolution paths, masking query metadata from network observers. Enterprise security teams are adopting these standards to prevent DNS-based data exfiltration and surveillance. This encryption layer is integrating with zero-trust network access frameworks, collapsing the distinction between DNS security and identity-based perimeter controls.
The Federal Communications Commission is enforcing reliability standards for telecommunications carriers that cascade into mandatory DDI redundancy and failover architectures. These requirements are accelerating investment in anycast DNS deployments and geographically distributed DHCP failover pairs. Rural broadband providers face the steepest compliance burden as they modernize legacy IP address management systems.
Cloud-native procurement patterns are displacing traditional RFP-driven appliance purchases with self-service marketplace transactions. Platform engineering teams are acquiring DDI capabilities through infrastructure-as-code templates rather than centralized IT procurement. This shift is most visible among technology and media enterprises with mature DevOps practices and multi-cloud footprints.
DNS DHCP and IPAM Market Segmentation
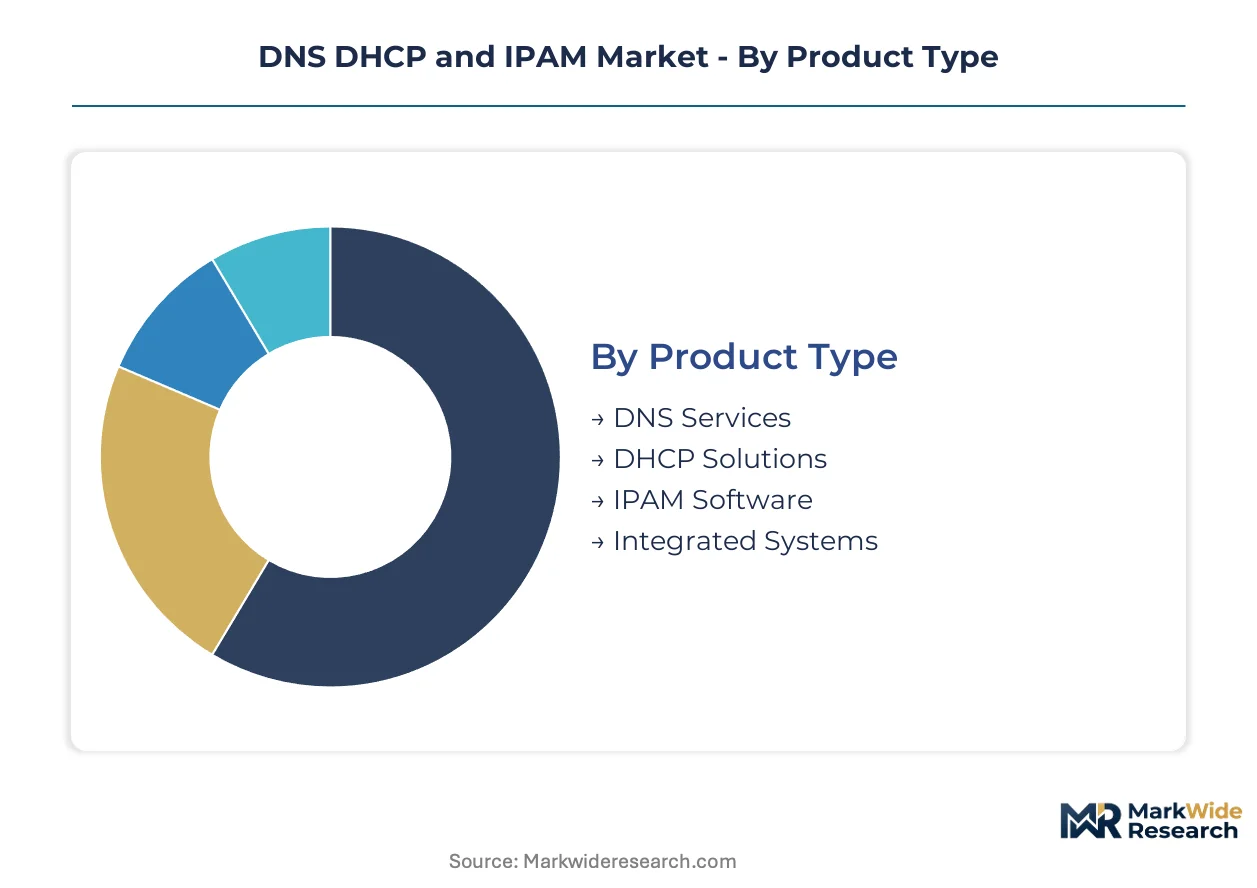
Segmentation in the DNS DHCP and IPAM market reveals divergent upgrade pressures across infrastructure layers. Deployment choices and protocol transitions create distinct procurement patterns that vendors must address through specialized packaging and pricing architectures.
Product Type:
Refresh cycles vary sharply by product layer, with integrated systems commanding the longest replacement timelines while point solutions face compressed obsolescence from cloud-native demands.
- DNS Services:Recursive and authoritative resolution platforms handle query routing across hybrid topologies. Federal zero-trust mandates in the United States are accelerating DNS security overlay purchases among defense contractors and civilian agencies.
- DHCP Solutions:Dynamic address allocation engines provision endpoints across physical, virtual, and containerized estates. Kubernetes-driven IP exhaustion in technology enterprises is forcing replacement of legacy ISC DHCP deployments with API-native alternatives.
- IPAM Software:Inventory and reconciliation systems track address utilization across fragmented estates. Financial services firms in Frankfurt and London prioritize these tools for audit compliance under NIS2 Directive requirements.
- Integrated Systems:Unified DDI platforms consolidate protocol management under single policy planes. Large-scale data center operators in Northern Virginia and Dallas-Fort Worth favor these systems for operational consolidation.
Integrated Systems sits at the top of the volume ranking, with DHCP Solutions climbing the fastest.
Deployment Model:
Cost tier differentiation separates perpetual-license appliances from consumption-based SaaS offerings, with hybrid architectures capturing mid-market procurement.
- On-Premises:Appliance and software deployments within customer-controlled facilities retain dominance in regulated sectors. German automotive manufacturers and Japanese telecommunications carriers maintain these installations for data sovereignty compliance.
- Cloud-Based:SaaS-delivered DDI platforms eliminate infrastructure ownership through subscription economics. Technology enterprises in Seattle and Austin with mature DevOps practices are displacing on-premises estates fastest.
- Hybrid Solutions:Split architectures anchor critical workloads on-premises while bursting policy management to cloud control planes. Canadian energy sector operators favor this model for operational technology segmentation.
- Managed Services:Outsourced DDI operations transfer operational burden to specialized providers. Mid-market enterprises in Australia and Singapore lacking BIND protocol expertise contract these arrangements for DNSSEC compliance.
On-Premises retains the largest revenue base, though Cloud-Based is expanding most quickly among net-new procurement.
End User:
Customer type determines feature prioritization, with government buyers emphasizing certification and audit trails while enterprises chase automation velocity.
- Enterprises:Corporate IT departments spanning manufacturing, retail, and healthcare verticals drive the majority of DDI refresh spending. Multi-cloud DNS sprawl in Fortune 500 technology divisions is forcing centralized visibility investments.
- Service Providers:Telecommunications and cloud infrastructure operators deliver DDI-as-a-service to downstream customers. South Korean mobile operators deploying 5G core networks require IPv6-native stacks for network slicing support.
- Government Agencies:Federal, state, and municipal entities face mandated resilience standards that elevate DDI to critical infrastructure. United States civilian agencies comply with CISA zero-trust architecture directives through hardened DNS deployments.
- Educational Institutions:Universities and research networks manage heterogeneous device populations across distributed campuses. EDUROAM federation participants in the Netherlands and Scandinavia prioritize DHCP option standardization for roaming client support.
Enterprises command the highest absolute spending, with Government Agencies showing the steepest expansion trajectory from regulatory compliance mandates.
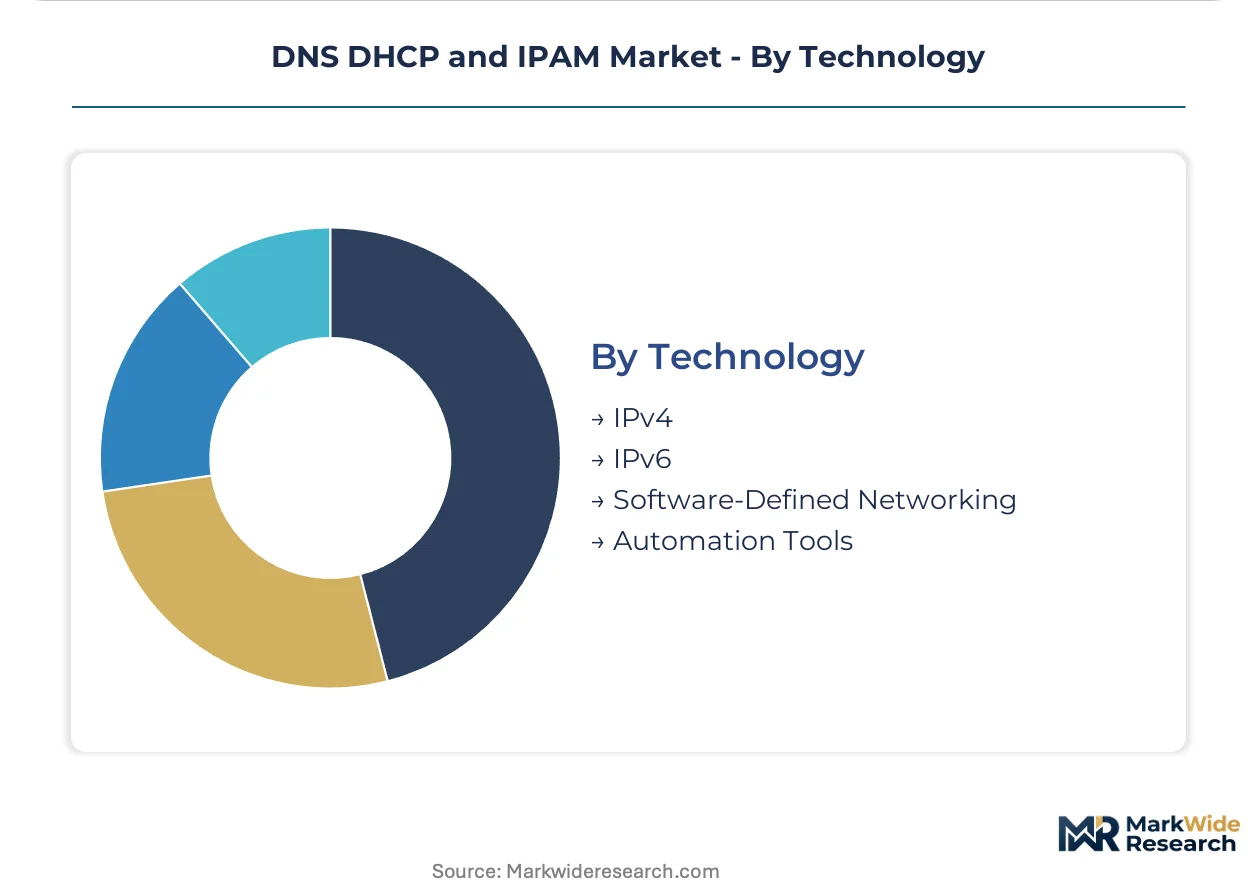
Technology:
Protocol maturity curves create divergent investment horizons, with IPv4 maintenance revenue funding IPv6 development roadmaps.
- IPv4:Legacy address management protocols dominate current installed base and renewal streams. Private address space exhaustion in Indian enterprise networks is accelerating NAT64 transition planning.
- IPv6:Next-generation addressing enables massive IoT scale and end-to-end connectivity restoration. Japanese and South Korean mobile operators deploy these stacks natively for 5G standalone core networks.
- Software-Defined Networking:SDN-integrated DDI enables programmable address allocation through controller APIs. Financial services data centers in Singapore and Hong Kong adopt these architectures for trading infrastructure agility.
- Automation Tools:Infrastructure-as-code and CI/CD-integrated provisioning eliminate manual IP management. Platform engineering teams at technology enterprises in Silicon Valley embed these capabilities through Terraform and Ansible modules.
IPv4 generates the largest current revenue pool, with Automation Tools gaining share fastest from cloud-native procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep BIND protocol expertise concentrates in the San Francisco Bay Area, Tel Aviv, and Stockholm, anchoring innovation clusters for DNS security automation. These talent pools feed engineering centers serving federal agencies and telecommunications carriers worldwide.
United States
Federal zero-trust mandates from CISA drive DDI refreshes across defense contractors and civilian agencies. The FCC enforces reliability standards that cascade into mandatory redundancy architectures for telecommunications carriers. Northern Virginia data center operators favor integrated DDI systems for operational consolidation at massive scale.
Germany
Automotive manufacturers in Stuttgart and Munich maintain on-premises DDI installations for data sovereignty compliance under GDPR Article 32. The EU NIS2 Directive elevates network resilience to core compliance infrastructure for energy and transport operators. Frankfurt financial services firms prioritize IPAM tools for audit trail requirements.
Japan
Mobile network operators deploy IPv6-native DDI stacks to support 5G standalone core networks and massive IoT addressing. METI industrial policy encourages domestic encryption standards for critical infrastructure. Tokyo and Osaka telecommunications clusters anchor regional deployment expertise for network slicing architectures.
South Korea
5G core buildouts by mobile operators demand IPv6-native DDI for network slicing and edge computing nodes. The national cybersecurity framework mandates DNSSEC implementation across critical infrastructure. Seoul Capital Area technology enterprises lead cloud-native DDI adoption through Kubernetes-integrated deployments.
United Kingdom
EDUROAM federation participants in London and Manchester prioritize DHCP option standardization for roaming client support across university networks. The National Cyber Security Centre publishes hardening guidelines that shape enterprise procurement specifications. Financial services firms in the City of London invest in API-first SaaS DDI for multi-cloud visibility.
DNS DHCP and IPAM Market Vendor Landscape
The competitive structure tilts toward protocol specialists commanding premium positioning in regulated sectors. Consolidation pressure concentrates among three to four integrated platform vendors while point solution providers face displacement from cloud-native demands. Strategic archetypes include deep protocol specialists, embedded networking incumbents, and API-native challengers. Dominant competitive moves encompass DNSSEC automation acquisitions and SaaS delivery model transitions.
Within the protocol specialist tier, Infoblox and BlueCat Networks exemplify deep BIND expertise anchoring premium positioning. Cisco Systems occupies a position as the embedded incumbent leveraging channel control through switching portfolio integration. Among cloud-native challengers, EfficientIP represents the API-first archetype targeting DevOps-centric procurement patterns. These three anchors illustrate the strategic divergence between on-premises consolidation and cloud-native displacement vectors reshaping vendor fortunes.
| Leading Market Players |
|---|
| Cisco Systems |
| SolarWinds |
| Infoblox |
| Men & Mice |
| TCPWave |
| BlueCat Networks |
| Microsoft |
| FusionLayer |
| EfficientIP |
| Others |
Supply Flow & Price Mechanics
Semiconductor price volatility in Taiwan and South Korea feeds directly into DDI appliance manufacturing costs, compressing margins on integrated hardware platforms while elevating SaaS subscription premiums for cloud-native alternatives.
Pricing Analysis
Bundled integrated DDI systems command substantial premiums over unbundled point solutions across enterprise procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates certified federal-compliant deployments from mid-market SaaS tiers and open-source alternatives. Price differentiation rests on DNSSEC automation capabilities and threat intelligence integration depth. Pricing pressure stems from hyperscale cloud providers bundling basic DNS resolution at marginal cost, forcing independent vendors toward specialized security overlays. Government agencies exhibit lowest price sensitivity due to zero-trust mandate compliance requirements, while mid-market enterprises in Australia and Singapore drive hardest bargain negotiations.
Supply Chain Analysis
Reverse-logistics flows for DDI hardware appliances concentrate refurbishment operations in Singapore and Amsterdam hubs, extending asset lifecycles for financial services clients with sunk on-premises investments. Manufacturing concentration spans Taiwan for proprietary silicon, Ireland for software development centers, and the United States for federal-certified final assembly. Component dependencies include x86 server platforms, cryptographic acceleration modules, and specialized network interface controllers. Single-source vulnerability in BIND protocol expertise pools creates talent acquisition bottlenecks that delay implementation timelines. Distribution runs through authorized channel partners for regulated sectors alongside direct self-service marketplaces for cloud-native procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in DDI markets hinges on SaaS delivery transitions that eliminate hardware COGS while capturing recurring revenue premiums from security-integrated subscriptions.
For Market Incumbents: Cement protocol specialization advantages through DNSSEC key management automation acquisitions that neutralize EfficientIP's API-native threat. Channel control in federal contracting requires maintaining FedRAMP authorization investments as CISA zero-trust mandates harden. Vertical integration into threat intelligence feeds differentiates premium tiers from commodity alternatives. For New Entrants and Emerging Players: Begin with edge computing micro data center deployments where localized DDI instances lack established vendor relationships. Canadian energy sector hybrid architectures offer lowest competitive density among regulated verticals. Kubernetes-native IPAM modules delivered through Terraform provider ecosystems bypass entrenched procurement committees. For Investors and Strategic Acquirers: Asymmetric upside sits with API-first SaaS challengers possessing consumption-based pricing architectures aligned to multi-cloud workload growth. Long-term viability favors vendors with demonstrated DNSSEC automation roadmaps and ENISA compliance positioning. Watch for hyperscaler partnership announcements as inflection indicators of enterprise credibility establishment.| Strategic Initiative | Industry Significance |
|---|---|
| DNSSEC Automation Acquisition | Consolidates key management expertise to meet ENISA compliance timelines for European critical infrastructure. |
| SaaS Delivery Transition | Eliminates hardware COGS while aligning revenue recognition with Kubernetes workload expansion patterns. |
| Federal Certification Investment | Unlocks CISA zero-trust mandate budgets across United States defense contractor and civilian agency procurement. |
| Threat Intelligence Integration | Differentiates premium positioning through real-time DNS-based attack vector detection and automated response. |
| Edge Computing Partnership | Captures greenfield micro data center deployments requiring localized DDI with centralized policy orchestration. |
Methodological Framework
Bottom-up enterprise IT procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with network architects, CISOs, platform engineering leads, and federal IT procurement officers combined with secondary validation from FCC enforcement databases, ENISA compliance guidance documents, hyperscaler capex disclosures, and SEC 10-K infrastructure software filings. Triangulation between demand-side budget cycle analysis and supply-side revenue recognition patterns ensures segmentation accuracy.
Input-output matrices map DDI deployment scale against IPv6 transition timelines and zero-trust architecture adoption curves across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory exposure, integration complexity, and regional sovereign cloud posture. CAGRs derive from regression analysis of historical refresh cycles against mandate-driven acceleration factors, with 5G core buildout schedules and container orchestration penetration serving as key forecast inputs.
Several conditions sit outside the modeled scope, including pure open-source BIND deployment economics and hyperscaler internal DDI tool development programs. Forecasts reflect assumptions regarding NIS2 enforcement consistency and federal zero-trust deadline adherence that regulatory delays could revise. Periodic stress-testing of base assumptions against emerging DNS-over-HTTPS standardization outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Wimax Solutions Market
Network Technology
Mobile Network Optimization Market
Network Technology
Industrial Ethernet Market
Network Technology
Enterprise Routers Market
Network Technology
Network Packet Broker Market
Network Technology
Hyperconnectivity Market
Network Technology
Europe Structured Cabling Market
Network Technology
MENA Wireless Routers Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Global Network Management Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Home Networking Device Market
Network Technology
Germany Residential Gateway Market
Network Technology
Microduct Market
Network Technology
Mobile Backhaul Market
Network Technology
Global Internet Transit Market