
 Global Internet Transit Market | 2026-2036
Global Internet Transit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet Transit Market Intelligence
Software-defined networking is reconfiguring how internet transit providers engineer backbone capacity and price interconnection services. Cogent Communications specializes in operating one of the largest IPv4 and IPv6 networks globally, leveraging its wholly owned fiber infrastructure to control last-mile costs. NTT Communications anchors significant trans-Pacific and intra-Asia capacity, sustaining dominance through submarine cable consortium investments and data center adjacencies.
Internet transit denotes the wholesale service of carrying IP traffic across autonomous systems, typically measured in megabits or gigabits per second with service level agreements guaranteeing packet delivery ratios above 99.99%. Its primary commercial purpose is enabling ISPs, content networks, and enterprises to reach destinations outside their own network boundaries without building global infrastructure. Dedicated transit commands premium pricing for guaranteed bandwidth and route diversity, while peering arrangements mature at major internet exchanges where traffic ratios balance and settlement-free interconnection displaces paid transit for large content platforms. Cloud service providers represent the fastest-growing application segment as hyperscalers backhaul traffic between distributed regions and local edge nodes.
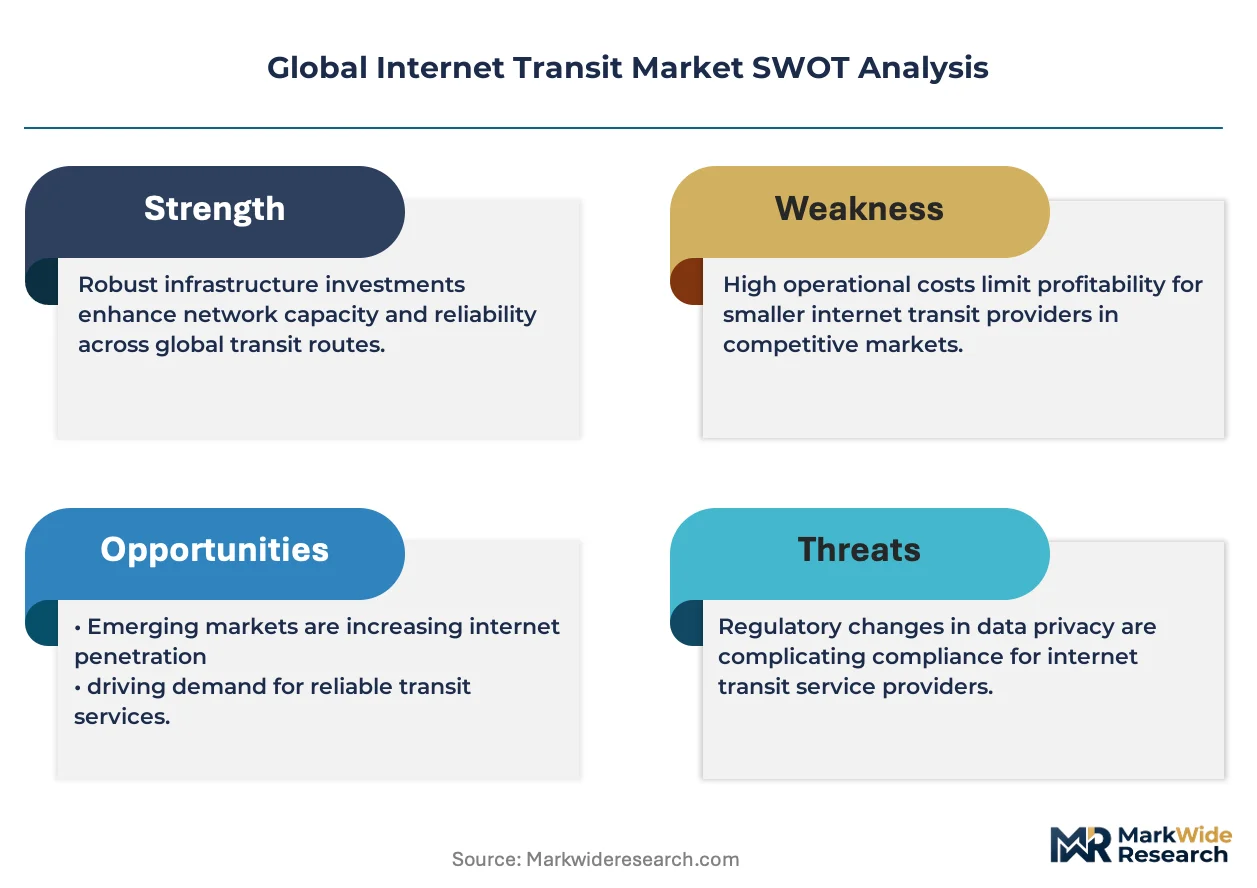
FCC open internet rules in the United States, EU GDPR data localization requirements, and China's MIIT cross-border data security assessments collectively shape where providers must site equipment, authenticate peers, and maintain lawful intercept capabilities. The EU AI Act and emerging spectrum coordination frameworks from the ITU further complicate transit routing decisions for machine learning workloads. Stakeholders must monitor regulatory divergence around data sovereignty and encryption standards to avoid stranded infrastructure investments and forced re-architectures of international backbones.
Market Dynamics
400G and 800G optical interface deployment is compressing per-bit economics while forcing wholesale repricing of long-haul capacity commitments across autonomous system interconnections.
Growth Catalysts
- Hyperscaler Edge Expansion:Cloud service providers are scaling distributed architectures that require dense interconnection at internet exchange points, pulling dedicated transit contracts into secondary metros.
- EU AI Act:Machine learning workload routing mandates under this framework are creating compliance-driven demand for sovereign transit paths with lawful intercept capabilities.
- Submarine Cable Landings:Brazil, Germany, and Japan are densifying landing station capacity, reducing latency arbitrage and anchoring regional hub economics for IP transit aggregation.
Market Restraints
- Optical Component Concentration:Coherent DSP and transceiver supply concentrates among a handful of foundry operators, creating input cost volatility for backbone upgrades.
- China MIIT Cross-Border Assessments:Data security review timelines extend provisioning cycles for international routes traversing Chinese territory, adding regulatory friction to capacity planning.
- IPv4 Address Exhaustion:Secondary market trading for remaining IPv4 blocks commands premium multiples, structurally elevating opex for providers maintaining dual-stack infrastructure.
Strategic Opportunities
- India TRAI Interconnection Reform:Pending regulatory revisions to internet exchange licensing create white space for neutral transit operators to establish presence in underpenetrated tier-2 cities.
- Terrestrial-Submarine Convergence:Integration of open line systems with cable landing stations enables new entrants to bypass incumbent carrier hotel bottlenecks at coastal aggregation points.
- Green Transit Certification:EU CSRD Scope 3 disclosure requirements are emerging as a procurement filter, rewarding providers with renewable-powered backbone footprints.
Industry Challenges
- Optical Engineering Talent Scarcity:Deployment of 800G coherent systems requires specialized skill sets in probabilistic constellation shaping that outpaces current training pipeline output.
- Multi-Vendor Interoperability:Disaggregated routing stacks from white-box suppliers introduce integration complexity with legacy MPLS cores during brownfield backbone modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet Transit Market |
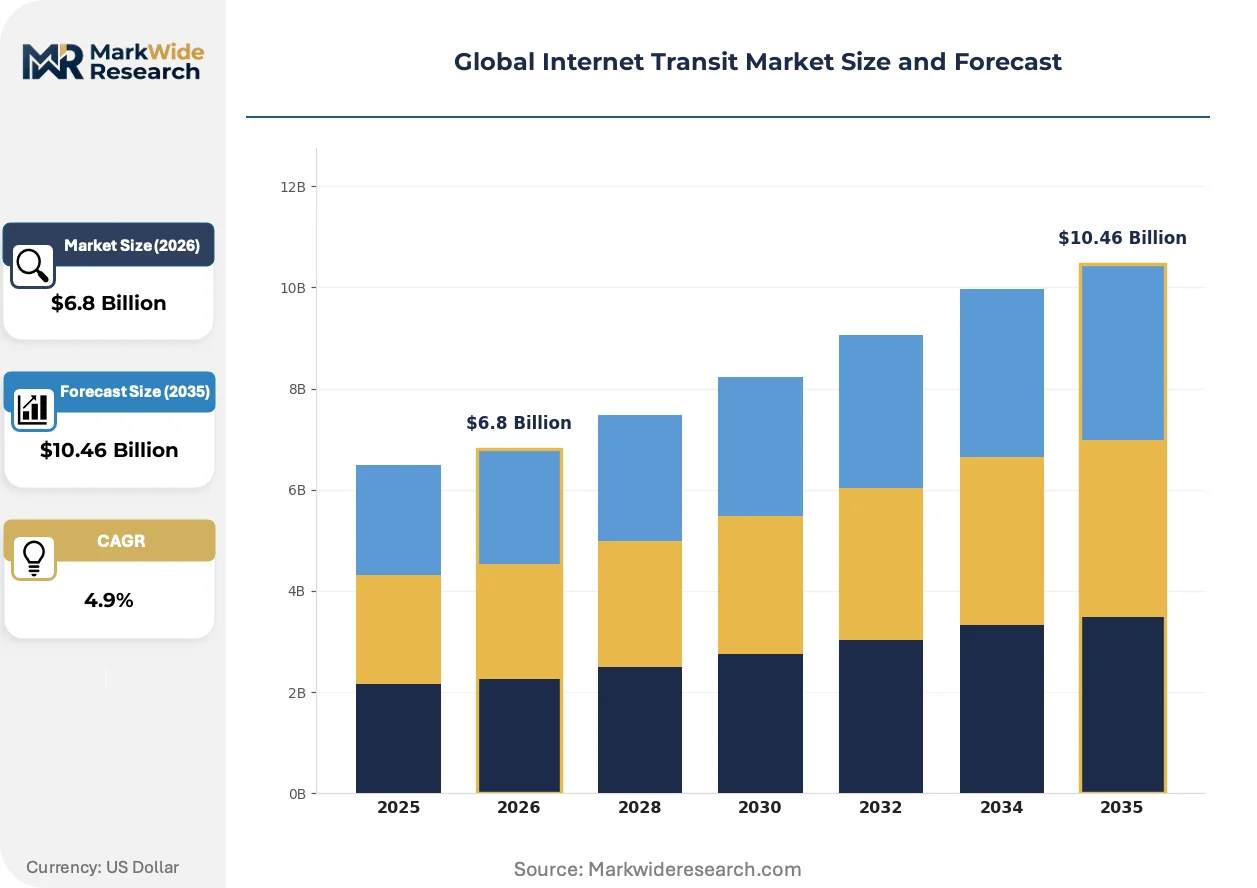
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Transit, Partial Transit, Peering, Resale, Managed Transit Application: Content Delivery Networks, Cloud Service Providers, Data Centers, Telecom Operators, Enterprise Connectivity End User: ISPs, Web Hosting Firms, Media Companies, E-commerce Platforms, Financial Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing, Virtualized Networks |
| Companies Covered | AT&T, Cogent Communications, Lumen Technologies, China Telecom, Verizon, Arelion, NTT Communications, Zayo Group, GTT Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet Transit Market Strategic Shifts & Innovations
Software-defined networking and programmable optics are dissolving traditional boundaries between transport layers, enabling transit providers to commoditize what was previously custom-engineered capacity.
400G ZR and ZR+ coherent pluggable optics are collapsing the distinction between metro and long-haul transmission economics. Hyperscalers are embedding these interfaces directly into switch routers, bypassing traditional transponder shelves. This disaggregation is rendering obsolete the multi-year vendor lock-in contracts that historically structured backbone procurement.
FCC open internet rulemaking in the United States continues to shape interconnection disclosure obligations for dominant providers. The framework mandates transparency in capacity pricing and traffic management practices. Content networks operating at scale are leveraging these disclosures to negotiate settlement-free peering that displaces paid transit for an expanding share of their traffic matrix.
Buyers are consolidating procurement around multi-year volume commitments with embedded escalation clauses tied to optical interface generation transitions. This compression of switching cycles reduces provider pricing power between upgrade windows. The pattern is most pronounced among North American streaming platforms negotiating backbone capacity for 4K and emerging 8K distribution infrastructure.
Global Internet Transit Market Segmentation
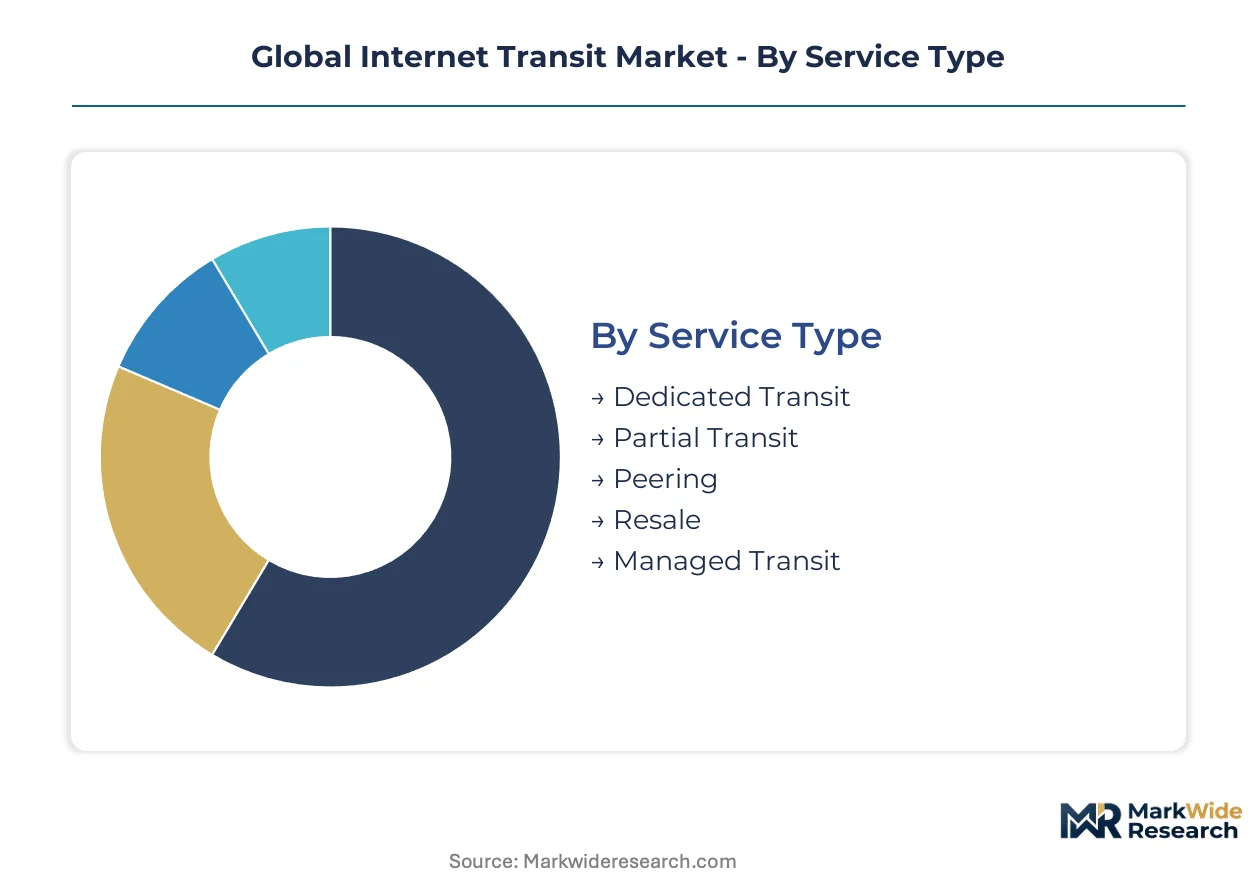
Service differentiation in internet transit determines provisioning complexity, SLA enforceability, and margin structure. Each segment category reflects distinct technical requirements and commercial negotiation patterns.
Service Type:
After-sales service intensity varies sharply across service tiers, with dedicated transit demanding 24/7 network operations center support while peering arrangements operate with minimal ongoing intervention.
- Dedicated Transit:Full-route table access with guaranteed bandwidth commitments and multi-homed path diversity. Cloud service providers in Germany and Japan anchor demand for premium SLAs as they distribute machine learning inference workloads across regions.
- Partial Transit:Limited route announcements targeting specific geographic prefixes or AS paths. Brazilian ISPs leverage partial transit to optimize costs for domestic traffic while maintaining direct peering for international destinations.
- Peering:Settlement-free interconnection at internet exchange points balanced by traffic ratio requirements. Content networks with symmetric traffic matrices displace paid transit through bilateral agreements.
- Resale:Third-party aggregation of upstream capacity with rebranded service delivery. Regional operators in tier-2 markets bundle resale transit with managed router services.
- Managed Transit:Outsourced routing policy optimization and DDoS mitigation. Financial institutions procure managed layers to satisfy operational risk frameworks without building internal BGP expertise.
Dedicated transit holds the largest share; momentum sits with managed transit as compliance burdens intensify.
Application:
Cost tier stratification separates commodity bandwidth buyers from workload-specific procurement where latency and sovereignty requirements command premium positioning.
- Content Delivery Networks:Distributed caching architectures demanding dense interconnection at internet exchange points. Streaming platforms negotiating 4K and 8K distribution infrastructure in North America drive volume commitments with embedded optical generation escalation clauses.
- Cloud Service Providers:Hyperscaler backhaul between distributed regions and local edge nodes. The EU AI Act's machine learning workload routing mandates are creating compliance-driven demand for sovereign transit paths with lawful intercept capabilities.
- Data Centers:Campus interconnect and cross-connect aggregation for multi-tenant facilities. Landing station adjacencies in Brazil, Germany, and Japan anchor regional hub economics for IP transit aggregation.
- Telecom Operators:Wholesale capacity for last-mile broadband and mobile backhaul. Mobile network operators consolidate procurement around multi-year volume commitments.
- Enterprise Connectivity:SD-WAN underlay and cloud on-ramp services. Manufacturing firms with distributed production sites procure dedicated transit for ERP system reliability.
Cloud service providers command the steepest expansion trajectory; data centers maintain structural volume leadership.
End User:
Customer type determines contract duration, payment terms, and technical support entitlements across the procurement lifecycle.
- ISPs:Multi-homed transit for residential and business broadband services. Regional providers in India leverage TRAI interconnection reforms to establish presence in tier-2 cities.
- Web Hosting Firms:Blended connectivity for shared and dedicated server offerings. Providers optimize costs through partial transit for domestic traffic and peering for international destinations.
- Media Companies:Burst-capable transit for live event streaming and content distribution. Sports broadcasters demand guaranteed bandwidth with route diversity during peak viewership windows.
- E-commerce Platforms:Low-latency paths for transaction processing and inventory synchronization. Payment gateway integration requirements drive procurement toward providers with PCI-DSS certified network operations.
- Financial Institutions:Microsecond-sensitive connectivity for trading infrastructure and regulatory reporting. The EU CSRD Scope 3 disclosure requirements are emerging as a procurement filter, rewarding providers with renewable-powered backbone footprints.
ISPs represent the largest addressable base; financial institutions are climbing the fastest on compliance-driven infrastructure refresh cycles.
Deployment:
Supply concentration in coherent DSP and transceiver foundries creates input cost volatility that propagates differently across deployment architectures.
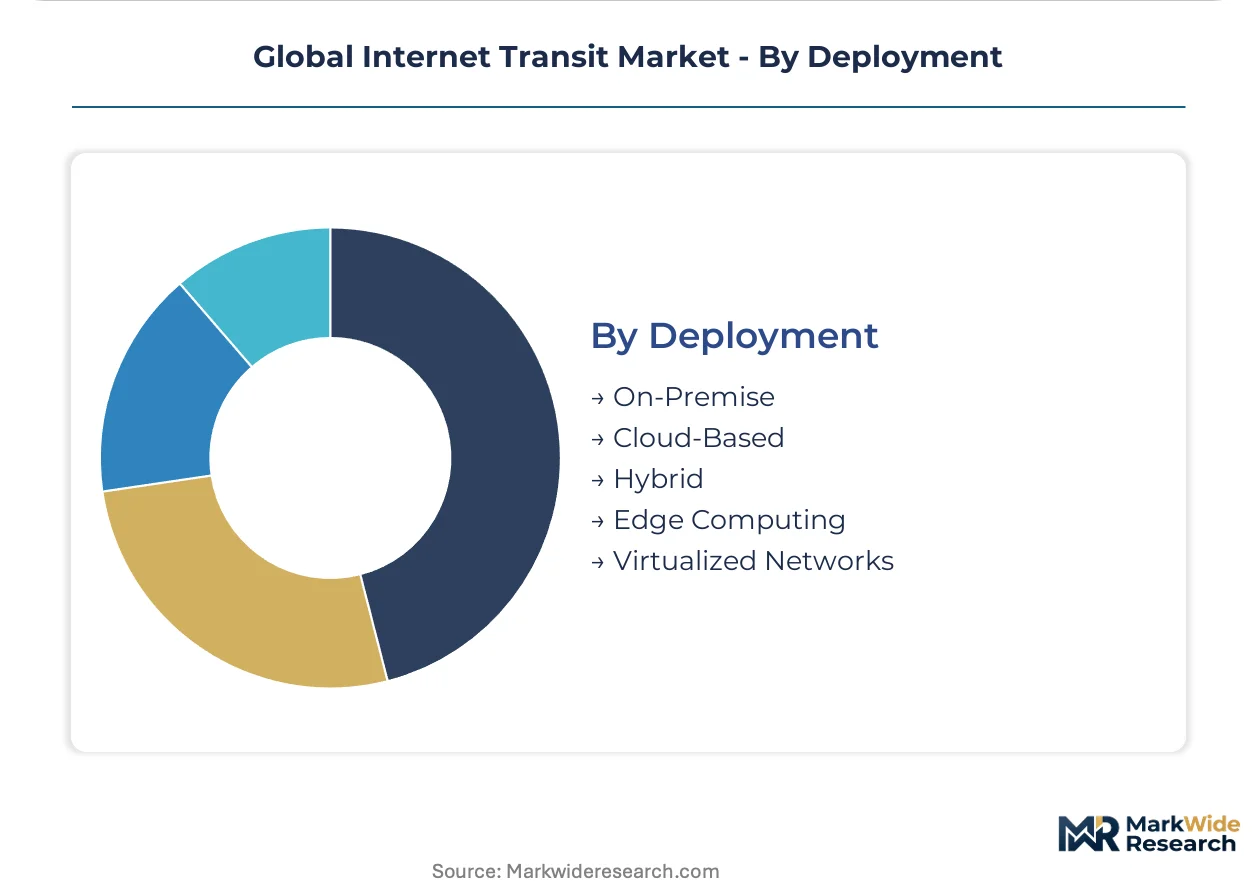
- On-Premise:Customer-operated routers and optical transport equipment with direct fiber access. Enterprises with legacy MPLS cores face multi-vendor interoperability complexity during brownfield modernization.
- Cloud-Based:Provider-managed virtual routing functions with API-driven provisioning. Hyperscalers embed 400G ZR and ZR+ coherent pluggable optics directly into switch routers, bypassing traditional transponder shelves.
- Hybrid:Split traffic engineering between owned infrastructure and outsourced capacity. Media companies balance dedicated transit for primary paths with cloud-based burst capacity for peak events.
- Edge Computing:Distributed compute nodes requiring localized interconnection at secondary metros. 800G coherent system deployment requires specialized skill sets in probabilistic constellation shaping that outpaces current training pipeline output.
- Virtualized Networks:Network function virtualization with software-defined routing policies. Disaggregated routing stacks from white-box suppliers introduce integration complexity with legacy MPLS cores.
Cloud-based deployment holds the largest share; edge computing is gaining share fastest on hyperscaler edge expansion strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports transit capacity to neighboring EU member states through dense internet exchange infrastructure at Frankfurt and Hamburg landing stations. Submarine cable investments from Brazil and Japan create triangular trade flows that reconfigure backbone routing economics across the Atlantic and Pacific corridors.
United States
FCC open internet rules mandate transparency in interconnection pricing and traffic management practices for dominant providers. Streaming platforms negotiating 4K and 8K distribution infrastructure drive multi-year volume commitments with embedded optical generation escalation clauses. Northern Virginia's data center corridor anchors hyperscaler edge expansion strategies requiring dense interconnection at secondary metros.
Germany
Cloud service providers distribute machine learning inference workloads across regions, pulling dedicated transit contracts into Frankfurt and Berlin. EU AI Act routing mandates create compliance-driven demand for sovereign transit paths with lawful intercept capabilities. DE-CIX Frankfurt operates the world's largest internet exchange by peak traffic, anchoring regional hub economics for IP transit aggregation.
Japan
Submarine cable landings at Chikura and Maruyama densify trans-Pacific and intra-Asia capacity commitments. METI spectrum coordination frameworks shape transit routing decisions for machine learning workloads requiring low-latency paths. Tokyo and Osaka internet exchanges sustain dominance through cable consortium investments and data center adjacencies.
Brazil
Regional ISPs leverage partial transit to optimize costs for domestic traffic while maintaining direct peering for international destinations. ANVISA data localization requirements intersect with MIIT cross-border assessments for routes traversing Chinese territory, adding regulatory friction. Fortaleza and Rio de Janeiro landing stations reduce latency arbitrage for South American traffic aggregation.
India
TRAI interconnection reforms to internet exchange licensing create white space for neutral transit operators in underpenetrated tier-2 cities. BIS equipment certification requirements shape where providers must site routers and authenticate peers. Mumbai and Chennai submarine cable landings anchor regional capacity expansion for hyperscaler backhaul between distributed regions and local edge nodes.
Global Internet Transit Market Key Industry Players
On the supply side, the industry is consolidating around tier-one backbone operators with wholly owned fiber infrastructure and tier-two aggregators reselling upstream capacity. Tier-one providers control last-mile costs through captive fiber while tier-two operators optimize procurement across multiple upstream relationships. Strategic archetypes include scale-driven global backbones, regional specialists with landing station adjacencies, and neutral exchange operators. Dominant competitive moves encompass submarine cable consortium investments and software-defined routing stack deployments.
Among North American infrastructure operators, AT&T, Cogent Communications, and Lumen Technologies occupy positions across the tier-one backbone archetype. Cogent Communications exemplifies the wholly owned fiber model with IPv4 and IPv6 network scale. AT&T and Lumen Technologies represent diversified infrastructure portfolios spanning transit, transport, and enterprise services. These operators anchor competitive dynamics through capacity commitment structures and interconnection pricing transparency mandated by FCC disclosure frameworks.
| Leading Market Players |
|---|
| AT&T |
| Cogent Communications |
| Lumen Technologies |
| China Telecom |
| Verizon |
| Arelion |
| NTT Communications |
| Zayo Group |
| GTT Communications |
| Others |
Cost & Logistics Intelligence
Frankfurt's internet exchange density anchors European transit pricing power through DE-CIX's peak traffic volumes, while submarine cable landing clusters in Chikura and Fortaleza compress inter-regional arbitrage windows. Optical component foundry concentration in Taiwan and South Korea feeds downstream cost volatility into backbone upgrade cycles.
Pricing Analysis
800G coherent interface pricing sits at a generational premium above 400G deployments, while 100G legacy commitments trade at commodity compression. Three-tier pricing structure across dedicated transit, partial transit, and peering levels separates SLA-guaranteed bandwidth from settlement-free exchange arrangements. Pricing pressure stems from hyperscaler volume consolidation around multi-year optical generation escalation clauses. Cloud service providers exhibit lowest price sensitivity due to compliance-driven sovereign path requirements, while regional ISPs in tier-2 markets optimize through partial transit procurement.
Supply Chain Analysis
Coherent DSP and transceiver manufacturing concentrates at Marvell, Broadcom, and Inphi foundry operations across Taiwan, South Korea, and the United States. Backbone deployment draws from indium phosphide substrates, silicon photonics wafers, and specialized cooling subsystems. Single-source vulnerability concentrates in probabilistic constellation shaping ASIC design talent pools. Distribution runs through submarine cable consortium procurement with terrestrial open line system integration at landing station facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global internet transit market sits at an inflection driven by 400G ZR pluggable optics disaggregating traditional transponder architectures. FCC disclosure mandates and EU AI Act routing requirements are reconfiguring competitive positioning around transparency and sovereign compliance capabilities.
For Market Incumbents: Entrench fiber ownership advantages through captive submarine cable consortium positions at Brazil and Japan landing stations. Deepen control over last-mile costs by expanding open line system integration at coastal aggregation points. Optical component supply volatility from Taiwan and South Korea foundries threatens margin stability without vertical integration into coherent DSP design partnerships.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 cities ahead of TRAI interconnection reform implementation. Target managed transit services for financial institutions facing EU CSRD Scope 3 disclosure requirements. Neutral exchange operator licensing in underpenetrated metros offers the most penetrable entry vector with minimal incumbent fiber ownership barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with landing station adjacencies and data center integration capabilities. Long-term viability hinges on 800G deployment readiness and software-defined routing stack ownership. Watch hyperscaler edge expansion announcements as the signal indicating capacity commitment inflection and secondary metro densification timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Consortium Investment | Fortaleza and Chikura landings anchor trans-Atlantic and trans-Pacific capacity aggregation economics. |
| 400G ZR Pluggable Optics Deployment | Hyperscalers embed coherent interfaces directly into switch routers, collapsing transponder shelf requirements. |
| Software-Defined Routing Stack Integration | Disaggregated white-box architectures bypass legacy MPLS vendor lock-in during backbone modernization. |
| Neutral Exchange Licensing Expansion | TRAI reforms in India create white space for tier-2 city presence without incumbent fiber barriers. |
| Green Transit Certification Program | EU CSRD Scope 3 requirements reward renewable-powered backbone footprints in procurement decisions. |
Research Approach
A spread of perspectives from network architects at cloud service providers, procurement leads at streaming platforms, submarine cable consortium executives, and regulatory affairs specialists at tier-one backbones converged on the working assumptions. Primary interviews combined with secondary validation through FCC interconnection disclosures, EU regulatory filings, submarine cable landing station databases, and hyperscaler capex announcements. Bottom-up capacity commitment tracking across Germany, Japan, and Brazil triangulated against top-down optical equipment spend analysis.
Demand-supply balance framing anchored the analytical approach across the analysis window, modeling service type segmentation alongside application, end user, and deployment architecture dimensions. CAGRs derived from optical interface generation transition curves and hyperscaler edge expansion trajectories. Forecast inputs incorporated submarine cable landing timelines, TRAI licensing reform implementation schedules, and coherent DSP foundry capacity constraints.
Sensitivities concentrate around China MIIT cross-border assessment timeline extensions, optical component supply disruptions from Taiwan and South Korea, and hyperscaler procurement consolidation patterns. Quarterly review of submarine cable consortium investment announcements, regulatory filing timelines, and foundry capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Intelligent Network Market
Network Technology
5G CPE Device Market
Network Technology
Global Private 5G Network Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
MENA Wireless Routers Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Digital Repeater Market
Network Technology
Mobile Network Optimization Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Low-Power WAN Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Small Cell Networks Market
Network Technology
Fiber to the Premises Market
Network Technology
2.4GHz Router Market