
 Managed MPLS Market | 2026-2036
Managed MPLS Market Size, Share, and Industry Trends Forecast 2026-2036
Managed MPLS Market Intelligence
ISO/IEC 27001 certification is collapsing as a baseline qualification for managed MPLS providers seeking enterprise contracts. AT&T leverages its fiber backbone to sustain dominance in Layer 3 VPN deployments across the United States. Orange Business Services anchors European operations with deep presence in France and extended reach into Africa. NTT Communications dominates Asia-Pacific routes through subsea cable investments and Tokyo-centric network operations.
Managed MPLS denotes a carrier-grade Wide Area Network service where a telecommunications operator owns, operates, and maintains Multiprotocol Label Switching infrastructure on behalf of enterprise clients, using label-switched paths to prioritize traffic across Layer 2 or Layer 3 virtual private networks with guaranteed quality-of-service parameters. Its primary purpose is to replace capital-intensive private leased-line networks with scalable, SLA-backed connectivity between geographically dispersed corporate sites. Layer 3 VPN remains the largest revenue pool due to its ubiquity in multinational routing, while Hybrid VPN architectures represent the fastest structural expansion as enterprises blend MPLS with direct internet breakout for cloud workloads. Deployment models show Cloud-Based managed services capturing disproportionate growth as hyperscaler interconnection requirements reshape enterprise edge strategies.
FCC net-neutrality rulings and EU GDPR data-localization mandates jointly shape how managed MPLS providers architect cross-border traffic engineering and encryption standards. The country's national telecommunications regulator in India enforces mandatory data routing through domestic MPLS nodes, constraining international carrier flexibility. Enterprise procurement teams must monitor how ISO standards, regional spectrum policy, and emerging post-quantum encryption requirements reshape vendor qualification criteria.
Market Dynamics
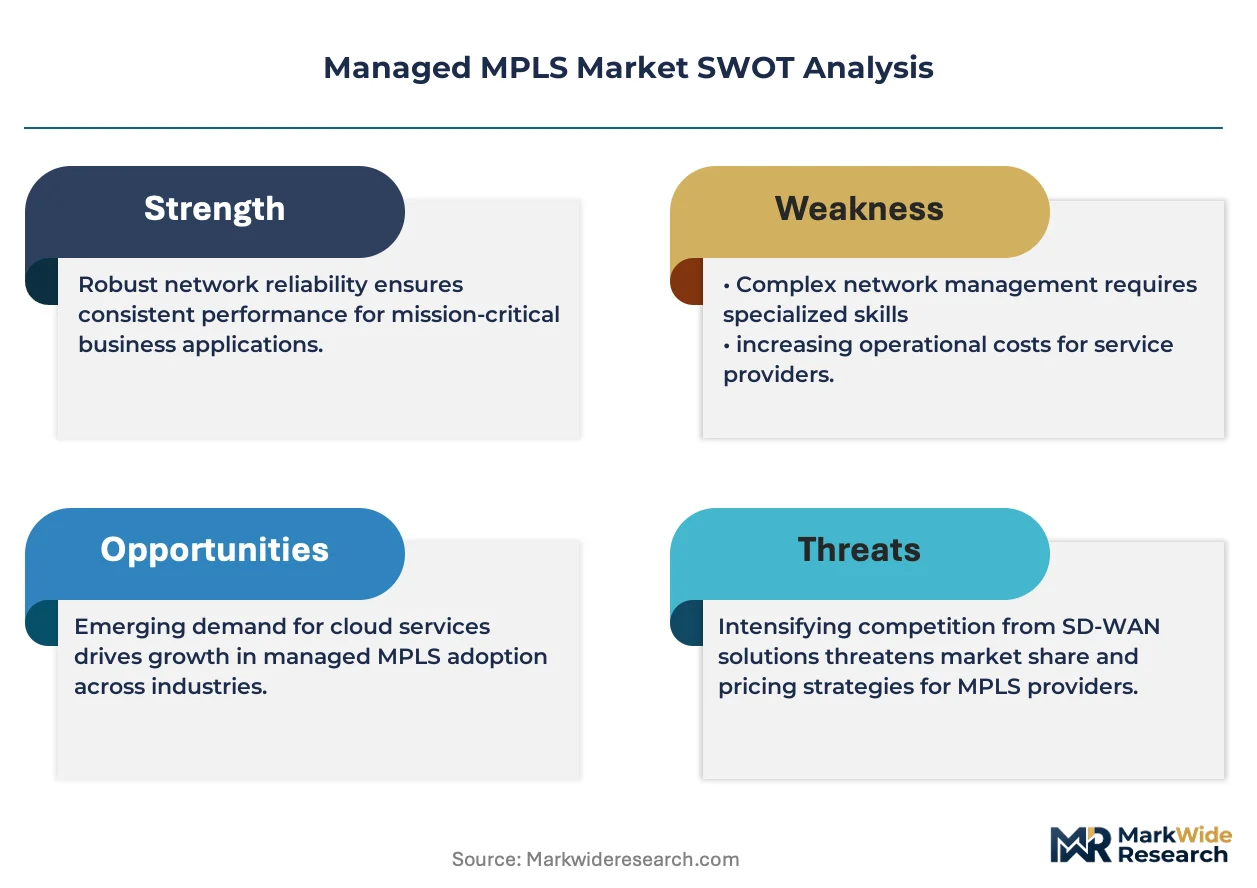
SD-WAN convergence with existing MPLS infrastructure is fragmenting procurement patterns as enterprises abandon single-carrier lock-in for hybrid architectures blending private label-switched paths with direct cloud interconnection.
Growth Catalysts
- GDPR data-localization mandates:European enterprises must route sensitive traffic through domestic MPLS nodes, compelling carrier investment in localized PoP infrastructure across Germany, France, and the Netherlands.
- Manufacturing cluster WAN modernization:German automotive and industrial equipment producers are replacing legacy frame-relay networks with SLA-backed Layer 3 VPN services to support Industry 4.0 sensor backhaul.
- Hyperscaler edge extension:AWS Direct Connect and Azure ExpressRoute integration requirements are pulling managed MPLS providers into cloud exchange facilities in Dallas, Frankfurt, and Singapore.
Market Restraints
- Subsea cable concentration risk:Asia-Pacific route diversity depends on a limited set of transpacific cable systems landing in Japan and California, creating single-point-of-failure exposure for intercontinental MPLS services.
- Optical transport cost volatility:Dense wavelength division multiplexing equipment and coherent optics module prices fluctuate with semiconductor foundry capacity constraints in Taiwan.
- 5G fixed wireless substitution:Private 5G network slicing from carriers including Verizon and Deutsche Telekom is capturing low-latency branch connectivity demand previously served by copper-access MPLS tails.
Strategic Opportunities
- India captive center expansion:TRAI-mandated domestic data routing requirements are creating greenfield demand for India-based MPLS nodes serving pharmaceutical and financial services outsourcing campuses in Bangalore and Hyderabad.
- Post-quantum encryption upgrade cycles:NIST-standardized quantum-resistant algorithms will force certificate refreshes across existing Layer 3 VPN deployments, generating professional services revenue for managed security integration.
- SD-WAN orchestration convergence:Unified management platforms combining MPLS underlay control with cloud security policy enforcement represent unclaimed white space between traditional carriers and SASE specialists.
Industry Challenges
- MPLS-IPv6 dual-stack engineering:Carrier operations teams face skill scarcity in label distribution protocol extensions for IPv6 transport, delaying enterprise migration from legacy IPv4-only VPN designs.
- ISO/IEC 27001 audit compression:Accelerated certification timelines demanded by financial services procurement teams strain provider documentation and third-party assessment capacity.
- Multivendor CPE integration friction:Enterprise branch routers from disparate suppliers require custom service interworking configurations, complicating zero-touch provisioning at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed MPLS Market |
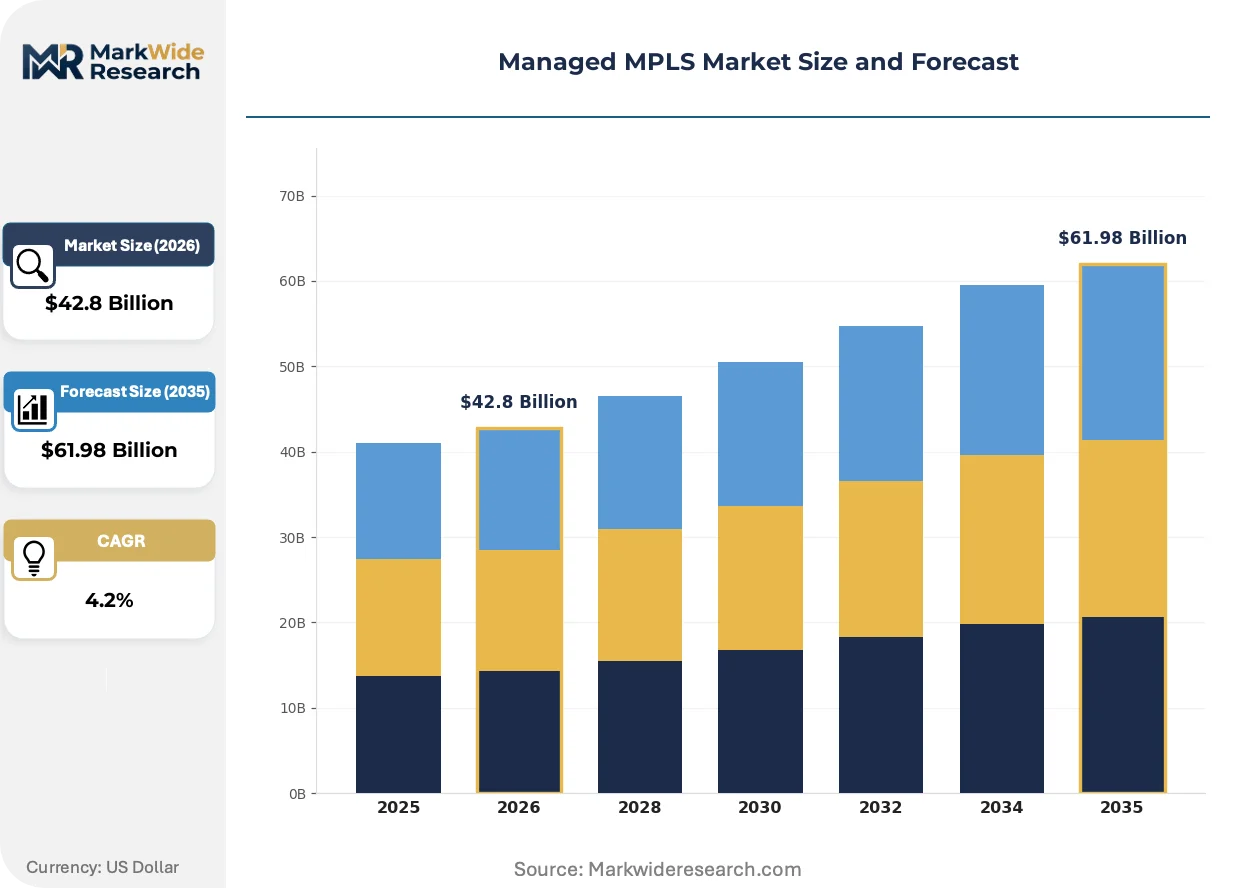
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $61.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Layer 2 VPN, Layer 3 VPN, Hybrid VPN, Managed WAN Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Enterprises, Government Agencies, Educational Institutions, Healthcare Facilities Service Type: Monitoring Services, Support Services, Optimization Services, Consulting Services |
| Companies Covered | Cogent Communications, NTT Communications, AT&T, Orange Business Services, BT Global Services, Verizon, Zayo Group, Tata Communications, Lumen Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed MPLS Market Strategic Shifts & Innovations
Artificial intelligence is penetrating traffic engineering operations, shifting provider investment from hardware-centric capacity expansion toward software-defined predictive analytics that anticipate congestion before SLA violations occur.
Segment routing with SR-MPLS data plane is bifurcating core network architectures. Tier-1 carriers deploy source-routed label stacks to simplify traffic engineering and reduce RSVP-TE state overhead in multi-terabit backbones. Financial services firms with deterministic latency requirements adopt SR-MPLS fastest, while retail and logistics segments lag in migration timelines. This protocol transition is compressing vendor differentiation around proprietary traffic engineering suites, commoditizing control-plane intelligence into open-source implementations.
EU GDPR cross-border data transfer adequacy decisions are reshaping how carriers architect transatlantic MPLS services. Providers must maintain encryption key custody within European Economic Area boundaries, forcing PoP restructuring and bilateral key escrow agreements with US landing points. German automotive manufacturers with Michigan engineering partnerships face the steepest compliance burden, driving demand for split-key management services that satisfy both EU data protection authorities and US CLOUD Act disclosure requirements.
Enterprise sourcing teams are unbundling managed WAN from managed security procurement, reversing decade-old bundled service preferences. Large pharmaceutical and professional services buyers now issue separate RFPs for transport connectivity and edge security, enabling best-of-breed vendor selection. This disaggregation is most pronounced in Switzerland and the United Kingdom, where CFO-led cost transparency initiatives demand line-item visibility into MPLS port charges distinct from firewall-as-a-service subscriptions.
Managed MPLS Market Segmentation
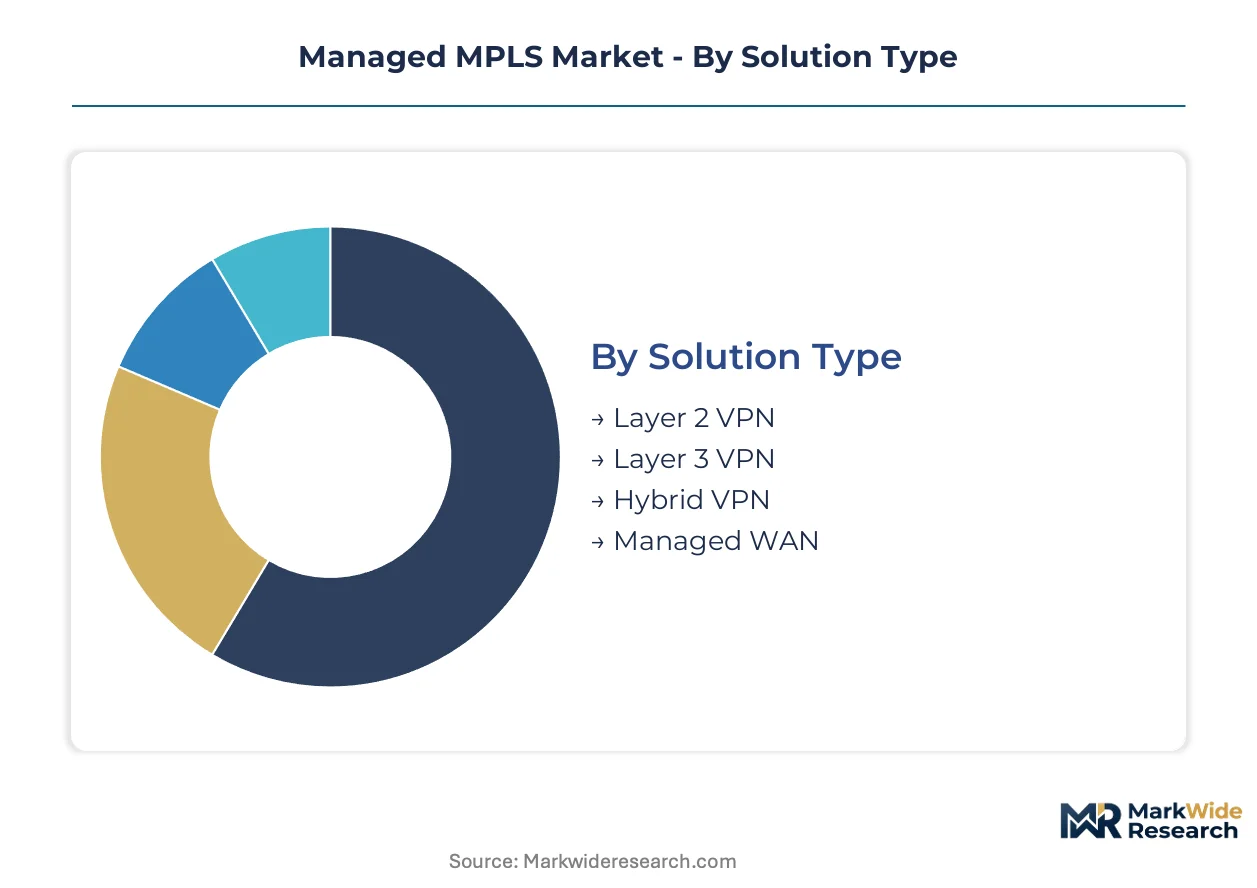
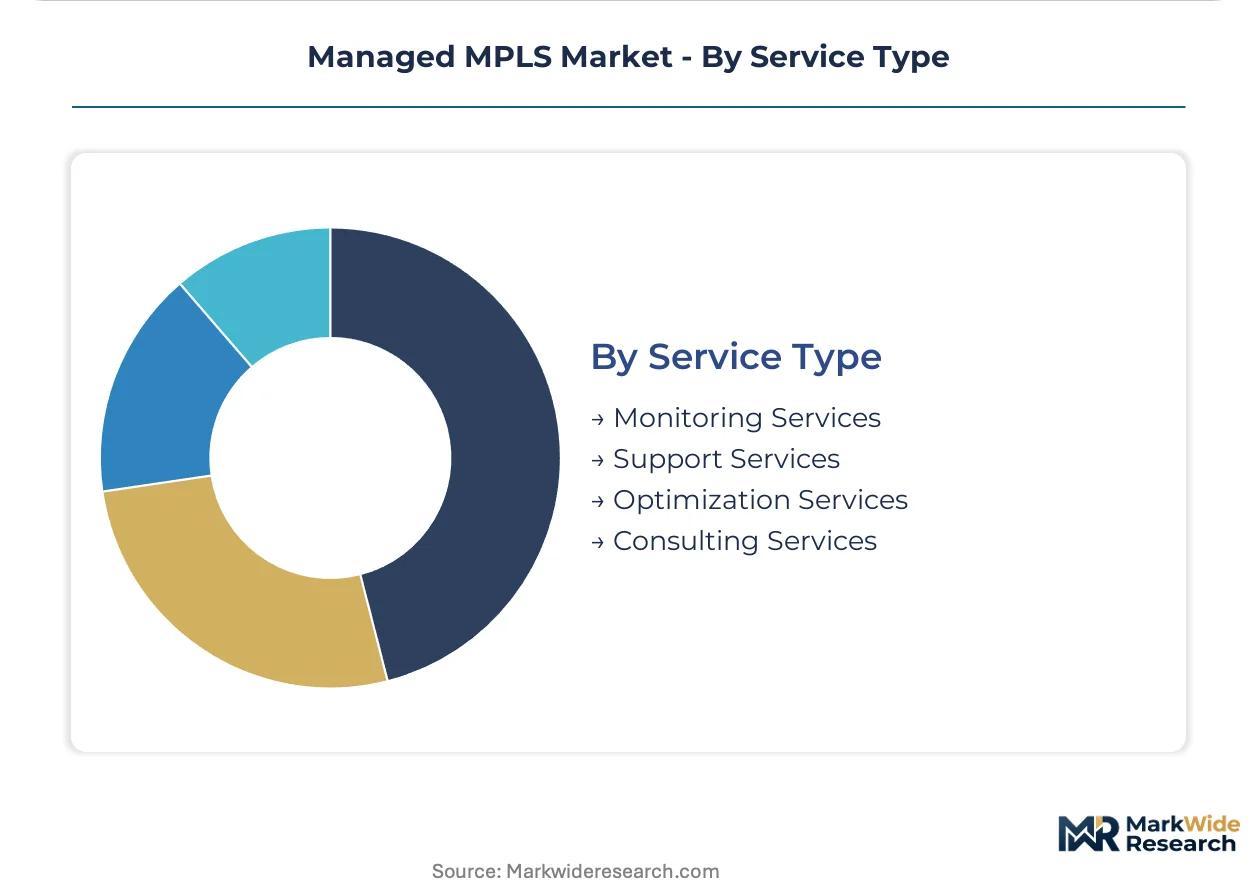
Segmentation in managed MPLS reflects how procurement teams unbundle transport, security, and operational responsibilities across divergent compliance environments. Each dimension carries distinct margin profiles and vendor qualification thresholds that reshape competitive positioning.
Solution Type:
GDPR cross-border adequacy rulings and India's TRAI-mandated domestic routing requirements force carriers to engineer solution-specific encryption architectures and PoP placement strategies.
- Layer 3 VPN:Multiprotocol BGP-based routing with MPLS label distribution protocol enables any-to-any connectivity across distributed enterprise sites. Financial services firms in Frankfurt and Singapore concentrate procurement here for deterministic latency between trading floors and disaster recovery sites. Regulatory pressure from EU data-localization mandates compels carriers to maintain European Economic Area key custody.
- Hybrid VPN:Architectures blend MPLS underlay with direct internet breakout for cloud workloads, requiring split-tunnel policy enforcement at branch CPE. German automotive manufacturers upgrading Industry 4.0 sensor backhaul drive fastest adoption as they reconcile legacy frame-relay reliability requirements with AWS Direct Connect cost economics.
- Layer 2 VPN:Point-to-point pseudowire services transport Ethernet frames across carrier backbones with transparent LAN extension.
- Managed WAN:Comprehensive outsourcing of routing, switching, and last-mile aggregation to carrier operations centers.
Layer 3 VPN handles the majority of throughput; Hybrid VPN is expanding most quickly on share as cloud interconnection requirements reshape procurement.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises CPE investments from operational expenditure models favored by CFO-led transparency initiatives in Switzerland and the United Kingdom.
- Cloud-Based:Provider-hosted control planes and virtualized network functions eliminate branch hardware dependencies. Hyperscaler edge extension requirements in Dallas, Frankfurt, and Singapore pull carriers into cloud exchange facilities, with enterprise procurement teams prioritizing opex predictability over ownership.
- Hybrid:Mixed estate combining retained on-premises gateways with cloud-orchestrated policy management. Financial services and pharmaceutical buyers issue separate RFPs for transport and security, enabling best-of-breed selection across this deployment mode.
- On-Premises:Dedicated physical CPE at each enterprise site with customer-managed power and space.
- Managed Service:Full operational handover including spares management, firmware updates, and field technician dispatch.
Cloud-Based deployment climbs the fastest on share; On-Premises retains the largest installed base among regulated industries with legacy audit requirements.
End User:
Application-specific latency and encryption requirements segment procurement authority across verticals with divergent compliance postures toward ISO/IEC 27001 and post-quantum readiness.
- Enterprises:Multinational corporations with 50-plus sites dominate contract value, unbundling WAN and security procurement to optimize line-item visibility. Manufacturing cluster WAN modernization in Germany and captive center expansion in Bangalore and Hyderabad concentrate demand.
- Government Agencies:Classified network requirements and domestic-only routing mandates constrain vendor pools to carriers with cleared personnel and sovereign infrastructure.
- Healthcare Facilities:HIPAA and GDPR dual compliance forces encryption key segmentation between clinical and administrative data flows.
- Educational Institutions:Research network federations and campus consolidation drive procurement through shared services organizations.
Enterprises command the dominant contract value; Government Agencies impose the steepest qualification barriers on vendor participation.
Service Type:
Customer maturity and internal IT capability gaps determine willingness to purchase professional services versus self-managed tooling subscriptions.
- Optimization Services:Traffic engineering analytics and capacity planning engagements leverage AI-driven predictive models to anticipate congestion. Tier-1 carriers deploy source-routed label stacks with SR-MPLS, commoditizing proprietary control-plane intelligence into software-defined implementations.
- Support Services:Tiered response commitments with mean-time-to-repair guarantees backed by geographic redundancy of technical staff.
- Monitoring Services:Real-time SLA dashboards and proactive alerting on latency, jitter, and packet loss thresholds.
- Consulting Services:Migration planning from legacy frame-relay or IPv4-only designs to dual-stack MPLS-IPv6 architectures.
Optimization Services generate the highest margin expansion; Support Services constitute the largest revenue pool by contract attachment rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services procurement teams in Frankfurt, Singapore, and New York Metro drive contract concentration for SLA-backed Layer 3 VPN services. Manufacturing clusters in Germany and captive center expansions in India reshape demand geography. Regulatory fragmentation across data-localization mandates forces carriers to restructure PoP placement and encryption custody.
United States
FCC net-neutrality rulings shape cross-border traffic engineering architectures for multinational enterprises. Financial services firms in New York Metro and Chicago concentrate procurement of deterministic latency circuits between trading floors and disaster recovery sites. Dallas and Ashburn host cloud exchange facilities where AWS Direct Connect and Azure ExpressRoute integration pulls carriers into hyperscaler edge extension strategies.
Germany
GDPR data-localization mandates compel carriers to maintain European Economic Area encryption key custody for sensitive traffic routing. German automotive and industrial equipment producers in Bavaria and Baden-Württemberg replace legacy frame-relay networks with Industry 4.0 sensor backhaul over SLA-backed Layer 3 VPN. Frankfurt anchors continental PoP infrastructure investment due to its central role in transatlantic and intra-European fiber routes.
India
TRAI-mandated domestic data routing requirements constrain international carrier flexibility and create greenfield demand for India-based MPLS nodes. Pharmaceutical and financial services outsourcing campuses in Bangalore and Hyderabad drive captive center expansion. Mumbai and Chennai concentrate submarine cable landing capacity, shaping intercontinental route diversity for Asia-Pacific traffic.
Singapore
Hyperscaler edge extension requirements pull managed MPLS providers into cloud exchange facilities serving Southeast Asian enterprise demand. Subsea cable investments from NTT Communications and Tata Communications anchor regional route diversity through Tokyo-centric and Mumbai-centric network operations. The city-state's data center concentration supports split-tunnel policy enforcement for hybrid VPN architectures blending MPLS underlay with direct cloud breakout.
United Kingdom
CFO-led cost transparency initiatives in London and the Southeast drive unbundling of managed WAN from managed security procurement. Separate RFPs for transport connectivity and edge security enable best-of-breed vendor selection among professional services and pharmaceutical buyers. Post-Brexit data adequacy negotiations with the EU reshape cross-border encryption standards for firms with continental operations.
Managed MPLS Market Key Industry Players
Player mix skews toward tier-1 telecommunications incumbents with fiber backbone ownership and cloud exchange presence. Market structure concentrates around carriers with subsea cable investments and sovereign infrastructure footprints. Strategic archetypes include fiber-rich Layer 3 VPN specialists, SD-WAN orchestration convergers, and regional cloud interconnection facilitators. Competitive moves center on hyperscaler partnership expansion and post-quantum encryption upgrade service packaging.
Within the fiber backbone tier, AT&T leverages its United States infrastructure to sustain dominance in domestic Layer 3 VPN deployments. Orange Business Services anchors European operations with deep presence in France and extended reach into Africa. NTT Communications dominates Asia-Pacific routes through Tokyo-centric network operations and transpacific cable investments. These three exemplify how carrier-grade infrastructure ownership shapes competitive positioning in SLA-backed enterprise connectivity.
| Leading Market Players |
|---|
| Cogent Communications |
| NTT Communications |
| AT&T |
| Orange Business Services |
| BT Global Services |
| Verizon |
| Zayo Group |
| Tata Communications |
| Lumen Technologies |
| Others |
Cost & Logistics Intelligence
Ninety-day optical transceiver lead times concentrate pricing power with Taiwan-based coherent optics suppliers, forcing carriers to pre-position DWDM inventory ahead of semiconductor foundry capacity cycles. This inventory positioning cascades into contract structures where enterprise buyers absorb cost volatility through indexed port charges.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate managed MPLS procurement, tying monthly recurring charges to coherent optics module costs. Price differentiation separates SLA-backed Layer 3 VPN with deterministic latency guarantees from best-effort internet breakout tiers. Cost compression in cloud-based deployment models intensifies as hyperscaler interconnection commoditizes edge port economics. Mid-market pharmaceutical buyers exhibit highest price sensitivity, while financial services trading floors prioritize latency certainty over unit cost.
Supply Chain Analysis
Port congestion on transpacific routes from Shanghai to Long Beach elevates inbound logistics costs for CPE shipments bound for North American enterprise branches. Supply concentrates in Taiwan for coherent optics, Japan for submarine cable landing equipment, and Germany for industrial-grade routing hardware. Dense wavelength division multiplexing modules and MPLS-enabled branch routers constitute critical component dependencies. Single-source vulnerability in Taiwan semiconductor foundries threatens carrier capacity expansion timelines. Distribution runs through carrier-direct channels with field technician deployment for last-mile installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed MPLS demand follows capital expenditure cycles in financial services and manufacturing, with current recovery signals emerging from German automotive WAN modernization programs and India captive center buildouts.
For Market Incumbents: Secure fiber backbone densification in Frankfurt and Dallas cloud exchange corridors before SD-WAN specialists capture orchestration layer margins. Defend Layer 3 VPN pricing power through ISO/IEC 27001 certification acceleration that disqualifies mid-tier competitors from financial services procurement. Vertical integration into submarine cable consortiums reduces transpacific route concentration risk. For New Entrants and Emerging Players: Anchor in India-based MPLS node deployment serving TRAI-mandated domestic routing requirements for pharmaceutical outsourcing campuses in Bangalore. Target hybrid VPN orchestration white space between traditional carriers and SASE specialists, emphasizing unified policy management platforms. Lead with professional services packaging around post-quantum encryption migration to differentiate from commodity transport offerings. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure yield play because recurring revenue streams from SLA-backed contracts exhibit low churn amid enterprise cloud migration tailwinds. Acquisition targets should display dense PoP footprints in GDPR-constrained European markets with established key custody protocols. Monitor NIST post-quantum algorithm standardization timelines as inflection indicator for professional services revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Edge Extension | AWS Direct Connect integration in Frankfurt and Singapore cloud exchanges captures cloud-bound enterprise traffic. |
| Post-Quantum Encryption Upgrade | NIST-standardized algorithm deployment generates professional services revenue across existing Layer 3 VPN installations. |
| Submarine Cable Consortium Participation | Transpacific route diversity through Tokyo-centric investments reduces single-point-of-failure exposure for Asia-Pacific services. |
| SD-WAN Orchestration Convergence | Unified management platforms combining MPLS underlay with cloud security policy enforcement address unclaimed white space. |
| India Captive Center Infrastructure | TRAI-mandated domestic routing requirements create greenfield PoP demand for pharmaceutical and financial services campuses. |
Research Approach
Findings reconcile primary fieldwork against secondary review of carrier tariff filings, FCC infrastructure reports, and hyperscaler capex disclosures to validate MPLS port pricing trajectories and cloud exchange expansion timelines. Primary interviews engaged network engineering directors at tier-1 telecommunications carriers, enterprise procurement managers at financial services and pharmaceutical firms, and regulatory affairs specialists at TRAI and BNetzA. Secondary validation drew from submarine cable consortium announcements, ISO certification registries, and ITU-T standards documentation. Bottom-up enterprise site counts triangulate against top-down carrier revenue segmentation.
Segmentation dimensions modeled include solution type (Layer 3 VPN, Hybrid VPN, Layer 2 VPN, Managed WAN), deployment model (Cloud-Based, Hybrid, On-Premises, Managed Service), end user vertical (Enterprises, Government Agencies, Healthcare Facilities, Educational Institutions), and service type (Optimization, Support, Monitoring, Consulting). CAGRs derive from enterprise site growth projections, cloud interconnection attach rates, and carrier pricing elasticity assumptions across the analysis window. Industry-specific inputs incorporate GDPR adequacy ruling timelines, TRAI domestic routing enforcement patterns, and NIST post-quantum standardization schedules.
Material uncertainties — regulatory enforcement intensity in India and EU, semiconductor foundry capacity allocation, and submarine cable system outages — sit outside the modeled envelope. Forecasts reflect assumptions regarding enterprise cloud migration velocity and SD-WAN substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Optical Networking Market
Network Technology
Global Network Probe Market
Network Technology
Europe SD-WAN Market
Network Technology
Global Internet Transit Market
Network Technology
Global LWAN Market
Network Technology
Residential Routers Market
Network Technology
GCC Set-Top Box Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Global Network Switches Market
Network Technology
Radio Modem Market
Network Technology
Industrial Ethernet Market
Network Technology
Mobile Accelerator Market
Network Technology
Netops Market
Network Technology
Protocol Analyzer Market
Network Technology
Internet Protocol Address Management (IPAM) Market