
 Cellular Modem Market | 2026-2036
Cellular Modem Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Modem Market Analysis
Subscription-based firmware management is consolidating around recurring revenue models in the cellular modem supply chain. Qualcomm Technologies leverages its Snapdragon modem-RF system to sustain technology leadership across premium tier designs. Quectel Wireless Solutions anchors volume production for industrial IoT applications with aggressive module cost positioning. MediaTek competes aggressively in mid-tier smartphone and tablet modem integration.
A cellular modem is a hardware component that encodes and decodes radio signals between a device and a cellular base station, typically supporting multiple frequency bands and modulation schemes such as 256-QAM for LTE Advanced or 256-element beamforming arrays in 5G NR millimeter wave implementations. Its primary purpose is to enable wireless wide area network connectivity for endpoints ranging from smartphones to industrial sensors and autonomous vehicles. 5G NR modules command premium positioning due to complex RF front-end requirements and carrier certification burdens, while Narrowband IoT segments serve ultra-low-power metering and tracking applications with minimal data throughput. Sub-6 GHz technology dominates current deployment economics because it balances coverage and equipment cost, though millimeter wave specialization is deepening for dense urban fixed wireless access.
The FCC governs spectrum licensing and device authorization for cellular modems in the United States, while ETSI and national regulators across European Union member states enforce CE marking and RED compliance for radio equipment market access. China's MIIT administers network access licenses and type approval for modules operating on domestic carrier networks, directly shaping which vendors participate in procurement cycles. Stakeholders must monitor evolving national security review frameworks for telecommunications components, as these determine supplier eligibility and design-in windows across major economies.
Market Dynamics
Automotive OEMs are mandating embedded cellular connectivity as a standard feature, forcing module suppliers to reconfigure certification pipelines and RF architectures around C-V2X and 5G NR specifications simultaneously.
Growth Catalysts
- China MIIT network access licenses:Domestic procurement cycles favor local module vendors for massive industrial IoT rollouts across smart manufacturing and utility metering infrastructure.
- Connected vehicle mandates:Automotive OEMs embed cellular modems for over-the-air updates, telematics, and autonomous driving data pipelines.
- Narrowband IoT spectrum allocation:Ultra-low-power modulation schemes enable decade-long battery life for agricultural sensors and asset tracking endpoints.
Market Restraints
- Millimeter wave RF front-end costs:256-element beamforming arrays and phased antenna modules require gallium nitride components that concentrate among a handful of compound semiconductor foundries.
- FCC certification timelines:Device authorization procedures for new frequency bands create six-to-twelve month gaps between silicon sampling and commercial shipment.
- Sub-6 GHz spectrum congestion:Limited contiguous bandwidth in mid-band allocations constrains peak throughput for fixed wireless access deployments.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing attract module assembly investments serving domestic smart factory and agricultural drone demand.
- Private 5G network integration:Mining operations and port logistics operators deploy campus-wide cellular infrastructure independent of public carrier infrastructure.
- Subscription firmware management:Recurring revenue models replace one-time hardware sales through continuous security patching and feature activation services.
Industry Challenges
- RF systems integration talent:Scarce expertise in antenna-tuner co-design and carrier aggregation optimization extends product development cycles.
- Legacy 4G LTE coexistence:Dual-mode modem architectures must maintain backward compatibility while minimizing power and board area penalties.
- Multi-carrier certification complexity:Operator-specific test suites for Verizon, AT&T, T-Mobile, and regional carriers multiply validation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Modem Market |
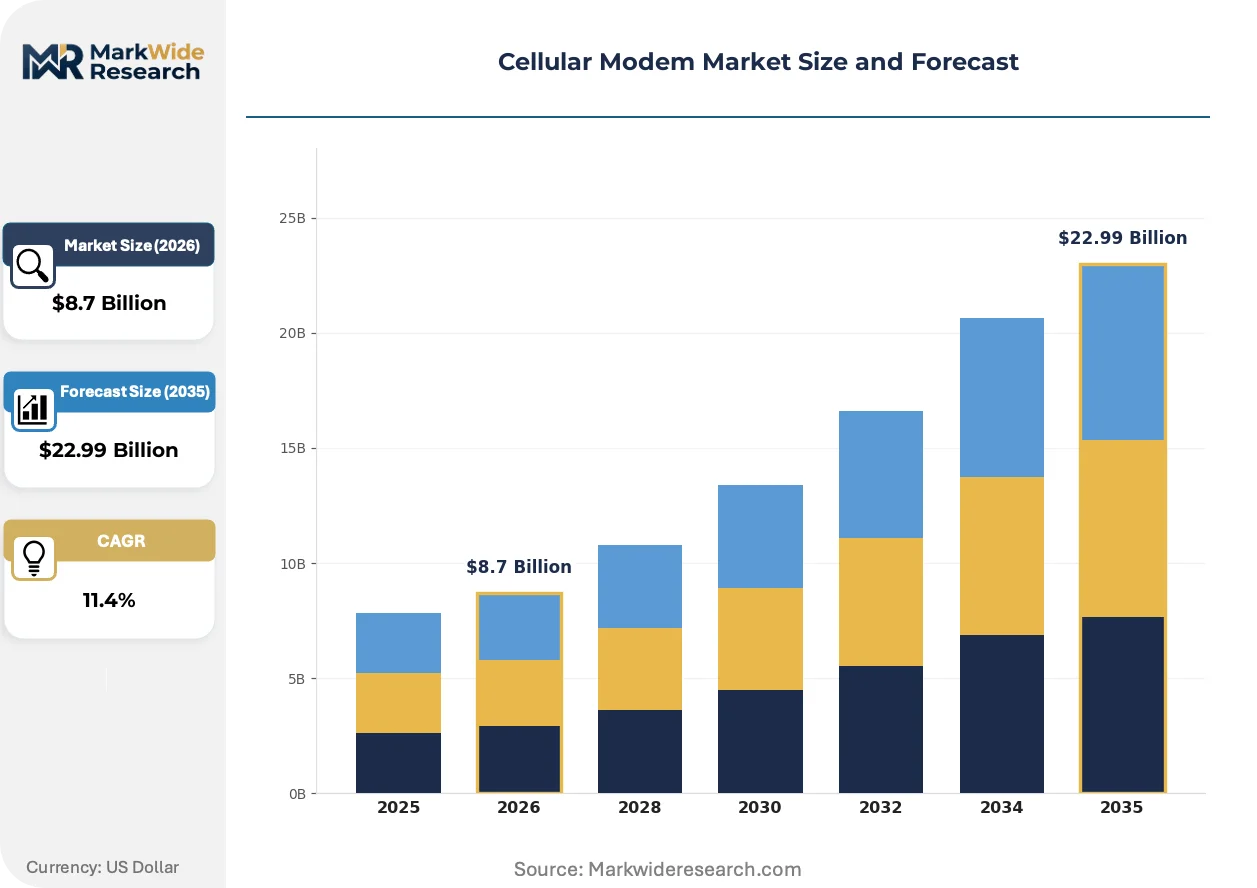
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4G LTE, 5G NR, HSPA+, CDMA2000 Technology: Millimeter Wave, Sub-6 GHz, Narrowband IoT, LTE Advanced End User: Telecom Operators, Enterprises, IoT Devices, Automotive Connectivity: Wired, Wireless, Satellite, Hybrid |
| Companies Covered | Huawei Device Co., Ltd., Quectel Wireless Solutions, Qualcomm Technologies, Inc., NETGEAR, Fibocom Wireless Inc., Digi International Inc., MediaTek Inc., Advantech Co., Ltd., Sierra Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Modem Market Emerging Trajectories
Open-source baseband software stacks are eroding proprietary modem firmware advantages, enabling tier-two manufacturers to customize protocol implementations without Qualcomm or MediaTek licensing dependencies.
Software-defined radio architectures are decentralizing baseband processing from dedicated DSP silicon to heterogeneous compute fabrics combining CPU, GPU, and AI accelerator cores. Automotive Tier-1 suppliers adopt these flexible platforms to consolidate infotainment and telematics domains onto single SoC implementations. This consolidation is compressing bill-of-materials counts and reducing thermal management complexity in engine-compartment installations.
The FCC's refreshed C-V2X spectrum rules in the 5.9 GHz band are accelerating direct vehicle-to-vehicle communication deployments independent of cellular network coverage. Automakers must now support dual-radio configurations combining DSRC heritage with cellular-V2X futures. European regulators under ETSI are harmonizing their framework, creating transatlantic certification reciprocity pressure.
Fleet operators now specify modems through outcome-based connectivity contracts rather than hardware procurement, paying per-vehicle per-month for guaranteed uptime and data throughput. This displaces traditional distribution through electronics distributors and value-added resellers. German automotive logistics providers pioneered this shift, with North American trucking fleets now adopting similar structures.
Cellular Modem Market Segmentation
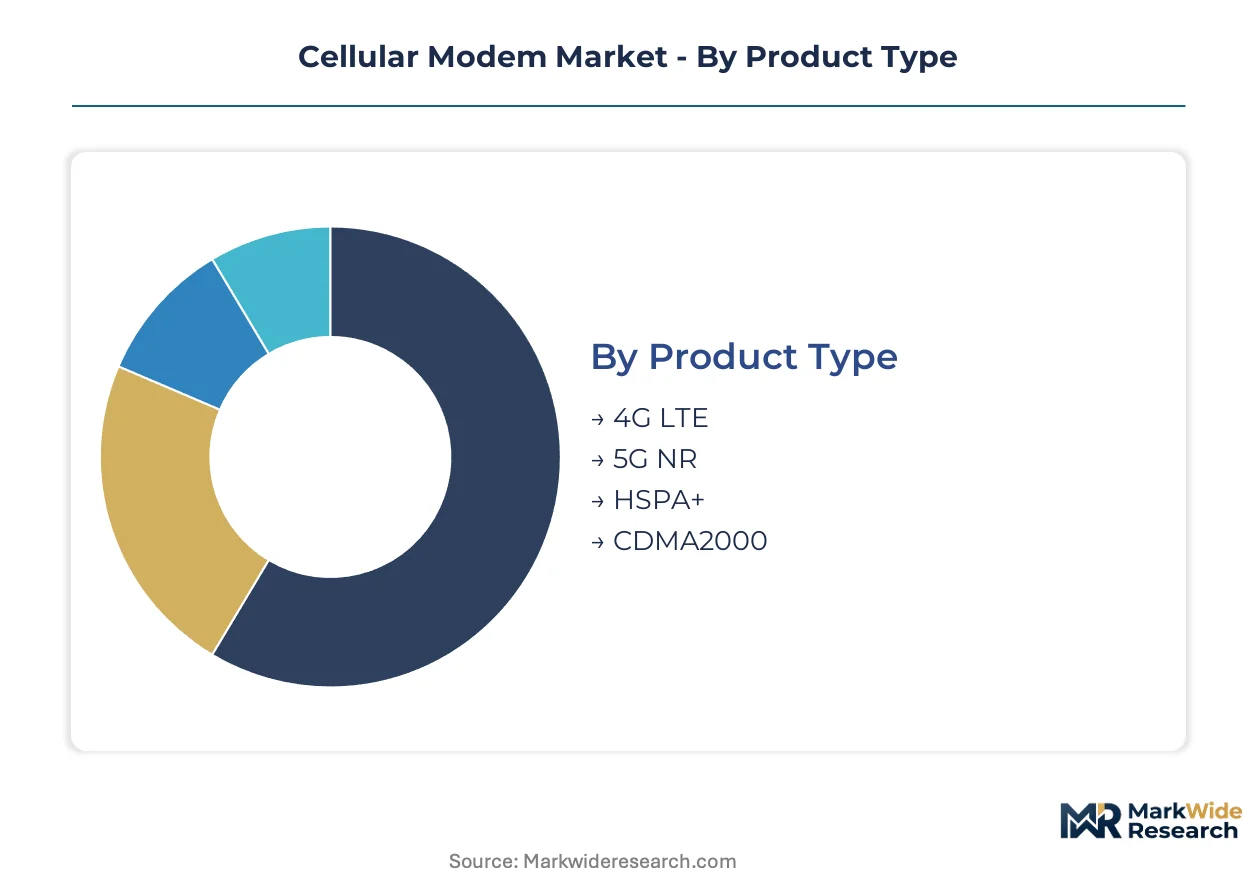
Cellular modem segmentation reveals how technology tiers map to divergent margin structures and certification burdens. Product type and technology categories separate volume-driven commodity supply from premium RF complexity, while end user and connectivity dimensions expose where procurement power concentrates.
Product Type:
Volume shipments cluster in legacy standards with mature certification pipelines, while 5G NR commands premium positioning through RF front-end complexity and carrier aggregation requirements.
- 5G NR:Supports millimeter wave beamforming arrays and massive MIMO configurations with 256-element antenna systems. Telecom operators in China and automotive OEMs in Germany drive procurement for fixed wireless access and connected vehicle platforms, though gallium nitride component shortages constrain supply.
- 4G LTE:Dominates current shipment volumes with established carrier certification libraries and backward-compatible modem architectures. Industrial IoT deployments across India's smart metering infrastructure and Brazil's agricultural sensor networks sustain demand despite spectrum congestion in sub-6 GHz allocations.
- HSPA+:Serves legacy machine-to-machine installations in remote monitoring and point-of-sale terminals where bandwidth requirements remain minimal.
- CDMA2000:Persists in specialized defense and maritime applications requiring proprietary waveform security profiles.
Today's leader: 4G LTE. Tomorrow's challenger: 5G NR.
Technology:
Deployment economics split between coverage-optimized sub-6 GHz infrastructure and capacity-focused millimeter wave specialization.
- Sub-6 GHz:Balances propagation range with equipment cost, enabling broad geographic coverage without dense small cell deployment. China's MIIT prioritizes mid-band allocations for nationwide 5G rollout, while India's TRAI auctions concentrate in this spectrum for rural connectivity expansion.
- Millimeter Wave:Delivers multi-gigabit throughput through phased antenna arrays for dense urban fixed wireless access. Verizon and AT&T deployment timelines in the United States shape vendor R&D prioritization, though FCC certification delays extend commercialization cycles.
- Narrowband IoT:Ultra-low-power modulation extends battery life beyond a decade for utility metering and livestock tracking endpoints.
- LTE Advanced:Carrier aggregation and 256-QAM modulation support peak throughput demands in mature 4G networks before 5G migration.
Sub-6 GHz captures current infrastructure investment. Millimeter Wave climbs the fastest as urban density intensifies.
End User:
Procurement patterns diverge between carrier-managed connectivity and enterprise-directed private network deployments.
- Telecom Operators:Specify modems through centralized procurement with stringent interoperability testing and multi-vendor sourcing mandates. China's three state-owned carriers dominate global module consumption through MIIT-coordinated network access licenses.
- Automotive:Mandates embedded cellular for over-the-air software updates and C-V2X direct communication, forcing dual-radio architectures that combine 5G NR with dedicated short-range communication heritage.
- Enterprises:Deploy private 5G networks for mining operations and port logistics independent of public carrier infrastructure.
- IoT Devices:Agricultural sensors and asset trackers prioritize power efficiency and minimal bill-of-materials over peak throughput.
Telecom operators anchor procurement volume today. Automotive specifications reshape RF architecture requirements fastest.
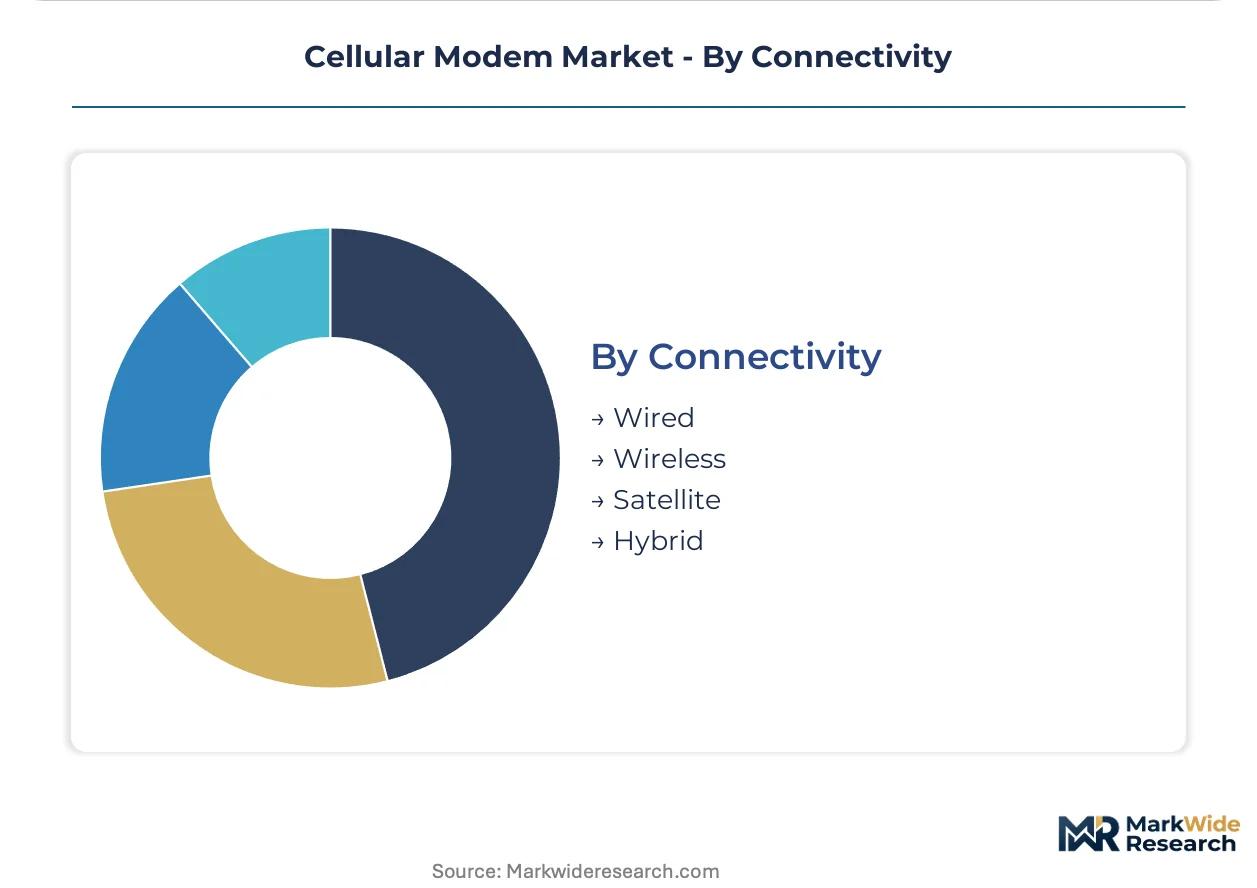
Connectivity:
Physical layer diversity determines failover resilience and deployment flexibility across geographic and regulatory contexts.
- Wireless:Cellular modems integrate with Wi-Fi 6E and Bluetooth Low Energy for local offloading and peripheral pairing in smartphones and industrial gateways.
- Wired:Ethernet and fiber backhaul complement cellular in hybrid enterprise installations requiring guaranteed throughput.
- Satellite:L-band and Ku-band modems extend coverage to maritime and remote terrestrial applications beyond cellular footprint.
- Hybrid:Combines multiple transport layers with intelligent traffic steering for mission-critical applications in emergency response and defense.
Wireless dominates endpoint attachment today. Hybrid configurations gain share fastest where connectivity continuity commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands procurement volume through MIIT-coordinated network access licenses, while Germany's automotive OEMs reshape RF architecture requirements for C-V2X deployment.
China
Domestic module vendors serve massive industrial IoT rollouts across smart manufacturing and utility metering infrastructure. MIIT administers network access licenses and type approval for modules operating on domestic carrier networks, directly shaping supplier eligibility in procurement cycles. Shenzhen and Shanghai host concentrated module assembly operations feeding both domestic consumption and export markets.
Germany
Automotive OEMs mandate embedded cellular connectivity as standard equipment for over-the-air updates and autonomous driving data pipelines. ETSI harmonizes C-V2X frameworks with FCC rules, creating transatlantic certification reciprocity pressure. Stuttgart and Munich anchor Tier-1 supplier clusters developing dual-radio configurations combining 5G NR with dedicated short-range communication heritage.
United States
Verizon and AT&T deployment timelines in millimeter wave fixed wireless access shape vendor R&D prioritization, though FCC certification delays extend commercialization cycles. The FCC governs spectrum licensing and device authorization for cellular modems, with refreshed C-V2X rules in the 5.9 GHz band accelerating direct vehicle-to-vehicle communication. San Diego and Austin concentrate modem-RF system design centers serving premium tier smartphone and automotive platforms.
India
PLI scheme incentives for electronics manufacturing attract module assembly investments serving domestic smart factory and agricultural drone demand. TRAI auctions concentrate in sub-6 GHz spectrum for rural connectivity expansion. Karnataka and Telangana host emerging design centers supporting industrial automation and private 5G network integration for mining operations.
Japan
METI prioritizes private 5G network deployment for port logistics and manufacturing campus applications independent of public carrier infrastructure. JIS standards govern radio equipment interoperability testing for industrial IoT endpoints. Tokyo and Osaka metropolitan areas concentrate system integrators developing hybrid connectivity configurations combining cellular with local offloading protocols.
Cellular Modem Market Vendor Landscape
Top-tier vendors anchor premium-tier modem-RF system design, while mid-tier specialists compete on aggressive module cost positioning for industrial IoT volume. The supply base organizes around three strategic archetypes: integrated semiconductor designers with captive baseband silicon, pure-play module assemblers with certification scale, and automotive-focused Tier-1 suppliers with embedded connectivity mandates. Dominant competitive moves include backward integration into compound semiconductor foundry capacity and geographic expansion through PLI-scheme assembly investments.
Within the integrated semiconductor tier, Qualcomm Technologies, Inc. and MediaTek Inc. exemplify contrasting approaches to premium and mid-tier market segmentation. Among module-focused vendors, Quectel Wireless Solutions and Fibocom Wireless Inc. occupy positions shaped by volume production economics and certification pipeline depth. Huawei Device Co., Ltd. represents a vertically integrated archetype spanning silicon through system-level implementation.
| Leading Market Players |
|---|
| Huawei Device Co., Ltd. |
| Quectel Wireless Solutions |
| Qualcomm Technologies, Inc. |
| NETGEAR |
| Fibocom Wireless Inc. |
| Digi International Inc. |
| MediaTek Inc. |
| Advantech Co., Ltd. |
| Sierra Wireless |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China's cellular module sector anchor supply discipline through MIIT-coordinated procurement, translating state-directed volume guarantees into pricing power that resists commoditization pressure. Their captive access to domestic gallium nitride foundry capacity insulates cost structures from compound semiconductor shortages that plague tier-two competitors.
Pricing Analysis
Capacity additions in India under PLI scheme incentives are reshaping price floors for mid-tier 4G LTE modules, compressing margins for legacy Chinese assemblers serving industrial IoT volume. Three-tier pricing structure across premium, standard, and economy levels separates 5G NR millimeter wave designs with gallium nitride RF front-ends from sub-6 GHz utility modems and narrowband IoT metering endpoints. Pricing pressure stems from aggressive module cost positioning by domestic Chinese vendors in massive smart manufacturing rollouts. Agricultural sensor deployers exhibit highest price sensitivity, while automotive OEMs absorb premium positioning for C-V2X-certified dual-radio architectures.
Supply Chain Analysis
Refurbishment flows for legacy 4G LTE modules extend service life in remote monitoring installations, creating secondary supply channels that compete with new production in price-sensitive segments. Manufacturing concentrates in China, Taiwan, and Vietnam, with Shenzhen and Shanghai anchoring module assembly and Taipei housing RF front-end design centers. Supply chains draw from gallium nitride wafers, ceramic antenna substrates, and baseband silicon. Single-source vulnerability in compound semiconductor foundry capacity poses structural risk. Distribution runs through carrier-direct procurement for telecom operators and outcome-based connectivity contracts displacing traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellular modem market functions as a stable compounder, with embedded connectivity mandates in automotive and industrial IoT creating recurring demand visibility across technology transition cycles.
For Market Incumbents: Hedge exposure to millimeter wave RF front-end shortages through backward integration into gallium nitride foundry partnerships or long-term offtake agreements with compound semiconductor specialists. Defend certification pipeline depth against emerging open-source baseband challengers by accelerating carrier aggregation optimization investments in sub-6 GHz architectures. For New Entrants and Emerging Players: Begin with narrowband IoT modules for Indian agricultural drone and smart metering applications, where PLI scheme assembly incentives lower capital barriers and domestic procurement preferences favor local entrants. Target private 5G network integration for mining operations and port logistics as the most penetrable enterprise segment, leveraging software-defined radio flexibility to bypass Qualcomm and MediaTek licensing dependencies. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play module assemblers with certification scale but without captive baseband silicon, as integrated semiconductor vendors capture premium-tier margins. Long-term viability favors vendors with automotive Tier-1 supplier relationships and C-V2X dual-radio qualification. Monitor FCC certification timeline compression and ETSI harmonization progress as inflection indicators for transatlantic market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Foundry Capacity | Secures compound semiconductor supply for 256-element beamforming arrays amid foundry concentration. |
| Dual-Mode 5G NR and C-V2X Certification | Meets automotive OEM mandates for over-the-air updates and direct vehicle-to-vehicle communication. |
| Subscription Firmware Management Launch | Replaces one-time hardware sales with recurring security patching revenue in enterprise IoT. |
| PLI Scheme Assembly Investment | Captures Indian smart factory and agricultural drone demand through domestic manufacturing eligibility. |
| Open-Source Baseband Stack Adoption | Erodes proprietary licensing dependencies for tier-two manufacturers customizing protocol implementations. |
Methodological Framework
Multiple input streams — carrier procurement officer interviews, module vendor technical director discussions, and automotive Tier-1 supplier engineering lead consultations — were reconciled against secondary validation from MIIT network access license databases, FCC equipment authorization filings, and ETSI harmonization documentation. Bottom-up triangulation across shipment volume estimates and top-down cross-checks against carrier capex disclosures ensured consistency in market sizing.
Historical carrier deployment data was cross-referenced against panel input from RF systems engineers and semiconductor procurement leads to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user archetype, and geographic regulatory cluster. CAGRs were derived from installed base migration curves and spectrum allocation timelines. Forecast inputs incorporated gallium nitride wafer supply constraints and C-V2X certification reciprocity developments between FCC and ETSI jurisdictions.
Several conditions sit outside the modeled scope, including unannounced national security review framework expansions, abrupt spectrum reallocation decisions, and compound semiconductor foundry disruption. Forecasts reflect assumptions around carrier aggregation roadmap adherence and automotive embedded connectivity mandate timing. Practitioners should monitor MIIT network access license issuance velocity and FCC 5.9 GHz C-V2X rule refinement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
DECT System Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Global 5G Services Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Italy Telecom Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
France Telecom Market
Telecommunications
Global LTE Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Spain ICT Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
A2P SMS Market