
 Germany Residential Gateway Market | 2026-2036
Germany Residential Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Residential Gateway Market Insights
A shortage of embedded systems engineers fluent in open-source router firmware is redrawing competitive boundaries for German hardware vendors. AVM Computersysteme Vertriebs GmbH leverages its Berlin-based R&D campus to sustain proprietary FritzOS development. Cisco Systems anchors enterprise-grade security feature migration into consumer-tier gateways. Huawei Technologies competes through vertical silicon sourcing despite geopolitical procurement headwinds.
A residential gateway functions as a premises-located network node integrating routing, firewall, and local area network switching with subscriber-line termination for DSL, cable, or fiber interfaces. Modern units incorporate Wi-Fi 6E or Wi-Fi 7 radio chipsets, multi-gigabit Ethernet switching fabrics, and embedded DECT base stations for VoIP telephony. Wireless Gateway variants lead volume shipments as cord-cutting households abandon wired backhaul. Hybrid Gateway configurations capture margin pools by combining fiber termination with cellular failover for rural subscribers underserved by fixed infrastructure.
BNetzA, Germany's federal network agency, mandates interoperability testing under the Telecommunications Terminal Equipment Act. The EU Cybersecurity Act and Germany's IT Security Act 2.0 impose baseline certification for connected home devices sold to consumers. KBA does not regulate this sector, though CE marking under the Radio Equipment Directive remains compulsory for RF-emitting gateways. Stakeholders must monitor whether BNetzA extends fiber access unbundling rules to gateway provisioning, which would force retail-ISP separation in hardware distribution.
Market Dynamics
Fiber-to-the-home infrastructure buildouts by Deutsche Telekom and regional carriers are forcing wholesale hardware replacement cycles across German households, compressing gateway lifespans from seven years toward four.
Growth Catalysts
- EU Cybersecurity Act:Mandatory baseline certification for connected home devices creates upgrade pull as older gateways fail compliance thresholds.
- Wi-Fi 7 radio chipsets:Multi-gigabit throughput requirements from 8K streaming and cloud gaming push bandwidth-heavy households toward hardware refresh.
- North Rhine-Westphalia fiber densification:Urban infrastructure concentration accelerates subscriber acquisition and gateway deployment velocity.
Market Restraints
- Semiconductor supply concentration:RF front-end module fabrication relies on a narrow supplier base in Taiwan, exposing German vendors to allocation volatility.
- BNetzA interoperability testing:Telecommunications Terminal Equipment Act mandates extend certification timelines and raise compliance costs for new market entrants.
- Cellular failover substitution:5G fixed wireless access from Vodafone and Telefónica Deutschland threatens hybrid gateway demand in suburban fiber gaps.
Strategic Opportunities
- Bavaria rural broadband gaps:Hybrid gateway configurations combining fiber termination with cellular backup address underserved municipalities outside metropolitan rings.
- IT Security Act 2.0:Mandatory security baseline certification for consumer IoT creates premium positioning for vendors with pre-certified firmware stacks.
- Matter protocol convergence:Thread radio integration with gateway baseband processors enables smart home hub consolidation and subscription service attachment.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers fluent in OpenWrt and proprietary router operating systems constrains R&D velocity for mid-tier hardware vendors.
- CE marking complexity:Radio Equipment Directive compliance for Wi-Fi 6E and 6 GHz spectrum authorization extends product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Residential Gateway Market |
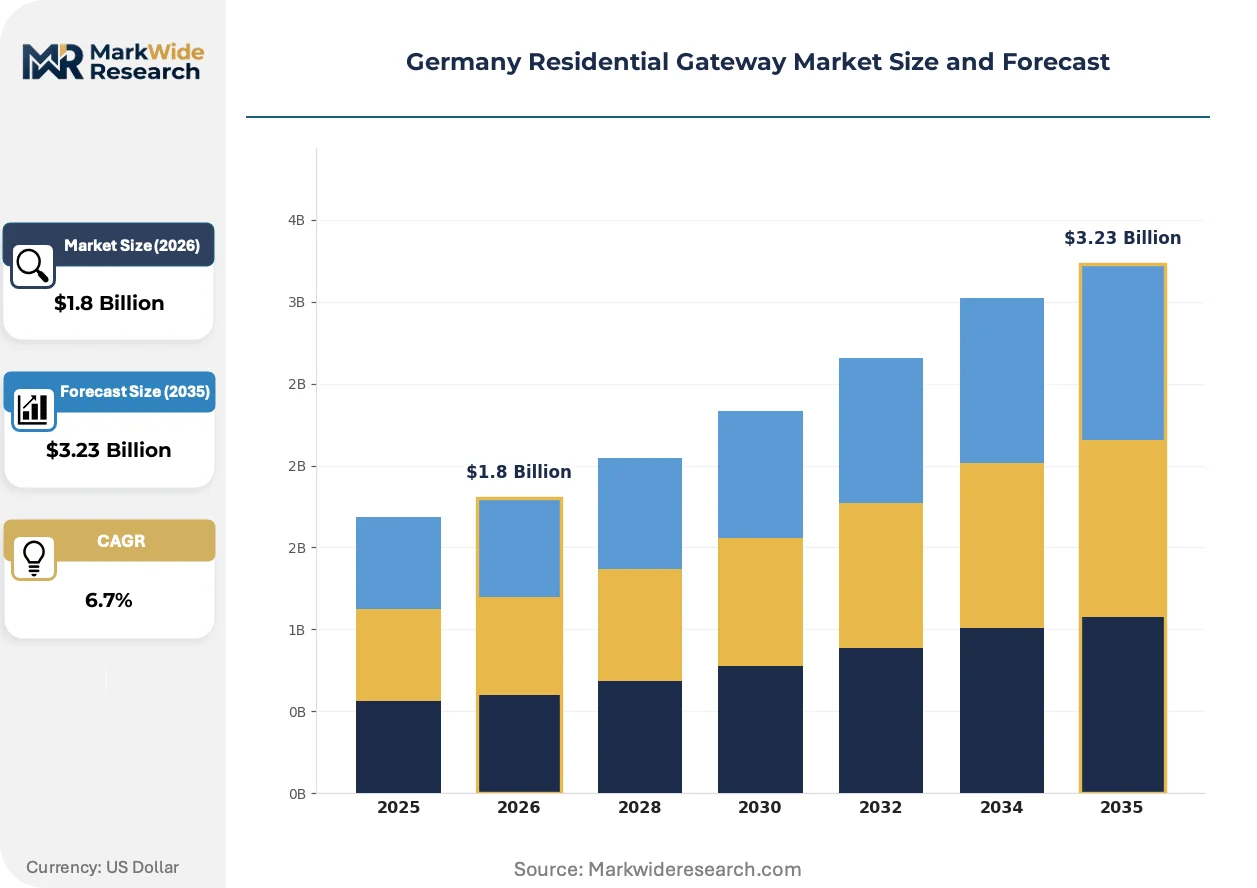
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Gateway, Wired Gateway, Hybrid Gateway, Multimedia Gateway Technology: Wi-Fi, Ethernet, Z-Wave, Zigbee End User: Homeowners, Renters, Property Managers, Service Providers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Telecom Operators |
| Companies Covered | Cisco Systems, TP-Link Corporation, Huawei Technologies, Hewlett Packard Enterprise, D-Link Corporation, AVM Computersysteme Vertriebs GmbH, ZTE Corporation, Zyxel Communications, ASUSTeK Computer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Residential Gateway Market Trends and Innovations
Gateway hardware architecture is fragmenting between purpose-built silicon and software-defined platforms, with vendor strategies diverging on whether to deepen proprietary firmware investment or adopt open-source base systems.
Wi-Fi 7 is supplanting Wi-Fi 6E as the default radio specification for premium gateway tiers. Deutsche Telekom's fiber subscribers in urban centers are receiving tri-band units with 320 MHz channel bonding during standard installations. This transition is compressing margin pools for vendors still shipping Wi-Fi 6 inventory, forcing accelerated discounting through retail channels.
Germany's IT Security Act 2.0 imposes baseline cybersecurity certification for network equipment sold to consumers. Hardware vendors must submit firmware images for vulnerability assessment by BSI-approved laboratories before market release. North Rhine-Westphalia-based ISPs are prioritizing pre-certified gateways in procurement specifications, disadvantaging smaller vendors with limited compliance resources.
Retail distribution through electronics chains is losing ground to ISP-direct provisioning models. Vodafone and Telefónica Deutschland bundle gateways with service contracts and manage firmware updates centrally, eliminating consumer choice but reducing support costs. This channel shift concentrates procurement power among three national carriers and compresses addressable market for independent hardware sales through MediaMarkt and alternate retail.
Germany Residential Gateway Market Segmentation
Gateway segmentation in Germany tracks divergent hardware requirements between fiber-dense urban cores and infrastructure-poor rural municipalities. Product architecture, radio protocol selection, and channel strategy all shift measurably across subscriber density gradients and tenancy arrangements.
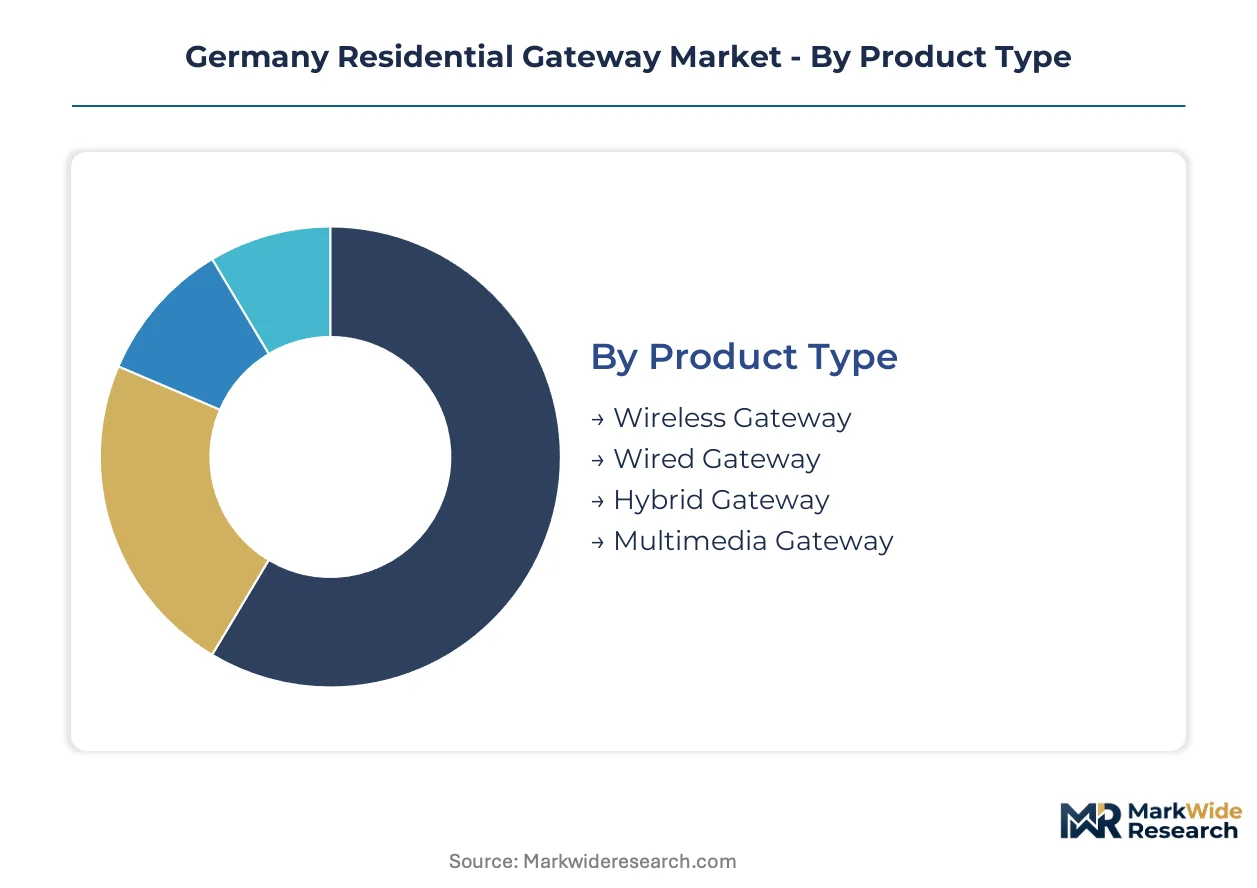
Product Type:
Domestic demand concentrates in configurations engineered for Deutsche Telekom's fiber topology, while export-oriented German vendors calibrate SKUs for neighboring Benelux and Austrian carrier specifications.
- Wireless Gateway:Cord-cutting households drive volume as tri-band Wi-Fi 7 units replace legacy 802.11ac hardware. North Rhine-Westphalia ISPs provision these as standard for subscribers above 100 Mbps tiers, though 6 GHz spectrum licensing delays constrain rural rollout velocity.
- Hybrid Gateway:Combines fiber termination with embedded 5G or LTE modems for automatic failover. Bavarian municipalities outside metropolitan rings generate disproportionate demand where fixed infrastructure remains patchy and cellular backup commands premium positioning.
- Wired Gateway:Purpose-built for subscriber-line termination without integrated Wi-Fi, serving basement installation scenarios and multi-dwelling unit distribution. Property management portfolios in Berlin and Hamburg specify these for centralized rack mounting.
- Multimedia Gateway:Integrates broadcast TV tuners, VoIP base stations, and storage networking for converged service bundles. Aging inventory faces replacement pressure as streaming-first households abandon linear television.
Wireless Gateway holds the largest share; momentum sits with Hybrid Gateway.
Technology:
Radio protocol selection determines firmware certification burden under BSI cybersecurity mandates, with newer standards carrying heavier laboratory validation timelines.
- Wi-Fi:Wi-Fi 7 (802.11be) with 320 MHz channel bonding is displacing Wi-Fi 6E in carrier procurement specifications. Deutsche Telekom's urban fiber subscribers receive tri-band units as default, compressing margin pools for vendors shipping Wi-Fi 6 inventory.
- Ethernet:Multi-gigabit switching fabrics (2.5 Gbps and 10 Gbps) anchor backhaul for bandwidth-intensive households. North Rhine-Westphalia's fiber densification accelerates deployment of 10G-PON compatible gateway variants.
- Z-Wave:Sub-GHz mesh networking for battery-powered sensors and smart locks. Property managers in rental portfolios favor this protocol for its interference resilience in dense building environments.
- Zigbee:Thread radio integration enables Matter protocol convergence for smart home hub consolidation. IT Security Act 2.0 certification requirements disadvantage smaller vendors lacking resources for multi-protocol firmware validation.
Wi-Fi dominates procurement volumes; Zigbee climbs fastest on Matter ecosystem attachment.
End User:
Tenancy status shapes hardware decision rights and replacement cycle timing, with institutional buyers exercising centralized procurement power unavailable to individual subscribers.
- Homeowners:Direct purchasers in single-family residences control device selection and bear full replacement cost. Bavaria's owner-occupied housing stock generates above-average demand for premium-tier units with cellular failover.
- Renters:Depend on landlord-provided infrastructure or ISP-bundled equipment with limited upgrade autonomy. Berlin's rental-heavy housing market concentrates gateway provisioning power with property management entities.
- Property Managers:Centralized procurement for multi-dwelling units favors standardized, remotely manageable hardware. North Rhine-Westphalia's institutional landlords prioritize BSI pre-certified firmware to minimize liability exposure.
- Service Providers:Deutsche Telekom, Vodafone, and Telefónica Deutschland exercise concentrated procurement power through direct provisioning models. Carrier-managed firmware updates eliminate consumer choice but reduce support cost per subscriber.
Service Providers command the largest procurement volume; Property Managers represent the steepest expansion trajectory on smart building integration.
Distribution Channel:
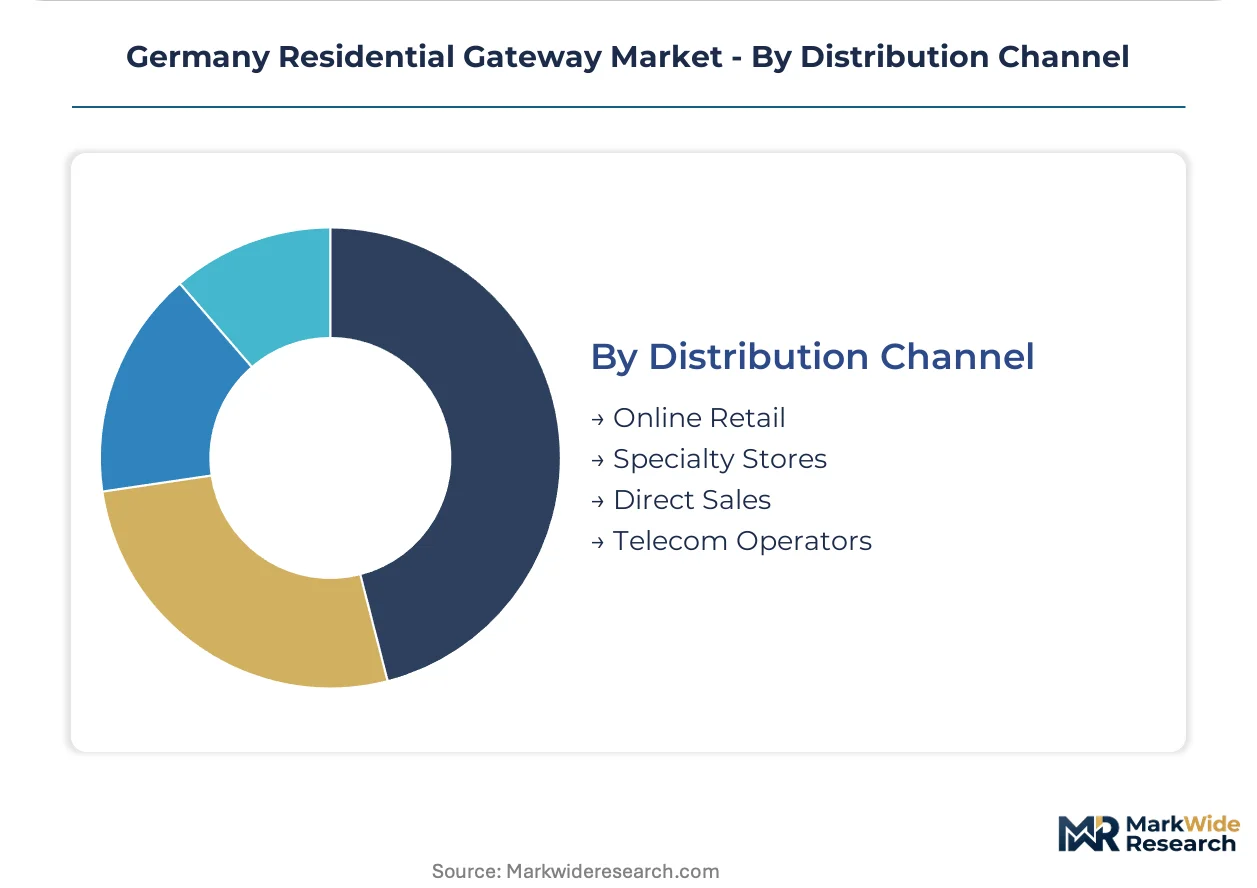
Channel structure is bifurcating between carrier-direct provisioning and residual retail paths, with online platforms capturing shrinking independent demand.
- Telecom Operators:Deutsche Telekom, Vodafone, and Telefónica Deutschland bundle gateways with service contracts and manage lifecycle centrally. This channel shift compresses addressable market for independent hardware sales.
- Online Retail:Amazon.de and alternate platforms serve self-install subscribers in rural fiber gaps and tech-enthusiast segments. Wi-Fi 7 early adopters bypass carrier provisioning to access unconstrained feature sets.
- Specialty Stores:MediaMarkt and Saturn retain relevance for replacement purchases and compatibility troubleshooting. Foot traffic concentrates in urban centers where immediate availability outweighs delivery friction.
- Direct Sales:Enterprise-grade vendors like Cisco route commercial-grade security features through VAR channels to prosumer segments. AVM maintains direct-to-consumer firmware support infrastructure for FritzOS ecosystem loyalty.
Telecom Operators hold the largest share; Online Retail gains fastest on cord-cutter self-provisioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BNetzA, Germany's federal network agency, anchors fiber access regulation across the country's most advanced broadband markets. Regional carrier buildouts and state-level digital infrastructure programs are compressing hardware replacement cycles unevenly across German sub-regions.
North Rhine-Westphalia
Urban fiber densification by Deutsche Telekom and regional carriers drives wholesale gateway replacements in Cologne, Düsseldorf, and the Ruhr metropolitan corridor. The state's Digital.NRW initiative accelerates municipal broadband partnerships that mandate BSI-compliant hardware procurement. Property management portfolios in Essen and Dortmund standardize on centrally manageable gateways for multi-dwelling unit distribution.
Bavaria
Owner-occupied housing stock in Munich, Nuremberg, and surrounding municipalities generates premium-tier demand with cellular failover capabilities. The Bayern Digital infrastructure program targets rural broadband gaps where hybrid gateway configurations command positioning advantages. Regional carriers in Upper Bavaria deploy fiber-to-the-home with embedded 5G backup for subscribers outside metropolitan rings.
Baden-Württemberg
Stuttgart's industrial automation ecosystem creates demand for gateways with industrial IoT protocol support alongside residential functions. The state's broadband funding agency, Breitband Baden-Württemberg, prioritizes fiber deployment in medium-sized cities where gateway procurement concentrates with municipal utilities. Karlsruhe's tech corridor attracts vendors establishing regional firmware support operations.
Berlin-Brandenburg
Rental-heavy housing markets in Berlin concentrate gateway provisioning power with property management entities rather than individual subscribers. The city's Gigabit Region Berlin-Brandenburg initiative mandates open network access that influences hardware interoperability requirements. Potsdam's media and research institutions drive demand for high-throughput units supporting 8K streaming and cloud computing workloads.
Hamburg
Port-city logistics and maritime service industries create specialized demand for gateways with redundant connectivity in harbor-adjacent residential zones. The Hamburg Broadband Masterplan accelerates fiber deployment across the metropolitan region with standardized procurement specifications. Altona and HafenCity districts represent early adoption clusters for Wi-Fi 7 tri-band installations.
Germany Residential Gateway Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Germany's residential gateway market. The upper tier commands carrier-direct provisioning relationships and manages firmware ecosystems at scale. The specialist tier competes through retail channel presence and protocol-specific feature differentiation. Strategic archetypes include proprietary firmware developers, silicon-integrated platform vendors, and open-source firmware specialists. Competitive moves concentrate on BSI pre-certification investments and Matter protocol integration partnerships.
Among Germany-based specialists, AVM Computersysteme Vertriebs GmbH exemplifies the proprietary firmware archetype with its Berlin R&D campus and FritzOS ecosystem. Cisco Systems occupies a position bridging enterprise-grade security migration into consumer-tier segments. Huawei Technologies represents vertical silicon sourcing despite geopolitical procurement constraints affecting German carrier relationships.
| Leading Market Players |
|---|
| Cisco Systems |
| TP-Link Corporation |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| D-Link Corporation |
| AVM Computersysteme Vertriebs GmbH |
| ZTE Corporation |
| Zyxel Communications |
| ASUSTeK Computer |
| Others |
Pricing and Supply Chain Analysis
Carrier-direct provisioning contracts lock in multi-year hardware supply commitments for Deutsche Telekom, Vodafone, and Telefónica Deutschland, anchoring price visibility while compressing margin pools for independent retail channels. These arrangements tether gateway vendors to volume-scale pricing tiers that reflect BSI certification investment amortization across subscriber bases.
Pricing Analysis
Long-term offtake agreements dominate procurement between national carriers and gateway vendors, with pricing stratifying across premium, standard, and economy tiers based on Wi-Fi protocol generation and cybersecurity certification grade. Price differentiation stems from BSI pre-certification status and embedded cellular failover capability. Cost compression in Wi-Fi 6 inventory is intensifying because carrier procurement specifications now default to Wi-Fi 7 tri-band units. Service providers exhibit lowest price sensitivity due to centralized lifecycle management economies, while self-install subscribers through online retail channels demonstrate highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German hardware vendors for final assembly, though strategic stockpiling of RF front-end modules occurs due to Taiwan fabrication concentration. Component sourcing draws from Taiwan for Wi-Fi chipsets, China for PCB substrates, and South Korea for memory modules. Single-source vulnerability concentrates in 6 GHz power amplifier fabrication. Distribution runs through carrier-direct provisioning for three-quarters of volume, with residual retail through Amazon.de and electronics chains serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as fiber buildouts fragment procurement authority between national carriers, regional utilities, and property management entities. Matter protocol convergence and IT Security Act 2.0 certification requirements are spawning specialist niches beyond incumbent scale advantages.
For Market Incumbents: Secure BSI pre-certification pipelines for firmware stacks to maintain carrier-direct provisioning relationships against emerging competitors. Deepen backward integration into radio chipset sourcing to mitigate Taiwan allocation volatility. Channel control through centralized firmware update infrastructure represents the critical defensive lever against retail-channel insurgents. For New Entrants and Emerging Players: BSI fast-track certification for open-source firmware derivatives opens procurement access to municipal utilities and regional carriers outside Deutsche Telekom's supplier base. Bavarian rural broadband gaps present the most penetrable geography, where hybrid gateway configurations with embedded 5G failover command premium positioning. Direct-to-property-manager sales models bypass carrier provisioning concentration. For Investors and Strategic Acquirers: Capital is best deployed toward firmware-specialist vendors with Matter protocol integration capabilities and existing BSI laboratory relationships. Long-term viability centers on cybersecurity certification moats rather than hardware cost scale. Watch for BNetzA fiber access unbundling rulings as the signal indicating retail-ISP separation and hardware distribution opening.| Strategic Initiative | Industry Significance |
|---|---|
| BSI Pre-Certification Investment | Accelerates carrier procurement eligibility under IT Security Act 2.0 mandates. |
| Matter Protocol Integration | Enables smart home hub consolidation and subscription service attachment opportunities. |
| Vertical Silicon Sourcing | Mitigates Taiwan RF module allocation volatility through captive supply arrangements. |
| Regional Carrier Partnership | Captures fiber buildout demand outside Deutsche Telekom's centralized procurement. |
| Open-Source Firmware Development | Addresses embedded systems talent scarcity constraining mid-tier vendor R&D velocity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating procurement directors at Deutsche Telekom and Vodafone, firmware engineering leads at AVM and regional hardware vendors, property management technology officers in North Rhine-Westphalia, and BSI laboratory certification specialists. Secondary validation drew from BNetzA regulatory filings, BSI technical guidelines, carrier capex disclosures, and CE marking databases under the Radio Equipment Directive. Bottom-up shipment estimates triangulated against top-down service provider subscriber data.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmented demand drivers: product type (wireless, hybrid, wired, multimedia), radio technology generation (Wi-Fi 6E, Wi-Fi 7), end-user tenancy status, and distribution channel structure. CAGRs were derived from hardware replacement cycle compression trends and fiber deployment velocity differentials across German states. Industry-specific inputs included BSI certification timeline assumptions and 6 GHz spectrum licensing progression.
Underlying assumptions cover carrier provisioning model persistence and Taiwan semiconductor supply stability, with deviation risk concentrated in BNetzA unbundling rulings and geopolitical export restrictions affecting Chinese vendor participation. Revision becomes warranted when cellular failover substitution rates in suburban fiber gaps cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Digital Repeater Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Global Network Management Market
Network Technology
Self-Healing Networks Market
Network Technology
Global Internet Transit Market
Network Technology
ISP Management Systems Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Global Network Probe Market
Network Technology
GCC Set-Top Box Market
Network Technology
Fiber to the Premises Market
Network Technology
Global Home Networking Device Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Wi-Fi Extender Market
Network Technology
BYOD Market
Network Technology
Gigabit Ethernet Market
Network Technology
Optical Networking Market