
 Gigabit Ethernet Market | 2026-2036
Gigabit Ethernet Market Size, Share, and Industry Trends Forecast 2026-2036
Gigabit Ethernet Market Analytics
Copper cabling is broadening its viable reach through advanced shielding and thinner-gauge twisted-pair designs that cut material costs for short-reach data center interconnects. Cisco Systems leverages its installed base of enterprise switches to sustain recurring software revenue. Arista Networks dominates cloud-scale deployments with programmable switching silicon. Huawei anchors supply for Chinese state-backed data center buildouts despite trade restrictions.
Gigabit Ethernet denotes physical-layer networking technology transmitting data at one billion bits per second, typically implemented via twisted-pair copper (1000BASE-T), fiber optic (1000BASE-SX/LX), or backplane electrical channels, with frame structures adhering to IEEE 802.3 standards for collision detection and media access control. Switches generate the largest revenue pool among product types because port density requirements rise with each server generation. Fiber optic technology captures expanding share in data center applications where reach and electromagnetic immunity outweigh copper's cost advantage. Enterprise networks represent a mature application segment with replacement-driven demand rather than greenfield expansion.
The Federal Communications Commission shapes US market access through equipment authorization rules, while the European Telecommunications Standards Institute governs interoperability testing for CE-marked products sold across EU member states. China's Ministry of Industry and Information Technology enforces domestic GB standards that favor local suppliers for government and critical infrastructure procurement. Stakeholders must weigh standardization timelines against proprietary silicon roadmaps when committing capital to next-generation port speeds.
Market Dynamics
AI training clusters are compressing equipment refresh cycles as hyperscale operators abandon 10-year depreciation schedules for 3-year replacement timelines to capture 800G and 1.6T throughput gains.
Growth Catalysts
- IEEE 802.3ck standardization:The 800G electrical interface specification reduces power per bit by 50% versus 400G implementations, enabling denser switch fabric designs for cloud data centers.
- Hyperscale buildouts in China:Domestic cloud providers are deploying millions of new ports annually, creating concentrated demand for high-density switching silicon and optical transceivers.
- Copper reach extension:Advanced shielding and thinner-gauge twisted-pair designs now support 10-meter links, cutting fiber deployment costs for top-of-rack server interconnects.
Market Restraints
- Optical component concentration:Taiwan and South Korea dominate coherent DSP and laser manufacturing, creating single-source risk for 400G+ transceiver supply.
- Power density constraints:800G switch ports draw 15-20 watts each, straining data center thermal budgets and requiring liquid cooling retrofits that extend deployment timelines.
- Trade restriction friction:US export controls on advanced semiconductors limit Chinese access to 7nm switching ASICs, fragmenting supply chains into incompatible regional ecosystems.
Strategic Opportunities
- Edge computing expansion:5G base stations and autonomous vehicle infrastructure require ruggedized Gigabit Ethernet switches with -40°C to 85°C operating ranges, opening industrial automation applications.
- India's data center stimulus:The PLI scheme for IT hardware manufacturing offers 4-6% incentives on incremental sales, attracting switch assembly investments from global OEMs.
- Silicon photonics convergence:Integrating lasers directly onto switch chips eliminates pluggable transceivers, reducing cost and latency for AI cluster interconnects.
Industry Challenges
- Signal integrity engineering scarcity:112G PAM-4 SerDes design requires specialized analog/mixed-signal talent that remains concentrated at a handful of semiconductor firms and universities.
- Interoperability certification delays:UNH-IOL and Ethernet Alliance testing backlogs stretch 6-9 months for 800G products, slowing revenue recognition for new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gigabit Ethernet Market |
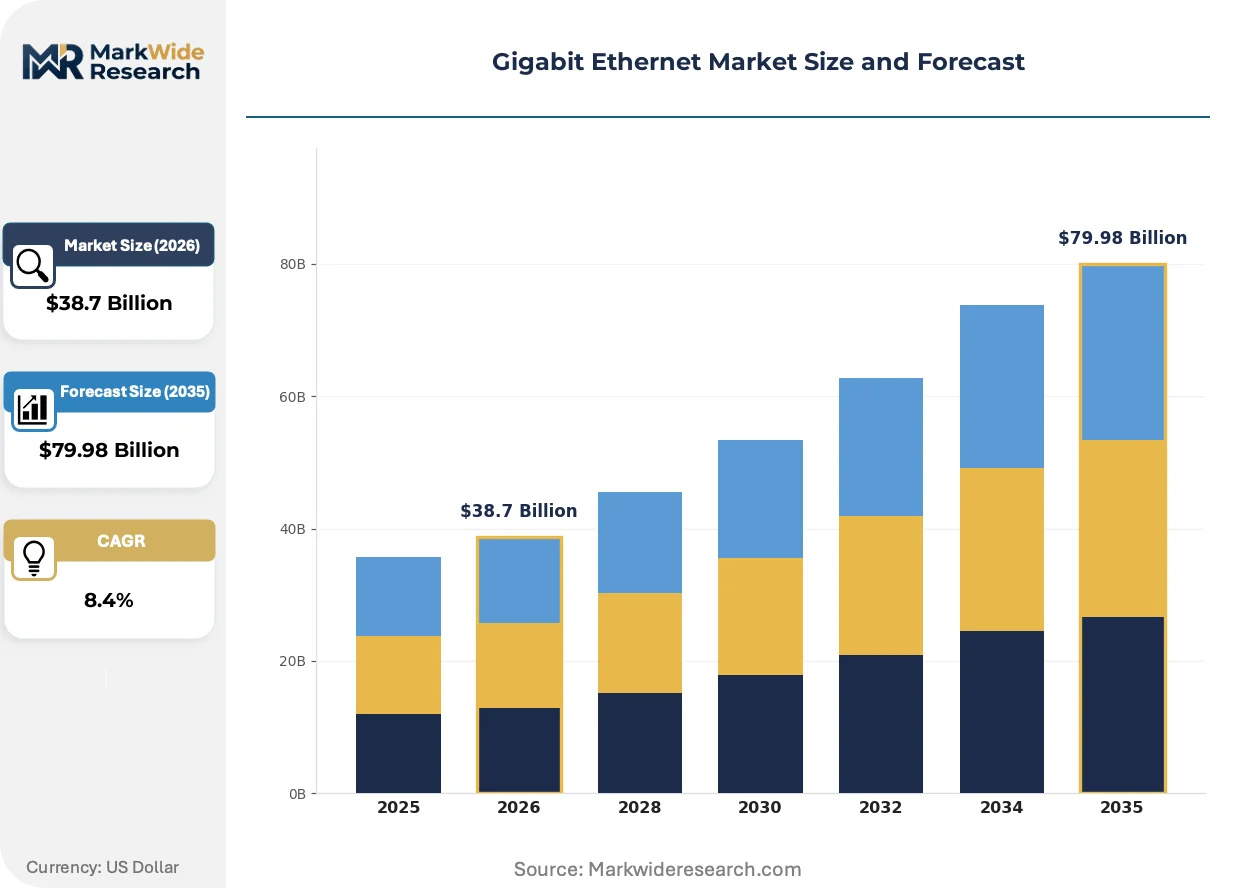
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Interface Cards, Cables Application: Data Centers, Enterprise Networks, Home Networking, Industrial Automation End User: SMEs, Large Enterprises, Service Providers, Government Technology: Copper, Fiber Optic, Wireless, Power over Ethernet |
| Companies Covered | Keysight Technologies, Viavi Solutions, Spirent Communications, Anritsu Corporation, EXFO Inc., Rohde & Schwarz, Cisco Systems, Huawei, Arista Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gigabit Ethernet Market Evolving Landscape
Physical-layer innovation is racing ahead of standardization timelines, with proprietary silicon roadmaps now dictating deployment schedules rather than IEEE consensus processes.
Linear-drive pluggable optics (LPO) eliminate digital signal processors from transceivers, cutting power consumption by 30% and latency by 40%. Amazon Web Services and Microsoft Azure are qualifying LPO modules for 51.2T switch deployments in 2025. This architecture is expanding into 800G data center interconnects as cloud operators prioritize total cost of ownership over multi-vendor interoperability.
The European Commission's Energy Efficiency Directive mandates power usage effectiveness (PUE) reporting for data centers exceeding 500kW capacity, effective 2024. Network equipment now faces embodied carbon disclosure requirements under the CSRD. Switch vendors serving EU markets are redesigning thermal architectures and sourcing recycled aluminum chassis to meet these thresholds.
Hyperscale buyers are consolidating procurement around vertically integrated switch suppliers who deliver pre-qualified optical modules, cables, and software as unified systems. Traditional value-added distributors lose relevance as direct OEM relationships dominate 400G+ transactions. This pattern is most pronounced in North American cloud deployments, where procurement teams now specify complete pod-level solutions rather than discrete components.
Gigabit Ethernet Market Segmentation
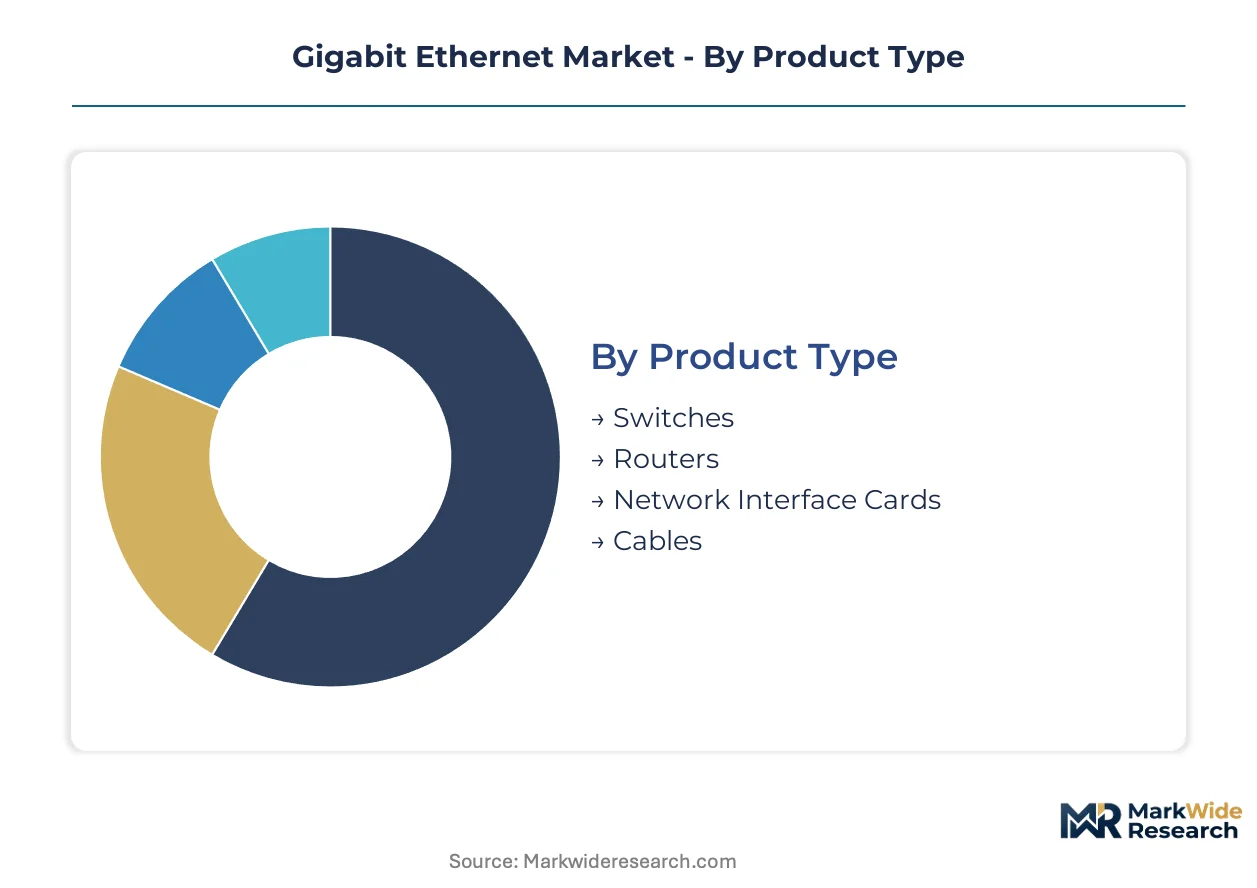
Segmentation in Gigabit Ethernet reveals how port speed requirements, physical layer choices, and procurement scale fragment demand across incompatible equipment tiers. Buyers optimize capex by matching cable reach, power budgets, and management complexity to specific workload patterns rather than deploying uniform infrastructure.
Product Type:
Port density and switching throughput define the hardware hierarchy, with silicon generation determining which products capture hyperscale procurement versus enterprise refresh cycles.
- Switches:Fixed and modular chassis designs aggregate server traffic through 48-port and 64-port configurations. Cloud operators in the United States deploy 51.2T aggregate capacity switches to feed AI training clusters, compressing refresh cycles to three years.
- Routers:Carrier-grade platforms handle BGP peering and WAN aggregation at the network edge. Service providers in India prioritize these for 5G backhaul expansion under PLI scheme incentives.
- Network Interface Cards:Server adapters terminate host connections with hardware offload for RDMA and encryption. Demand concentrates in Chinese hyperscale facilities where domestic cloud providers build captive server fleets.
- Cables:Direct-attach copper and active optical assemblies complete physical-layer connectivity. Top-of-rack deployments under ten meters increasingly specify shielded twisted-pair to avoid fiber transceiver costs.
Mature deployment sits with Routers. Newer deployment is concentrated in Switches.
Application:
Workload characteristics dictate whether buyers prioritize raw bandwidth, latency consistency, or environmental ruggedization.
- Data Centers:Hyperscale facilities demand 800G and 1.6T signaling to minimize training time for large language models. Liquid cooling retrofits become necessary as 15-20 watt per port power density strains thermal budgets.
- Enterprise Networks:Campus and branch infrastructure runs predominantly at 1G and 10G speeds with ten-year depreciation schedules. Replacement demand dominates as organizations migrate from end-of-life Catalyst and ProCurve generations.
- Home Networking:Consumer routers and mesh systems deliver Gigabit speeds over Wi-Fi 6 and 6E. Service provider bundled equipment drives volume in North American and European residential markets.
- Industrial Automation:Factory floors and utility substations require -40°C to 85°C operating ranges with vibration tolerance. Edge computing for autonomous systems is expanding addressable market beyond traditional IT environments.
Volume concentration rests with Enterprise Networks. Steepest expansion trajectory belongs to Data Centers.
End User:
Procurement sophistication and contract scale separate buyers who specify complete pod-level solutions from those purchasing through distribution channels.
- SMEs:Organizations under 500 employees purchase through value-added distributors with limited technical specification. Price sensitivity favors unmanaged switches and copper cabling for office connectivity.
- Large Enterprises:Fortune 500 technology and financial services firms maintain direct OEM relationships for campus refresh programs. These buyers negotiate enterprise licensing for network management software alongside hardware procurement.
- Service Providers:Telecommunications carriers and cable operators deploy carrier Ethernet for residential and business service delivery. 5G fronthaul requirements are accelerating 25G and 100G port absorption in mobile infrastructure.
- Government:Federal agencies and state entities in the United States follow FCC equipment authorization rules with additional FISMA security compliance. Chinese state-backed data centers source through MIIT procurement channels that favor domestic suppliers.
Procurement consolidation is most advanced with Service Providers. Emerging specification complexity is greatest with Government.
Technology:
Physical layer selection trades reach, electromagnetic immunity, and power consumption against material and installation economics.
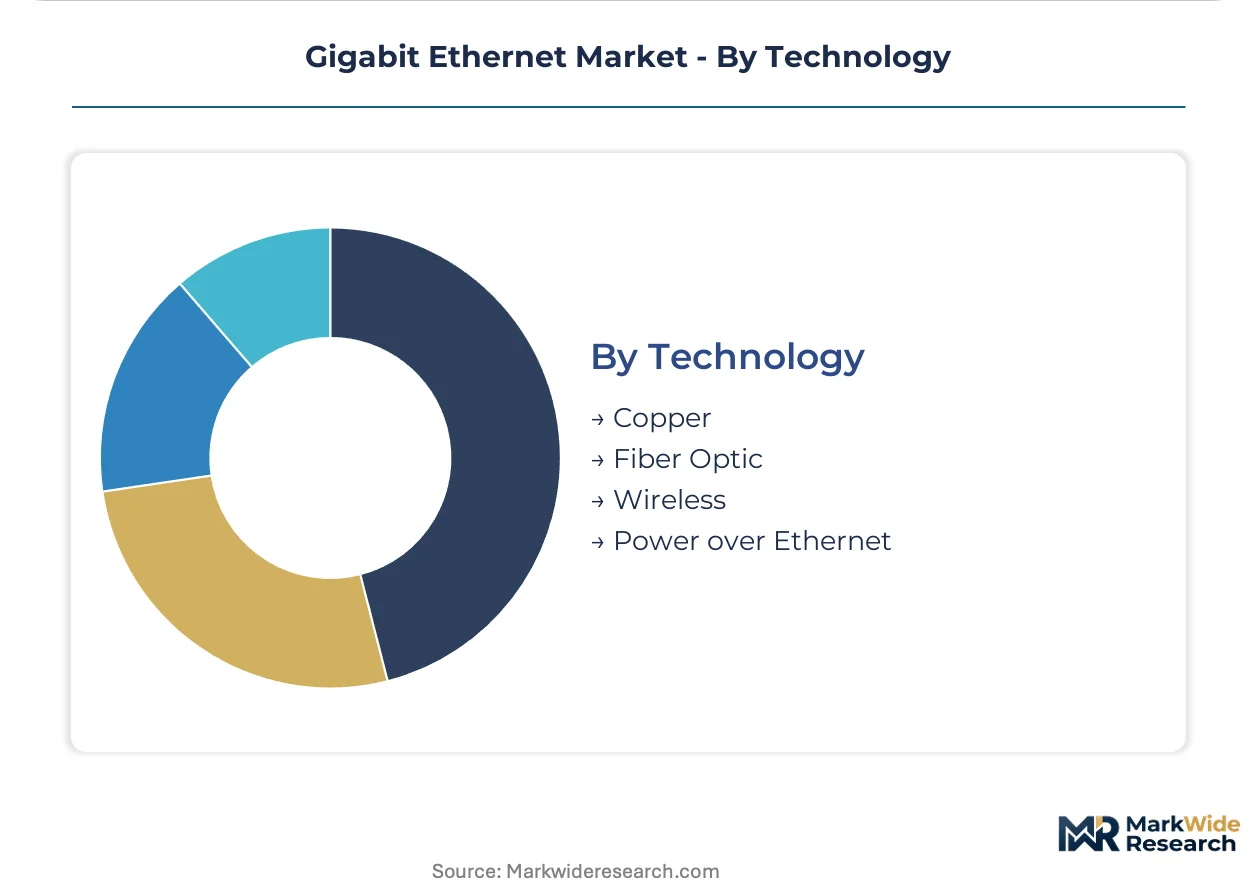
- Copper:Twisted-pair cabling with advanced shielding now supports ten-meter links for top-of-rack server interconnects. IEEE 802.3bz and 802.3bt standards extend viability for cost-sensitive short-reach applications.
- Fiber Optic:Single-mode and multimode implementations dominate data center spine layers where electromagnetic immunity and distance matter. Coherent DSP and laser manufacturing concentration in Taiwan and South Korea creates supply risk for 400G+ transceivers.
- Wireless:Wi-Fi 6E and emerging 7 standards deliver Gigabit speeds without structured cabling. Enterprise campus overlay networks use this for conference rooms and temporary deployments.
- Power over Ethernet:IEEE 802.3bt delivers 90 watts to support IP cameras, access points, and IoT sensors over existing cable plants. Smart building retrofits drive absorption where rewiring is prohibitively expensive.
Established infrastructure relies on Copper. Fastest technology transition is occurring in Fiber Optic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center construction concentrates demand in three distinct geographies, each shaped by divergent regulatory regimes and infrastructure investment cycles. Cloud operators in the United States, China, and Germany account for the majority of 400G and 800G port deployments, while emerging buildouts in India and Brazil reshape regional supply chain configurations.
United States
AI training clusters in Northern Virginia and Phoenix drive 51.2T switch absorption, compressing equipment refresh cycles to three years. The FCC enforces equipment authorization rules that govern market access for 800G-capable hardware. Dallas-Fort Worth anchors secondary data center expansion as power constraints limit growth in traditional Ashburn and Santa Clara clusters.
China
Domestic cloud providers deploy millions of new ports annually, creating concentrated demand for high-density switching silicon. The Ministry of Industry and Information Technology enforces GB standards that favor local suppliers for state-backed procurement. Inner Mongolia and Guizhou provinces host hyperscale facilities leveraging cool climates and renewable energy for thermal budget relief.
Germany
Enterprise network refresh cycles sustain demand for 10G and 25G campus infrastructure across Mittelstand manufacturers. The European Commission's Energy Efficiency Directive mandates PUE reporting for facilities exceeding 500kW capacity, effective 2024. Frankfurt's DE-CIX internet exchange anchors interconnection demand, driving 100G and 400G port growth at carrier-neutral facilities.
India
The PLI scheme for IT hardware manufacturing offers 4-6% incentives on incremental sales, attracting switch assembly investments from global OEMs. Mumbai and Chennai concentrate data center construction as Jio and Airtel expand cloud infrastructure. TRAI regulations govern interconnection pricing for carrier Ethernet services delivered to enterprise customers.
Brazil
Financial services and e-commerce platforms drive enterprise switch replacement in São Paulo's commercial districts. ANATEL certification requirements govern telecommunications equipment market access, creating compliance timelines for 400G product launches. Campinas anchors domestic assembly operations as manufacturers seek proximity to South American cloud demand.
Gigabit Ethernet Market Competitive Landscape
Capacity expansion dominates the current landscape as vendors race to qualify 800G platforms before IEEE 802.3ck interoperability testing concludes. The market structures around three tiers: vertically integrated hyperscale suppliers, enterprise-focused platform vendors, and test and measurement specialists serving validation workflows. Strategic archetypes include silicon-integrated system houses, optical component suppliers, and protocol conformance laboratories. Geographic expansion and technology licensing represent the dominant competitive moves, with vendors establishing regional support centers and cross-licensing SerDes IP to accelerate time-to-market.
Among test and measurement specialists, Keysight Technologies, Viavi Solutions, and Spirent Communications exemplify the protocol validation archetype, occupying positions where 112G PAM-4 signal integrity testing creates capability scarcity. These firms anchor the conformance certification layer that gates revenue recognition for switch and transceiver launches, sitting within a segment where UNH-IOL and Ethernet Alliance testing backlogs stretch six to nine months for 800G products.
| Leading Market Players |
|---|
| Keysight Technologies |
| Viavi Solutions |
| Spirent Communications |
| Anritsu Corporation |
| EXFO Inc. |
| Rohde & Schwarz |
| Cisco Systems |
| Huawei |
| Arista Networks |
| Others |
Value Network & Pricing Analysis
Captive silicon production at Arista Networks, Cisco Systems, and Huawei anchors both supply security and pricing power across the 400G and 800G switching tiers. These vertically integrated system houses control switch ASIC design in-house while sourcing optical components through qualified supplier lists, creating tiered procurement leverage that commodity switch vendors cannot replicate.
Pricing Analysis
Volume concentration at hyperscale cloud operators splits the market into margin-diluted bulk contracts versus premium-priced enterprise segments. Three-tier pricing structure across premium, standard, and economy levels separates 51.2T AI cluster switches from campus 10G refreshes and unmanaged SME equipment. Pricing pressure stems from Chinese domestic suppliers capturing state-backed procurement under MIIT GB standards. SMEs exhibit highest price sensitivity, while North American cloud operators prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for coherent DSP and laser manufacturing in 400G+ transceivers. Switch ASIC fabrication draws from TSMC's leading-edge nodes in Taiwan, while passive optical component assembly concentrates in Shenzhen and Dongguan. Tariff exposure from US semiconductor export controls fragments supply chains into incompatible regional ecosystems. Distribution runs through direct OEM relationships for hyperscale procurement, bypassing traditional value-added distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over switch silicon and optical module qualification timelines determines competitive survival. Players are pursuing backward integration into 112G PAM-4 SerDes IP and captive optical transceiver manufacturing to compress time-to-market.
For Market Incumbents: Acquire 112G SerDes design teams and linear-drive pluggable optics capabilities to defend against merchant silicon entrants. Cisco Systems and Arista Networks should deepen upstream control over optical module qualification workflows to extend testing backlog advantages. Certification investment at UNH-IOL and Ethernet Alliance accelerates revenue recognition for 800G platforms ahead of IEEE 802.3ck finalization. For New Entrants and Emerging Players: Cloud reseller and systems integrator partnerships offer the fastest path to hyperscale procurement visibility. White-space targets concentrate in India's PLI-subsidized switch assembly and Brazil's ANATEL-certified enterprise replacement cycles. Edge computing for industrial automation presents the most penetrable segment, with -40°C to 85°C ruggedized switches underserved by incumbent portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated system houses seeking optical component capabilities. Long-term viability hinges on five-to-ten year positioning around 1.6T signaling and silicon photonics convergence. Acquisition target archetype: test and measurement specialists with 112G PAM-4 signal integrity expertise. Watch IEEE 802.3ck interoperability testing completion as inflection indicator for revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Eliminates pluggable transceivers for Amazon Web Services and Microsoft Azure AI clusters. |
| 112G SerDes IP Licensing | Accelerates time-to-market for 800G switch platforms at Keysight Technologies validation labs. |
| India PLI Manufacturing Footprint | Captures 4-6% incentives for switch assembly serving Jio and Airtel data center expansion. |
| Linear-Drive Pluggable Optics Qualification | Reduces power consumption 30% for 51.2T cloud switch deployments. |
| UNH-IOL Certification Investment | Shortens 6-9 month testing backlogs that gate 800G product revenue recognition. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center procurement officers, switch platform engineers, optical transceiver manufacturing leads, and IEEE standards committee participants validated demand assumptions. SEC 10-K disclosures from Cisco Systems and Arista Networks, FCC equipment authorization databases, and MIIT GB standard publications provided bottom-up shipment estimates. Top-down triangulation against Ethernet Alliance port shipment reports and UNH-IOL certification queues cross-checked market sizing.
Reconciliation of hyperscaler capex disclosures, OEM production schedules, and component supplier bill-of-materials data streams anchored the forecast framework. Segmentation dimensions modeled include port speed tier, physical layer technology, deployment scale, and regional regulatory cluster across the analysis window. CAGRs derived from equipment refresh cycle compression in AI training clusters and greenfield data center buildouts in China and India. Forecast inputs incorporated IEEE 802.3 standards evolution timelines and thermal density constraints from liquid cooling adoption curves.
Caveats apply where IEEE 802.3ck standardization delays, Taiwan semiconductor supply disruptions, or US export control expansion could materially shift the outlook. Forecasts reflect assumptions about hyperscale depreciation schedule compression and Chinese domestic supplier qualification rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Systems (NMS) Market
Network Technology
North America Enterprise WLAN Market
Network Technology
5G CPE Device Market
Network Technology
Mobile Network Optimization Market
Network Technology
Low-Power WAN Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Global Network Monitoring Market
Network Technology
Global Wireless Router Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Global Network Switches Market
Network Technology
Network Devices Market
Network Technology
Network Management Solutions Market
Network Technology
RTP Market
Network Technology
CPE Router Market
Network Technology
Zero-Touch Provisioning Market